
 Ultra Micro Drone Market | 2026-2036
Ultra Micro Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Micro Drone Market Insights
Subscription-based fleet management software is hardening as the primary revenue layer in ultra micro drone operations, shifting vendor economics from hardware margins to recurring service contracts. DJI leverages its App-based flight planning ecosystem to lock in enterprise accounts across infrastructure inspection workflows. Parrot SA sustains competitive positioning through specialized rotary-wing designs optimized for confined-space environmental monitoring. AeroVironment anchors defense-sector relationships with fixed-wing platforms purpose-built for battlefield reconnaissance.
Ultra micro drones are unmanned aerial vehicles weighing under 250 grams, typically constructed from carbon fiber reinforced polymers and powered by brushless DC motors driving ducted or exposed rotors, with flight endurance ranging from 10 to 30 minutes depending on battery cell density. Their primary commercial purpose centers on close-proximity data capture in GPS-denied or structurally complex environments where larger platforms cannot operate safely. Rotary-wing configurations dominate current shipment volumes due to mechanical simplicity and vertical takeoff versatility, while hybrid architectures represent the fastest-expanding segment as end users demand multi-mission flexibility without swapping airframes. Optical flow and visual inertial navigation technologies concentrate margin pools, as these sensor fusion stacks differentiate premium platforms from commodity alternatives.
The FAA's Remote ID mandate and the EU's CE marking under the Drone Regulation framework constrain market access for non-compliant manufacturers, while China's MIIT enforces GB standards on radio transmission power that shape exportable product specifications. Defense procurement offices in multiple jurisdictions now require counter-UAS detection compatibility as a precondition for contract eligibility. Stakeholders must monitor regulatory divergence between permissive recreational frameworks and restrictive commercial certification pathways, as this policy fragmentation will determine which technology architectures achieve scalable deployment.
Market Dynamics
Defense procurement offices are mandating counter-UAS detection compatibility as a precondition for contract eligibility, forcing platform architects to embed standardized RF signatures and kill-switch protocols into firmware stacks from initial design phases.
Growth Catalysts
- Urban warfare doctrine:Military forces in the United States are expanding procurement of palm-sized reconnaissance platforms for GPS-denied building interiors and subterranean tunnel complexes.
- FAA Part 107 evolution:Remote pilot certification requirements and evolving counter-UAS rules are creating compliant operator pools that commercial infrastructure inspectors can access reliably.
- Shenzhen component density:China's manufacturing cluster achieves unmatched supply chain compression for brushless motors, lithium-polymer cells, and carbon fiber airframes.
Market Restraints
- Lithium-polymer cell volatility:Battery energy density improvements have plateaued, capping flight endurance at 10-30 minutes regardless of airframe optimization.
- Single-source sensor dependency:Optical flow and visual inertial navigation chipsets concentrate in Taiwanese fabs, exposing margin pools to geopolitical supply interruptions.
- EU Drone Regulation friction:CE marking requirements and class-specific conformity assessments extend product launch timelines by 8-14 months for non-European manufacturers.
Strategic Opportunities
- Environmental monitoring whitespace:Specialized rotary-wing designs for confined-space methane detection and wildlife tracking remain underpenetrated in Nordic conservation programs.
- Hybrid architecture convergence:Fixed-wing endurance combined with rotary-wing VTOL capability is unifying mission profiles without airframe swapping.
- Subscription software layering:Fleet management platforms are displacing perpetual licenses with recurring service contracts that lock enterprise infrastructure accounts.
Industry Challenges
- RF engineer scarcity:Firmware developers capable of integrating Remote ID broadcast protocols with proprietary flight control stacks command premium compensation that mid-tier vendors cannot match.
- Certification timeline compression:Divergent FAA, EASA, and MIIT radio transmission standards force manufacturers to maintain three distinct hardware variants, fragmenting production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Micro Drone Market |
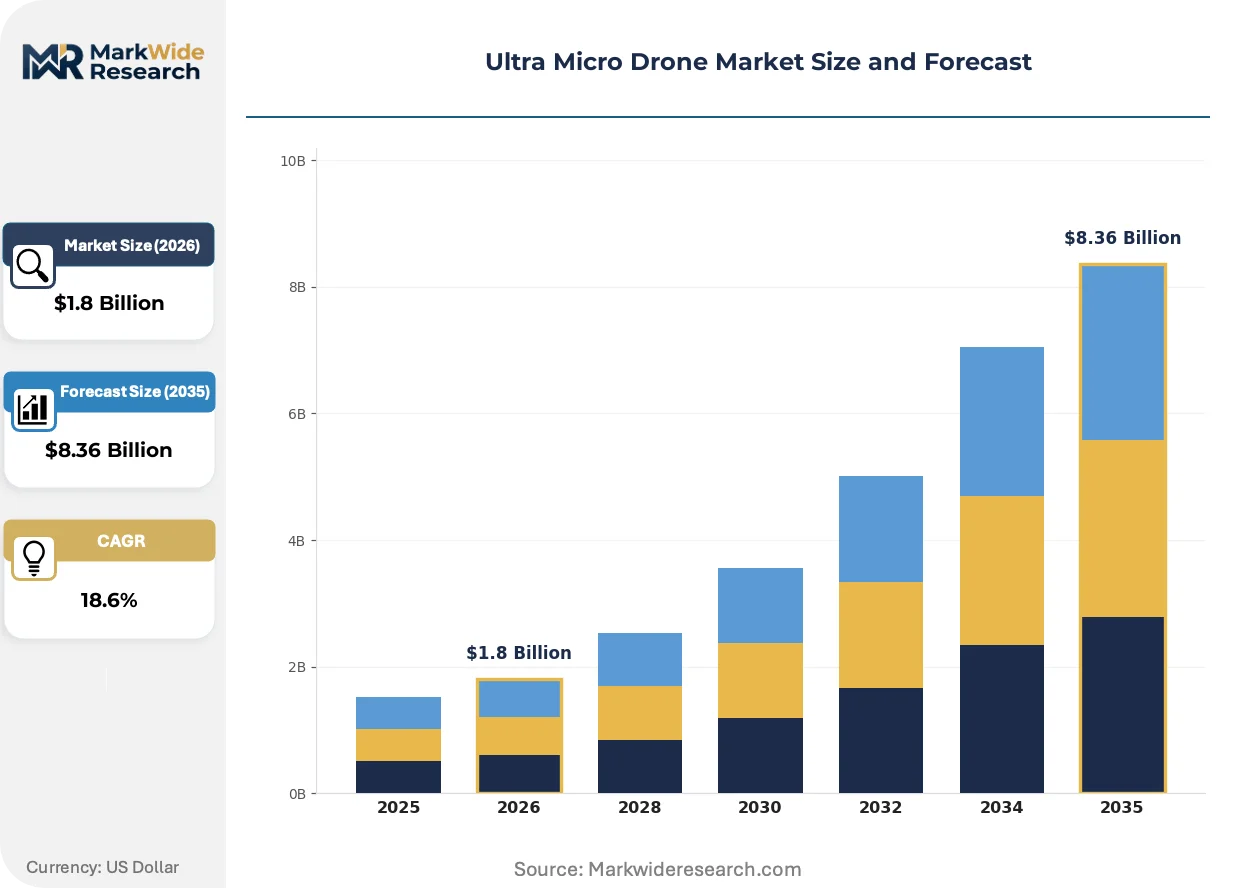
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Flapping-Wing, Hybrid, Single Rotor Technology: Optical Flow, GPS Navigation, Infrared Sensors, Ultrasonic Sensors, Visual Inertial Application: Surveillance, Environmental Monitoring, Search & Rescue, Entertainment, Structural Inspection End User: Defense Forces, Agriculture Specialists, Emergency Responders, Film Production, Infrastructure Inspectors |
| Companies Covered | DJI, Parrot SA, Yuneec International, AeroVironment, Hubsan, 3D Robotics, senseFly, Walkera, Extreme Fliers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Micro Drone Market Trends and Innovations
Sensor fusion architectures and autonomous navigation stacks are compressing the technical barrier between commodity toy-grade platforms and enterprise-grade inspection tools, collapsing historical price-performance segmentation.
Optical flow and visual inertial navigation is unifying positioning capability in GPS-denied environments. Infrastructure inspection teams in Germany and Japan are adopting these sensor stacks for bridge underdeck and tunnel wall surveys. The technology is unifying previously separate hardware categories into single-platform solutions.
China's MIIT enforcement of GB standards on radio transmission power is reshaping exportable product specifications for manufacturers targeting domestic and international markets simultaneously. Vendors must now design dual-firmware architectures that throttle output power based on detected geographic location. Hardware destined for European distribution requires distinct RF front-ends to satisfy EASA spectrum allocation rules.
After-sales service unbundling is fragmenting traditional bundled support contracts. Enterprise buyers in Australia's mining sector now procure airframes, pilot training, and maintenance subscriptions through separate channel relationships. This decomposition favors specialized software vendors who can integrate across heterogeneous hardware fleets rather than original equipment manufacturers with captive service arms.
Ultra Micro Drone Market Segmentation
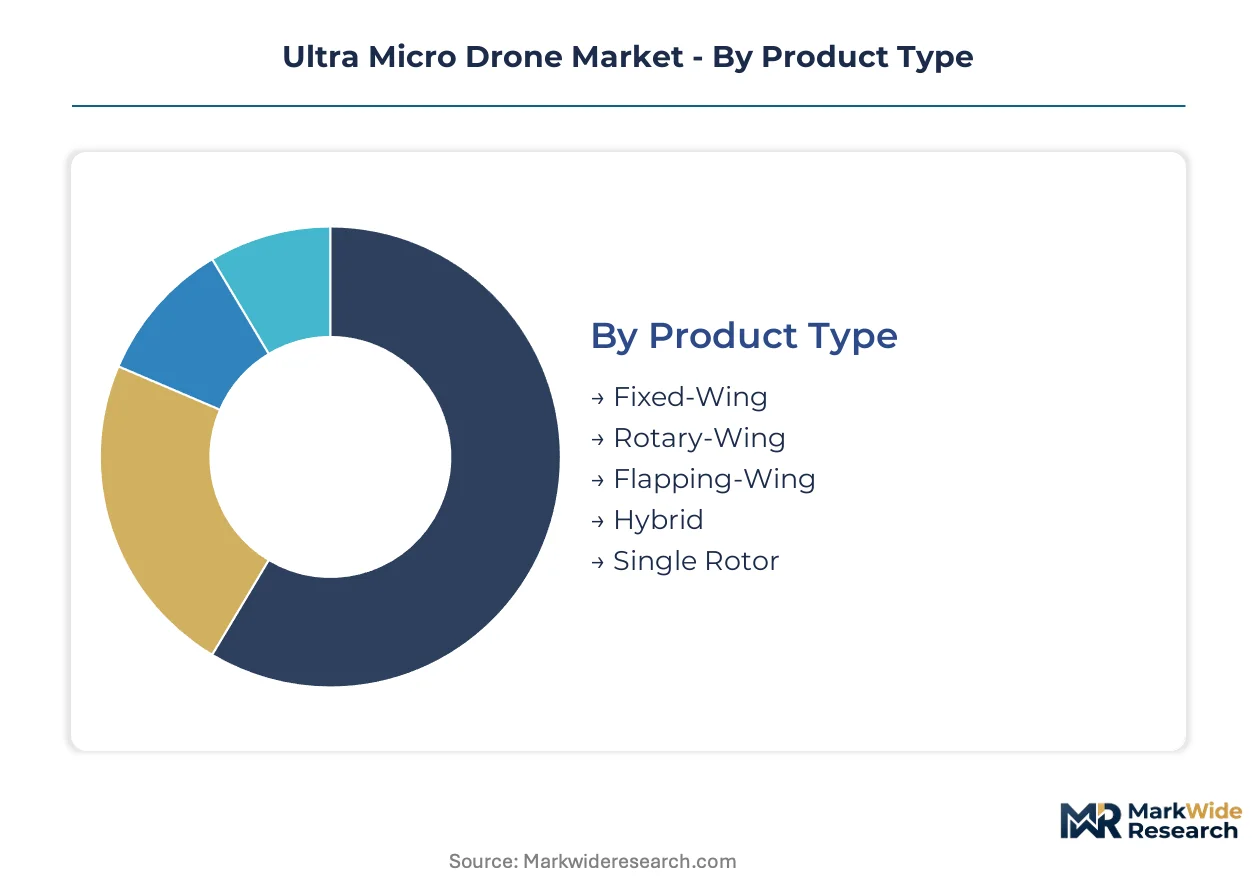
Ultra micro drone procurement decisions pivot on payload capacity, flight endurance, and navigation autonomy. Segment boundaries blur as hybrid architectures absorb capabilities from historically distinct product categories. Understanding these overlaps reveals where vendor R&D investments concentrate and which technology stacks command pricing premiums.
Product Type:
Rotary-wing platforms dominate shipment volumes through mechanical simplicity, while hybrid architectures capture the steepest expansion trajectory as operators demand multi-mission flexibility without airframe swaps.
- Fixed-Wing:Carbon fiber reinforced polymer airframes with pusher or tractor propeller configurations achieve 25-30 minute endurance through aerodynamic efficiency. Demand concentrates in United States defense procurement for battlefield reconnaissance where range outweighs maneuverability constraints.
- Rotary-Wing:Quadrotor and hexarotor configurations with brushless DC motors and ducted rotors enable vertical takeoff in GPS-denied building interiors. Shenzhen manufacturing clusters supply 70% of global brushless motor volumes for this segment, compressing unit economics.
- Flapping-Wing:Biomimetic designs mimicking avian flight mechanics for acoustic signature reduction in sensitive wildlife monitoring.
- Hybrid:Tiltrotor or tail-sitter architectures combining fixed-wing cruise efficiency with rotary-wing hover capability.
- Single Rotor:Conventional helicopter layouts with swashplate mechanics for payload-heavy industrial applications.
Today's leader: Rotary-Wing. Tomorrow's challenger: Hybrid.
Technology:
Navigation autonomy separates commodity hardware from enterprise-grade platforms, with sensor fusion stacks concentrating margin pools in Taiwanese semiconductor fabs.
- Optical Flow:Downward-facing camera arrays tracking surface texture motion for position hold without GPS. German infrastructure inspection teams deploy these stacks for bridge underdeck surveys where satellite signals attenuate.
- GPS Navigation:Multi-constellation receivers leveraging GPS, GLONASS, and BeiDou for outdoor waypoint missions. FAA Remote ID mandates require broadcast modules that integrate with these navigation cores.
- Infrared Sensors:Thermal imaging payloads for search and rescue operations detecting heat signatures through smoke or foliage.
- Ultrasonic Sensors:Proximity detection for indoor obstacle avoidance in warehouse inventory applications.
- Visual Inertial:Camera-IMU fusion algorithms enabling simultaneous localization and mapping in subterranean tunnel complexes.
Cost leadership sits with GPS Navigation. Premium positioning belongs to Visual Inertial.
Application:
Mission specificity determines sensor payload integration, with surveillance and structural inspection absorbing the majority of enterprise software subscription revenues.
- Surveillance:Persistent overwatch missions requiring encrypted video downlinks and counter-UAS detection compatibility. United States urban warfare doctrine drives procurement of palm-sized platforms for building interior reconnaissance.
- Environmental Monitoring:Methane detection and wildlife tracking in Nordic conservation programs using specialized rotary-wing designs.
- Search & Rescue:Thermal-equipped platforms for disaster response in GPS-denied environments.
- Entertainment:Cinematography and light-show coordination demanding precise formation flight algorithms.
- Structural Inspection:Close-proximity data capture for bridge, turbine, and pipeline integrity assessment.
Defense budgets anchor Surveillance. Commercial expansion favors Structural Inspection.
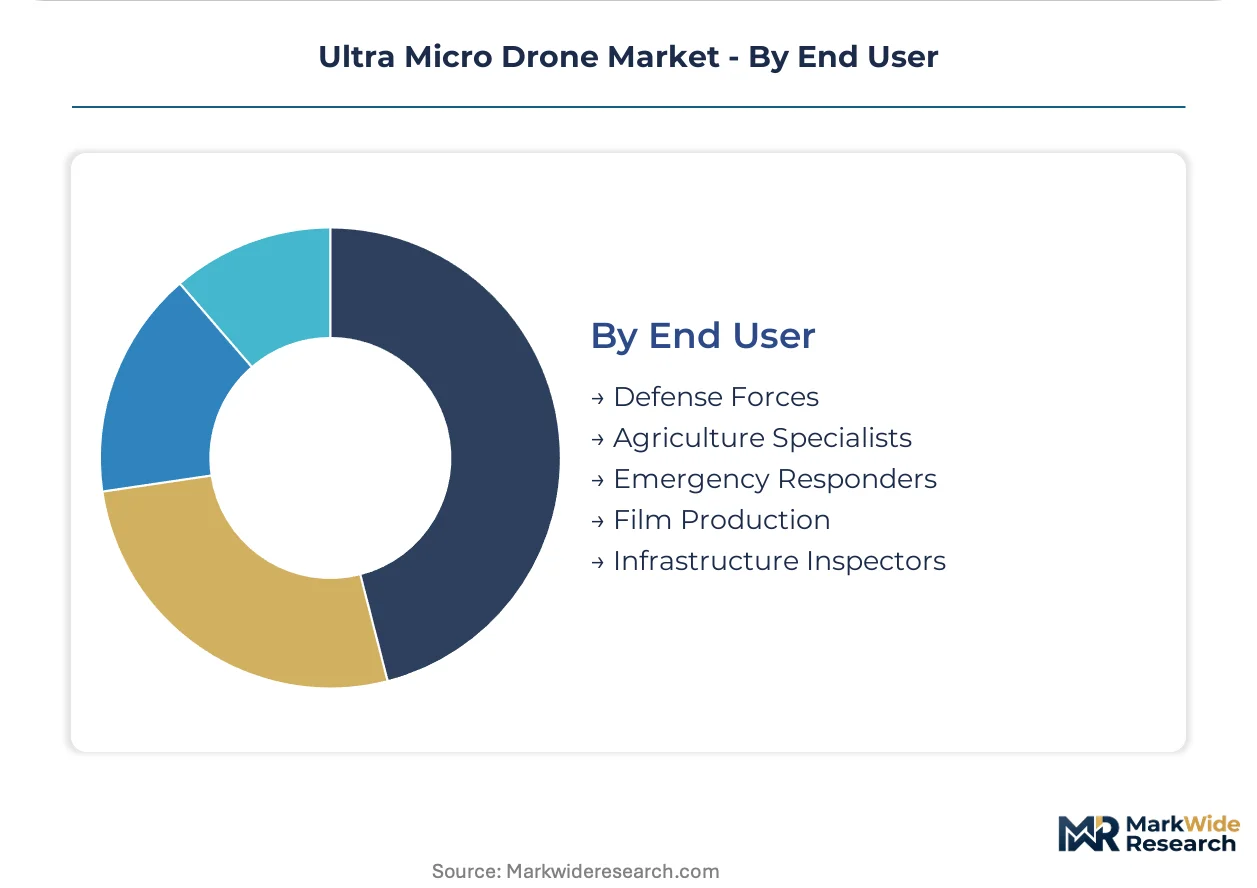
End User:
Procurement authority fragments across federal defense offices, municipal emergency departments, and private infrastructure operators with diverging compliance requirements.
- Defense Forces:Counter-UAS detection compatibility and kill-switch protocols mandated as contract preconditions. RF signature standardization shapes firmware architecture from initial design phases.
- Agriculture Specialists:Crop health monitoring and precision spraying in GPS-challenged canopy environments.
- Emergency Responders:Rapid deployment requirements for wildfire perimeter mapping and hazmat incident assessment.
- Film Production:Cinematic capture demanding gimbal stabilization and low-latency video transmission.
- Infrastructure Inspectors:Recurring fleet management software subscriptions displacing perpetual licenses across Australian mining and German utility sectors.
Defense Forces set technical specifications. Infrastructure Inspectors drive recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are fragmenting production geography as Shenzhen's cost-of-compliance advantage erodes under stricter GB standards, pushing some final assembly toward Vietnam and Mexico while core component fabrication remains concentrated in China's Pearl River Delta.
United States
Defense procurement offices in Arlington and Huntsville are mandating counter-UAS detection compatibility for all palm-sized reconnaissance contracts. FAA Part 107 remote pilot certification requirements are reshaping commercial operator compliance burdens. Austin and Boston clusters host emerging autonomy software vendors serving infrastructure inspection workflows.
China
Shenzhen manufacturing compresses brushless motor and lithium-polymer cell supply chains to unmatched density. MIIT enforcement of GB standards on radio transmission power forces dual-firmware architectures for export-bound hardware. Dongguan carbon fiber airframe fabricators supply 70% of global rotary-wing platform volumes.
Germany
Infrastructure inspection teams in Munich and Hamburg deploy optical flow sensor stacks for bridge underdeck surveys where GPS signals attenuate. EASA spectrum allocation rules require distinct RF front-ends from hardware destined for other markets. Stuttgart automotive suppliers are adapting visual inertial navigation for factory-floor quality control applications.
Japan
Tokyo-based emergency responders demand rapid-deployment platforms for disaster perimeter mapping in GPS-challenged urban canyons. METI standards on radio equipment conformity extend product launch timelines for non-domestic manufacturers. Nagoya industrial automation specialists integrate ultra micro drones into precision manufacturing workflows.
Australia
Mining sector buyers in Perth and Brisbane now unbundle airframe procurement from pilot training and maintenance subscriptions. The country's civil aviation safety regulator enforces remote pilot licensing that commercial operators must navigate for infrastructure surveys. Melbourne software vendors are capturing fleet management contracts across heterogeneous hardware fleets.
Ultra Micro Drone Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated platform vendors while commercial infrastructure buyers accept hardware-agnostic software layers. The vendor base concentrates around three strategic archetypes: Shenzhen-anchored component integrators, European sensor-stack specialists, and North American defense contractors. Dominant competitive moves include geographic diversification of final assembly to Vietnam and Mexico, plus backward integration into captive brushless motor production.
Within the integrated platform tier, DJI and Parrot SA exemplify divergent positioning strategies, while AeroVironment occupies a distinct defense-contractor archetype. DJI represents the Shenzhen-anchored full-stack model with App-based flight planning ecosystems. Parrot SA exemplifies specialized rotary-wing design optimization for confined-space environmental monitoring. AeroVironment anchors the fixed-wing battlefield reconnaissance segment through relationships with United States defense procurement offices.
| Leading Market Players |
|---|
| DJI |
| Parrot SA |
| Yuneec International |
| AeroVironment |
| Hubsan |
| 3D Robotics |
| senseFly |
| Walkera |
| Extreme Fliers |
| Others |
Pricing and Supply Chain Analysis
Dual-firmware architectures for geographic RF compliance are compressing development amortization across smaller production batches while fragmenting final assembly geography. Shenzhen's brushless motor and lithium-polymer cell clusters retain upstream margin capture, yet Vietnam and Mexico are absorbing tariff-sensitive final assembly as China's GB standards tighten.
Pricing Analysis
Distributor margins for enterprise fleet management software subscriptions now exceed hardware resale spreads by a factor of three, anchoring vendor profitability. Three-tier pricing structure across premium visual-inertial navigation, standard GPS-guided platforms, and economy optical-flow units differentiates on certification grade and sensor fusion complexity. Cost compression in the economy tier intensifies because Shenzhen component oversupply erodes brushless motor pricing. Defense procurement offices show least price sensitivity due to counter-UAS compatibility mandates, while Australian mining sector buyers unbundle services to drive hardware-only negotiation.
Supply Chain Analysis
Domestic-content mandates in United States defense procurement are forcing dual-source qualification for carbon fiber airframes and RF front-end modules. Component fabrication concentrates in China, Taiwan, and South Korea, with Taiwanese fabs supplying optical flow and visual inertial navigation chipsets. The chain rests on lithium-polymer cells, brushless DC motors, and carbon fiber reinforced polymers as core inputs. Single-source vulnerability in Taiwanese semiconductor fabrication exposes margin pools to geopolitical interruption. Distribution runs through direct OEM relationships for defense contracts and software-integrated channel partners for commercial infrastructure accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on sensor fusion software layering displacing hardware-centric revenue models, with autonomous navigation stacks capturing value previously lost to commodity airframe competition.
For Market Incumbents: Hedge against RF engineer scarcity by captive recruitment in Austin and Boston autonomy clusters while accelerating backward integration into brushless motor production. Defense contract eligibility now requires kill-switch protocol standardization from initial design phases, raising firmware architecture barriers that mid-tier vendors cannot match. Certification investment across FAA, EASA, and MIIT variants fragments production runs but locks out unqualified competitors. For New Entrants and Emerging Players: Enter via Nordic environmental monitoring whitespace where specialized rotary-wing designs for methane detection remain underpenetrated. Wildlife tracking applications in GPS-denied conservation zones offer the most penetrable segment due to incumbent neglect of small-batch customization. Go-to-market should anchor on software-agnostic fleet management platforms that integrate across heterogeneous hardware estates rather than competing on airframe specifications. For Investors and Strategic Acquirers: Roll-up economics work for autonomy software specialists because defense procurement offices now mandate counter-UAS detection compatibility that fragmented hardware vendors cannot self-develop. Long-term viability favors platforms with recurring service contract density over transactional hardware shipments. Watch for FAA Remote ID enforcement acceleration as the inflection signal indicating compliance-capable vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Stack Acquisition | Captures margin pools concentrated in Taiwanese fabs while reducing single-source dependency. |
| Dual-Firmware Architecture Development | Enables simultaneous China domestic and export-bound production under divergent MIIT and EASA rules. |
| Fleet Management Platform Launch | Locks enterprise infrastructure accounts through recurring subscriptions displacing perpetual licenses. |
| Final Assembly Geographic Diversification | Mitigates tariff exposure by shifting carbon fiber airframe integration to Vietnam and Mexico. |
| Defense Certification Pre-Qualification | Secures contract eligibility through standardized RF signatures and kill-switch protocol integration. |
Research Methodology
Coverage spans United States, China, Germany, Japan, and Australia, with primary inputs from each market's defense procurement offices, infrastructure inspection operators, and autonomy software developers. The approach combines primary interviews with fleet management executives, RF firmware engineers, and commercial drone pilots with secondary validation through FAA regulatory filings, EASA conformity assessment databases, and MIIT GB standard publications. Bottom-up shipment estimates triangulate against top-down defense budget allocations and commercial infrastructure inspection spending.
Granularity-level modeling disaggregates rotary-wing, fixed-wing, and hybrid architectures separately while tracking optical flow, GPS navigation, and visual inertial technology stacks as distinct price-performance tiers. End-use segmentation captures surveillance, structural inspection, and environmental monitoring mission profiles with diverging sensor payload requirements. CAGRs derive from installed base replacement cycles and procurement pipeline visibility across the projection horizon. Forecast inputs incorporate lithium-polymer cell energy density plateaus and Remote ID mandate compliance timelines.
Inputs from defense procurement databases and commercial fleet operator surveys were available through the study window; gaps in subterranean tunnel complex deployment metrics introduce uncertainty bands around GPS-denied navigation demand estimates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and component supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
US Commercial Drone Market
UAV
Global Drone Light Shows Market
UAV
Drone Tracking Antenna Market
UAV
Drone Data Management Market
UAV
Tactical UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Passenger Drones Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Fuel Cell UAV Market
UAV
Asia-Pacific Drone Motor Market
UAV
Drone Wireless Charging Station Market
UAV
Fixed Wing Military Drones Market
UAV
FPV Drone Goggles Market
UAV
Electric Glider Market
UAV
North America Drone Software Market
UAV
UAV Lidar Market