
 Asia-Pacific Drone Motor Market | 2026-2036
Asia-Pacific Drone Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drone Motor Market Analytics
Brushless motor performance tiers above 300W is bifurcating the competitive landscape as commercial operators prioritize thrust-to-weight ratios for heavy-lift applications. Nidec Corporation leverages its precision magnetics expertise to sustain dominance in high-reliability segments. T-Motor anchors the agricultural spraying sub-market with specialized winding architectures that resist humidity degradation across tropical climates.
Asia-Pacific drone motors are electromechanical rotary actuators converting DC electrical energy into mechanical torque through permanent magnet synchronous or brushed commutation architectures, typically operating at 10,000-30,000 RPM with kV ratings calibrated to propeller load profiles. Their primary purpose is generating sufficient thrust for controlled multirotor or fixed-wing flight under variable payload and atmospheric conditions. Brushless configurations now command the largest installed base due to superior thermal efficiency and reduced maintenance intervals in commercial duty cycles. The 100W-200W power band represents the fastest-expanding segment as last-mile delivery drones proliferate across dense urban corridors. Agricultural surveillance applications concentrate margin pools where dust-sealed bearing systems and IP67 ingress protection justify premium positioning.
China's MIIT enforces GB standards for UAV airworthiness that mandate motor redundancy protocols in commercial platforms above specified weight thresholds, directly elevating dual-motor architecture adoption. Japan's METI coordinates with JIS standards bodies to establish electromagnetic compatibility benchmarks for beyond-visual-line-of-sight operations, shaping export qualification requirements for regional suppliers. India's DGCA operational guidelines for drone corridors impose noise and reliability thresholds that filter brushed motor entrants from urban logistics contracts. Stakeholders must monitor evolving certification reciprocity agreements between national aviation authorities to anticipate which motor specifications will unlock cross-border fleet deployments.
Market Dynamics
China's MIIT certification tightening for UAV airworthiness is forcing brushless motor architecture upgrades across commercial fleets, compressing brushed motor supplier margins while elevating dual-redundancy system demand.
Growth Catalysts
- Precision agriculture expansion:Southeast Asian palm oil and rice producers are scaling drone spraying fleets, driving sustained orders for high-thrust motors with humidity-resistant winding systems.
- MIIT GB standard enforcement:China's mandatory motor redundancy protocols for commercial platforms above weight thresholds are accelerating dual-motor architecture adoption.
- Last-mile logistics corridors:Dense urban delivery networks across Tokyo, Seoul, and Singapore are concentrating procurement for 100W-200W power band motors optimized for vertical takeoff cycles.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing dominance by Chinese state-controlled entities creates input cost volatility and geopolitical exposure for motor assemblers.
- IP67 sealing cost premiums:Dust-sealed bearing systems and ingress protection for agricultural duty cycles add 15-25% manufacturing overhead versus standard commercial motors.
- Brushed motor substitution ceiling:Legacy brushed architectures retain cost advantage in hobbyist segments below 100W, limiting full brushless conversion in price-sensitive tiers.
Strategic Opportunities
- India DGCA corridor expansion:Designated drone corridors in Maharashtra and Karnataka impose reliability thresholds that filter low-grade motor entrants, creating premium positioning for certified suppliers.
- Japan METI electromagnetic compatibility standards:Beyond-visual-line-of-sight operation benchmarks are shaping export qualification requirements that regional suppliers can capture.
- Hybrid propulsion convergence:Gas-electric range extender systems for long-endurance surveillance drones are opening motor-generator integration contracts with defense integrators.
Industry Challenges
- Magnet wire winding automation:Precision coil winding for high-kV racing motors requires specialized capital equipment that mid-tier assemblers struggle to finance.
- Cross-border certification reciprocity gaps:Divergent airworthiness approval timelines between China's CAAC, Japan's JCAB, and Australia's CASA fragment fleet deployment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drone Motor Market |
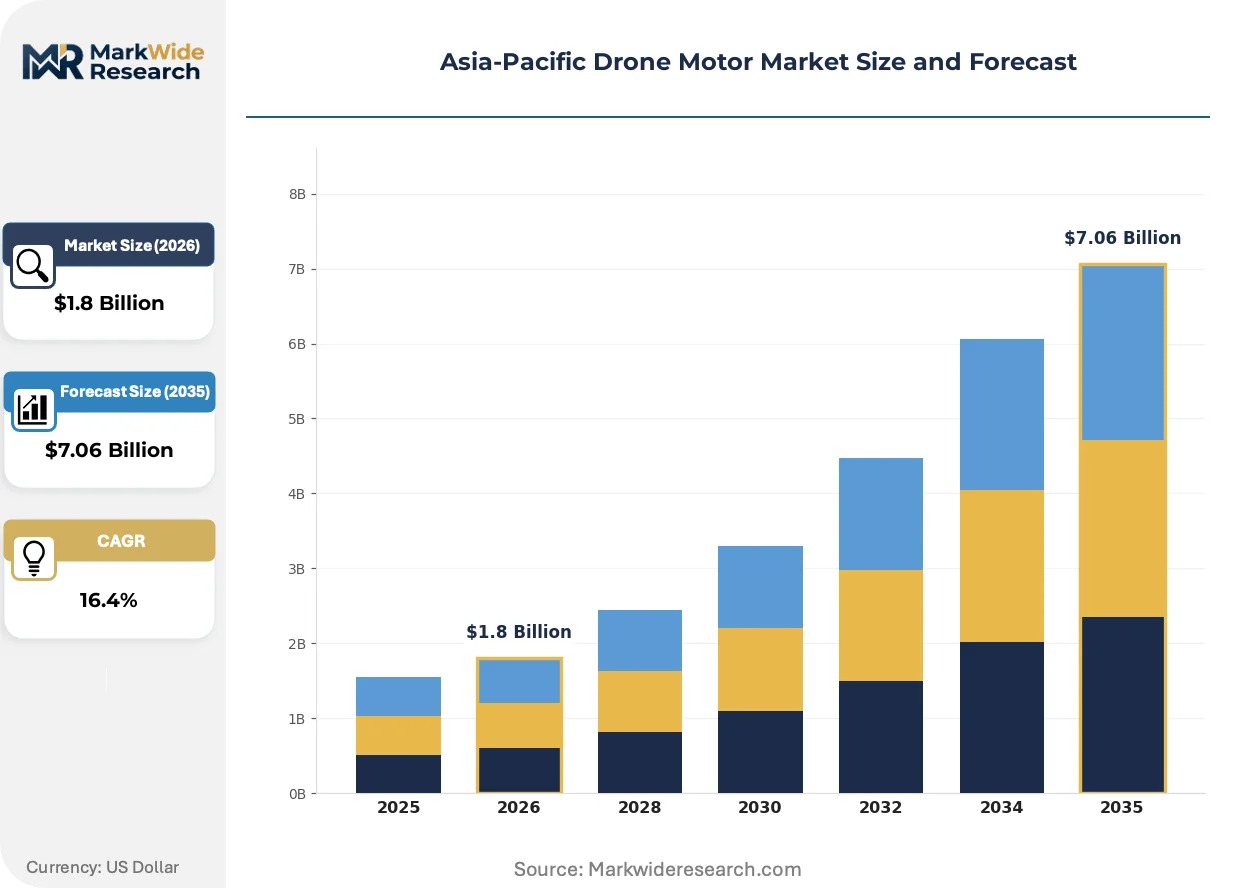
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless, Brushed, Coreless, Stepper Power Rating: Less than 100W, 100W-200W, 200W-300W, More than 300W Application: Aerial Photography, Agricultural Surveillance, Delivery Services, Mapping End User: Consumer, Commercial, Military, Industrial |
| Companies Covered | Nidec Corporation, Constar Micromotor Co., Ltd., Changzhou Fulling Motor Co., Ltd., Tiger Motor International Co., Ltd., KDE Direct, LLC, T-Motor, Jiangxi MAD Motor Components Co., Ltd., Tamagawa Seiki Co., Ltd., Dr. Fritz Faulhaber GmbH & Co. KG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drone Motor Market Evolving Landscape
Active thermal management architectures and magnet material substitution are compressing motor weight-to-thrust ratios while regulatory pressure on electromagnetic emissions is reshaping design priorities.
Halbach array magnet configurations are bifurcating the high-performance segment by delivering 15-20% flux density improvement over conventional radial magnet arrangements. Racing drone operators and cinematic aerial cinematography houses are adopting these arrays despite 30% cost premiums. The technology is bifurcating supplier tiers between precision magnetics specialists and commodity motor assemblers unable to replicate complex pole patterns.
Japan's METI coordination with JIS standards bodies on electromagnetic compatibility benchmarks for beyond-visual-line-of-sight operations is elevating shielding and filtering requirements. Motor suppliers must now submit to conducted emissions testing above 30MHz that previously applied only to complete aircraft systems. Agricultural surveillance platforms operating across Japan's mountainous terrain face the steepest compliance cost increases.
Direct procurement relationships between fleet operators and motor specialists are displacing traditional component distributor channels in volumes above 500 units annually. Large agricultural cooperatives in Vietnam and Thailand now negotiate winding specifications and thermal interface materials directly with Guangdong manufacturers. This channel compression is most visible where fleet standardization around single motor platforms enables volume commitment leverage.
Asia-Pacific Drone Motor Market Segmentation
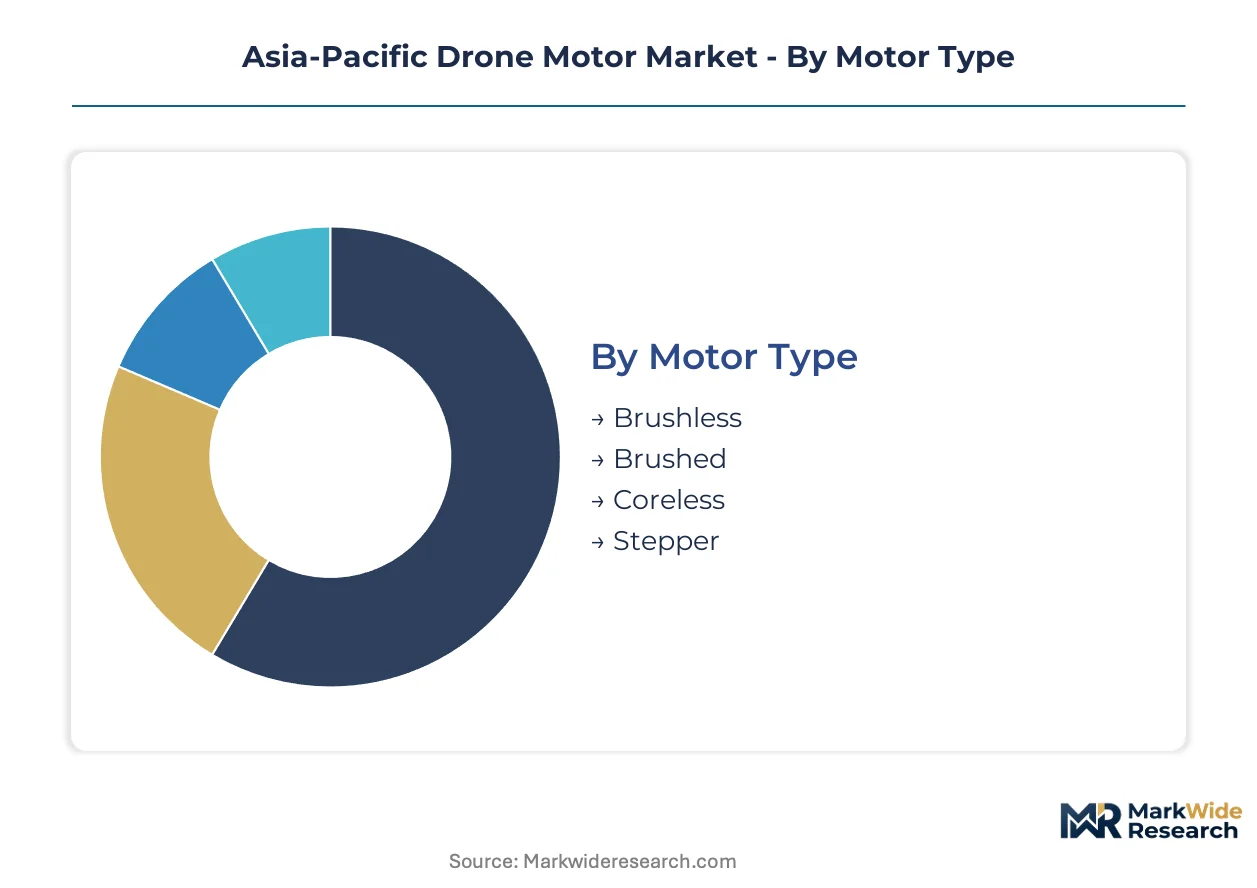
Drone motor segmentation in Asia-Pacific reflects divergent thermal architectures and duty cycle requirements across precision agriculture, urban logistics, and defense applications. Margin pools concentrate where IP67 sealing and redundancy protocols command premium positioning against commodity alternatives.
Motor Type:
Brushless configurations capture the deepest margin pools through superior efficiency in commercial duty cycles, while brushed architectures retain cost-driven hobbyist volumes.
- Brushless:Permanent magnet synchronous designs dominate commercial fleets above 100W through reduced maintenance intervals and thermal efficiency. Guangdong manufacturers prioritize these for agricultural spraying contracts across Vietnam and Thailand where humidity-resistant winding systems justify 20-30% price premiums.
- Brushed:Commutator-based architectures retain installed base in sub-100W consumer segments through 40-50% cost advantages. Price-sensitive hobbyist markets in Indonesia and Philippines sustain volume despite brushless substitution pressure from MIIT certification tightening.
- Coreless:Ironless rotor designs enable sub-50g racing drone motors with acceleration response below 50ms.
- Stepper:Discrete angular positioning suits camera gimbal stabilization and payload articulation systems.
Brushless holds installed capacity. Coreless is rotating up the share rankings in cinematic cinematography sub-segments.
Power Rating:
Volume concentration sits in the 100W-200W band where last-mile delivery networks optimize thrust-to-weight for vertical takeoff cycles, while heavy-lift applications above 300W extract premium positioning through specialized magnetics.
- 100W-200W:This band dominates procurement from Tokyo, Seoul, and Singapore logistics corridors where multirotor platforms execute 15-20 daily delivery cycles. Thermal management architectures prioritize rapid cool-down between flights over absolute efficiency metrics.
- More than 300W:Heavy-lift configurations for agricultural spraying and defense surveillance require Halbach array magnetics and active cooling. Japanese defense integrators specify these for hybrid propulsion range-extender platforms.
- Less than 100W:Consumer racing and toy segments concentrate in Shenzhen supply chains with minimal certification overhead.
- 200W-300W:Mid-tier commercial mapping and inspection drones balance payload capacity against battery density constraints.
100W-200W anchors current fleet deployments. Above-300W is climbing the fastest as precision agriculture scales in Southeast Asia.
Application:
Agricultural surveillance commands the steepest specification premiums where dust-sealed bearings and humidity-resistant windings separate qualified suppliers from commodity entrants.
- Agricultural Surveillance:Palm oil and rice producers across Malaysia and Indonesia scale precision spraying fleets requiring IP67 ingress protection. Dual-motor redundancy protocols under China's MIIT GB standards elevate brushless architecture adoption for platforms above 25kg.
- Delivery Services:Dense urban corridors impose noise thresholds and electromagnetic compatibility requirements that filter brushed motor suppliers. Japan's METI beyond-visual-line-of-sight benchmarks shape procurement specifications for Tokyo and Osaka networks.
- Aerial Photography:Cinematic houses prioritize kV precision and rapid throttle response for gimbal-stabilized platforms.
- Mapping:Survey-grade endurance requirements favor efficiency-optimized motors with extended mean-time-between-failures.
Agricultural surveillance concentrates margin pools. Delivery services is gaining share fastest as urban logistics corridors expand across Northeast Asia.
End User:
Commercial operators extract maximum specification leverage through direct procurement relationships with Guangdong manufacturers, while military integrators impose longest qualification timelines.
- Commercial:Fleet operators above 500 annual units negotiate winding specifications and thermal interface materials directly with manufacturers. Large agricultural cooperatives in Vietnam and Thailand standardize around single motor platforms to secure volume commitment pricing.
- Military:Defense integrators specify hybrid propulsion motor-generator architectures for long-endurance surveillance. Australia's defense procurement imposes electromagnetic compatibility testing that exceeds civilian CAAC or JCAB requirements.
- Consumer:Hobbyist segments retain brushed motor preference in price-sensitive tiers below 100W.
- Industrial:Infrastructure inspection and asset monitoring require extended temperature range operation.
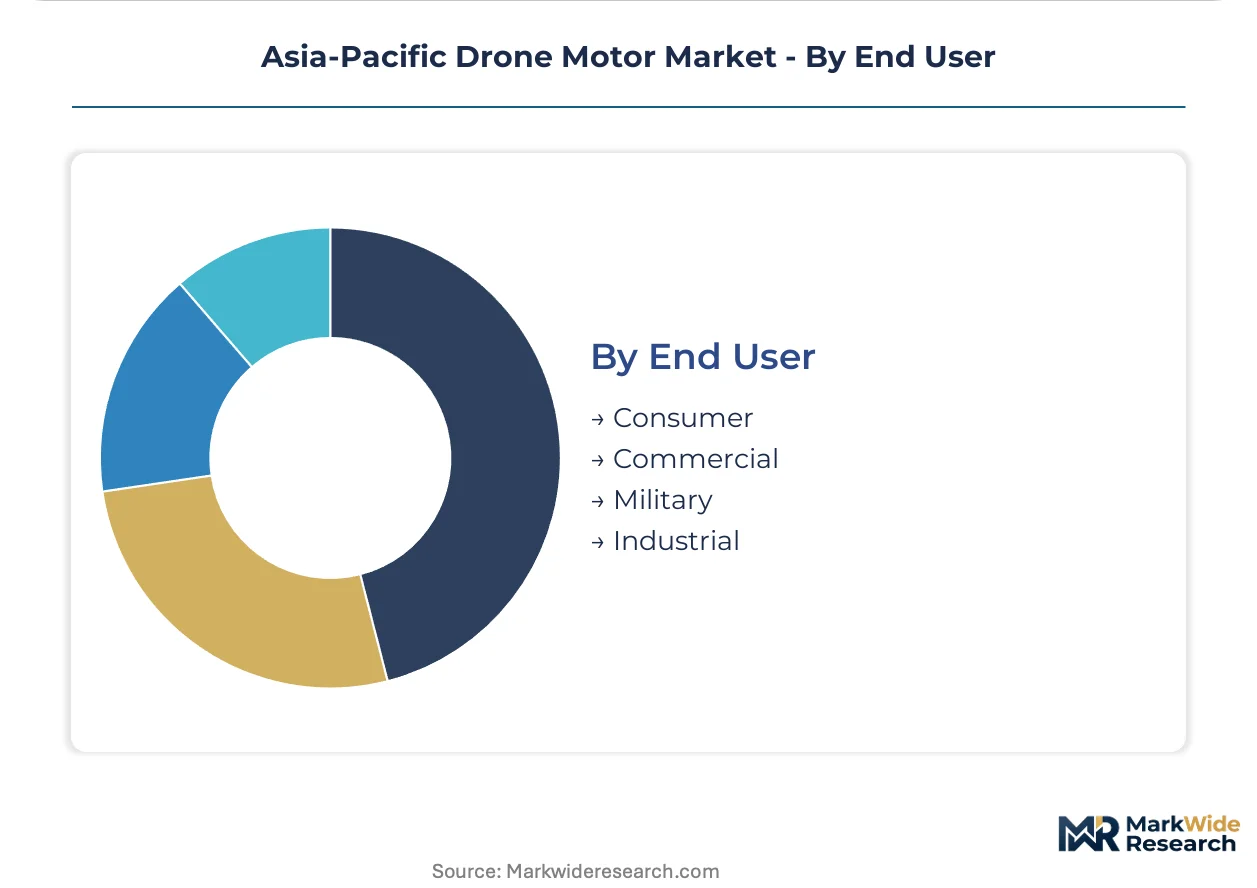
Commercial holds procurement volume concentration. Military is rotating up the share rankings through hybrid propulsion integration contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across the Asia-Pacific drone motor market reveal China as the dominant supplier to regional fleet operators, while Japan and South Korea remain net importers of high-reliability precision components. Trade flows concentrate through Guangdong and Jiangsu manufacturing corridors, with Vietnam and Thailand emerging as demand growth poles for agricultural spraying applications.
China
Precision agriculture fleet expansion and last-mile logistics corridor development drive sustained brushless motor procurement from Guangdong and Jiangsu manufacturing clusters. MIIT GB standards enforcement mandates dual-motor redundancy protocols for commercial platforms above specified weight thresholds. Shenzhen and Dongguan production hubs dominate export supply to Southeast Asian agricultural cooperatives.
Japan
Beyond-visual-line-of-sight delivery networks across Tokyo and Osaka corridors concentrate demand for electromagnetic compatibility-certified motors in the 100W-200W power band. METI coordination with JIS standards bodies elevates shielding and filtering requirements for conducted emissions testing above 30MHz. Nagoya precision manufacturing clusters supply defense integrators with hybrid propulsion motor-generator architectures.
India
Designated drone corridors in Maharashtra and Karnataka impose reliability thresholds that filter low-grade motor entrants from urban logistics contracts. DGCA operational guidelines create premium positioning opportunities for certified brushless suppliers. Bengaluru and Hyderabad aerospace clusters incubate domestic motor assembly capabilities for agricultural surveillance platforms.
South Korea
Seoul metropolitan delivery networks optimize vertical takeoff cycles through concentrated procurement of thermally efficient 100W-200W motors. National aviation authority noise thresholds shape specifications for dense urban operations. Incheon and Gyeonggi-do manufacturing zones import precision magnetics from Chinese suppliers while developing domestic winding capabilities.
Vietnam
Palm oil and rice producer cooperatives scale precision spraying fleets requiring IP67 ingress protection and humidity-resistant winding systems. Direct procurement relationships with Guangdong manufacturers displace traditional distributor channels for volumes above 500 units annually. Ho Chi Minh City logistics hubs coordinate regional fleet standardization around single motor platforms.
Asia-Pacific Drone Motor Market Competitive Landscape
Concentration sits with precision magnetics specialists and agricultural-duty motor fabricators who command premium positioning through certification depth. The vendor base stratifies across three tiers: multinational component conglomerates with integrated magnet supply chains, mid-cap winding specialists serving tropical climate applications, and commodity assemblers competing on cost in sub-100W consumer segments. Dominant competitive moves include backward integration into rare earth magnet sourcing and direct procurement channel compression with large fleet operators.
Within the precision magnetics tier, Nidec Corporation and Tamagawa Seiki Co., Ltd. exemplify Japanese specialists occupying positions defined by electromagnetic compatibility certification depth. T-Motor represents the agricultural-duty archetype, anchoring humidity-resistant winding specifications for Southeast Asian spraying applications. These three companies illustrate how regulatory compliance capabilities and climate-specific engineering separate premium suppliers from commodity entrants in an increasingly specification-driven procurement environment.
| Leading Market Players |
|---|
| Nidec Corporation |
| Constar Micromotor Co., Ltd. |
| Changzhou Fulling Motor Co., Ltd. |
| Tiger Motor International Co., Ltd. |
| KDE Direct, LLC |
| T-Motor |
| Jiangxi MAD Motor Components Co., Ltd. |
| Tamagawa Seiki Co., Ltd. |
| Dr. Fritz Faulhaber GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Ninety-day magnet wire inventory cycles in Guangdong manufacturing corridors concentrate pricing power with precision winding specialists serving agricultural fleet operators. This lead-time compression elevates dual-motor redundancy premiums while forcing commodity assemblers toward thin-margin hobbyist segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Premium positioning rests on IP67 certification depth and MIIT GB standard compliance, while price differentiation separates humidity-resistant winding systems from standard commercial motors. Cost compression in the sub-100W brushed tier is intensifying because Indonesian and Philippine hobbyist segments resist brushless upgrades. Agricultural cooperatives above 500-unit annual volumes exhibit lowest price sensitivity through direct procurement leverage.
Supply Chain Analysis
Port congestion across Shenzhen-Dongguan export corridors elevates inbound logistics costs for Japanese and South Korean defense integrators sourcing precision magnetics. Supply concentrates in China's Guangdong and Jiangsu manufacturing clusters, with secondary winding capabilities emerging in Vietnam and Thailand. Rare earth magnet processing draws from Chinese state-controlled entities, creating single-source vulnerability for neodymium-dependent Halbach array configurations. Distribution runs through direct procurement relationships displacing traditional component distributors for fleet operators above volume thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific drone motor demand is accelerating through regulatory inflection as China's MIIT GB standards mandate dual-redundancy architectures above weight thresholds, compressing brushed motor viability windows.
For Market Incumbents: Secure backward integration into rare earth magnet sourcing to insulate against Chinese state-controlled supply volatility. Defend agricultural spraying margins through captive humidity-resistant winding production in Dongguan corridors. Channel control via direct procurement relationships with Vietnamese palm oil cooperatives offsets distributor displacement pressure from Guangdong manufacturers. For New Entrants and Emerging Players: Anchor in India's DGCA-certified drone corridors where reliability thresholds filter low-grade competitors from Maharashtra and Karnataka urban logistics contracts. The most penetrable white-space sits in hybrid propulsion motor-generator integration for Japanese defense range-extender platforms. Go-to-market execution should leverage electromagnetic compatibility pre-certification against METI-JIS benchmarks to accelerate beyond-visual-line-of-sight qualification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant precision magnetics divisions lacking drone-specific certification depth. Long-term viability over the next decade hinges on regulatory reciprocity expansion enabling cross-border fleet deployments. Monitor MIIT-CAAC-JCAB harmonization negotiations as the decisive inflection signal for premium supplier valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Sourcing | Captive neodymium supply insulates Japanese and Korean assemblers from Chinese state-controlled price volatility. |
| Dual-Motor Redundancy Architecture Certification | MIIT GB standard compliance unlocks commercial platforms above 25kg in China's precision agriculture corridors. |
| Direct Procurement Channel Development | Volume commitment leverage with Vietnamese cooperatives displaces distributor margins for Guangdong manufacturers. |
| Hybrid Propulsion Motor-Generator Integration | Defense integrators in Nagoya specify these architectures for long-endurance surveillance range-extender contracts. |
| Electromagnetic Compatibility Pre-Certification | METI-JIS shielding benchmarks accelerate beyond-visual-line-of-sight approval for Tokyo-Osaka delivery networks. |
Research Methodology
The analysis maps brushless motor architectures, brushed legacy segments, coreless racing configurations, and hybrid propulsion systems, each validated through procurement directors at agricultural cooperatives, winding engineers at Guangdong manufacturers, electromagnetic compliance specialists at METI-coordinated laboratories, and fleet operations managers at Japanese logistics integrators. Primary interview findings triangulate against customs trade data from China and Vietnam, MIIT certification registries, JIS electromagnetic compatibility test reports, and DGCA drone corridor designations. Bottom-up unit economics from motor assemblers reconcile with top-down fleet deployment projections across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including rare earth magnet consumption patterns, agricultural spraying fleet registrations, and urban logistics corridor procurement disclosures. Segmentation modeling spans motor type, power rating band, application vertical, and end-user procurement scale throughout the forecast period. CAGRs derive from installed base turnover assumptions, certification timeline acceleration, and substitution elasticity between brushed and brushless architectures. Industry-specific inputs include MIIT GB standard enforcement schedules and METI-JIS electromagnetic compatibility adoption curves.
Decision-makers should treat outputs as directional under sustained MIIT certification tightening and stable rare earth supply chain configurations; material deviation in regulatory reciprocity timelines or magnet export restrictions would warrant model refresh. Forecasts assume continued agricultural surveillance fleet expansion across Southeast Asia and last-mile logistics corridor development in Northeast Asian metropolitan zones. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Asia-Pacific Drone Light Shows Market
UAV
Europe Drones Market
UAV
North America Small UAV Market
UAV
Bubble Drone Market
UAV
GCC Drone Pilot Training Market
UAV
GCC Drones Market
UAV
North America Tactical UAV Market
UAV
Military UAV Sensor Market
UAV
Miniature Drone Market
UAV
UAV Payload Market
UAV
Short-Range Delivery Drone Market
UAV
Nano Drones Market
UAV
Stratospheric Flying Drone Market
UAV
North America Fuel Cell UAV Market
UAV
Ultra-Long Endurance Drone Market
UAV
Global Drone Analytics Market