
 UAV Sense-And-Avoid Systems Market | 2026-2036
UAV Sense-And-Avoid Systems Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Sense-And-Avoid Systems Market Insights
Software-defined radar updates delivered through subscription licensing is recalibrating how prime contractors monetize sense-and-avoid capabilities. Lockheed Martin leverages its classified signal-processing heritage to anchor high-assurance military contracts. Thales Group competes through dual-use positioning, sustaining civilian certification momentum alongside defense programs. uAvionix Corporation specializes in compact transponder-integrated solutions for commercial drones, occupying a distinct tier below prime integrators.
UAV sense-and-avoid systems comprise integrated sensor suites—typically combining radar, electro-optical, and LiDAR modalities with onboard fusion algorithms—that autonomously detect, track, and maneuver unmanned aircraft around cooperative and non-cooperative intruders. These systems operate with sub-second latency requirements and must function across GPS-denied environments to prevent mid-air collisions in civilian and military airspace. Electro-optical and infrared technologies lead current deployment volumes due to mature supply chains and lower unit costs, while LiDAR segments are gaining fastest in urban air mobility applications where three-dimensional obstacle mapping is critical. Defense agencies represent the deepest margin pool, though agricultural enterprises and energy operators are expanding commercial adoption of scaled-down configurations.
FAA detect-and-avoid rules under Part 89 remote identification framework and EASA's SORA methodology for specific-category operations are reshaping certification burdens and product roadmaps for manufacturers serving transatlantic markets. The EU AI Act's risk-classification approach to autonomous decision systems adds compliance complexity for vendors deploying machine-learning-based collision avoidance in European airspace. Stakeholders must monitor divergence between military hardening standards and civilian certification pathways, as this gap determines which sensor architectures achieve scalable dual-use deployment.
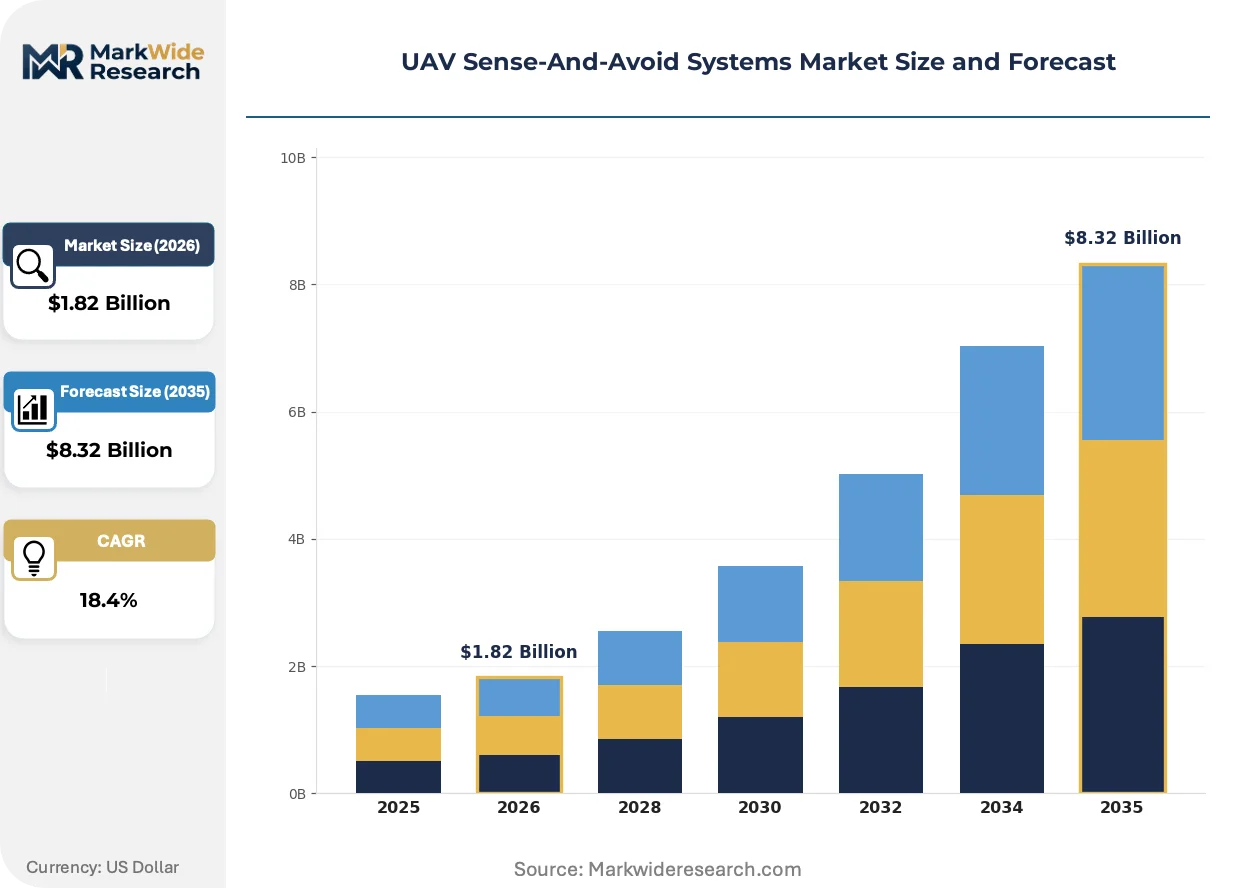
Market Dynamics
Software-defined radar architectures are compressing hardware refresh cycles while subscription licensing restructures contractor revenue streams away from unit sales toward recurring service models.
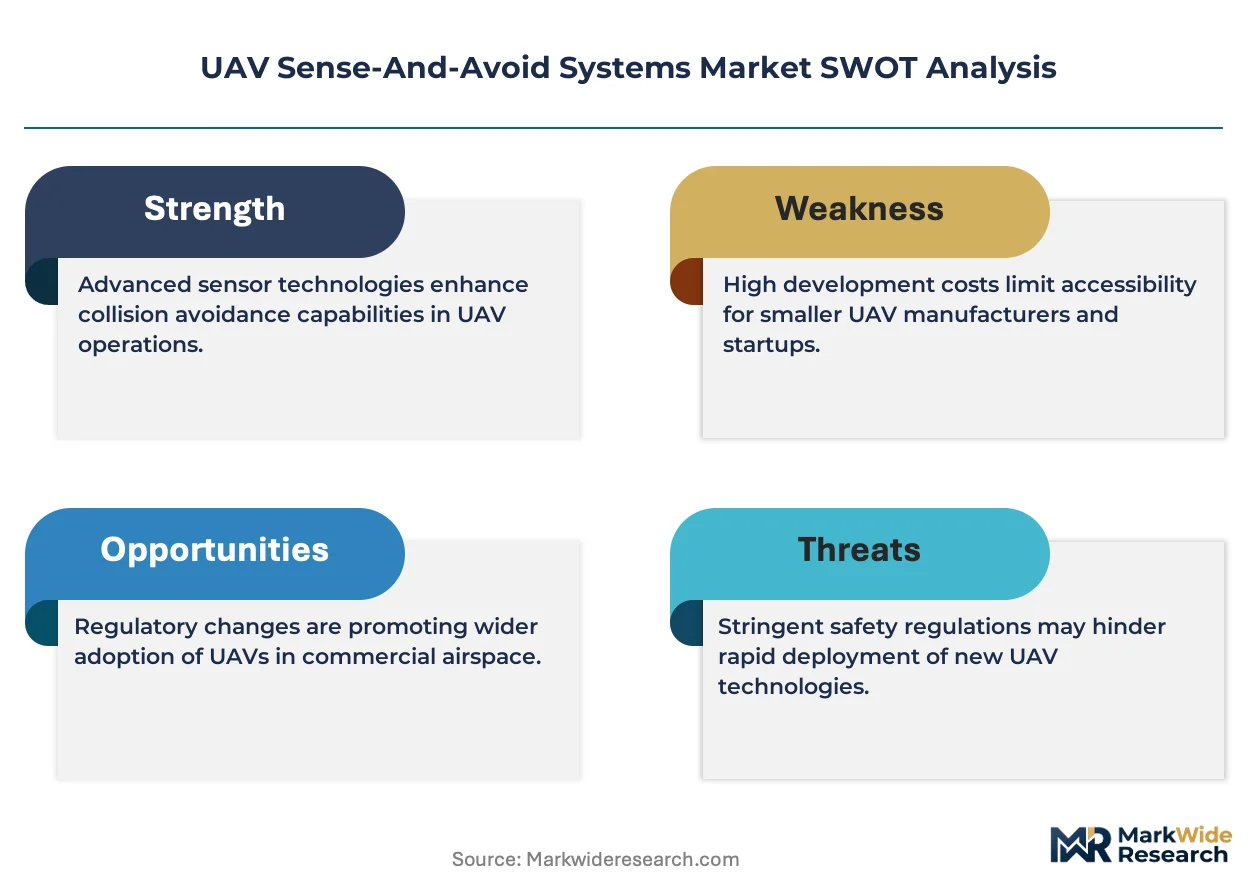
Growth Catalysts
- FAA Part 89 Remote ID Mandate:Commercial operators must equip detect-and-avoid capabilities for beyond-visual-line-of-sight authorization, forcing fleet-wide sensor upgrades.
- Urban Air Mobility Corridors:Three-dimensional obstacle mapping requirements in dense metropolitan environments are accelerating LiDAR fusion deployments.
- NATO Autonomous Detection Procurement:Allied defense agencies are standardizing multi-sensor suites for interoperable unmanned fleet operations.
Market Restraints
- Gallium Nitride Supply Concentration:RF component fabrication depends on specialized foundry capacity concentrated in East Asian manufacturing clusters.
- EASA SORA Certification Burden:Specific-category operational risk assessments impose documentation requirements that extend product qualification timelines.
- Electro-Optical Performance Limits:Adverse weather degradation constrains standalone camera-based systems in maritime and arctic deployments.
Strategic Opportunities
- Agricultural Autonomous Spraying:Low-altitude crop-dusting operations in Brazil and Australia present unmet collision-avoidance needs for rotorcraft fleets.
- EU AI Act Risk Classification:Machine-learning-based decision systems face harmonized compliance pathways that reward pre-certified algorithmic architectures.
- Energy Infrastructure Inspection:Pipeline and transmission tower surveys require GPS-denied navigation capabilities in remote terrain.
Industry Challenges
- Sensor Fusion Engineering Talent:Shortage of specialists capable of integrating radar, electro-optical, and LiDAR modalities with real-time Kalman filtering.
- Dual-Use Certification Divergence:Military hardening standards and civilian FAA pathways require parallel validation streams that fragment R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Sense-And-Avoid Systems Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $8.32 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, LiDAR, Infrared, Electro-Optical, Ultrasonic, Acoustic Application: Surveillance, Environmental Monitoring, Precision Agriculture, Disaster Management, Infrastructure Inspection End User: Defense Agencies, Security Firms, Agricultural Enterprises, Emergency Responders, Energy Operators Deployment: Fixed-Wing Drones, Rotary-Wing Drones, Hybrid UAVs, Tethered Drones |
| Companies Covered | General Atomics, Northrop Grumman, Lockheed Martin, Raytheon Technologies, BAE Systems, Honeywell, Thales Group, Airbus, uAvionix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Sense-And-Avoid Systems Market Trends and Innovations
Computational hardware miniaturization and edge-AI inference capabilities are enabling onboard processing that previously required ground station relay, collapsing system latency thresholds.
Solid-state beam-steering arrays are electrifying radar front-end design by eliminating mechanical gimbal assemblies. Urban air mobility developers at Joby Aviation and Archer Aviation are integrating these flat-panel architectures into compact air taxi nacelles. The shift is compressing sensor payload volume by sixty percent while enabling microsecond-scale beam repositioning for high-closure-rate encounters.
EASA's SORA methodology for specific-category operations is mandating quantitative risk ratios that force manufacturers to document sensor performance in degraded visual environments. Commercial drone operators in Germany and France must now submit technical standard orders proving sub-second detection-to-maneuver latency. The compliance burden favors vendors with existing military qualification heritage who can repurpose test data.
Acquisition patterns among agricultural enterprises are rotating toward bundled service contracts where sense-and-avoid capability is embedded in per-acre spraying fees rather than capital equipment purchases. Equipment lessors in Australia's wheat belt are capturing margin through usage-based pricing that internalizes collision risk. The model displaces upfront hardware sales with recurring revenue streams tied to seasonal flight hours.
UAV Sense-And-Avoid Systems Market Segmentation
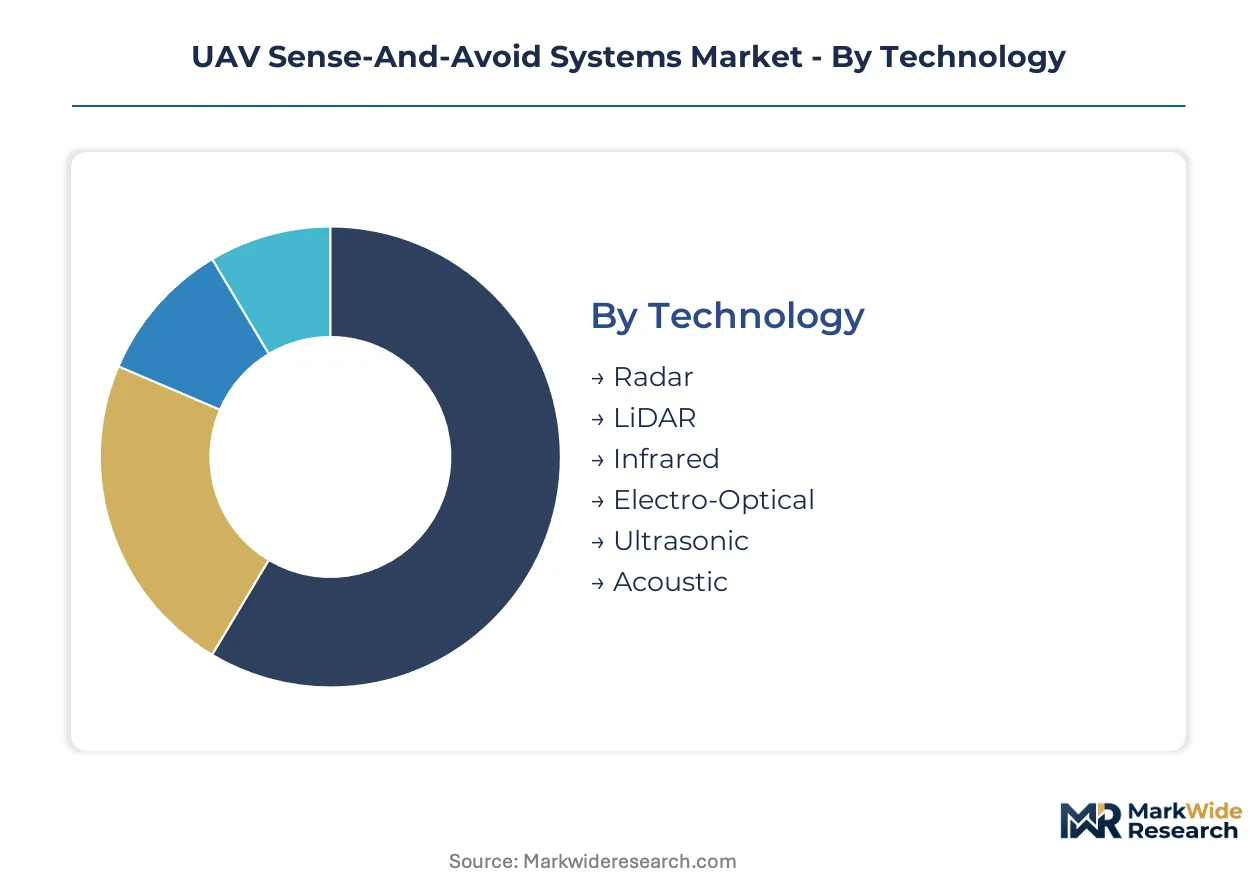
UAV sense-and-avoid architectures vary dramatically across operational contexts. Technology choices determine detection range and weather resilience. Application requirements dictate sensor fusion complexity and certification pathways.
Technology:
Defense contractors prioritize detection reliability under electromagnetic interference. Commercial operators weigh unit economics against regulatory minimums.
- Radar:Solid-state architectures with software-defined waveforms penetrate fog, rain, and dust. Military procurement in the United States and Germany favors active electronically scanned arrays for beyond-visual-line-of-sight missions. FAA certification timelines compress for vendors with existing radar heritage.
- Electro-Optical:Camera-based systems leverage mature CMOS supply chains and machine-learning inference at the edge. Agricultural spraying fleets in Brazil and Australia adopt these for daytime obstacle recognition where cost sensitivity dominates.
- LiDAR:Solid-state beam steering enables three-dimensional point cloud generation for urban air mobility corridors.
- Infrared:Thermal detection supplements electro-optical in low-light and smoke-obscured environments.
- Ultrasonic:Short-range proximity sensing protects during takeoff, landing, and indoor navigation.
- Acoustic:Microphone arrays detect non-cooperative aircraft through engine signature recognition.
Volume sits with electro-optical; growth tilts toward LiDAR.
Application:
Mission profiles determine sensor payload weight, power draw, and real-time processing requirements.
- Surveillance:Persistent wide-area coverage demands multi-spectral detection with target classification algorithms. Border security contracts in Israel and Australia specify all-weather performance across extended operational envelopes.
- Precision Agriculture:Low-altitude crop monitoring accepts lighter electro-optical configurations with reduced detection ranges. Brazilian soybean operators and Australian wheat belt lessors drive adoption through bundled service contracts.
- Infrastructure Inspection:GPS-denied navigation near transmission towers and pipelines requires inertial augmentation.
- Environmental Monitoring:Long-endurance flights over marine reserves and forests prioritize power efficiency.
- Disaster Management:Rapid deployment scenarios favor modular payloads that swap sensors based on incident type.
Defense surveillance commands premium pricing; precision agriculture scales fastest.
End User:
Procurement authority and operational risk tolerance shape buying behavior across buyer categories.
- Defense Agencies:NATO standardization initiatives mandate interoperable multi-sensor suites. Classified signal-processing requirements favor prime contractors with existing security clearances and test range access.
- Agricultural Enterprises:Fleet operators in Brazil and Australia rotate toward usage-based contracts that internalize collision risk. Equipment lessors capture margin through per-acre spraying fees rather than hardware sales.
- Energy Operators:Pipeline and transmission operators require GPS-denied navigation in remote terrain.
- Security Firms:Private operators face lighter certification burdens than defense counterparts.
- Emergency Responders:Fire departments and search-and-rescue units prioritize rapid deployment over sensor sophistication.
Defense agencies anchor revenue; agricultural enterprises expand addressable volume.
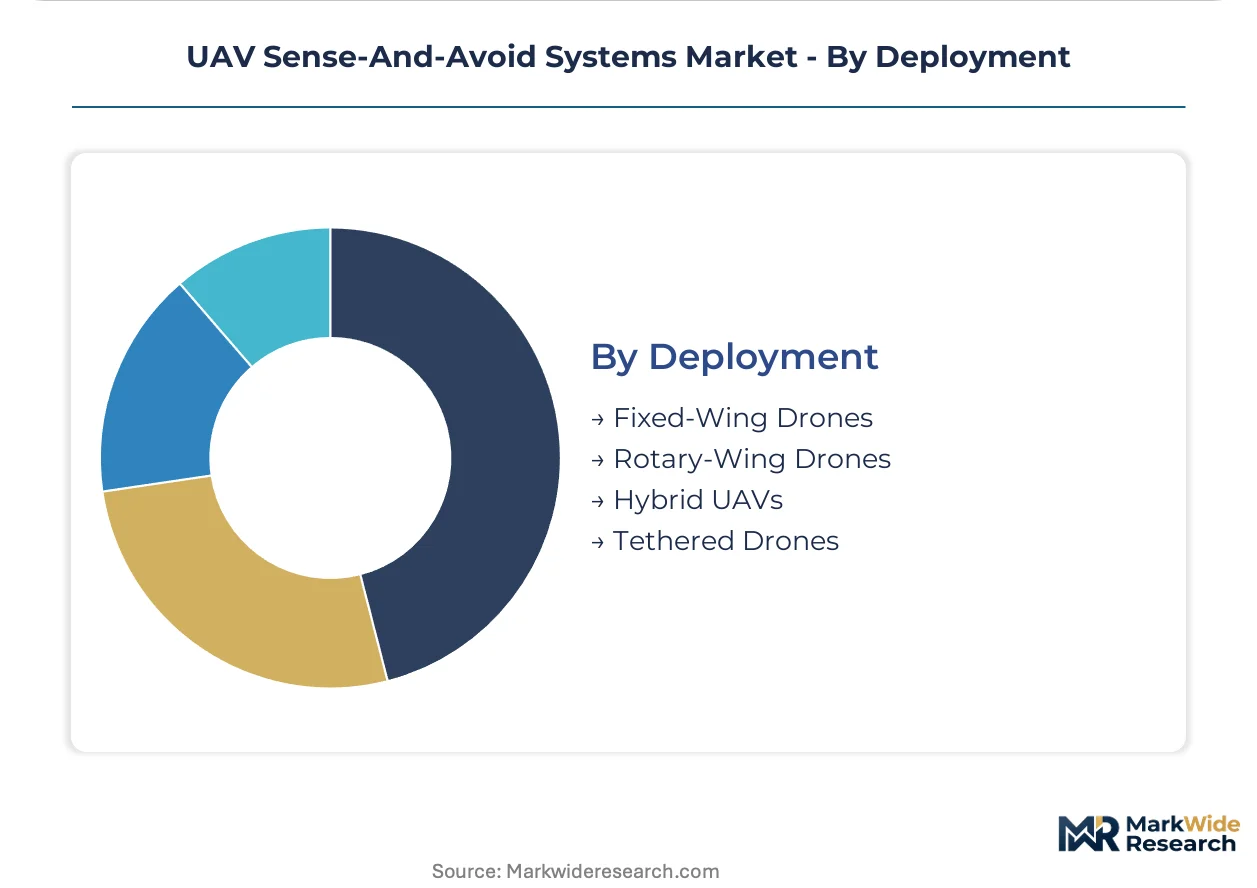
Deployment:
Airframe dynamics determine sensor mounting constraints and field of view requirements.
- Rotary-Wing Drones:Multi-rotor platforms dominate commercial inspection and agricultural spraying. Vibration isolation and 360-degree coverage requirements favor compact fused sensor heads.
- Fixed-Wing Drones:Long-endurance surveillance missions accommodate larger radar apertures and higher power budgets. Forward-looking configurations suffice for most collision scenarios.
- Hybrid UAVs:Vertical-takeoff-and-landing transitions complicate sensor placement for both hover and cruise phases.
- Tethered Drones:Persistent aerial platforms for border monitoring and event security rely on ground-station processing.
Rotary-wing configurations dominate unit shipments; hybrid architectures climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of GaN RF components and solid-state radar arrays concentrates in East Asian foundries, while defense procurement and commercial certification demand centers on NATO member states and Australia. Consumption patterns diverge sharply between military hardening requirements and civilian regulatory minimums.
United States
FAA Part 89 mandates drive fleet-wide sensor upgrades for commercial BVLOS authorization, while Pentagon procurement anchors prime contractor revenue. Lockheed Martin leverages classified signal-processing heritage from Palmdale, California facilities to secure high-assurance military contracts. Urban air mobility corridors in Dallas-Fort Worth and Los Angeles accelerate LiDAR fusion deployments for three-dimensional obstacle mapping.
Germany
EASA SORA methodology imposes quantitative risk ratios forcing manufacturers to document sub-second detection-to-maneuver latency in degraded visual environments. Thales Group sustains civilian certification momentum alongside defense programs through dual-use positioning. Industrial clusters in Bavaria and Baden-Württemberg host test ranges for NATO interoperable multi-sensor suite validation.
Australia
Agricultural enterprises in the wheat belt rotate toward bundled service contracts embedding sense-and-avoid capability in per-acre spraying fees. Equipment lessors capture margin through usage-based pricing tied to seasonal flight hours. TGA-equivalent civil aviation standards for remote operations create compliance pathways that favor vendors with existing military qualification heritage.
Israel
Border security contracts specify all-weather multi-spectral detection with target classification algorithms across extended operational envelopes. Defense agencies mandate interoperable autonomous detection suites for unmanned fleet operations. Industrial concentration around Haifa and Tel Aviv supports rapid prototyping of solid-state beam-steering arrays for surveillance missions.
Brazil
Soybean operators in Mato Grosso and Paraná drive adoption of electro-optical configurations for daytime obstacle recognition where cost sensitivity dominates. ANVISA-equivalent agricultural aviation regulations shape equipment certification timelines. Low-altitude crop-dusting operations present unmet collision-avoidance needs that attract compact transponder-integrated solution vendors.
UAV Sense-And-Avoid Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across sensor fusion architectures, with prime contractors maintaining captive test range access while specialist vendors rely on outsourced fabrication. The vendor base stratifies across three tiers: classified program integrators with security clearance infrastructure, dual-use positioning specialists bridging military and civilian certification, and compact commercial solution providers occupying distinct price bands below prime integrators. Dominant competitive moves include strategic partnerships for GaN foundry access and portfolio diversification into subscription-based software-defined radar updates.
Within the classified program integrator tier, Lockheed Martin and Northrop Grumman exemplify archetypes leveraging defense heritage for high-assurance contract capture. Thales Group occupies a position bridging military and civilian certification pathways through dual-use positioning. uAvionix Corporation represents the compact commercial specialist archetype, anchoring a distinct tier below prime integrators with transponder-integrated solutions for cost-sensitive operators.
| Leading Market Players |
|---|
| General Atomics |
| Northrop Grumman |
| Lockheed Martin |
| Raytheon Technologies |
| BAE Systems |
| Honeywell |
| Thales Group |
| Airbus |
| uAvionix Corporation |
| Others |
Pricing and Supply Chain Analysis
FAA Part 89 mandates for beyond-visual-line-of-sight authorization are compelling fleet operators to absorb sensor upgrade costs, forcing suppliers to balance certification investment against volume scaling while defense procurement sustains premium tier viability.
Pricing Analysis
Margin tightening in commercial tiers reflects agricultural enterprise migration toward bundled service contracts that displace upfront hardware sales. Three-tier pricing structure across prime integrator, dual-use specialist, and compact commercial levels separates defense-grade multi-sensor suites from civilian-certified configurations and cost-sensitive electro-optical units. Pricing pressure intensifies in the compact tier as Brazilian and Australian agricultural lessors internalize collision risk through per-acre fees. Defense agencies exhibit least price sensitivity due to classified signal-processing requirements and security clearance infrastructure.
Supply Chain Analysis
Dual-sourcing requirements for GaN RF components are compelling prime contractors to qualify alternative foundry partnerships beyond East Asian manufacturing clusters. Gallium nitride substrate fabrication draws from Taiwan, South Korea, and Japan, while solid-state radar array assembly rests on specialized capacity in Germany and the United States. Single-source vulnerability concentrates in epitaxial wafer growth for military-grade RF performance. Distribution runs through defense procurement channels, direct OEM integration contracts, and agricultural equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN foundry capacity constraints are propping pricing power for qualified suppliers, creating durable margin pools for incumbents with secured wafer allocations.
For Market Incumbents: To counter subscription licensing erosion from software-defined radar updates, anchor high-assurance military contracts through classified signal-processing heritage while expanding civilian certification momentum alongside defense programs. Pursue backward integration into GaN epitaxial growth to secure wafer supply. For New Entrants and Emerging Players: Australian agricultural equipment lessors represent an underserved buyer archetype seeking compact transponder-integrated solutions below prime integrator pricing. Target Brazilian soybean operators with daytime electro-optical configurations. Pursue usage-based pricing partnerships with seasonal spraying fleets. For Investors and Strategic Acquirers: The window for entry favors dual-use positioning specialists bridging military qualification heritage and civilian certification pathways. Long-term viability hinges on algorithmic architecture pre-certification under EASA SORA and EU AI Act risk classifications. Watch EASA quantitative risk ratio enforcement as inflection indicator for compliance-ready vendors.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures epitaxial wafer supply for AESA radar production against East Asian concentration risk. |
| EASA SORA Pre-Certification | Accelerates European commercial authorization through documented sub-second latency performance. |
| Agricultural Service Contract Bundling | Captures recurring revenue from Australian wheat belt lessors through per-acre collision risk internalization. |
| Software-Defined Radar Subscription | Restructures prime contractor revenue streams from unit sales toward recurring waveform update licensing. |
| Urban Air Mobility LiDAR Integration | Addresses three-dimensional obstacle mapping requirements for Dallas-Fort Worth corridor deployments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with defense procurement officers, commercial UAV fleet operators, GaN foundry technical directors, agricultural equipment lessors, and FAA certification specialists provided operational validation. FAA Part 89 implementation guidance, EASA SORA technical standard orders, NATO standardization initiative documents, and Pentagon budget justification materials supplied regulatory and demand-side benchmarks. Bottom-up sensor shipment tracking and top-down defense expenditure analysis enabled triangulation.
Data-stream reconciliation across technology deployment volumes, procurement contract values, and certification timeline databases structured the analytical framework. Segmentation dimensions modeled include sensor modality, application mission profile, end-user procurement authority, and airframe deployment configuration. CAGRs derived from fitted growth curves applied to defense budget trajectories and commercial fleet replacement cycles. Urban air mobility corridor announcements and agricultural spraying hour data informed application-specific trajectory assumptions.
Revisions become necessary when EASA SORA enforcement intensity, GaN foundry capacity expansion, or FAA beyond-visual-line-of-sight authorization timelines deviate from baseline assumptions. Deviation in defense procurement prioritization for autonomous detection suites would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Small UAV Market
UAV
Solar-Powered UAV Market
UAV
Rc Helicopter Market
UAV
UAV Lidar Market
UAV
Drone Powered Business Solutions Market
UAV
Drone Telematics Market
UAV
Europe Small UAV Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
GCC Drone Pilot Training Market
UAV
Enterprise Drone Management Solutions Market
UAV
Electric Glider Market
UAV
UAV Navigation Systems Market
UAV
Drone Leasing Market
UAV
Tethered Drones Market
UAV
Consumer Drone Market
UAV
Global Aerial Imaging Market