
 North America Drone Software Market | 2026-2036
North America Drone Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drone Software Market Analytics
The North America drone software market is consolidating around a sharp split between premium analytics suites and commodity flight control layers. DroneDeploy leverages its cloud-native architecture to dominate commercial mapping workflows across construction and agriculture verticals. Skydio sustains competitive positioning through autonomous navigation algorithms purpose-built for defense and public safety applications. PrecisionHawk anchors its presence in enterprise agronomy with specialized data management tools for crop insurance and seed-trial validation.
North America drone software encompasses the code platforms, middleware, and analytics engines that govern unmanned aerial vehicle operations, sensor fusion, and geospatial data processing, typically requiring real-time kinematic positioning accuracy below two centimeters for survey-grade outputs. These systems enable automated mission planning, orthomosaic generation, and predictive maintenance across industrial asset inspections. Flight control and imaging solutions currently command the deepest margin pools as hardware-software integration tightens, while fleet management deployments are accelerating fastest among multi-drone logistics operators seeking centralized compliance dashboards. Cloud deployment architectures lead in adoption frequency, though hybrid configurations are gaining favor among defense contractors with classified data requirements.
The FAA governs commercial airspace access through Part 107 certification and experimental waivers for beyond-visual-line-of-sight missions, directly conditioning software feature roadmaps for flight planning and detect-and-avoid systems. Transport Canada imposes parallel operator certificate requirements that force vendors to maintain dual compliance modules for cross-border deployments. Stakeholders must monitor pending FAA Remote ID enforcement deadlines and corresponding software authentication upgrades to preserve market access across both jurisdictions.
Market Dynamics
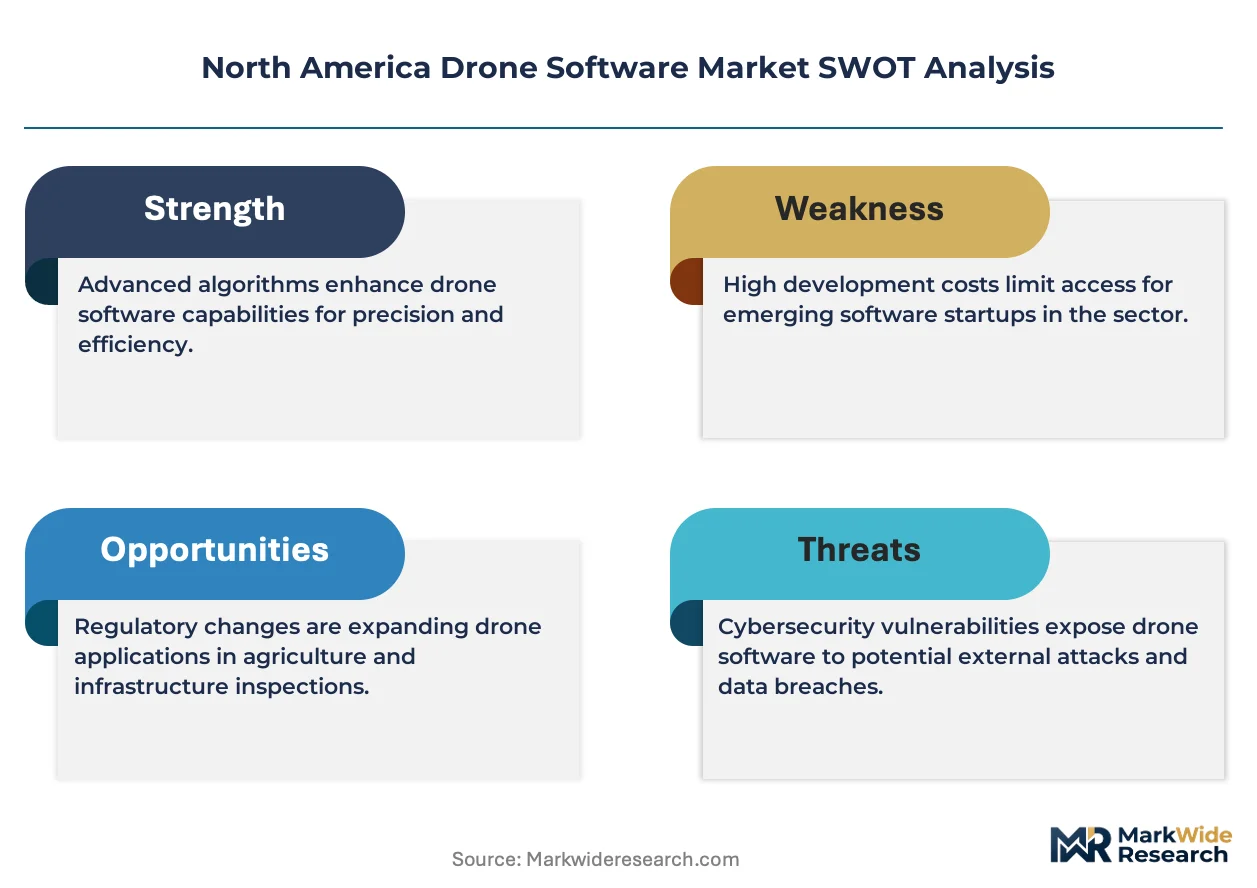
Drone software vendors face intensifying pressure from FAA Part 107 waiver complexity and the operational gap between visual-line-of-sight compliance and true beyond-visual-line-of-sight autonomy. The regulatory bottleneck is compressing feature roadmaps and forcing architectural bets on detect-and-avoid middleware.
Growth Catalysts
- Precision Agriculture Expansion:Variable-rate application platforms across the Great Plains and California Central Valley are pulling demand for sub-centimeter RTK positioning and automated mission planning tools.
- FAA Remote ID Mandates:Enforcement deadlines are accelerating authentication software upgrades across commercial fleets, creating captive demand for compliance modules.
- Energy Corridor Inspections:Alberta and British Columbia pipeline operators are deploying multi-drone logistics platforms with centralized fleet management dashboards.
Market Restraints
- Silicon Supply Concentration:Flight control chipsets depend on concentrated Asian foundry capacity, exposing North American vendors to input volatility and allocation risk.
- BVLOS Regulatory Friction:Experimental waiver timelines from FAA Flight Standards District Offices create deployment delays that compress software monetization windows.
- GNSS Jamming Vulnerability:Survey-grade outputs require signal integrity that remains technically exposed to spoofing and interference in contested electromagnetic environments.
Strategic Opportunities
- Canadian Cross-Border Deployments:Transport Canada operator certificate requirements create dual-compliance software modules that vendors can productize for transnational energy and agriculture clients.
- Defense Hybrid Cloud Architectures:Classified data requirements at U.S. defense contractors are pulling demand for on-premise analytics nodes with selective cloud burst capability.
- Seed-Trial Validation Workflows:Crop insurance actuaries are adopting predictive yield models that fuse drone imagery with soil sensor networks, opening enterprise agronomy contracts.
Industry Challenges
- Remote Pilot Certification Bottlenecks:FAA Part 107 testing capacity constraints are limiting qualified operator supply and throttling fleet scaling for commercial service providers.
- Sensor Fusion Integration Complexity:LiDAR, multispectral, and thermal payload interoperability demands specialized calibration protocols that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drone Software Market |
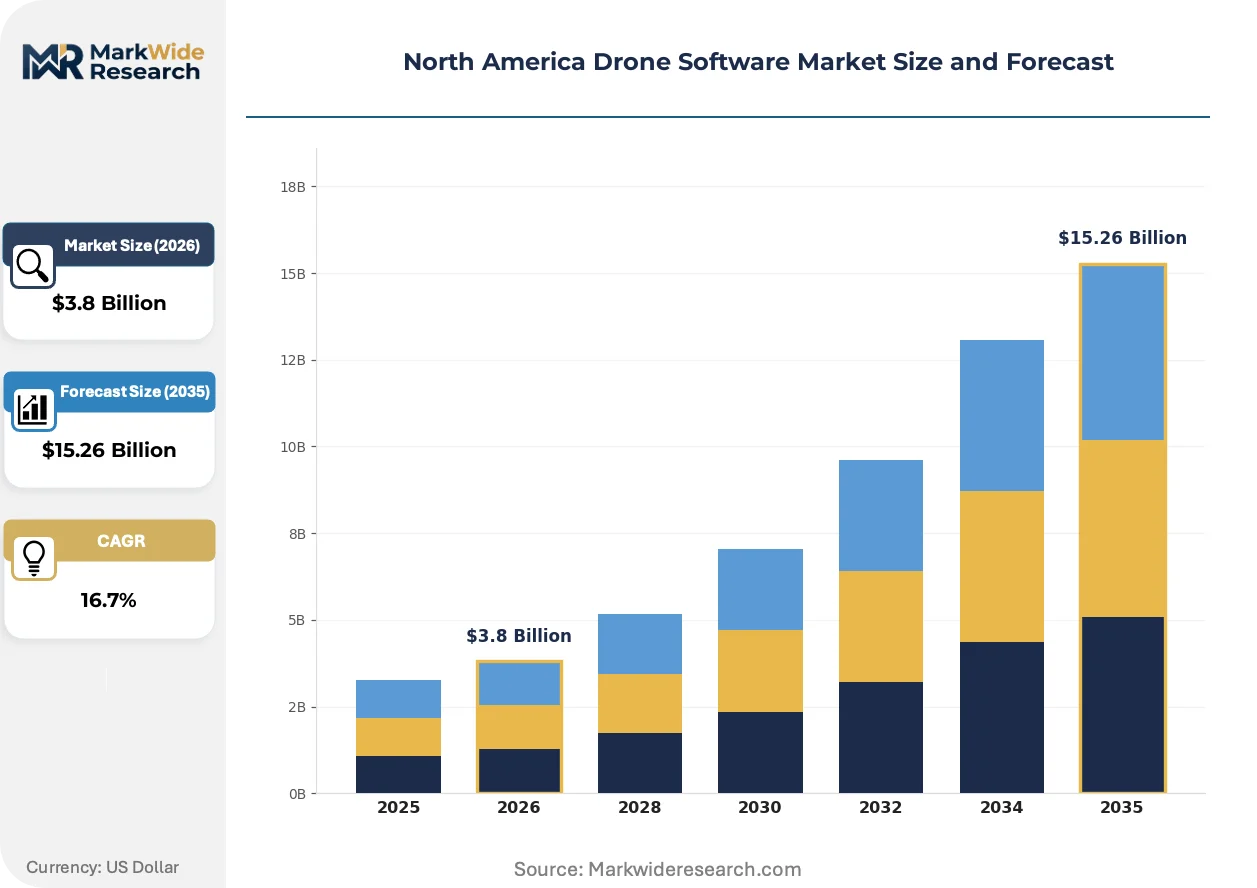
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control, Data Management, Imaging, Fleet Management Deployment: Cloud, On-Premises, Hybrid, Edge End User: Agriculture, Construction, Defense, Logistics Solution: Analytics, Safety, Navigation, Communication |
| Companies Covered | DroneDeploy, Inc., Skydio, Inc., PrecisionHawk, Inc., Pix4D SA, Kespry, Inc., Esri, Inc., AirMap Inc., Skycatch, Inc., Sentera, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drone Software Market Evolving Landscape
Artificial intelligence inference at the edge is compressing latency requirements for real-time decision-making in contested airspace. Software architectures are pivoting from post-flight analytics to onboard processing pipelines.
Computer vision algorithms are integrating directly into flight control loops, enabling dynamic obstacle avoidance without ground-station dependency. Defense and public safety operators in the southwestern United States are deploying these capabilities for urban canyon navigation. The technology is integrating sensor fusion and predictive path planning into unified navigation stacks that reduce operator cognitive load.
FAA Remote ID rulemaking is mandating broadcast-based identification for most commercial drones above 250 grams, forcing firmware updates across installed bases. Transport Canada is harmonizing parallel requirements, creating cross-border compliance complexity. Agricultural and construction fleet operators in the U.S. Midwest are absorbing these costs through bundled software maintenance contracts.
Subscription pricing for cloud-native analytics is displacing perpetual license models among mid-market construction firms. Enterprise buyers now expect usage-based billing tied to acreage mapped or assets inspected. This shift is most visible in California Central Valley agronomy services, where growers resist capital outlays for seasonal deployment tools.
North America Drone Software Market Segmentation
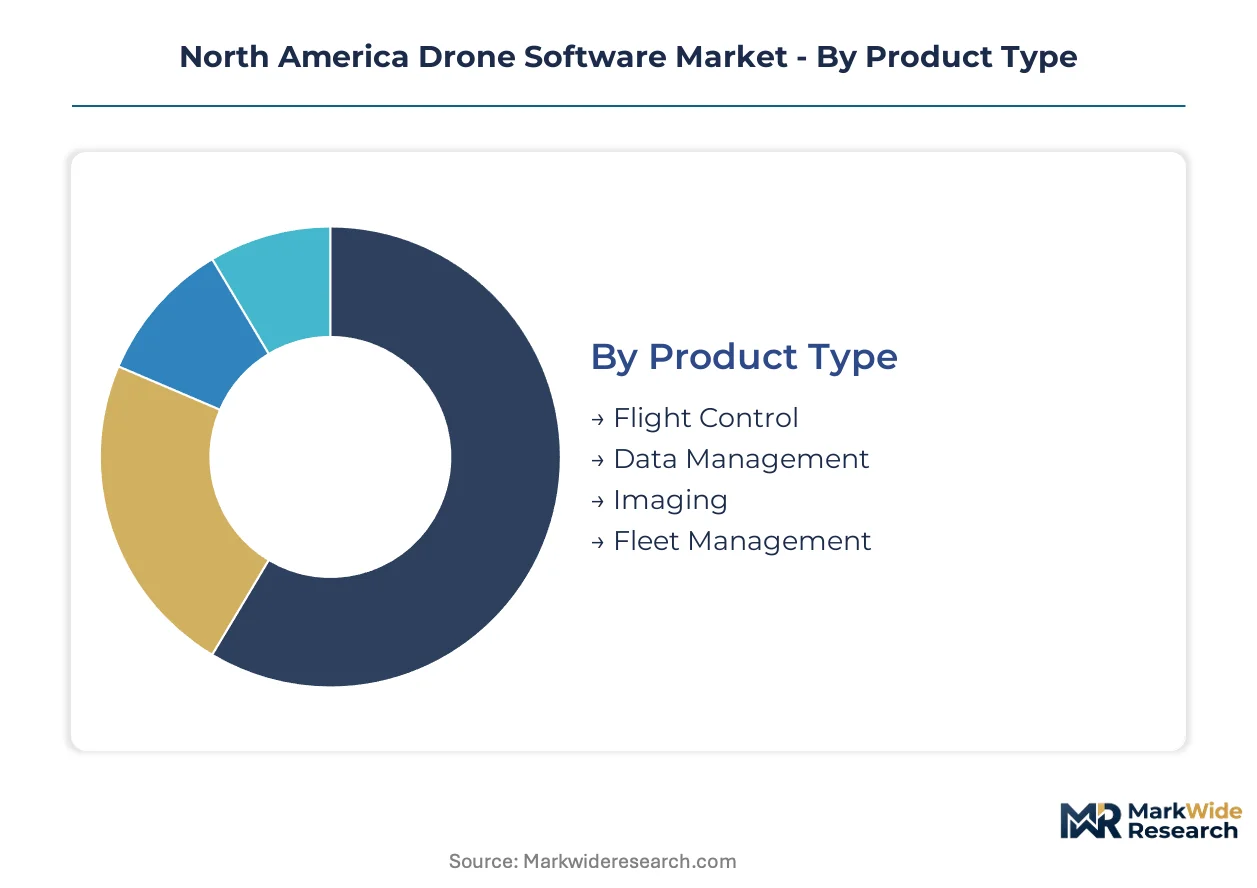
Drone software architectures fragment sharply between embedded flight control stacks and standalone analytics platforms. Vendors configure pricing and integration depth around whether code executes onboard silicon or remote servers. Understanding these splits clarifies where margin pools concentrate and where standardization pressures mount.
Product Type:
Integration depth varies dramatically across this dimension, with some segments functioning as embedded firmware and others as decoupled SaaS layers.
- Flight Control:Real-time kinematic positioning algorithms and autopilot logic execute directly on ARM-based flight controllers with sub-50-millisecond loop times. FAA Part 107 waiver complexity is pulling demand for detect-and-avoid middleware in this segment across Texas and California test corridors. Flight control leads volumes today; fleet management is gaining share fastest.
- Data Management:Orthomosaic generation pipelines and geospatial asset libraries require GPU-accelerated processing for point cloud densification. Crop insurance validators in the Great Plains are adopting these tools for seed-trial documentation and yield prediction workflows.
- Imaging:Multispectral index computation and radiometric correction modules process raw sensor feeds into agronomy-ready outputs.
- Fleet Management:Centralized compliance dashboards aggregate Remote ID broadcasts and maintenance logs for multi-vehicle logistics operators.
Flight control leads volumes today; fleet management is gaining share fastest.
Deployment:
Cost tier stratification separates premium hybrid configurations from commodity cloud subscriptions, with defense buyers absorbing on-premise premiums for air-gapped security.
- Cloud:Serverless architectures host mission planning and photogrammetry pipelines with elastic compute scaling. Construction firms in the U.S. Midwest favor subscription billing tied to acreage mapped rather than capital deployment.
- On-Premises:Air-gapped installations serve defense contractors with classified data handling requirements and export-controlled source code. Alberta energy corridor operators maintain these configurations for pipeline integrity data sovereignty.
- Hybrid:Selective cloud burst capability routes sensitive preprocessing to local nodes while pushing non-critical analytics to remote servers.
- Edge:Onboard inference engines compress latency for real-time obstacle avoidance without ground-station dependency.
Cloud deployments dominate subscription revenue today; edge architectures are climbing the fastest among public safety operators.
End User:
Application maturity varies sharply, with agriculture and construction representing proven revenue bases while defense and logistics build specialized procurement channels.
- Agriculture:Variable-rate application platforms demand sub-centimeter RTK accuracy and automated mission planning for California Central Valley growers. Soil sensor network integration is opening enterprise contracts with crop insurance actuaries.
- Construction:Progress monitoring and volumetric survey workflows dominate commercial mapping deployments. DroneDeploy's cloud-native architecture anchors this vertical across U.S. commercial real estate development.
- Defense:Autonomous navigation algorithms for contested airspace require hardened flight stacks with spoofing-resistant GNSS.
- Logistics:Multi-drone coordination platforms manage beyond-visual-line-of-sight parcel delivery trials.
Agriculture anchors current installed base; defense procurement is expanding most quickly through federal autonomy research programs.
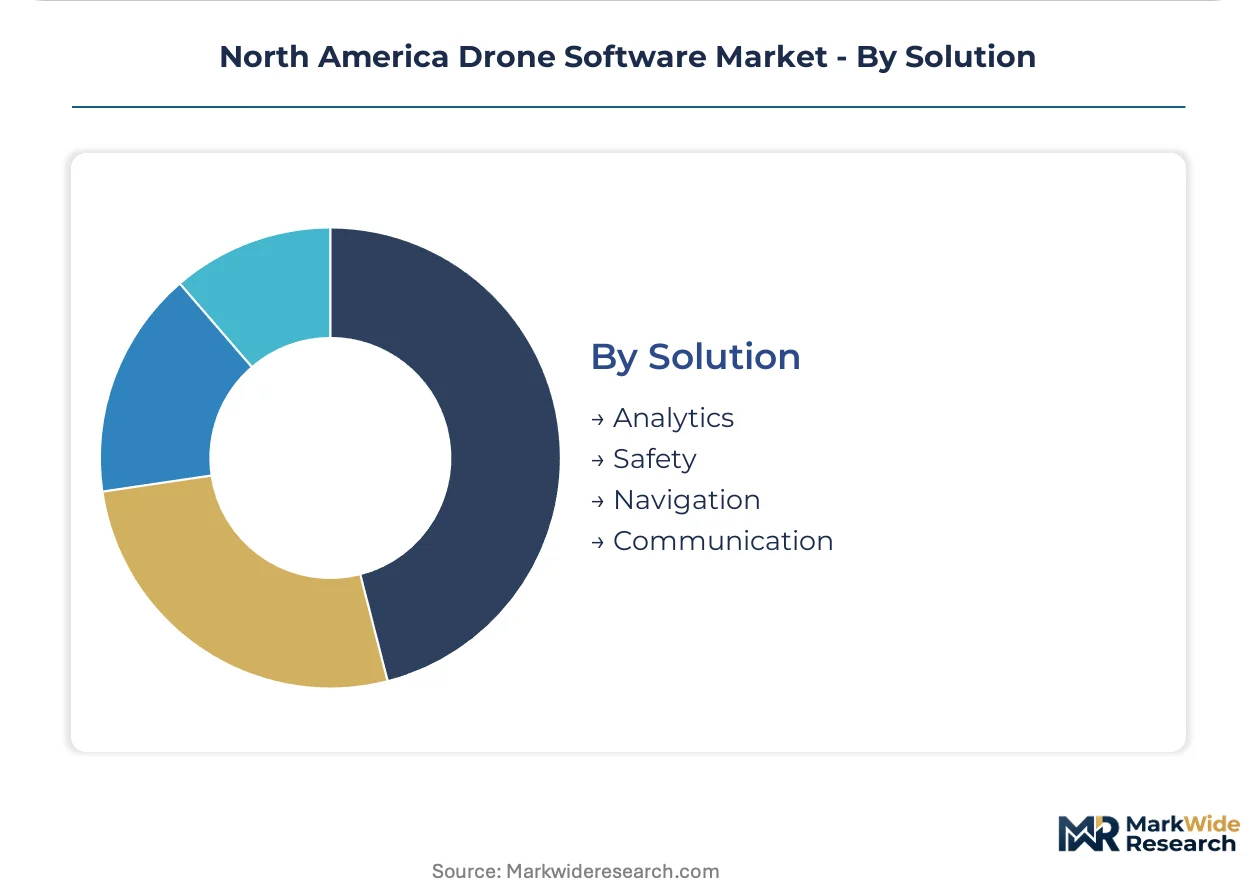
Solution:
Margin concentration flows toward safety and navigation modules where certification requirements create vendor lock-in, while analytics faces commoditization pressure.
- Analytics:Predictive maintenance models and yield forecasting engines fuse drone imagery with ground-truth sensor networks. Commodity pricing pressure is accelerating as open-source photogrammetry tools mature.
- Safety:Detect-and-avoid middleware and geofencing enforcement satisfy FAA Remote ID mandates and Transport Canada parallel requirements. Regulatory deadlines are creating captive upgrade cycles across commercial fleets.
- Navigation:Sensor fusion stacks integrate LiDAR, visual odometry, and inertial measurement units for GPS-denied environments.
- Communication:Mesh networking protocols and C-band datalinks enable multi-vehicle coordination without centralized infrastructure.
Safety modules command premium pricing today; navigation solutions are gaining share fastest through defense urban canyon contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified remote pilot density concentrates in the United States, with Canadian energy corridor deployments expanding across Alberta and British Columbia. FAA Part 107 waiver processing and Transport Canada operator certificate requirements create dual-compliance complexity for cross-border vendors.
United States
Precision agriculture adoption accelerates across California Central Valley and Great Plains growing regions. FAA Part 107 certification requirements and beyond-visual-line-of-sight waiver frameworks condition software feature roadmaps for flight planning systems. Texas and Arizona test corridors host detect-and-avoid middleware validation programs for autonomous navigation.
Canada
Pipeline integrity inspections drive demand across Alberta oil sands and British Columbia coastal energy infrastructure. Transport Canada imposes parallel operator certificate requirements that force vendors to maintain dual compliance modules. Calgary and Vancouver anchor energy sector procurement channels for multi-drone logistics platforms.
Mexico
Agricultural monitoring deployments expand across Sinaloa and Baja California growing belts for export crop quality assurance. Mexican civil aviation regulations align with FAA Remote ID harmonization timelines for cross-border fleet operations. Guadalajara technology clusters incubate localized mission planning software for Latin American market adaptation.
North America Drone Software Market Competitive Landscape
Top-tier vendors anchor cloud-native analytics suites, while mid-tier specialists compete on vertical-specific workflow integration. The vendor base splits between autonomous navigation architects and geospatial data platform operators. Three archetypes dominate: defense-hardened flight stack providers, subscription-based mapping SaaS vendors, and enterprise agronomy data managers. Competitive moves concentrate on strategic partnerships with sensor hardware manufacturers and geographic expansion into Canadian energy corridors.
Within the cloud-native mapping tier, DroneDeploy, Inc. exemplifies vertical integration into construction workflow ecosystems. Skydio, Inc. occupies a position among defense-focused autonomy specialists with hardened navigation stacks. PrecisionHawk, Inc. represents the enterprise agronomy archetype through crop insurance validation tooling. These three anchors demonstrate how vendor positioning fragments across mission-critical safety modules, commodity analytics layers, and specialized compliance dashboards.
| Leading Market Players |
|---|
| DroneDeploy, Inc. |
| Skydio, Inc. |
| PrecisionHawk, Inc. |
| Pix4D SA |
| Kespry, Inc. |
| Esri, Inc. |
| AirMap Inc. |
| Skycatch, Inc. |
| Sentera, Inc. |
| Others |
Value Network & Pricing Analysis
FAA Remote ID mandate deadlines are compressing procurement timelines for commercial fleet operators, forcing software vendors to absorb firmware authentication costs into bundled maintenance contracts rather than pass-through pricing. This cost absorption dynamic concentrates margin pressure on mid-tier analytics providers while flight control specialists with detect-and-avoid certification capture premium positioning.
Pricing Analysis
Bundled compliance-authentication services versus unbundled per-module licensing splits the North America drone software market into two distinct procurement camps. Three-tier pricing structure across premium certified, standard subscription, and economy flight-control tiers dominates, with FAA Part 107 waiver complexity and Transport Canada dual-compliance requirements driving differentiation. Cost compression in standard-tier analytics is intensifying because open-source photogrammetry tools mature, while public safety agencies show least price sensitivity for hardened navigation stacks with spoofing-resistant GNSS.
Supply Chain Analysis
Trans-Pacific freight volatility and port congestion at Long Beach and Vancouver are elevating landed costs for ARM-based flight controllers and GPU accelerators sourced from Taiwan, South Korea, and China. Silicon foundry capacity concentration in East Asia exposes North American vendors to allocation risk for RTK positioning chipsets and thermal imaging sensors. Single-source vulnerability in advanced node semiconductor fabrication threatens detect-and-avoid middleware production timelines. Distribution runs through direct OEM partnerships with Texas and California test corridor operators, supplemented by channel relationships with agronomy service cooperatives across the Great Plains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North America drone software rests on successful cost-down migration of edge inference workloads to commodity silicon, alongside premium-tier capture of defense-hardened navigation contracts with classified data handling requirements.
For Market Incumbents: Hedge against open-source analytics commoditization by deepening captive supply of RTK correction services and detect-and-avoid certification pipelines. Acquire specialized sensor fusion engineering teams in Arizona and Texas test corridors to defend positioning against autonomous navigation entrants. FAA waiver processing delays threaten fleet management revenue recognition timelines; vertical integration into pilot training networks mitigates operator certification bottlenecks. For New Entrants and Emerging Players: Launch via usage-based billing partnerships with California Central Valley agronomy cooperatives seeking seasonal deployment flexibility without capital outlay. Canadian energy corridor operators in Alberta and British Columbia represent the most penetrable geography, with Transport Canada compliance gaps creating white-space for dual-certification software modules. Target seed-trial validation workflows for crop insurance actuaries as the fastest-adopting application with minimal incumbent lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid cloud architecture specialists serving defense contractors with air-gapped analytics nodes and selective cloud burst capability. Long-term viability over the next decade favors vendors with FAA certification moats and cross-border regulatory navigation expertise. Watch BVLOS waiver approval velocity at FAA Flight Standards District Offices as the critical inflection signal for autonomous navigation software monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | DroneDeploy's cloud-native architecture anchors construction workflow ecosystems across U.S. commercial real estate development. |
| Acquisition of Specialist Firm | Sensor fusion calibration protocols for LiDAR-multispectral interoperability compress deployment timelines for enterprise agronomy contracts. |
| Geographic Expansion | Canadian energy corridor penetration requires Transport Canada operator certificate modules that vendors can productize for transnational clients. |
| Strategic Partnership | Soil sensor network alliances with crop insurance actuaries open predictive yield modeling contracts in the Great Plains. |
| Product Launch | Edge inference engines for real-time obstacle avoidance address public safety demand for urban canyon navigation without ground-station dependency. |
Research Methodology
Direct dialogue with flight operations directors at precision agriculture cooperatives, FAA Part 107 certification instructors, defense procurement officers, and energy corridor logistics managers grounded qualitative assessments. Secondary validation drew from FAA waiver processing databases, Transport Canada operator certificate filings, SEC disclosures by publicly traded drone hardware OEMs, and hyperscaler edge computing capex reports. Bottom-up segment sizing triangulated against top-down addressable market estimates from customs records of UAV component imports.
Segment-level outputs across flight control, data management, imaging, and fleet management product types were modeled over the projection horizon, with deployment mode, end-user vertical, and solution architecture as cross-cutting dimensions. CAGRs were derived from regression analysis against historical adoption curves in adjacent automation software markets, incorporating FAA regulatory timeline assumptions and silicon supply elasticity parameters.
Several conditions sit outside the modeled scope, including unilateral export control expansion affecting GPU accelerators, electromagnetic warfare escalation degrading GNSS signal integrity, and catastrophic waiver processing backlogs at FAA district offices. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Target Drone Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
GCC Drones Market
UAV
Global Inspection Drones Market
UAV
Drone Inspection Service Market
UAV
Europe Tethered Drone Market
UAV
Fuel Cell UAV Market
UAV
Drone Powered Business Solutions Market
UAV
Global Drone Data Services Market
UAV
UAV Battery Market
UAV
Combat Drone Market
UAV
Stratospheric Flying Drone Market
UAV
Europe Drone Light Shows Market
UAV
Middle-East and Africa Drones Market
UAV
Global VTOL UAV Market
UAV
North America Fuel Cell UAV Market