
 Fixed Wing Military Drones Market | 2026-2036
Fixed Wing Military Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Wing Military Drones Market Analysis
Defense procurement channels across NATO members and allied Pacific nations is reshaping vendor qualification requirements and contract award patterns. General Atomics leverages its integrated ground control and sensor payload architecture to sustain multi-year sole-source positions on endurance-class programs. AeroVironment competes through tactical portability, dominating hand-launched platforms for expeditionary units requiring rapid deployment. Kratos Defense & Security Solutions anchors the attritable segment with jet-powered targets and loyal wingman concepts priced below manned alternatives.
Fixed wing military drones are unmanned aerial vehicles characterized by rigid airfoil structures, typically exhibiting wingspans from three to thirty meters, propulsion via turbofan, turboprop, or piston engines, and endurance profiles exceeding twenty-four hours for surveillance variants. These systems execute intelligence collection, precision strike, electronic warfare, and communications relay missions without exposing human operators to hostile environments. Reconnaissance drones occupy the largest value pool given multi-decade sensor upgrade cycles on legacy airframes, while combat drones represent the fastest-expanding category as air forces validate autonomous targeting protocols. Surveillance capabilities within the technology dimension command premium pricing when fused with signals intelligence and synthetic aperture radar subsystems.
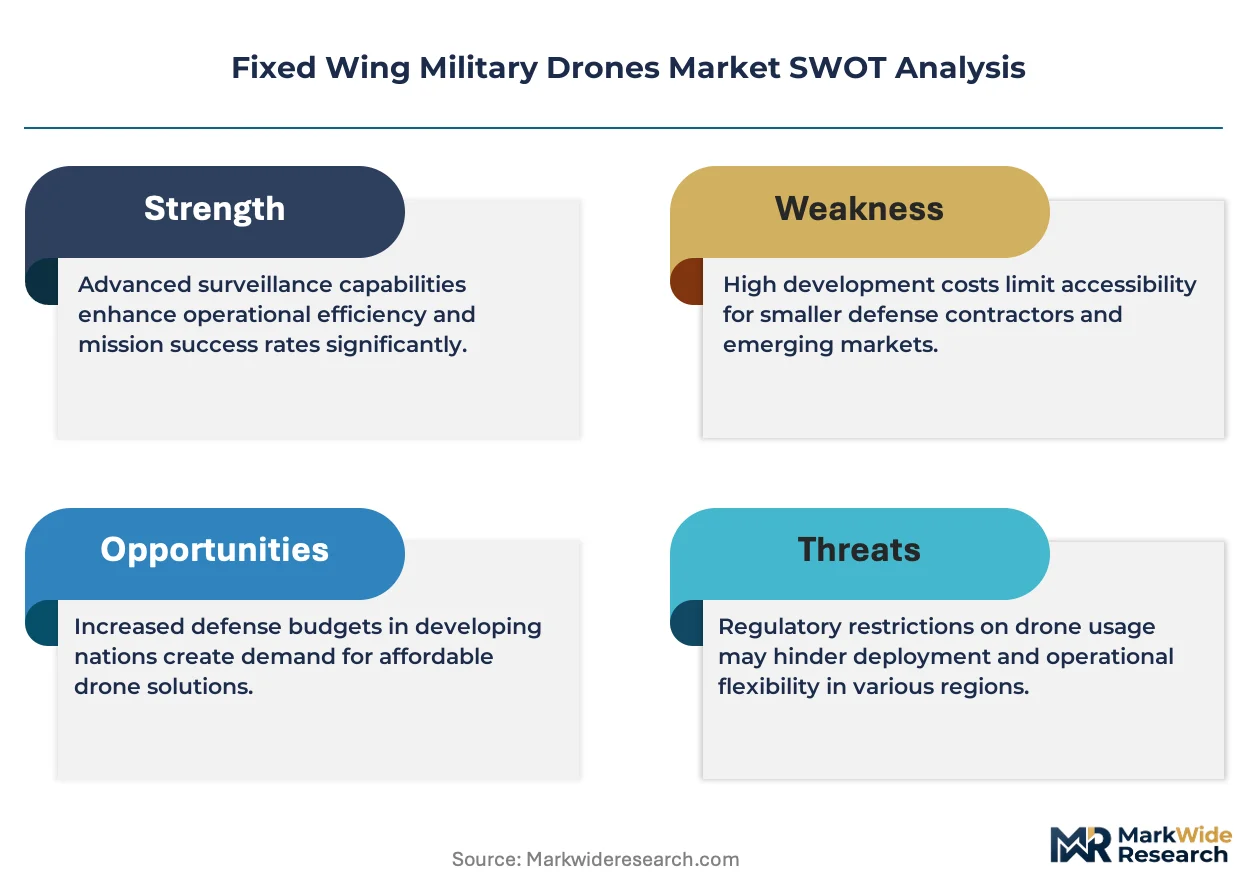
The FAA governs airworthiness certification pathways that constrain domestic flight testing timelines, while the EMA's CE marking and EU AI Act provisions shape algorithmic transparency requirements for autonomous engagement systems in European procurement. NATO's STANAG standards harmonize interoperability but create compliance barriers for non-member suppliers seeking cross-border sales. Stakeholders must monitor evolving rules of engagement policies governing human-in-the-loop decisions, as these will determine whether beyond-line-of-sight automated flight modes achieve operational acceptance or face operational restrictions.
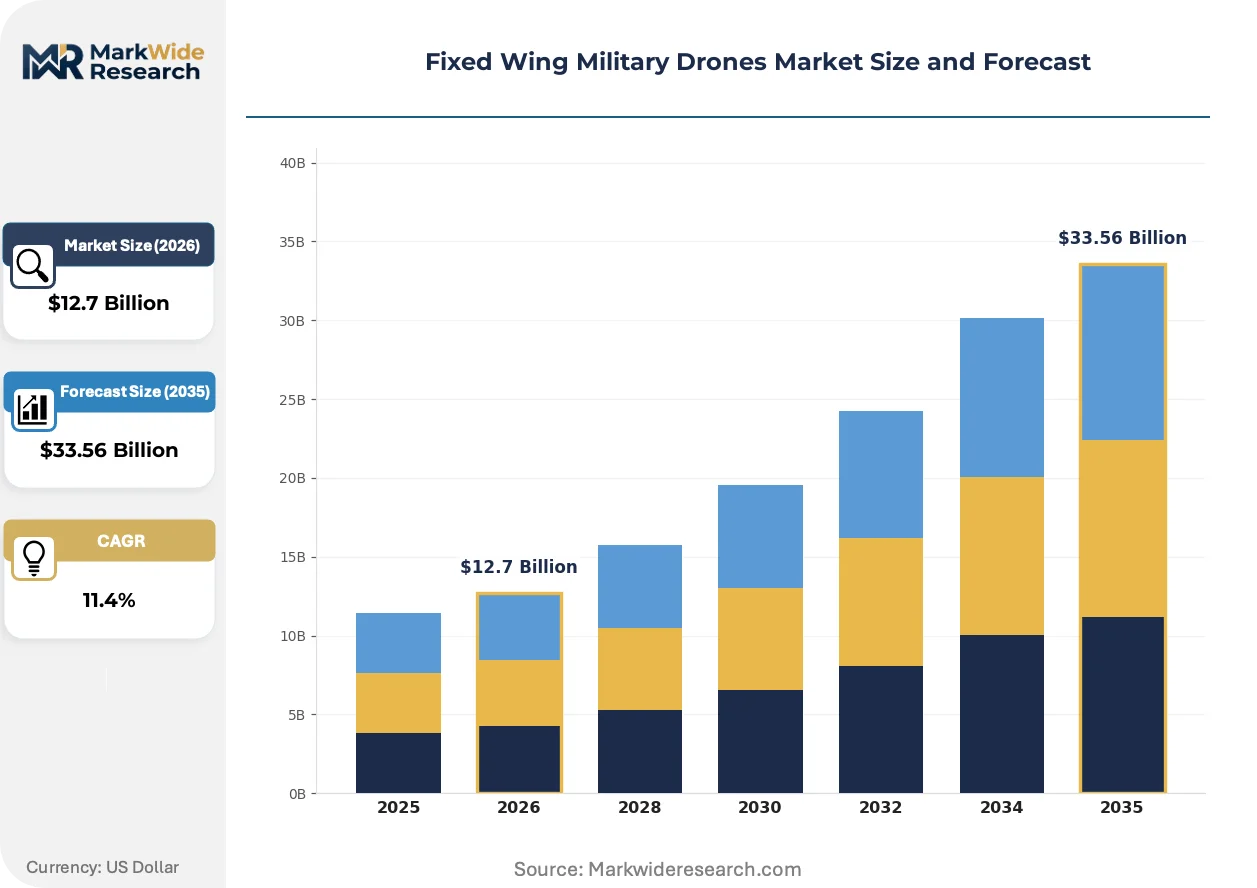
Market Dynamics
The Fixed Wing Military Drones Market is restructuring around sovereign autonomy mandates, with defense ministries prioritizing domestic supply chains for critical subsystems and pressuring foreign vendors into joint-venture architectures.
Growth Catalysts
- Indo-Pacific Maritime Patrol Expansion:Naval forces across Australia, Japan, and South Korea are fielding long-endurance platforms for contested waterway surveillance, creating sustained procurement pipelines for turboprop-powered systems.
- FAA Certification Pathway Acceleration:Streamlined military-to-civilian airworthiness frameworks are reducing flight-test timelines for dual-use platforms, enabling faster technology transfer to homeland security agencies.
- Autonomous Targeting Validation:Air forces in NATO member states are operationalizing machine-learning engagement protocols, expanding operational envelopes for combat-variant procurement.
Market Restraints
- Semiconductor Supply Concentration:Radiation-hardened chip fabrication concentrates among three East Asian foundries, exposing prime contractors to single-source vulnerability for flight-control processors.
- EU AI Act Algorithmic Transparency:European procurement rules now mandate explainable decision trees for autonomous engagement systems, extending software validation cycles by 18-24 months.
- Manned Aviation Substitution Economics:Fighter jet and maritime patrol aircraft retain institutional preference in several air forces, compressing budget allocations for unmanned alternatives in mixed fleet competitions.
Strategic Opportunities
- Attritable Platform Scale Production:Jet-powered loyal wingman concepts priced below manned fighter operating costs are opening new budget categories for air forces previously excluded from advanced unmanned procurement.
- Swarming Architecture Integration:Convergence of mesh-network communications and distributed artificial intelligence enables coordinated multi-aircraft missions previously requiring single large airframes.
- Poland and Baltic Defense Modernization:NATO eastern flank members are establishing dedicated unmanned systems commands, creating localized demand centers for expeditionary-class platforms with rapid deployment requirements.
Industry Challenges
- Human-in-the-Loop Policy Fragmentation:Rules of engagement vary across national command authorities, forcing platform designers to maintain multiple software configurations for identical hardware exports.
- Legacy C4ISR Integration Complexity:Existing ground control stations from 1990s-era programs require costly middleware development to communicate with modern IP-based datalink architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Wing Military Drones Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reconnaissance Drones, Surveillance Drones, Combat Drones, Training Drones End User: Defense Forces, Law Enforcement, Intelligence Agencies, Governmental Organizations Technology: Autonomous Systems, Remote Control, Surveillance Capabilities, Navigation Systems Operation Mode: Line of Sight, Beyond Line of Sight, Automated Flight, Manual Flight |
| Companies Covered | UAVOS Inc., Norinco, AeroVironment, General Atomics, Zala Unmanned Systems, Kratos Defense & Security Solutions, Anduril Industries, Northrop Grumman, TEKEVER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Wing Military Drones Market Emerging Trajectories
Active development portfolios are converging on modular payload architectures and sovereign manufacturing requirements, with platform economics increasingly determined by software upgrade velocity rather than airframe longevity.
Synthetic aperture radar and signals intelligence fusion is migrating from dedicated large-airframe installations to compact gimbal systems deployable across medium-altitude platforms. Israeli and Turkish defense forces are fielding these condensed packages at squadron scale. This compression is migrating from boutique special-mission units toward standard line-squadron equipment, collapsing the historical price premium between surveillance and multi-intelligence variants.
The EU AI Act's risk-classification framework for autonomous weapon systems is forcing European primes to rearchitect software stacks for algorithmic auditability. Industrial consequence includes mandatory third-party code review for export-licensed platforms. Combat-drone segments bound for European Union member state procurement are responding by segregating mission-computer hardware between flight-critical and targeting functions.
Defense ministries are consolidating vendor relationships through multi-year availability contracts that bundle airframe, sensor, and sustainment into single performance metrics. Traditional transactional procurement of discrete platforms is yielding to contractor logistics support arrangements where operational availability guarantees replace unit-price competition. This restructuring is most visible in United States Department of Defense programs, where Indo-Pacific prepositioning requirements favor vendor co-location with forward-deployed maintenance infrastructure.
Fixed Wing Military Drones Market Segmentation
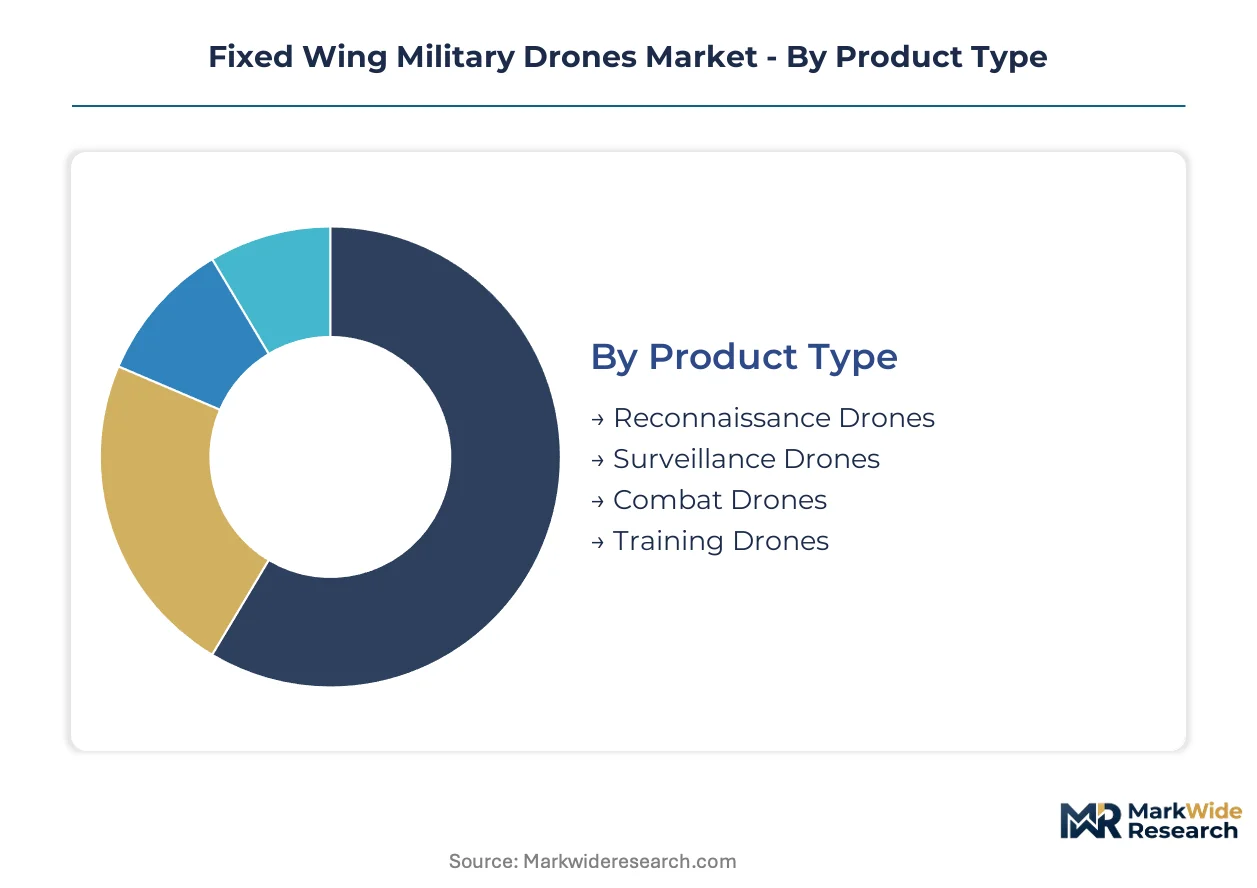
Fixed wing military drones segment across mission function, operator type, and control architecture, with procurement patterns diverging sharply between endurance-class surveillance platforms and attritable combat variants. Technology integration and operational mode selections determine unit economics and export compliance requirements more than airframe specifications alone.
Product Type:
Mature surveillance and reconnaissance categories coexist with emerging combat and training variants, reflecting divergent development timelines and validation requirements.
- Reconnaissance Drones:Long-endurance platforms equipped with multi-spectral imaging and signals intelligence payloads for deep-penetration intelligence collection. Demand concentrates in United States Indo-Pacific Command operations, where beyond-line-of-sight datalinks support contested environment missions. Procurement pipelines favor turboprop propulsion for 24+ hour endurance profiles.
- Surveillance Drones:Medium-altitude systems optimized for persistent area coverage through synthetic aperture radar and electro-optical fusion. Border security agencies across Poland, Romania, and Baltic states drive near-term procurement for NATO eastern flank monitoring. FAA certification pathways accelerate dual-use transfers to homeland security applications.
- Combat Drones:Jet-powered platforms with precision strike and electronic warfare capabilities. Autonomous targeting validation remains incomplete across NATO command authorities.
- Training Drones:Subscale target platforms and adversary air surrogates for live-fire exercises. Kratos Defense attritable systems anchor this segment with operating costs below manned fighter alternatives.
Reconnaissance drones handle the majority of throughput; combat drones are expanding most quickly on share as autonomous engagement protocols gain operational acceptance.
End User:
Customer concentration spans sovereign defense ministries, with procurement authority fragmentation creating distinct qualification requirements across institutional buyers.
- Defense Forces:Uniformed military services operating integrated unmanned systems commands with dedicated maintenance infrastructure. United States Department of Defense multi-year availability contracts bundle airframe, sensor, and sustainment into operational availability guarantees rather than unit-price competition.
- Law Enforcement:Federal and state-level agencies requiring FAA-certified platforms for border patrol and counter-narcotics missions. Streamlined military-to-civilian airworthiness frameworks reduce flight-test timelines for technology transfer.
- Intelligence Agencies:Civilian and military intelligence services prioritizing low-observable signatures and specialized signals intelligence payloads. Operational security requirements constrain vendor selection to domestic or allied-nation suppliers.
- Governmental Organizations:Coast guards, customs services, and emergency management agencies with disaster response and maritime domain awareness missions. Procurement volumes remain below defense force thresholds but accelerate with dual-use platform availability.
Defense forces absorb the dominant procurement volume; intelligence agencies are gaining share fastest through classified program expansion.
Technology:
Control architecture and sensor integration determine platform classification and export licensing tiers more than propulsion or airframe design.
- Autonomous Systems:Machine-learning flight control and targeting algorithms with human-in-the-loop override protocols. EU AI Act risk-classification frameworks mandate algorithmic auditability for European procurement, extending software validation cycles.
- Remote Control:Ground-based piloting through C-band or Ku-band datalinks with manual waypoint management. Legacy C4ISR integration complexity forces costly middleware development for compatibility with 1990s-era ground control stations.
- Surveillance Capabilities:Fused electro-optical, infrared, and synthetic aperture radar subsystems. Israeli and Turkish defense forces field compact gimbal packages at squadron scale, collapsing historical price premiums between surveillance and multi-intelligence variants.
- Navigation Systems:GPS-denied positioning through inertial measurement units, celestial navigation, and terrain-relative matching. Semiconductor supply concentration in East Asian foundries exposes flight-control processors to single-source vulnerability.
Surveillance capabilities generate the highest value capture; autonomous systems are climbing the fastest as rules of engagement policies evolve.
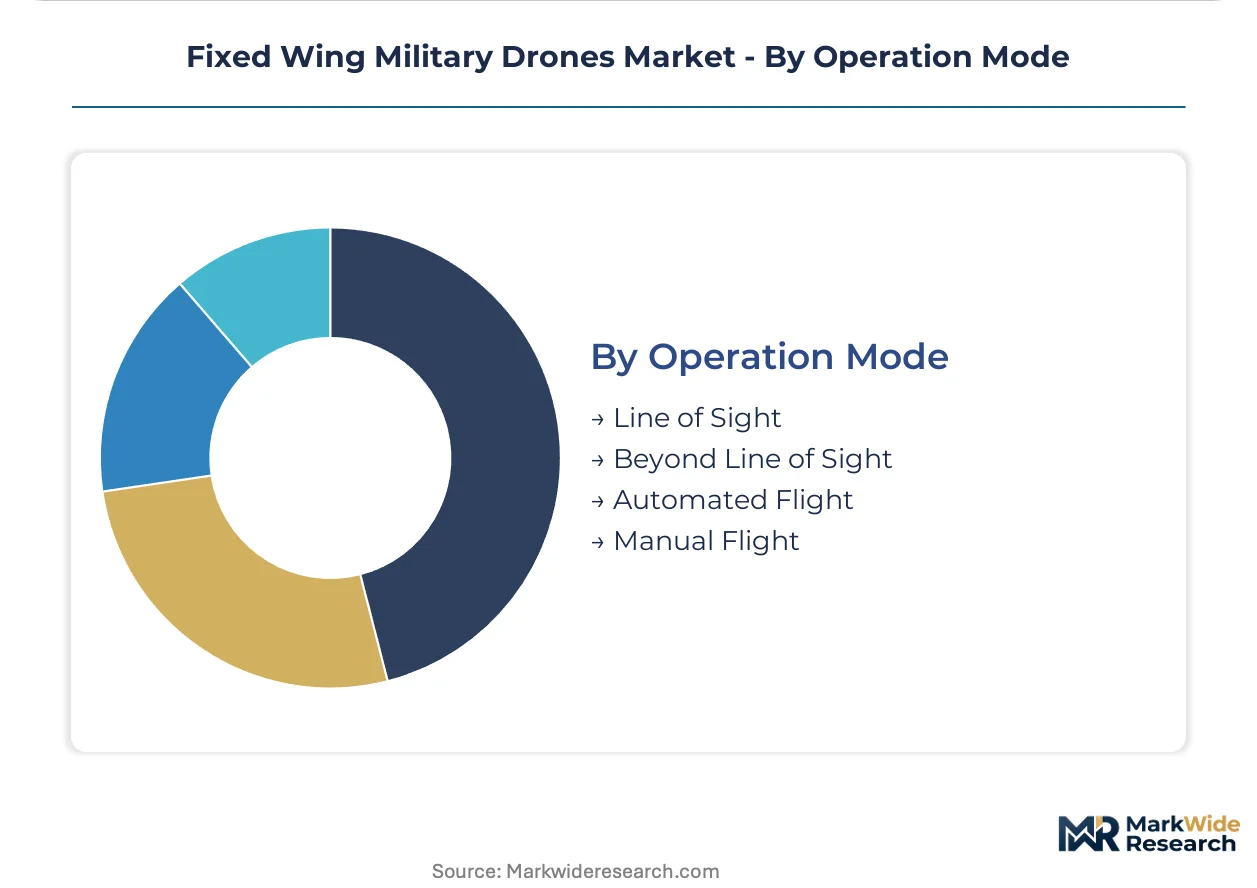
Operation Mode:
Control range and automation level determine mission envelope, regulatory compliance burden, and operator training requirements.
- Line of Sight:Visual-range operation with direct radio control, typical of tactical hand-launched platforms for expeditionary units. AeroVironment dominates this mode through rapid-deployment systems for dismounted infantry.
- Beyond Line of Sight:Satellite-relayed command links enabling transcontinental mission profiles. United States Indo-Pacific prepositioning requirements favor vendor co-location with forward-deployed maintenance infrastructure.
- Automated Flight:Pre-programmed waypoint navigation with autonomous contingency responses. Human-in-the-loop policy fragmentation across national command authorities forces multiple software configurations for identical hardware exports.
- Manual Flight:Real-time pilot control through all flight phases, retaining operational preference for complex contested environments where autonomous decision-making faces restrictions.
Beyond line of sight commands the investment priority; automated flight is gaining share fastest as NATO STANAG interoperability standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA governs airworthiness certification pathways that constrain domestic flight testing timelines, while defense procurement across NATO members and allied Pacific nations reshapes vendor qualification requirements. Sovereign autonomy mandates are pressuring foreign vendors into joint-venture architectures as defense ministries prioritize domestic supply chains for critical subsystems.
United States
The Department of Defense prioritizes autonomous beyond-line-of-sight capabilities for Indo-Pacific operations, driving multi-year availability contracts that bundle airframe, sensor, and sustainment into operational availability guarantees. FAA integration of unmanned systems into national airspace frameworks accelerates certification pathways for military-to-civilian technology transfers. General Atomics leverages integrated ground control and sensor payload architecture from its San Diego operations to sustain sole-source positions on endurance-class programs.
United Kingdom
Royal Air Force procurement validates machine-learning engagement protocols for combat-variant platforms, expanding operational envelopes for autonomous targeting systems. NATO STANAG standards harmonize interoperability requirements while creating compliance barriers for non-member suppliers seeking cross-border sales. BAE Systems and QinetiQ anchor unmanned systems development clusters in Lancashire and Farnborough, supporting sovereign manufacturing requirements for critical flight-control subsystems.
Germany
Bundeswehr acquisition channels favor turboprop-powered platforms with 24+ hour endurance profiles for persistent area coverage missions. EU AI Act algorithmic transparency mandates extend software validation cycles by 18-24 months for autonomous engagement systems bound for European procurement. Rheinmetall and Diehl Defence concentrate development activity in Bavaria and Baden-Württemberg, responding to risk-classification frameworks through segregated mission-computer hardware architectures.
Israel
Israeli Defense Forces field compact gimbal packages fusing synthetic aperture radar and signals intelligence at squadron scale, collapsing historical price premiums between surveillance and multi-intelligence variants. National command authority rules of engagement favor human-in-the-loop override protocols for contested environment operations. Elbit Systems and Israel Aerospace Industries maintain integrated production facilities in Haifa and the Negev Desert, supporting classified program expansion for intelligence agency customers.
Australia
Royal Australian Navy procurement of long-endurance platforms for contested waterway surveillance creates sustained pipelines for maritime patrol variants. AUKUS technology-sharing frameworks accelerate sovereign capability development for autonomous systems integration. Boeing Australia and local defense primes establish maintenance infrastructure in Queensland and South Australia to support Indo-Pacific prepositioning requirements and forward-deployed operational availability guarantees.
Fixed Wing Military Drones Market Vendor Landscape
Endurance-class specialists and attritable-platform developers split the market between multi-decade sensor upgrade cycles and rapid-production loyal wingman concepts. Tier-1 primes with integrated ground control architectures command sole-source positions on high-value surveillance programs, while tactical-portability vendors compete on expeditionary deployment velocity. Competitive dynamics center on contractor logistics support arrangements replacing unit-price competition, alongside sovereign manufacturing mandates forcing joint-venture structures for foreign market access.
Within the endurance-class tier, General Atomics and Northrop Grumman represent integrated-systems archetypes with multi-year sole-source positioning on Department of Defense programs. Kratos Defense & Security Solutions anchors the attritable segment, exemplifying jet-powered target platforms priced below manned fighter operating costs. AeroVironment occupies the tactical-portability vector, supporting rapid-deployment requirements for dismounted infantry through hand-launched systems. UAVOS Inc. and Zala Unmanned Systems represent specialized regional developers responding to localized sovereign autonomy mandates through indigenous production capabilities.
| Leading Market Players |
|---|
| UAVOS Inc. |
| Norinco |
| AeroVironment |
| General Atomics |
| Zala Unmanned Systems |
| Kratos Defense & Security Solutions |
| Anduril Industries |
| Northrop Grumman |
| TEKEVER |
| Others |
Supply Flow & Price Mechanics
Radiation-hardened semiconductor fabrication concentrates among East Asian foundries, anchoring cost structures for flight-control processors and concentrating margin capture with prime contractors who maintain multi-year sole-source positions on endurance-class programs.
Pricing Analysis
Geographic price spreads widen between United States Department of Defense sole-source contracts and NATO allied-nation competitive procurements, with contractor logistics support arrangements replacing unit-price competition. Three-tier pricing structure across premium endurance-class platforms, standard medium-altitude surveillance systems, and economy attritable targets reflects differentiation by certification grade and operational availability guarantees. Pricing pressure stems from sovereign autonomy mandates pressuring foreign vendors into joint-venture architectures with domestic partners. Defense forces exhibit lowest price sensitivity given mission-critical requirements, while governmental organizations and coast guards face budget constraints compressing procurement timelines.
Supply Chain Analysis
Upstream feedstock for composite airframes and specialized avionics draws from United States, Israel, and Turkey, with turboprop engines sourcing from Pratt & Whitney Canada and Continental Aerospace. Critical dependencies include gallium nitride semiconductors for radar systems, carbon fiber prepregs for lightweight structures, and precision inertial measurement units for navigation. Single-source vulnerability in radiation-hardened chip fabrication exposes prime contractors to supply disruption. Distribution runs through defense procurement channels with multi-year availability contracts bundling airframe, sensor, and sustainment into operational readiness guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in fixed wing military drones hinge on software upgrade velocity displacing airframe longevity as the primary value driver, with NATO STANAG interoperability standards and AUKUS technology-sharing frameworks creating ecosystem lock-in effects that reshape competitive positioning.
For Market Incumbents: Build switching-cost moats through integrated ground control station architectures that embed proprietary datalink protocols and sensor fusion software. General Atomics exemplifies this approach with multi-decade sole-source positioning on Department of Defense endurance programs. Deepen backward integration into flight-control processor design to mitigate East Asian foundry concentration risk. Invest in forward-deployed maintenance infrastructure across Indo-Pacific prepositioning sites to satisfy operational availability guarantees.
For New Entrants and Emerging Players: Build out attritable platform production capabilities targeting air forces previously excluded from advanced unmanned procurement by manned fighter operating costs. Poland and Baltic defense modernization programs present penetrable entry points with rapid deployment requirements for expeditionary-class systems. Pursue sovereign manufacturing joint ventures with NATO eastern flank members to satisfy domestic supply chain mandates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed defense technology platforms possessing FAA certification pathways and established military-to-civilian technology transfer capabilities. Long-term viability favors vendors with contractor logistics support contract experience and software-defined payload architectures. Watch for inflection signals in autonomous targeting validation across NATO command authorities, as rules of engagement policy convergence would accelerate combat-drone procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Availability Contracting | Bundles airframe, sensor, and sustainment into operational readiness guarantees replacing unit-price competition. |
| Sovereign Manufacturing Joint Venture | Satisfies domestic supply chain mandates for critical flight-control subsystems in NATO member states. |
| Autonomous Targeting Software Certification | Addresses EU AI Act algorithmic transparency requirements through segregated mission-computer architectures. |
| Forward-Deployed Maintenance Infrastructure | Supports Indo-Pacific prepositioning requirements with vendor co-location for rapid response availability. |
| Compact Multi-Intelligence Payload Development | Migrates synthetic aperture radar and signals intelligence fusion from large-airframe to medium-altitude platforms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with unmanned systems program managers at defense ministries, procurement officers at NATO allied-nation air forces, flight-test engineers at FAA certification centers, and sustainment directors at contractor logistics support operations. Secondary validation drew from Department of Defense budget justification documents, NATO STANAG standard publications, FAA airworthiness certification filings, and EU AI Act regulatory impact assessments. Bottom-up platform deployment forecasts were triangulated against top-down defense expenditure projections across the analysis window.
Calibration against historical program award patterns and technology adoption curves informed segmentation modeling across mission function, operator type, control architecture, and operation mode. CAGRs were derived from deployment velocity assumptions tied to autonomous targeting validation timelines and sovereign autonomy mandate implementation. Industry-specific forecast inputs included semiconductor supply lead times, flight-test certification durations, and rules of engagement policy evolution across national command authorities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by attritable-platform specialists or sovereign manufacturing mandates by Baltic defense ministries would shift outcomes beyond modeled ranges. Quarterly review of FAA certification pathway acceleration, EU AI Act enforcement precedence, and Indo-Pacific maritime patrol procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Small UAV Market
UAV
Europe Drone Light Shows Market
UAV
Drones Market
UAV
Drone Payload Market
UAV
Toy Drones Market
UAV
Drone Powered Business Solutions Market
UAV
Asia Pacific Commercial Drone Market
UAV
Rc Helicopter Market
UAV
Global Drone Services Market
UAV
North America Drone Services Market
UAV
Europe Commercial Drones Market
UAV
Autonomous Aircraft Cameras Market
UAV
Delivery Drones Market
UAV
UAV Navigation Systems Market
UAV
Global Aerial Imaging Market
UAV
Anti-Drone Technology Market