
 Reverse Osmosis Pump Market | 2026-2036
Reverse Osmosis Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Osmosis Pump Market Analytics
Specialized hydraulic engineering talent is unwinding supply bottlenecks for high-pressure RO pump fabrication. Grundfos leverages its Danish R&D campus to sustain energy-recovery integration across desalination installations. Xylem anchors North American municipal retrofit programs with smart monitoring architectures. Danfoss competes through variable frequency drive pairing that trims energy draw on membrane trains.
Reverse osmosis pumps are positive-displacement or centrifugal units engineered to deliver 800–1,200 psi feed pressure to semipermeable membranes, separating dissolved solids from brackish water or seawater for potable and industrial use. Centrifugal pumps dominate large-scale desalination for their flow scalability, while diaphragm pumps occupy niche high-pressure brackish applications where precise chemical dosing intersects with membrane protection. Energy recovery technology is the fastest-growing segment as plant operators target operating expenditure reduction on energy-intensive seawater reverse osmosis trains.
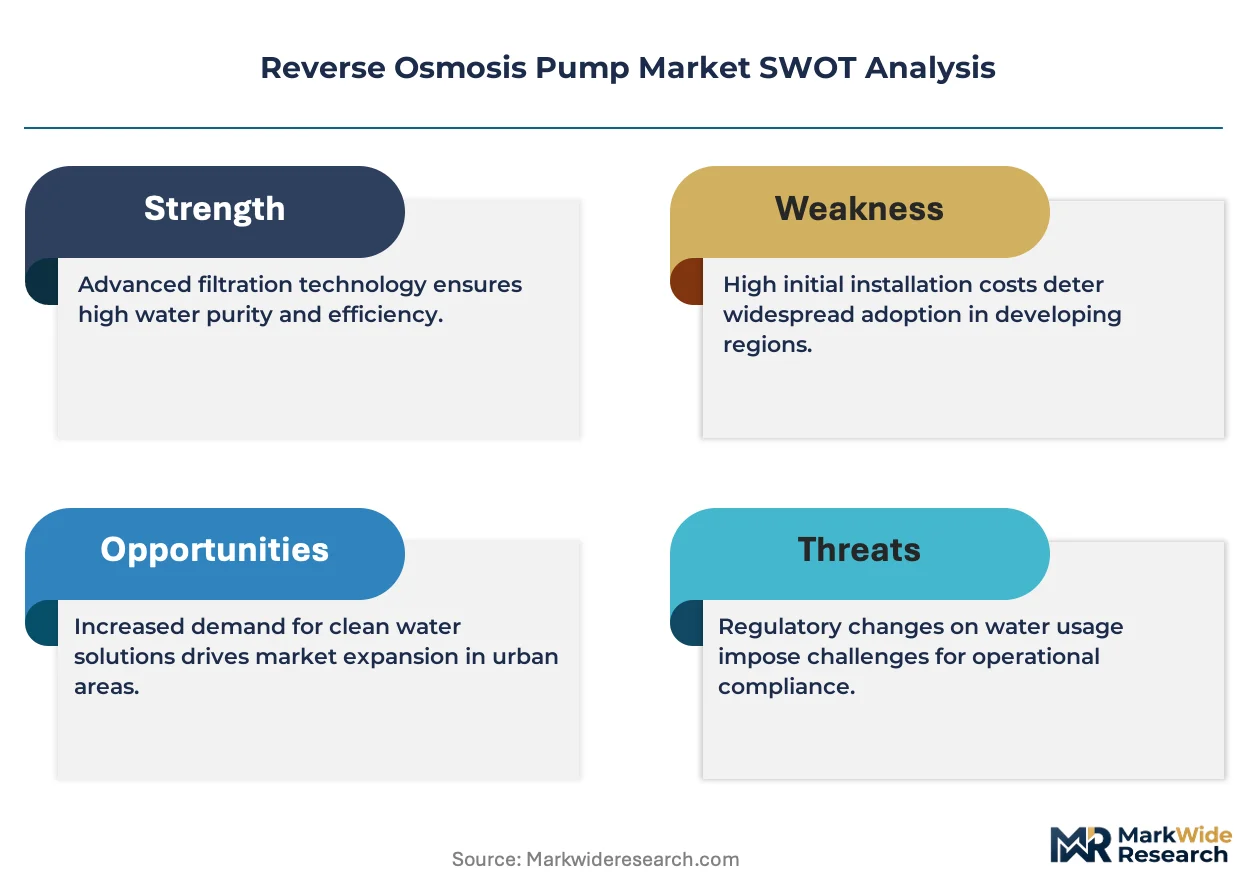
The EPA Lead and Copper Rule revisions and California's Title 22 recycled water standards shape product certification requirements for potable and reclaimed water service. The EU Green Deal and F-Gas Regulation pressure manufacturers to eliminate fluorinated seal materials and document lifecycle carbon intensity. Saudi Arabia's Saline Water Conversion Corporation procurement mandates and India's Central Pollution Control Board effluent norms collectively expand addressable demand for corrosion-resistant alloy pump construction. Stakeholders must weigh energy recovery integration depth against upfront capital allocation as electricity tariffs fluctuate and membrane fouling protocols tighten.
Market Dynamics
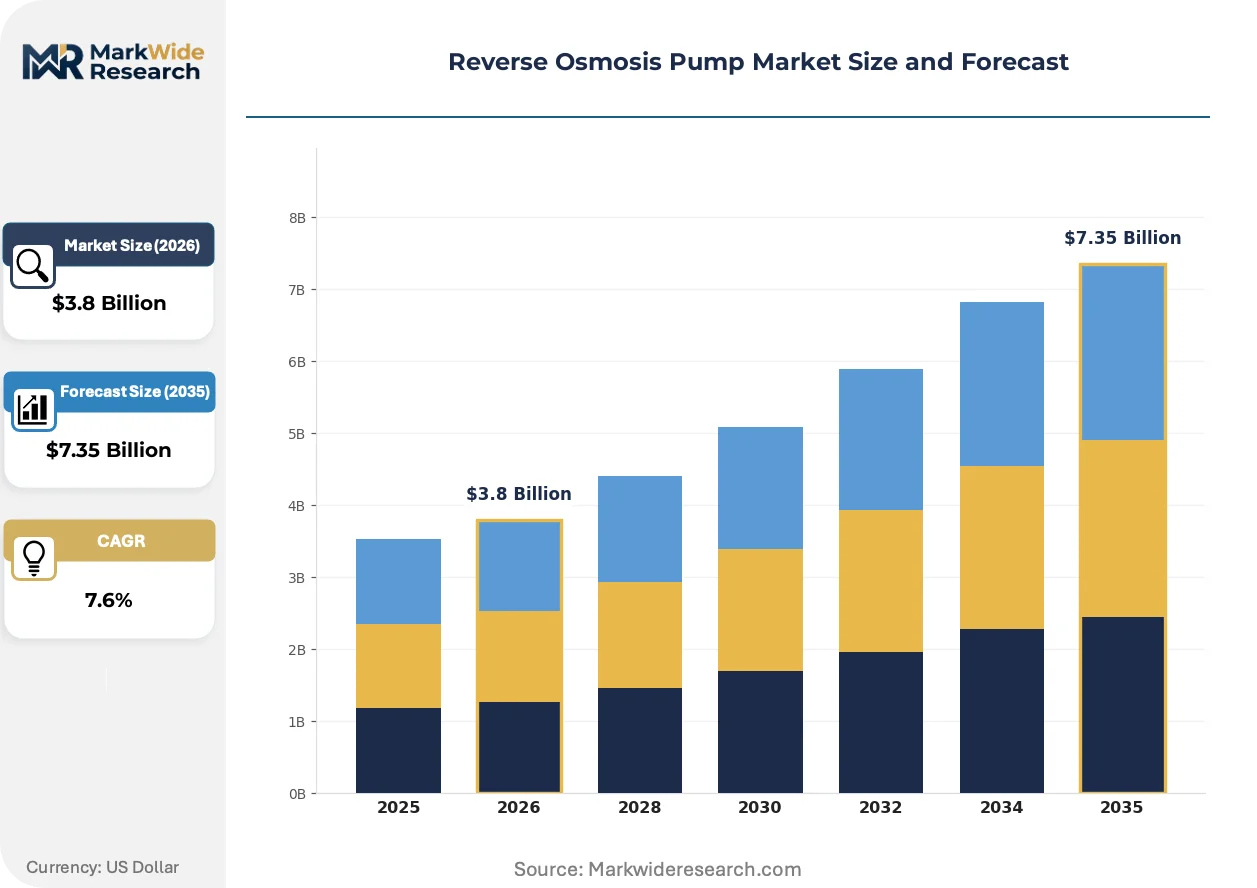
Energy recovery device integration is compressing operating expenditure for seawater reverse osmosis trains while simultaneously raising upfront capital requirements for pump procurement. This tension between lifecycle cost optimization and initial equipment outlay now governs specification decisions across municipal and industrial desalination projects.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Tightened potable water purity thresholds in the United States mandate membrane-based filtration upgrades, expanding replacement demand for high-pressure feed pumps in municipal distribution networks.
- Saudi Arabia's IWPP megaproject pipeline:Saline Water Conversion Corporation procurement mandates for independent water and power producers are scaling membrane train capacity across the Red Sea and Gulf coasts.
- Isobaric energy recovery devices:Pressure exchanger technology paired with centrifugal pumps is reducing specific energy consumption below 3 kWh per cubic meter, accelerating retrofit cycles in aging Mediterranean and Caribbean plants.
Market Restraints
- Super-duplex stainless steel supply concentration:Foundry capacity for corrosion-resistant alloys concentrates in Scandinavian and Japanese suppliers, exposing pump manufacturers to 18-24 month lead times for critical castings.
- Fluorinated seal material phase-out:EU F-Gas Regulation compliance is eliminating perfluoroelastomer options, forcing reformulation of high-pressure sealing systems with unproven lifecycle durability.
- Electrodialysis reversal substitution:Brackish water treatment operators in the US Great Plains are piloting ED-R trains for TDS below 10,000 ppm, displacing RO pump demand in specific groundwater remediation applications.
Strategic Opportunities
- India's industrial effluent reuse mandate:Central Pollution Control Board zero-liquid-discharge requirements for textile and pharmaceutical clusters are creating first-time demand for high-pressure brackish pumps in Gujarat and Tamil Nadu.
- Digital twin integration:Smart monitoring architectures converging with predictive maintenance algorithms are opening subscription-based service revenue streams for pump OEMs serving North American municipal retrofits.
- California Title 22 indirect potable reuse:Advanced treatment train certification for recycled water injection is expanding the addressable market for corrosion-resistant pump construction in Orange County and Los Angeles basin projects.
Industry Challenges
- High-pressure hydraulic engineering talent scarcity:Specialized design expertise for 1,000+ psi centrifugal staging is concentrating at Danish and German R&D campuses, constraining fabrication capacity expansion.
- Membrane train integration complexity:Variable frequency drive pairing with energy recovery devices requires synchronized control architecture, extending commissioning timelines and site acceptance testing.
- Multi-jurisdictional certification burden:Pump assemblies must simultaneously satisfy NSF/ANSI 61 for North American potable service, WRAS for UK compliance, and ACS for French market entry, fragmenting product platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Osmosis Pump Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Centrifugal Pumps, Peristaltic Pumps, Submersible Pumps Application: Water Treatment, Desalination, Industrial Process, Waste Water Management End User: Municipalities, Industrial Facilities, Residential Users, Commercial Establishments Technology: Membrane Technology, Energy Recovery, Filtration Technology, Automation Solutions |
| Companies Covered | CAT Pumps, Grundfos, KSB, Pentair, Xylem, Evoqua Water Technologies, Danfoss, Alfa Laval, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Osmosis Pump Market Evolving Landscape
Digitalization of hydraulic performance monitoring is enabling predictive maintenance contracts that unbundle hardware from lifecycle service revenue. This shift is compressing traditional equipment-only sales models while expanding recurring income pools for technology-integrated suppliers.
Ceramic-coated impeller surfaces are displacing traditional super-duplex metallurgy in high-salinity environments. Saudi Aramco and ADNOC procurement specifications now prioritize silicon carbide coating for seawater intake pumps, reducing cavitation erosion by 60% compared to untreated alloys. The structural consequence is compressing aftermarket spare parts demand while extending mean time between overhauls beyond 80,000 operating hours.
REACH Annex XVII restrictions on chromium(VI) compounds are forcing reformulation of surface treatment protocols for pump housings. German and Dutch manufacturers are transitioning to trivalent chromium and plasma electrolytic oxidation finishes, adding 8-12% to coating costs but securing CE marking continuity. The industrial water treatment segment is absorbing these cost increments fastest, as EMAS-registered facilities face heightened supply chain due diligence requirements.
Performance-based contracting is displacing capital purchase models for large desalination operators. Suez and Veolia water divisions now specify guaranteed output-per-kWh terms, transferring operational risk to pump and energy recovery system integrators. This procurement evolution is most visible in Australia's Gold Coast and Perth plants, where 15-year service agreements now dominate tender structures over traditional EPC arrangements.
Reverse Osmosis Pump Market Segmentation
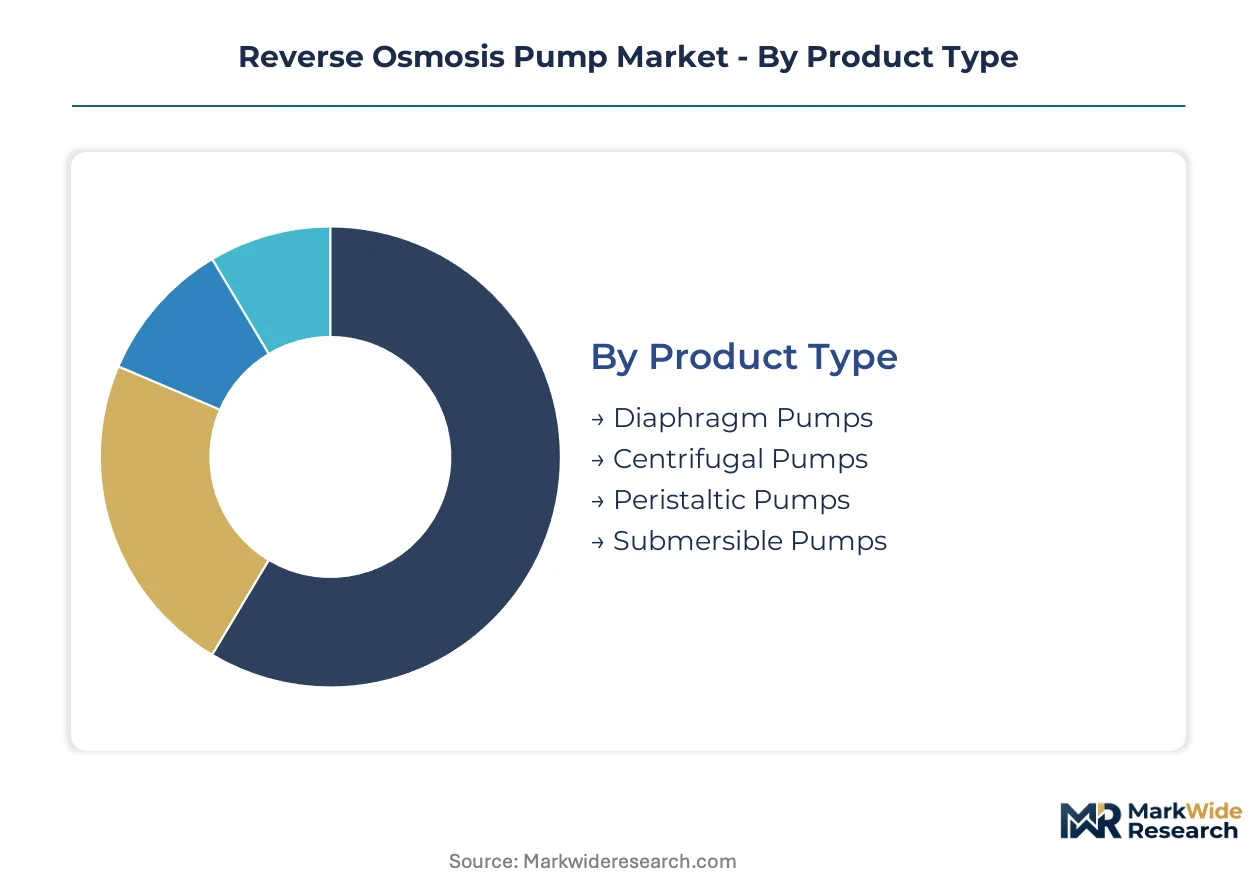
Reverse osmosis pump procurement patterns diverge sharply across product architectures and end-use contexts. Specification committees weight capital efficiency against membrane protection requirements differently in Saudi megaprojects versus California municipal retrofits. Segmentation clarity enables suppliers to align R&D cadence with geographic demand concentration.
Product Type:
Domestic fabrication capacity concentrates centrifugal and diaphragm pump lines in Denmark and Germany for European and Middle Eastern export markets. Peristaltic and submersible variants rely more heavily on Asian assembly for cost-sensitive residential and commercial applications.
- Centrifugal Pumps:Multi-stage horizontal or vertical configurations deliver 800–1,200 psi feed pressure to membrane trains through optimized impeller geometry. Demand concentrates in Saudi Arabia's Saline Water Conversion Corporation procurement pipeline and Australia's Gold Coast desalination expansion, driven by scale economies in 50,000+ cubic meter-per-day installations.
- Diaphragm Pumps:Positive-displacement mechanisms with PTFE or HNBR diaphragms provide precise flow control and chemical compatibility for high-pressure brackish applications. California Title 22 indirect potable reuse projects and Gujarat textile cluster zero-liquid-discharge mandates are absorbing capacity, constrained by super-duplex stainless steel casting lead times from Scandinavian foundries.
- Peristaltic Pumps:Hose compression technology eliminates seal wear in low-pressure pretreatment and chemical dosing loops.
- Submersible Pumps:Immersed motor configurations serve seawater intake and brine disposal applications where NPSH constraints dominate.
Centrifugal pumps command the established base. The steepest expansion runs through diaphragm pumps.
Application:
Cost tier segmentation separates municipal-scale desalination with 15-year service agreements from industrial process water procurement on 3-5 year replacement cycles. Water treatment and wastewater management applications absorb mid-tier pricing, while desalination projects negotiate performance-based contracting with energy recovery integration.
- Desalination:Seawater and brackish membrane trains require corrosion-resistant alloy construction, ceramic-coated impellers, and isobaric energy recovery device pairing. Saudi Arabia's Red Sea and Gulf coast IWPP pipeline, Australia's Perth and Gold Coast plants, and Spain's Carboneras facility upgrades are concentrating specification activity.
- Water Treatment:Municipal distribution network upgrades for EPA Lead and Copper Rule compliance and North American municipal retrofit programs anchor demand for NSF/ANSI 61 certified high-pressure feed pumps with smart monitoring architectures.
- Industrial Process:Pharmaceutical and electronics manufacturing ultrapure water systems specify pumps with documented lifecycle carbon intensity under EU Green Deal procurement screens.
- Waste Water Management:India's Central Pollution Control Board effluent norms for Tamil Nadu pharmaceutical clusters are creating first-time demand for corrosion-resistant construction in reuse applications.
Desalination absorbs the premium tier. Water treatment offers the broadest retrofit runway.
End User:
Customer type determines specification authority structure and procurement timeline. Municipalities run 18-24 month tender cycles with engineering consultant oversight, while industrial facilities delegate to EPC integrators on faster-tracked commercial terms.
- Municipalities:Public water utilities in the United States, Saudi Arabia, and Australia specify energy recovery integration depth against electricity tariff volatility, with digital twin and predictive maintenance requirements expanding in North American retrofits.
- Industrial Facilities:Textile, pharmaceutical, and electronics manufacturers in Gujarat, Tamil Nadu, and Orange County face zero-liquid-discharge or indirect potable reuse mandates that compress procurement into 6-12 month equipment-only or performance-based contracting structures.
- Residential Users:Point-of-use and point-of-entry systems in water-stressed regions specify compact diaphragm or booster pump configurations.
- Commercial Establishments:Hotels, hospitals, and food service operations in the US Great Plains are piloting electrodialysis reversal alternatives for brackish groundwater below 10,000 ppm TDS, displacing RO pump demand in specific remediation contexts.
Industrial facilities are expanding most quickly. Municipalities retain the largest installed base.
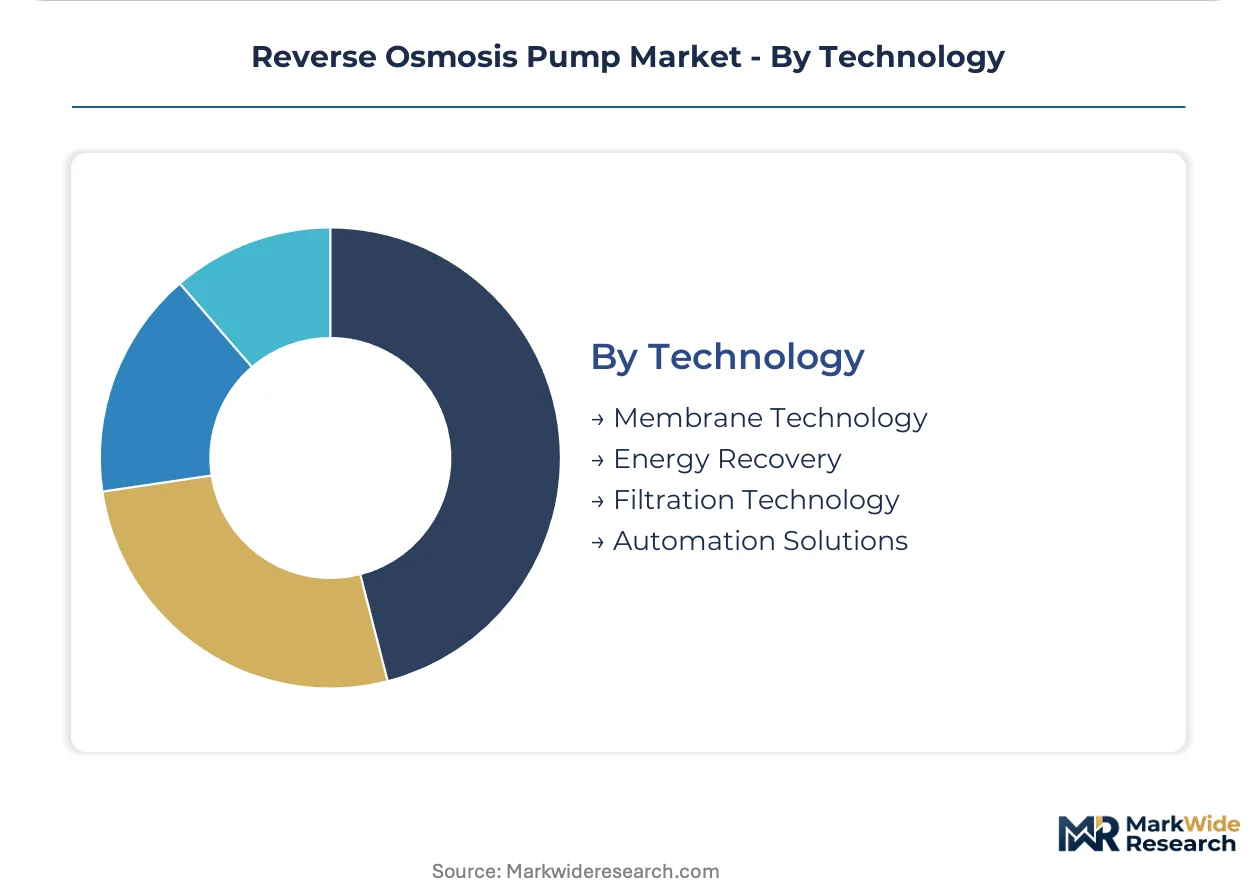
Technology:
Technology segmentation tracks integration depth from standalone pump hardware through fully automated membrane train architectures. Maturity curves separate proven membrane and filtration technologies from emerging energy recovery and automation solutions still navigating multi-jurisdictional certification.
- Energy Recovery:Isobaric pressure exchangers and work exchangers paired with centrifugal pumps reduce specific energy consumption below 3 kWh per cubic meter. Mediterranean and Caribbean plant retrofits are accelerating adoption, though variable frequency drive synchronization complexity extends commissioning timelines.
- Membrane Technology:High-rejection polyamide thin-film composite membranes dictate 800–1,200 psi feed pressure requirements that define pump staging and materials selection across all geographic markets.
- Filtration Technology:Pretreatment cartridge and media filtration systems specify low-pressure centrifugal or peristaltic pumps for chemical dosing and backwash operations.
- Automation Solutions:Smart monitoring architectures with predictive maintenance algorithms are opening subscription-based service revenue streams for OEMs serving North American municipal retrofits.
Membrane technology anchors incumbent specifications. Energy recovery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Lead and Copper Rule revisions are tightening potable water purity thresholds across the United States, while Saudi Arabia's Saline Water Conversion Corporation procurement mandates scale membrane train capacity. These regulatory anchors shape specification authority and procurement timelines across four concentrated demand centers.
United States
California's Title 22 recycled water standards and EPA compliance mandates drive municipal retrofit programs in Orange County and Los Angeles basin. North American utilities specify smart monitoring architectures with NSF/ANSI 61 certification for high-pressure feed pumps. The Great Plains region pilots electrodialysis reversal alternatives for brackish groundwater below 10,000 ppm TDS.
Saudi Arabia
Saline Water Conversion Corporation procurement mandates for independent water and power producers scale membrane train capacity across Red Sea and Gulf coasts. Megaproject pipelines concentrate specification activity in Riyadh and Eastern Province. Ceramic-coated impeller requirements from Saudi Aramco procurement screens prioritize silicon carbide surface treatment for seawater intake pumps.
Germany
REACH Annex XVII restrictions on chromium(VI) compounds force reformulation of surface treatment protocols for pump housings. German manufacturers transition to trivalent chromium and plasma electrolytic oxidation finishes for CE marking continuity. Bavarian and North Rhine-Westphalian fabrication clusters absorb coating cost increments for EMAS-registered industrial water treatment facilities.
India
Central Pollution Control Board zero-liquid-discharge requirements for textile and pharmaceutical clusters create first-time demand for high-pressure brackish pumps. Gujarat and Tamil Nadu industrial zones face compressed procurement timelines on 6-12 month equipment-only structures. Mumbai-Pune and Chennai-Bengaluru corridors concentrate corrosion-resistant alloy pump specification for effluent reuse mandates.
Australia
Performance-based contracting with 15-year service agreements now dominates tender structures over traditional EPC arrangements at Gold Coast and Perth desalination plants. TGA-equivalent water quality standards shape membrane train certification requirements. Western Australian utilities specify guaranteed output-per-kWh terms, transferring operational risk to system integrators.
Reverse Osmosis Pump Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in reverse osmosis pump fabrication. The upper tier commands specification authority on megaproject tenders through captive energy recovery integration capabilities. Specialist fabricators compete on alloy casting lead times and jurisdiction-specific certification bundling. Danish and German R&D campuses concentrate high-pressure hydraulic engineering talent, constraining capacity expansion for centrifugal staging above 1,000 psi. Competitive moves center on strategic partnerships for membrane train integration and geographic expansion through local certification acquisition.
Among the integrated tier, Grundfos anchors Danish R&D-led energy recovery integration across desalination installations. Xylem occupies a position exemplifying North American municipal retrofit program anchoring with smart monitoring architectures. Danfoss represents variable frequency drive pairing specialization that trims energy draw on membrane trains. These three exemplify the strategic archetypes of full-system integration, regional specification authority, and component-level energy optimization that structure competitive positioning.
| Leading Market Players |
|---|
| CAT Pumps |
| Grundfos |
| KSB |
| Pentair |
| Xylem |
| Evoqua Water Technologies |
| Danfoss |
| Alfa Laval |
| GEA Group |
| Others |
Value Network & Pricing Analysis
NSF/ANSI 61 certification for North American potable water service gates both supplier qualification and price differentiation simultaneously, separating premium-tier pump assemblies with documented lifecycle carbon intensity from economy-grade alternatives lacking smart monitoring integration. This regulatory threshold compresses margin structures for uncertified fabricators while concentrating pricing power with integrated OEMs that bundle energy recovery devices and predictive maintenance subscriptions.
Pricing Analysis
Price spreads between Scandinavian-sourced super-duplex castings and Asian-assembled standard alloys run 40-60% across equivalent pressure ratings. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with NSF/ANSI 61 plus EU Green Deal compliance commanding the top tier. Cost compression in the economy tier is intensifying because electrodialysis reversal pilots in the US Great Plains are displacing RO pump demand for brackish groundwater below 10,000 ppm TDS. Industrial facilities in Gujarat textile clusters exhibit the highest price sensitivity, while Saudi IWPP megaprojects prioritize guaranteed output-per-kWh terms over upfront capital minimization.
Supply Chain Analysis
Strategic stockpiling of super-duplex stainless steel castings dominates procurement strategy among European pump fabricators, contrasting with just-in-time component flows for variable frequency drives sourced from Asian electronics hubs. Foundry capacity concentrates in Denmark, Germany, and Japan for corrosion-resistant alloy pump housings. Raw material dependencies center on nickel-chromium-molybdenum superalloys, silicon carbide ceramic coatings, and HNBR elastomer compounds. Single-source vulnerability runs through Scandinavian foundry capacity for 1,000+ psi centrifugal staging castings. Distribution runs through EPC integrators on megaproject tenders and direct municipal procurement channels for North American retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse osmosis pump demand sits in early-cycle expansion as India's Central Pollution Control Board zero-liquid-discharge mandates create first-time high-pressure brackish pump installations across textile and pharmaceutical clusters previously unserved by membrane-based treatment.
For Market Incumbents: Compound specification authority by deepening captive energy recovery device integration and securing 15-year performance-based service agreements at Australian Gold Coast and Perth plants. Electrodialysis reversal substitution in US Great Plains brackish applications threatens volume in the sub-10,000 ppm TDS segment. Prioritize backward integration into ceramic-coated impeller surface treatment to reduce reliance on Japanese silicon carbide coating suppliers. For New Entrants and Emerging Players: Differentiate on rapid certification bundling for India's Central Pollution Control Board effluent norms, where 6-12 month procurement timelines favor agile responders over incumbent engineering consultant cycles. Gujarat and Tamil Nadu industrial zones represent the most penetrable geography. Lead with equipment-only sales structures before attempting performance-based contracting. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across energy recovery device integration as isobaric pressure exchanger pairing becomes standard rather than optional. Long-term viability favors OEMs with Danish or German R&D campuses where high-pressure hydraulic engineering talent concentrates. Acquisition target archetype: mid-cap specialists with WRAS or ACS certification assets and established relationships with Saline Water Conversion Corporation procurement. Watch for ceramic coating technology transfers from Saudi Aramco procurement screens as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Recovery Device Integration | Isobaric pressure exchanger pairing reduces specific energy consumption below 3 kWh per cubic meter at Mediterranean retrofits. |
| Ceramic Coating Technology Adoption | Silicon carbide surface treatment for seawater intake pumps cuts cavitation erosion by 60% per Saudi Aramco specifications. |
| Predictive Maintenance Platform Launch | Digital twin architectures open subscription revenue streams for OEMs serving North American municipal retrofit programs. |
| Multi-Jurisdictional Certification Acquisition | Simultaneous NSF/ANSI 61, WRAS, and ACS compliance fragments product platform economics but secures tender eligibility. |
| Zero-Liquid-Discharge System Partnership | Gujarat textile cluster mandates create first-time demand for corrosion-resistant alloy pump construction in India. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and project development databases. Primary interviews engaged desalination plant operators, EPC procurement managers, municipal water utility engineers, pump OEM technical directors, and energy recovery device specialists. Secondary validation drew from EPA Lead and Copper Rule documentation, Saline Water Conversion Corporation tender announcements, EU F-Gas Regulation compliance filings, and India Central Pollution Control Board effluent norm updates. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across product architectures and end-use contexts.
Segmentation dimensions modeled include pump type, application context, end-user category, and technology integration depth. Volume and value outputs reflect reconciliation of installed base replacement cycles, megaproject pipeline visibility, and retrofit program timelines across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns against regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated membrane train capacity expansion data from Saudi IWPP pipelines and California Title 22 indirect potable reuse certification timelines.
Material uncertainties — regulatory delay in EPA rule enforcement, foundry capacity constraints for super-duplex alloys, and electrodialysis reversal technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about electricity tariff trajectories and membrane fouling protocol standardization that could revise demand projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market