
 Melt & Gear Pump Market | 2026-2036
Melt & Gear Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Melt & Gear Pump Market Insights
Capital-intensity divergence between precision-machining specialists and volume-scale producers is bifurcating competitive dynamics across the melt and gear pump landscape. Dover (PSG) leverages integrated pump-drive systems to anchor North American polymer processing demand. Oerlikon sustains dominance in high-temperature alloy metallurgy for corrosive chemical applications. Nordson differentiates through tight-tolerance gear profiles serving medical-grade extrusion segments.
A melt and gear pump is a positive-displacement rotary pump engineered to convey molten polymers, resins, or viscous fluids at controlled volumetric rates, typically operating between 200°C and 400°C with discharge pressures up to 700 bar. Its primary industrial purpose is to generate stable, pulse-free flow that eliminates screw surge in extrusion systems while optimizing energy efficiency and dimensional consistency in finished products. External gear pumps occupy the mature volume tier, serving commodity polymer lines where standardization compresses margins. Electric drive technology leads growth trajectories across food processing and paint dispensing applications, displacing hydraulic systems under energy-efficiency mandates. Internal gear pumps capture premium positioning in high-viscosity chemical transfer where NPSH constraints and shear sensitivity dictate specialized tooth geometry.
US OSHA process safety management standards and EPA emissions frameworks shape equipment specifications for chemical transfer and polymer processing installations, mandating sealed-bearing designs and leak detection integration. REACH substance restrictions and EU machinery directives from ECHA and EU institutions drive material substitution in gear coatings and housing alloys, elevating compliance costs for European-sourced equipment. Stakeholders must monitor divergence between regional efficiency standards and carbon-border adjustment mechanisms as these determine competitive access for imported pump assemblies.
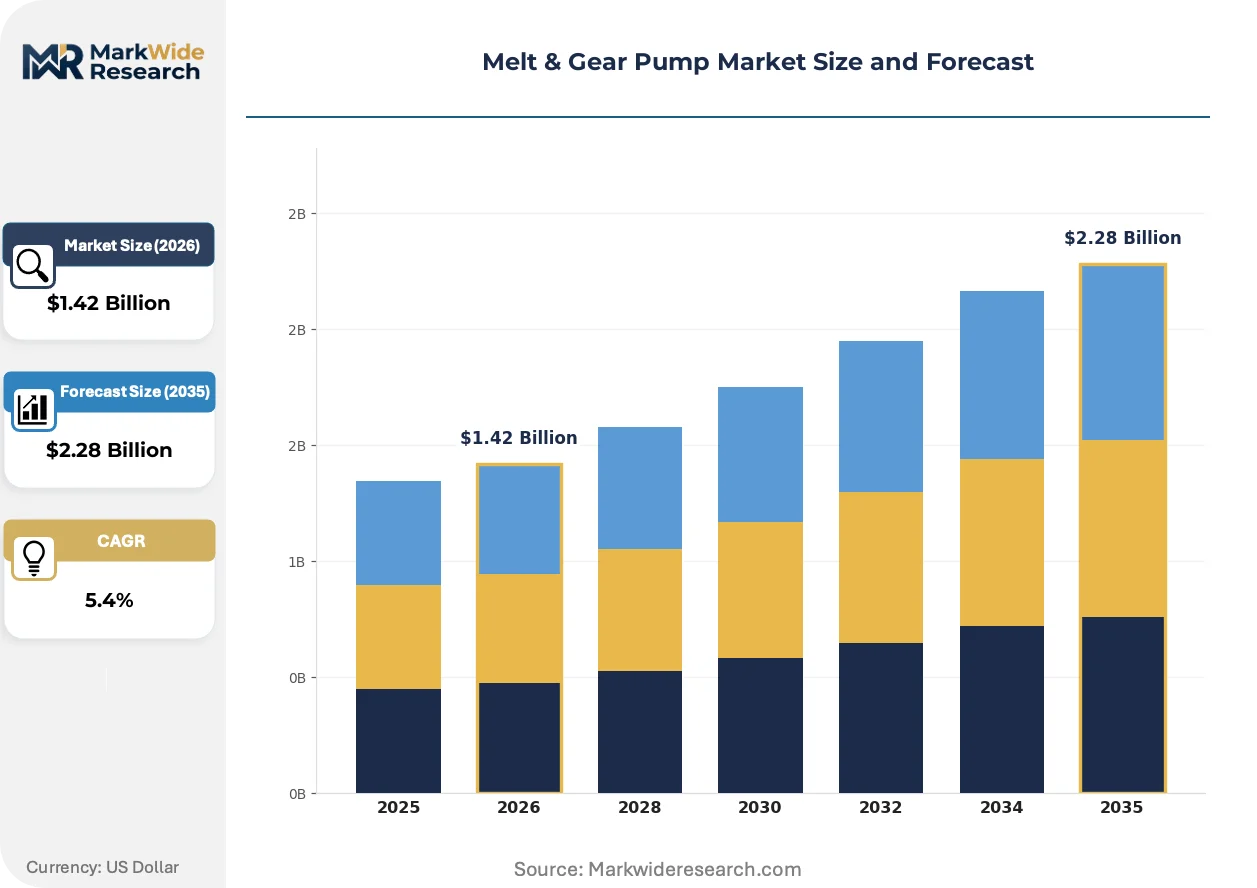
Market Dynamics
Electric drive systems are displacing hydraulic architectures across polymer extrusion lines, compressing maintenance intervals while elevating precision requirements for gear profile machining.
Growth Catalysts
- OSHA Process Safety Management:Mandates for sealed-bearing designs in high-temperature chemical transfer are accelerating specification upgrades across US petrochemical corridors.
- Medical-grade extrusion:Tight-tolerance gear profiles for catheter and tubing production are pulling precision equipment demand from FDA-regulated device manufacturers.
- China petrochemical expansion:Concentrated capacity buildouts along coastal refining clusters are generating volume-tier equipment procurement at scale.
Market Restraints
- High-temperature alloy scarcity:Specialized metallurgy for corrosive chemical applications concentrates among limited European and Japanese suppliers, creating input cost volatility.
- REACH substance restrictions:ECHA-driven material substitution in gear coatings elevates compliance costs and extends qualification timelines for European-sourced equipment.
- Standard external gear commoditization:Mature volume-tier pumps face margin compression from standardized designs with limited differentiation pathways.
Strategic Opportunities
- Food processing electrification:Energy-efficiency mandates are creating white space for electric drive pumps in thermal-sensitive ingredient handling applications.
- Carbon-border adjustment mechanisms:Emerging EU trade instruments will advantage low-carbon equipment producers serving polymer processing imports.
- Paint dispensing automation:Shear-sensitive internal gear geometries are penetrating automotive coating lines requiring precise volumetric control.
Industry Challenges
- Precision machining talent scarcity:Tight-tolerance gear profile grinding requires specialized skill sets concentrated among aging European and Japanese technician pools.
- Legacy hydraulic integration:Electric drive retrofits demand complex control system harmonization with existing extrusion line PLCs, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melt & Gear Pump Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Gear Pump, External Gear Pump, Circumferential Piston Pump, Screw Pump, Vane Pump Technology: Hydraulic Drive, Electric Drive, Pneumatic Drive, Steam-Driven, Mechanical Drive Application: Polymer Processing, Chemical Transfer, Food Processing, Paint Dispensing, Lubricant Supply, Paper Manufacturing End User: OEMs, Aftermarket Suppliers, Polymer Manufacturers, Chemical Plants, Foodstuff Producers |
| Companies Covered | Dover (PSG), Oerlikon, Nordson, WITTE, Coperion, Kawasaki Heavy Industries, Zenith Pumps, Kobelco, Maag Germany GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melt & Gear Pump Market Trends and Innovations
Three interconnected developments are compressing equipment replacement cycles while elevating performance specifications across polymer processing and chemical transfer applications.
Servo-electric drive architectures are displacing hydraulic power units in high-pressure extrusion environments. Medical device manufacturers and food packaging lines are adopting these systems to eliminate oil contamination risks and reduce energy consumption by half. The shift is compressing demand for traditional hydraulic pump-drive combinations while expanding the addressable market for precision motion control integration.
EPA emissions frameworks and EU F-Gas Regulation are converging on leak detection integration and sealed-system mandates for chemical transfer equipment. These frameworks are forcing housing alloy substitutions and elevated sealing specifications. German and US Gulf Coast chemical processors are responding with preemptive equipment upgrades ahead of enforcement phase-ins.
After-sales service unbundling is disrupting traditional OEM-captive maintenance models. Independent service providers are capturing calibration and spare parts demand through remote monitoring platforms. This pattern is most visible among North American polymer compounders seeking to reduce total cost of ownership through competitive sourcing of precision gear refurbishment.
Melt & Gear Pump Market Segmentation
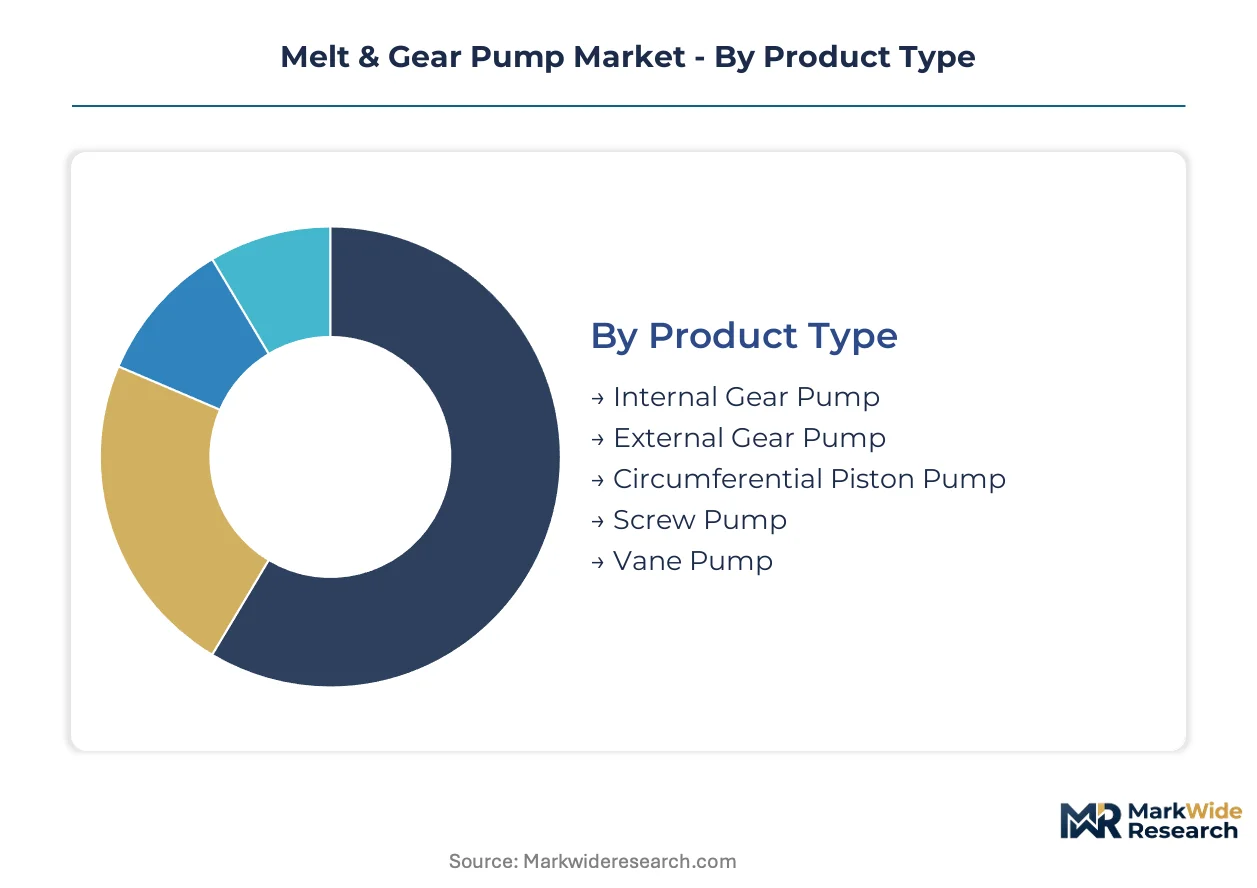
Segmentation in melt and gear pump procurement reflects divergent technical requirements across viscosity ranges, temperature envelopes, and contamination sensitivity. Equipment specification varies sharply between polymer extrusion lines demanding pulse-free flow and chemical transfer operations prioritizing corrosion resistance.
Product Type:
Margin pools concentrate in specialized geometries serving high-viscosity and shear-sensitive applications where standardization offers limited value.
- Internal Gear Pump:Crescent-shaped internal gear design with idler gear minimizes fluid shear and handles viscosities exceeding 100,000 cP. Paint dispensing lines at automotive coating plants in Stuttgart and Detroit specify these geometries for precise volumetric control of metallic finishes. REACH substance restrictions on gear coatings elevate European-sourced unit costs.
- External Gear Pump:Intermeshing external gears deliver straightforward positive displacement for commodity polymer processing. Chinese petrochemical corridors along Ningbo and Dalian deploy standardized external gear units in high-volume extrusion lines where pulse tolerance is acceptable. Electric drive retrofits are compressing hydraulic power unit demand in this tier.
- Circumferential Piston Pump:Rotor-based design handles large solids and fibrous materials without clogging.
- Screw Pump:Progressive cavity geometry manages multiphase fluids and high gas entrainment.
- Vane Pump:Sliding vane mechanism suits lower-viscosity lubricant transfer with minimal pulsation.
External gear pumps hold installed capacity across commodity polymer lines. Internal gear pumps are rotating up the share rankings in precision coating applications.
Technology:
Technology selection tracks energy-efficiency mandates and maintenance interval compression across regional regulatory frameworks.
- Electric Drive:Servo-controlled motor systems eliminate hydraulic oil contamination and reduce energy consumption by 40-50% versus conventional power units. FDA-regulated medical tubing manufacturers in Minnesota and Massachusetts mandate electric drives for catheter extrusion lines. OSHA process safety management standards accelerate specification upgrades in US Gulf Coast chemical corridors.
- Hydraulic Drive:Established power-dense architecture dominates legacy extrusion installations with established maintenance protocols. German precision engineering clusters around Stuttgart maintain hydraulic expertise for high-pressure applications exceeding 500 bar. Electric displacement is compressing new hydraulic system demand in food packaging segments.
- Pneumatic Drive:Compressed air actuation suits explosion-sensitive chemical environments with simplified spark containment.
- Steam-Driven:Direct thermal energy conversion serves integrated petrochemical complexes with captive steam supply.
- Mechanical Drive:Direct shaft coupling from extruder motors persists in cost-sensitive volume installations.
Hydraulic drive holds installed capacity across legacy polymer processing infrastructure. Electric drive is rotating up the share rankings under energy-efficiency mandates.
Application:
Application segmentation reveals divergent performance specifications between continuous extrusion and batch chemical transfer operations.
- Polymer Processing:Continuous duty cycles at 300-400°C demand thermal expansion compensation and hardened gear surfaces. Chinese coastal refining clusters in Zhejiang and Shandong provinces concentrate new capacity buildouts generating volume-tier procurement. Electric drive technology is displacing hydraulic systems under dual carbon goals.
- Chemical Transfer:Corrosive media handling requires high-temperature alloy metallurgy and sealed-bearing configurations. German chemical processors along the Rhine corridor specify nickel-based alloys for sulfuric acid service. EPA emissions frameworks mandate leak detection integration for US installations.
- Food Processing:Hygienic design with 3A sanitary certification serves thermal-sensitive ingredient handling.
- Paint Dispensing:Shear-sensitive internal gear geometries penetrate automotive coating automation lines.
- Lubricant Supply:Viscosity-stable delivery supports metalworking and turbine maintenance operations.
- Paper Manufacturing:High-consistency stock handling requires abrasion-resistant pump configurations.
Polymer processing holds installed capacity across global extrusion infrastructure. Food processing is rotating up the share rankings under electrification mandates.
End User:
End user segmentation tracks procurement authority concentration between captive OEM specifications and independent aftermarket decision-making.
- OEMs:Original equipment manufacturers specify integrated pump-drive systems for extrusion line deliveries. Nordson and Coperion anchor North American and European polymer processing demand through bundled system procurement. Tight-tolerance gear profile requirements elevate precision machining specifications.
- Aftermarket Suppliers:Independent service providers capture calibration and spare parts demand through remote monitoring platforms. North American polymer compounders in Ohio and Texas pursue competitive sourcing of gear refurbishment to reduce total cost of ownership. Precision machining talent scarcity constrains service expansion.
- Polymer Manufacturers:Captive processing operations specify equipment for in-house compounding and extrusion.
- Chemical Plants:Process operators prioritize corrosion resistance and sealed-system reliability under EPA and ECHA frameworks.
- Foodstuff Producers:Hygienic design compliance with FDA and EFSA standards drives equipment specification.
OEMs hold installed capacity across bundled system architectures. Aftermarket suppliers are rotating up the share rankings through service unbundling and remote monitoring penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Chinese petrochemical corridors exhibit extreme price elasticity for standardized external gear pumps, while German chemical processors along the Rhine demonstrate low elasticity for corrosion-resistant nickel-alloy systems. This demand-elasticity contrast shapes procurement patterns across major industrial clusters.
China
Coastal refining clusters in Zhejiang and Shandong provinces drive volume-tier procurement for polymer extrusion lines. MEE emissions standards and dual carbon goals accelerate electric drive retrofits displacing hydraulic systems. Ningbo and Dalian concentrate capacity buildouts generating standardized equipment demand at scale.
Germany
Precision engineering clusters around Stuttgart and Frankfurt sustain premium equipment procurement for medical-grade extrusion. REACH substance restrictions and EU F-Gas Regulation elevate compliance costs for gear coatings and housing alloys. The Rhine corridor chemical processors specify nickel-based alloys for sulfuric acid service applications.
United States
FDA-regulated medical tubing manufacturers in Minnesota and Massachusetts mandate electric drives for catheter extrusion lines. OSHA process safety management standards mandate sealed-bearing designs and leak detection integration across Gulf Coast petrochemical installations. Ohio and Texas polymer compounders pursue competitive aftermarket sourcing.
Japan
METI energy-efficiency directives compress maintenance intervals while elevating precision requirements for gear profile machining. Aging technician pools concentrate specialized grinding skills in Nagoya and Osaka industrial zones. High-temperature alloy metallurgy for corrosive applications remains concentrated among limited domestic suppliers.
India
BIS standards and PLI scheme incentives attract polymer processing capacity to Gujarat and Maharashtra industrial corridors. Food processing electrification creates white space for electric drive pumps in thermal-sensitive ingredient handling. Domestic fabrication capabilities expand for standard external gear units serving commodity extrusion lines.
Melt & Gear Pump Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the melt and gear pump landscape. The vendor base stratifies between precision-machining specialists commanding premium positioning and volume-scale producers competing on standardization. Three archetypes dominate: integrated pump-drive system providers, high-temperature alloy metallurgists, and tight-tolerance gear profile specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as electric drive architectures reshape procurement specifications.
Among precision-engineering specialists, Dover (PSG), Oerlikon, and Nordson occupy positions reflecting divergent technical competencies. Dover (PSG) represents the integrated system archetype anchoring North American polymer processing demand. Oerlikon exemplifies high-temperature alloy metallurgy dominance for corrosive chemical applications. Nordson sits within the tight-tolerance gear profile tier serving medical-grade extrusion segments where FDA compliance elevates machining specifications. These three companies illustrate how technical specialization, rather than scale alone, determines competitive positioning across electric drive transition cycles.
| Leading Market Players |
|---|
| Dover (PSG) |
| Oerlikon |
| Nordson |
| WITTE |
| Coperion |
| Kawasaki Heavy Industries |
| Zenith Pumps |
| Kobelco |
| Maag Germany GmbH |
| Others |
Pricing and Supply Chain Analysis
Sixteen-to-twenty-week lead times for high-temperature alloy forgings concentrate pricing power among Japanese and European metallurgical suppliers while compressing margins for volume-tier external gear pump assemblers in China. This inventory-to-delivery gap separates premium precision-machining specialists from commodity producers competing on standardization.
Pricing Analysis
After-sales service revenue streams anchor lifetime value for precision gear profile specialists serving medical-grade extrusion segments. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA-compliant tight-tolerance systems commanding substantial premiums over commodity polymer processing units. Cost compression in the standard external gear tier intensifies because Chinese petrochemical corridors drive extreme price elasticity for undifferentiated equipment. Polymer manufacturers in Ningbo and Dalian exhibit highest price sensitivity, while German chemical processors along the Rhine demonstrate lowest elasticity for corrosion-resistant nickel-alloy systems.
Supply Chain Analysis
Inbound logistics costs from European and Japanese specialty alloy suppliers fluctuate with container availability on Asia-North America trade lanes, elevating landed costs for precision-machining clusters in Minnesota and Massachusetts. High-temperature alloy metallurgy concentrates in Germany, Japan, and select European suppliers, while precision gear grinding equipment draws from Swiss and German machine tool builders. Single-source vulnerability in specialized grinding skill pools concentrated among aging Nagoya and Osaka technician zones threatens capacity expansion timelines. Distribution runs through OEM-integrated pump-drive system bundling for extrusion line deliveries, with independent aftermarket channels penetrating calibration and refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized grinding expertise and high-temperature alloy metallurgy constitute scarce capabilities that constrain expansion timelines and concentrate margin pools among incumbent precision-machining specialists.
For Market Incumbents: Compound defensive positioning through captive supply of precision gear grinding capacity and preemptive certification investment under evolving EPA emissions frameworks and REACH substance restrictions. Electric drive technology substitution threatens hydraulic system incumbents; vertical integration into servo-controlled motor systems preserves bundled system procurement relationships with FDA-regulated medical device manufacturers. For New Entrants and Emerging Players: Remote monitoring platform deployment represents a service-layer gap where incumbents under-serve North American polymer compounders seeking competitive aftermarket sourcing. Food processing electrification in thermal-sensitive ingredient handling offers the most penetrable application white space. Target calibration and spare parts demand through independent service provider positioning, leveraging precision machining talent scarcity to capture gear refurbishment revenue from Ohio and Texas compounders. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because precision-machining capability scarcity and electric drive transition cycles favor technical specialists with integrated pump-drive system expertise over volume-scale commodity producers. Acquisition targets should display tight-tolerance gear profile competencies serving medical-grade extrusion or high-temperature alloy metallurgy for corrosive chemical applications. Watch carbon-border adjustment mechanism implementation timing as the inflection signal advantaging low-carbon equipment producers serving polymer processing imports.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive System Integration | Servo-controlled architectures displace hydraulic units under OSHA process safety mandates and FDA contamination-risk protocols. |
| High-Temperature Alloy Backward Integration | Captive metallurgy for corrosive chemical applications reduces input cost volatility from limited Japanese and European supplier pools. |
| Remote Monitoring Platform Deployment | Independent service providers capture calibration demand from North American polymer compounders through competitive refurbishment sourcing. |
| Precision Machining Talent Development | Specialized grinding skill expansion in Nagoya and Osaka industrial zones addresses technician pool aging constraints. |
| Carbon-Border Adjustment Compliance | Low-carbon equipment certification positions producers for EU trade instrument advantages on polymer processing imports. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across polymer processing and chemical transfer installations; and secondary validation through customs/trade data, SEC 10-K filings, and industry association reports from ACC and Cefic. Bottom-up equipment shipment tallies and top-down end-use demand estimates were triangulated to anchor volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning pump geometry type, drive technology architecture, application viscosity range, and regional regulatory cluster intensity. CAGRs were derived from equipment replacement cycle compression analysis and electric drive penetration trajectory assessment. Forecast inputs incorporated REACH substance restriction phase-in schedules and MEE emissions standard enforcement timelines affecting specification upgrades.
Underlying assumptions cover stable high-temperature alloy supply availability and gradual electric drive retrofit adoption curves, with deviation risk concentrated in precision machining talent pool attrition rates and carbon-border adjustment mechanism implementation scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Chemical Metering Pumps Market