
 Mist Sprayer Pumps Market | 2026-2036
Mist Sprayer Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Mist Sprayer Pumps Market Foresight
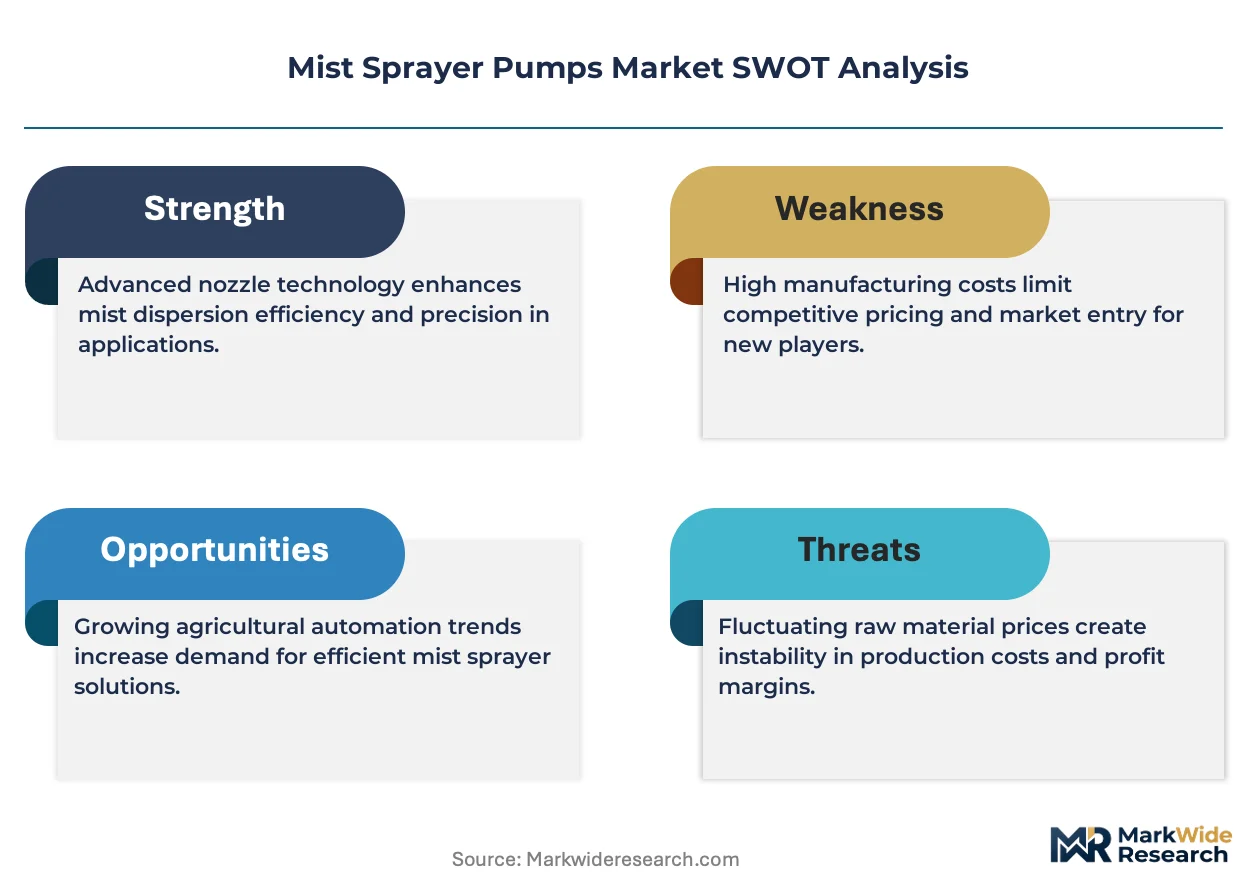
The EU Green Deal's Farm to Fork Strategy is rebalancing procurement criteria toward reduced chemical application equipment across European agricultural supply chains. Berry Global leverages its blow-molding capacity to supply large-format sprayer reservoirs for commercial vineyard operators. Silgan Dispensing anchors its position through precision valve engineering that controls droplet size distribution in sanitization applications. AptarGroup competes on spray-pattern consistency for pharmaceutical-grade misting systems used in hospital disinfection protocols.
Mist sprayer pumps are mechanical or electromechanical devices that convert liquid formulations into fine aerosol droplets through pressurized nozzles or ultrasonic vibration, typically achieving particle sizes between 20 and 100 microns for optimal surface coverage. These systems serve agricultural crop protection, public health vector control, and industrial surface sanitization by enabling targeted chemical delivery with minimized waste. Battery-powered technology leads unit growth as lithium-ion cell costs decline and farm labor shortages intensify across mature agricultural economies. Manual pressurized systems retain volume dominance in emerging markets where capital constraints limit equipment upgrades. Sanitization applications command premium pricing following permanent elevation of hygiene protocols in healthcare and food-processing facilities.
The US EPA regulates pesticide application equipment through certification requirements under the Federal Insecticide, Fungicide, and Rodenticide Act, while OSHA mandates worker exposure limits during commercial spraying operations. REACH compliance in Europe restricts certain polymer chemistries in pump components, pushing manufacturers toward validated alternative materials. India's Central Insecticides Board requires equipment registration for restricted-use chemical application, creating a compliance threshold for imported sprayer systems. Stakeholders must monitor evolving battery transport regulations and chemical compatibility standards as electrification penetrates higher-duty agricultural segments.
Market Dynamics
Battery-powered sprayer technology is compressing replacement cycles for manual pump systems as lithium-ion cell costs decline and plantation operators in Southeast Asia face acute labor shortages.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Procurement criteria across European agricultural supply chains now prioritize reduced chemical application equipment, redirecting capital toward precision spraying systems.
- Brazilian agricultural cooperatives:Large-scale precision spraying deployments in Mato Grosso and São Paulo states are cutting chemical runoff while satisfying export market sustainability audits.
- Ultrasonic vibration nozzles:Droplet size control down to 20-micron precision is expanding addressable applications from crop protection into pharmaceutical-grade sanitization protocols.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in China create input vulnerability for electrified sprayer manufacturers outside East Asia.
- REACH polymer restrictions:ECHA limitations on certain elastomer chemistries in pump seals force costly material revalidation cycles for European component suppliers.
- Manual system persistence:Capital constraints across smallholder operations in Sub-Saharan Africa and South Asia delay upgrade timelines despite total cost of ownership advantages for battery-powered alternatives.
Strategic Opportunities
- Maharashtra state horticulture:Grape and pomegranate growers facing 15-20% annual labor cost inflation represent concentrated demand for automated spraying solutions in India's western agricultural belt.
- Healthcare permanent hygiene elevation:Post-pandemic hospital disinfection protocols in North America and Western Europe sustain premium pricing for validated misting systems with documented droplet consistency.
- Indonesian palm oil plantation electrification:Battery-powered backpack sprayers are penetrating previously manual-dependent estates as Jakarta implements worker safety regulations limiting chemical exposure hours.
Industry Challenges
- Cross-border battery transport compliance:UN 38.3 lithium-ion shipping certifications and evolving IATA dangerous goods rules complicate inventory positioning for manufacturers serving distributed agricultural markets.
- Chemical compatibility validation:Formulation-specific seal and reservoir testing under EPA FIFRA and India's Central Insecticides Board requirements extends new product introduction timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mist Sprayer Pumps Market |
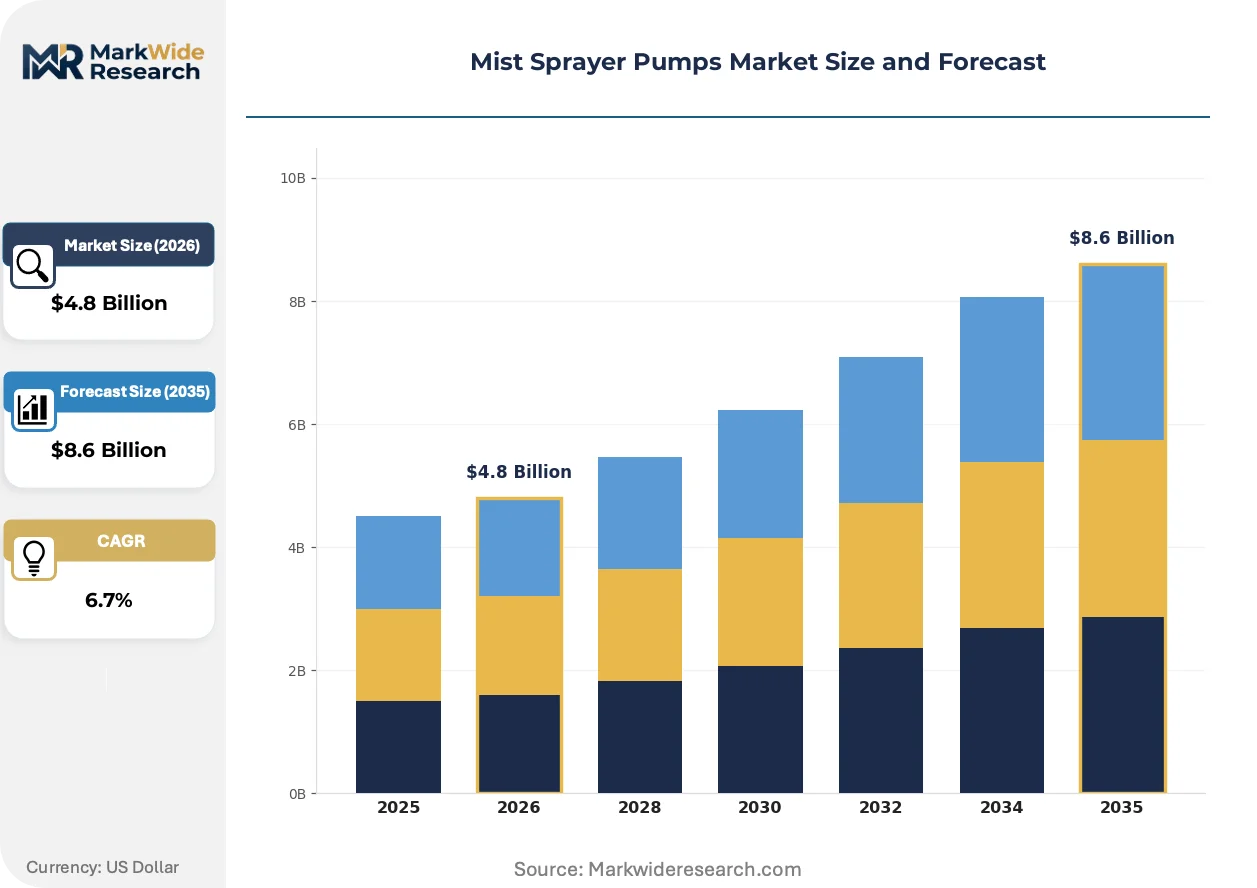
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Sprayers, Handheld Sprayers, Backpack Sprayers, Tractors Application: Agricultural Use, Pest Control, Sanitization, Landscape Maintenance End User: Farmers, Landscaping Companies, Hospitals, Pest Control Services Technology: Electrical, Battery-Powered, Manual, Pressurized |
| Companies Covered | Frapak Packaging, Berry Global, Silgan Dispensing, Raepak, RPC Group, AptarGroup, Rieke Packaging, Z&Z Sprayer, Albéa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mist Sprayer Pumps Market Shifts & Advancements
Electromechanical spraying systems are absorbing functionality from adjacent precision agriculture equipment categories, compressing the boundary between standalone pumps and integrated crop management platforms.
Ultrasonic atomization modules are converging with GPS-guided autonomous ground vehicles in commercial vineyard operations across California's Central Valley and France's Bordeaux region. Large-format estate managers are retrofitting existing tractor fleets with precision boom attachments rather than purchasing dedicated self-propelled sprayers. This convergence is collapsing the addressable market for conventional high-volume hydraulic sprayers while expanding serviceable obtainable market for component suppliers with valve engineering expertise.
REACH authorization requirements for persistent organic pollutants in polymer formulations are forcing seal manufacturers toward fluoropolymer alternatives with shorter field-proven histories. European component suppliers bear the primary compliance burden, with ECHA registration dossiers requiring 18-24 month preparation cycles. Agricultural OEMs are responding by dual-sourcing critical elastomer components from validated Asian suppliers with existing REACH registrations.
Cooperative procurement consortia in Brazil and Argentina are consolidating equipment purchasing decisions previously fragmented across individual farm managers. These buying groups now specify multi-year service contracts bundling hardware, calibration, and chemical compatibility testing. The channel shift is most pronounced in Rio Grande do Sul soybean operations, where cooperatives command 60-70% of precision agriculture capital expenditure approvals.
Mist Sprayer Pumps Market Segmentation
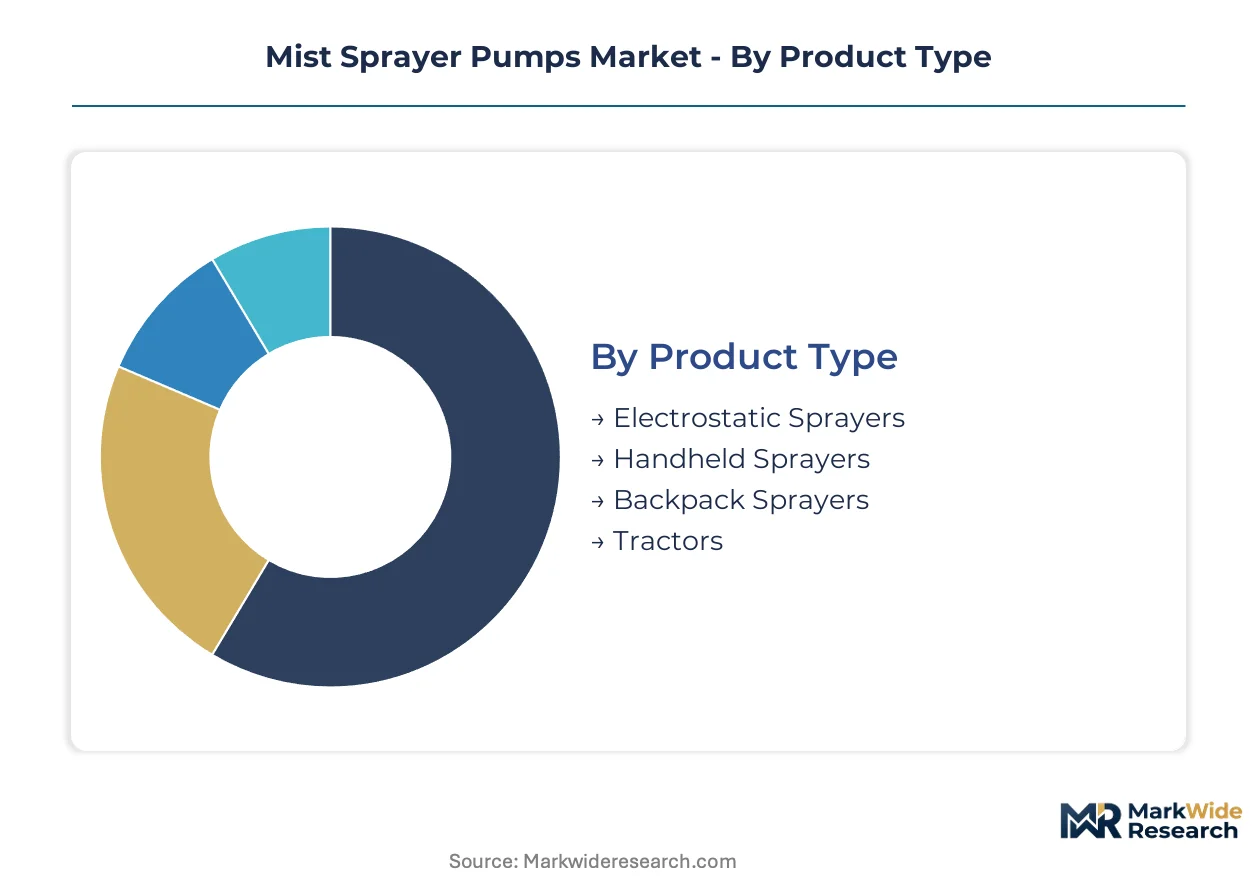
Segmentation in mist sprayer pumps reveals how technology choice, application intensity, and operator scale fragment procurement behavior across agricultural, healthcare, and commercial maintenance verticals. Equipment specifications diverge sharply between chemical-intensive crop protection and precision-controlled sanitization protocols.
Product Type:
Buyers differentiate primarily by mobility requirements and treatment area scale, with estate size dictating whether operators prioritize portability or throughput capacity.
- Backpack Sprayers:These portable electromechanical systems mount 15-20 liter reservoirs on operator frames, enabling maneuverability through dense row crops and greenhouse corridors. Demand concentrates in Indonesian palm oil estates and Brazilian citrus cooperatives where Jakarta's worker safety regulations limit chemical exposure hours. Labor shortages across Southeast Asian plantation operations accelerate displacement of manual alternatives.
- Handheld Sprayers:Compact units under 5 liters serve spot-treatment applications requiring precision targeting of individual plants or surface zones. Maharashtra's grape and pomegranate growers facing acute labor cost inflation deploy these for targeted fungicide application in trellised vineyards. Battery-powered variants are compressing replacement cycles as lithium-ion cell costs decline.
- Electrostatic Sprayers:Charged-droplet systems achieve wraparound coverage on complex geometries through electrostatic attraction between particles and target surfaces.
- Tractors:Self-propelled or pull-behind boom systems deliver high-volume application across extensive field operations.
Volume sits with backpack configurations; growth tilts toward handheld electrified units.
Application:
Regulatory intensity and chemical formulation sophistication separate applications into commodity crop protection versus protocol-driven sanitization segments with diverging margin structures.
- Agricultural Use:Crop protection applications dominate unit shipments through seasonal demand cycles tied to planting and harvest calendars. Brazil's Mato Grosso soybean belt and São Paulo sugarcane regions drive precision spraying adoption as export market sustainability audits intensify scrutiny of chemical runoff metrics. EU Green Deal procurement criteria redirect European supply chain capital toward reduced-application equipment.
- Sanitization:Hospital-grade disinfection protocols demand validated droplet consistency documentation for EPA FIFRA compliance and OSHA worker exposure limits. North American and Western European healthcare facilities sustain premium pricing for pharmaceutical-grade misting systems with 20-micron precision control. Post-pandemic permanent hygiene elevation created durable demand elevation independent of seasonal patterns.
- Pest Control:Vector management applications target mosquito and rodent populations through public health agency contracts.
- Landscape Maintenance:Commercial groundskeeping and municipal park operations require broad-area herbicide and fertilizer distribution.
Revenue concentrates in agricultural channels; margin expansion favors sanitization applications.
End User:
Capital availability and technical sophistication stratify end users from price-sensitive smallholders to specification-driven institutional procurement departments.
- Farmers:Individual operators and cooperative members represent the volume foundation, with Brazilian agricultural cooperatives in Rio Grande do Sul consolidating previously fragmented purchasing decisions. These buying groups now specify multi-year service contracts bundling hardware, calibration, and chemical compatibility testing under Central Insecticides Board requirements.
- Hospitals:Infection control departments operate under Joint Commission protocols and OSHA mandates, requiring documented spray-pattern consistency for terminal cleaning validation. Procurement committees prioritize REACH-compliant component traceability and EPA-registered equipment certification over upfront cost minimization.
- Landscaping Companies:Commercial maintenance contractors balance equipment durability against seasonal utilization rates.
- Pest Control Services:Licensed applicators face state-level certification requirements under FIFRA that influence equipment selection.
Unit volume flows through farmer channels; specification intensity peaks with hospital procurement.
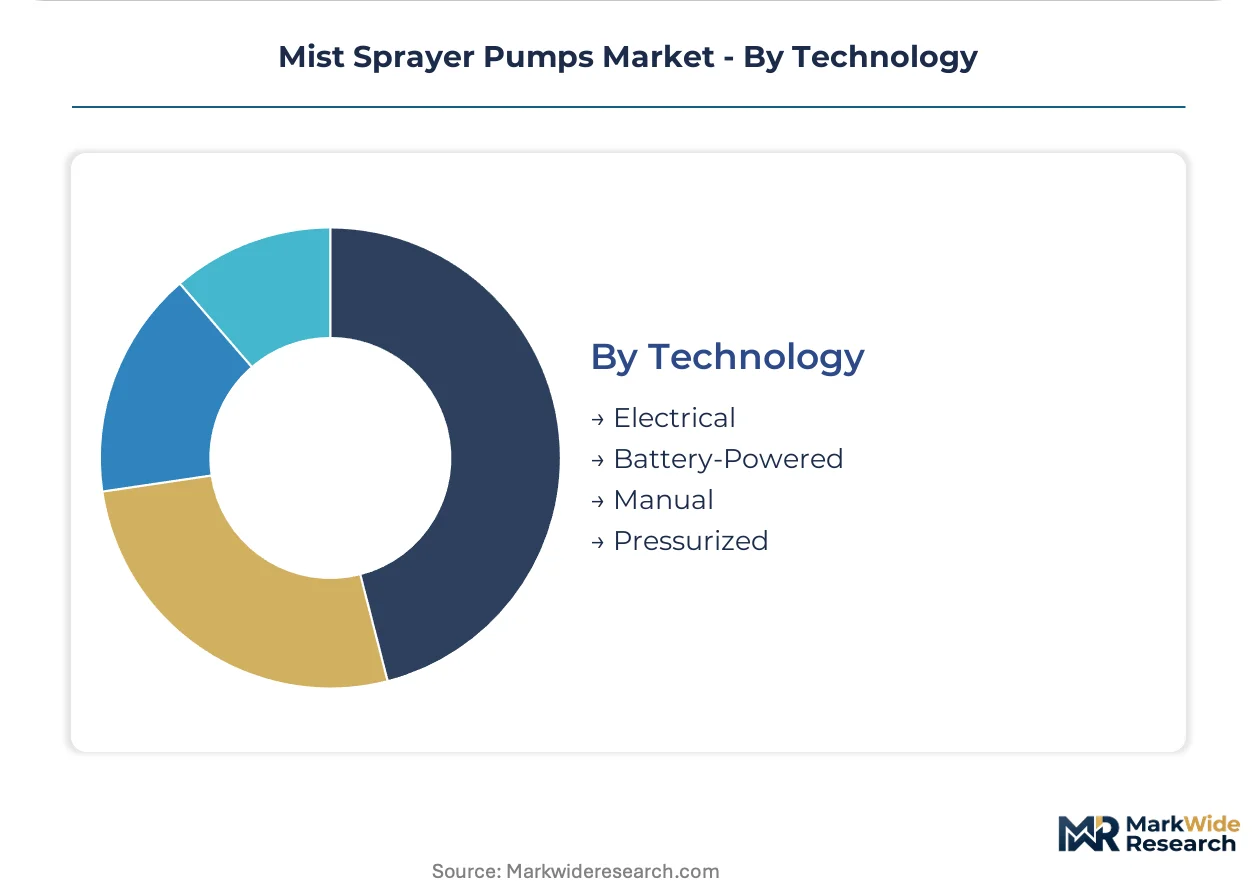
Technology:
Power source selection reflects capital constraints against labor cost trajectories, with electrification penetration varying by regional energy infrastructure and wage pressure intensity.
- Battery-Powered:Lithium-ion cell cost declines enable 4-6 hour continuous operation from backpack and handheld form factors. Southeast Asian plantation operators facing acute labor shortages adopt these systems to reduce operator fatigue and improve application consistency. UN 38.3 shipping certifications and evolving IATA dangerous goods rules complicate inventory positioning for manufacturers.
- Manual:Hand-pump systems retain dominance in Sub-Saharan African and South Asian smallholder operations where capital constraints delay upgrade timelines despite total cost of ownership disadvantages. Persistence of these systems in price-sensitive segments constrains average selling price progression for market incumbents.
- Electrical:Corded systems serve fixed-location applications with reliable grid access.
- Pressurized:Compressed air or CO2 propulsion delivers consistent flow rates for specialized formulations.
Shipment volume remains with manual systems; technology transition accelerates fastest toward battery-powered alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian component hubs while consumption concentrates in agricultural belts facing labor cost pressure. Battery cell supply chains create input dependency for electrification transitions outside China. Regulatory divergence across jurisdictions fragments compliance architectures for multinational equipment suppliers.
Brazil
Agricultural cooperatives in Mato Grosso and São Paulo states drive precision spraying procurement as export sustainability audits intensify chemical runoff scrutiny. ANVISA registration requirements for pesticide application equipment create compliance thresholds for imported systems. Rio Grande do Sul soybean operations channel 60-70% of precision agriculture capital expenditure through cooperative buying groups.
United States
California Central Valley vineyard operators retrofit existing tractor fleets with GPS-guided precision boom attachments rather than purchasing dedicated self-propelled sprayers. EPA FIFRA certification requirements govern pesticide application equipment standards. OSHA mandates on worker exposure limits during commercial spraying operations shape equipment specification protocols in hospital disinfection segments.
India
Maharashtra state grape and pomegranate growers facing 15-20% annual labor cost inflation represent concentrated demand for automated spraying solutions. The Central Insecticides Board requires equipment registration for restricted-use chemical application, extending new product introduction timelines. Western agricultural belt procurement concentrates in Pune and Nashik district cooperative networks.
Germany
ECHA REACH restrictions on certain elastomer chemistries in pump seals force material revalidation cycles for European component suppliers. The EU Green Deal Farm to Fork Strategy redirects supply chain capital toward reduced chemical application equipment. Bavarian and Baden-Württemberg agricultural machinery clusters anchor precision valve engineering for sanitization applications.
Indonesia
Jakarta's worker safety regulations limiting chemical exposure hours accelerate battery-powered backpack sprayer penetration in palm oil estates. Labor shortages across Sumatran and Kalimantan plantation operations compress replacement cycles for manual pump systems. Battery transport compliance under evolving IATA dangerous goods rules complicates inventory positioning for equipment distributors.
Mist Sprayer Pumps Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with blow-molding and valve engineering capabilities. Tier-one suppliers leverage polymer formulation expertise and regulatory compliance infrastructure to capture specification-driven healthcare and agricultural procurement. Three archetypes dominate: precision valve specialists, large-format reservoir fabricators, and integrated dispensing system providers. Capacity expansion in Asian manufacturing hubs and strategic partnerships for chemical compatibility testing represent the dominant competitive vectors.
Among diversified packaging groups, Berry Global exemplifies the large-format reservoir fabrication archetype through blow-molding capacity deployment. Silgan Dispensing occupies a position within precision valve engineering tiers, while AptarGroup anchors the spray-pattern consistency segment for pharmaceutical-grade applications. Frapak Packaging, Raepak, and Rieke Packaging represent European and North American component supply positions. Z&Z Sprayer exemplifies specialized sprayer system fabrication. Albéa sits within the integrated dispensing solutions tier alongside RPC Group.
| Leading Market Players |
|---|
| Frapak Packaging |
| Berry Global |
| Silgan Dispensing |
| Raepak |
| RPC Group |
| AptarGroup |
| Rieke Packaging |
| Z&Z Sprayer |
| Albéa |
| Others |
Supply & Pricing Matrix
Lithium-ion cell costs cascade through battery-powered sprayer tiers from East Asian production clusters to Maharashtra grape growers and Indonesian palm oil estates, with REACH-compliant fluoropolymer seals commanding premium positioning against standard elastomer alternatives.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for precision spraying systems, with droplet consistency documentation supporting premium tiers in hospital sanitization protocols. Three-tier pricing structure separates pharmaceutical-grade misting systems with EPA FIFRA validation from standard agricultural equipment and economy manual pump alternatives. Cost compression in economy tiers intensifies because Chinese battery cell oversupply feeds component price erosion. Smallholder cooperatives in Sub-Saharan Africa exhibit highest price sensitivity, while North American hospital infection control departments prioritize REACH traceability over upfront cost minimization.
Supply Chain Analysis
Refurbishment flows for lithium-ion backpack sprayers are emerging through Indonesian plantation operator networks and Brazilian cooperative service contracts, extending asset life cycles. Manufacturing concentrates in China, South Korea, and Vietnam, with precision valve engineering anchored in German and Swiss component clusters. Supply chains draw from lithium carbonate, fluoropolymer elastomers, and blow-molded polymer resins. Single-source vulnerability concentrates in Chinese battery cell production. Distribution runs through agricultural cooperative consortia in Brazil and India alongside healthcare GPO contracts in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoropolymer seal capacity constraints prop pricing power for REACH-compliant component suppliers, with ECHA registration dossier backlogs limiting qualified supplier expansion.
For Market Incumbents: Anchor market position through captive lithium-ion cell sourcing partnerships and dual-sourcing validation of fluoropolymer seal alternatives. Battery transport compliance infrastructure and Central Insecticides Board registration dossiers create defensive moats against emerging Asian component suppliers lacking regulatory documentation depth. For New Entrants and Emerging Players: Sub-Saharan African smallholder cooperatives represent an underserved buyer archetype with unmet demand for pay-per-use spraying services rather than capital equipment ownership. Indonesian palm oil estate electrification mandates offer the most penetrable application segment. Go-to-market through Jakarta-based equipment leasing platforms with bundled chemical compatibility testing accelerates adoption without upfront capital barriers. For Investors and Strategic Acquirers: Brazilian cooperative consolidation into multi-year service contracts is the leading indicator that recurring revenue models are displacing transactional equipment sales. Long-term viability favors component suppliers with valve engineering expertise over standalone sprayer assemblers. Acquisition targets should demonstrate existing REACH registrations and EPA FIFRA certification infrastructure. Monitor ECHA authorization timelines for persistent organic pollutant replacements as inflection signals for material cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Ion Cell Supply | Captive battery sourcing insulates manufacturers from Chinese production concentration risks under evolving IATA rules. |
| REACH-Compliant Fluoropolymer Seal Validation | ECHA registration dossiers create 18-24 month competitive moats for European component suppliers. |
| Multi-Year Service Contract Bundling | Brazilian cooperative procurement consortia in Rio Grande do Sul now specify hardware-calibration-testing packages. |
| GPS-Guided Autonomous Boom Integration | California vineyard operators retrofit existing tractors, collapsing demand for dedicated self-propelled sprayers. |
| Chemical Compatibility Testing Infrastructure | Central Insecticides Board requirements extend new product introductions by 8-14 months, favoring incumbent laboratories. |
Research Methodology
Multi-period observation of lithium-ion cell cost trajectories, cooperative procurement consolidation patterns, and ECHA registration timelines anchored the trend analysis, supplemented by interviews with precision agriculture equipment procurement managers, hospital infection control directors, fluoropolymer seal manufacturers, Indonesian plantation operations supervisors, and Brazilian cooperative technical advisors. Secondary validation drew from EPA FIFRA certification databases, REACH authorization dossiers, Indian Central Insecticides Board registration records, and Southeast Asian customs trade data. Bottom-up shipment modeling and top-down agricultural machinery expenditure triangulation cross-verified volume estimates.
Input-output matrices mapped battery cell costs to equipment pricing tiers, droplet precision specifications to sanitization application premiums, and cooperative buying power to service contract penetration across segmentation dimensions including power source technology, application intensity, and end-user capital availability. CAGRs were derived from fitted growth curves against observed replacement cycle compression and labor cost inflation trajectories. Forecast inputs incorporated Jakarta worker safety regulation implementation timelines and EU Green Deal procurement criteria adoption rates.
Revisions become necessary when lithium-ion supply chain disruptions, ECHA polymer authorization reversals, or cooperative procurement centralization accelerations materialize outside modeled parameters. Forecasts reflect documented assumptions on battery cost decline trajectories and regulatory compliance burden stability. Practitioners should monitor IATA dangerous goods rule evolutions and Brazilian export sustainability audit intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Hydraulic Pumps Market