
 Nanosatellite Market | 2026-2036
Nanosatellite Market Size, Share, and Industry Trends Forecast 2026-2036
Nanosatellite Market Intelligence
ISO 19683 qualification for nanosatellite mechanical and environmental testing is rotating the competitive field toward vendors with certified cleanroom and vibration-test infrastructure. Planet Labs leverages its vertically integrated satellite manufacturing in San Francisco to sustain rapid constellation refresh cycles. GomSpace anchors European supply through its Aalborg facility, while ICEYE competes on synthetic-aperture radar miniaturization for all-weather imaging.
A nanosatellite is a spacecraft with mass between 1 kg and 10 kg, typically built on standardized Cubesat form factors (1U, 3U, 6U, 12U) using commercial off-the-shelf electronics, aluminum 6061-T6 frames, and body-mounted or deployable solar arrays; its primary purpose is to deliver targeted orbital services at cost points one to two orders of magnitude below traditional satellites. Cubesats dominate production volume due to university and government heritage, but Earth Observation applications generate the strongest margin pools as operators sell subscription-based analytics to agriculture and insurance clients. Propulsion Systems represent the fastest-evolving technology segment as constellation operators seek orbit-raising and deorbit capability to comply with debris rules.
FAA Office of Commercial Space Transportation governs U.S. launch licensing, while FCC Part 25 and Part 87 rules govern spectrum and station authorization for nanosatellite operators; in parallel, ESA and national European agencies enforce debris mitigation guidelines that shape spacecraft design requirements. China's MIIT and SAMR administer radio frequency licensing and product quality certification for domestic constellation ventures. Stakeholders must monitor evolving orbital slot coordination protocols and spectrum auction schedules to time capital deployment and partnership strategies.
Market Dynamics
Constellation operators are compressing refresh cycles from five years to eighteen months, forcing vendors to restructure manufacturing workflows around modular subsystems and automated test sequences rather than bespoke satellite builds.
Growth Catalysts
- FCC Part 25 streamlining:The United States regulator has reduced station authorization timelines for small satellites under 180 kg, accelerating constellation deployment schedules for commercial Earth observation ventures.
- Synthetic-aperture radar miniaturization:All-weather imaging payloads now fit 6U form factors, opening subscription analytics to agriculture and maritime insurance underwriters previously locked out by optical limitations.
- China:Domestic launch cost reductions through Long March rocket reusability programs are enabling MIIT-licensed operators to field national Earth observation networks without foreign launch dependence.
Market Restraints
- Aluminum 6061-T6 supply volatility:Aerospace-grade frame stock faces price swings tied to energy-intensive smelting constraints in primary production regions.
- Cleanroom infrastructure scarcity:ISO 19683-qualified vibration and thermal-vacuum test facilities concentrate in Denmark, the United States, and Japan, creating qualification bottlenecks for new entrants.
- Deorbit propulsion mandates:ESA debris mitigation guidelines now require active deorbit capability for LEO spacecraft above 400 km altitude, adding mass and complexity to nominally disposable platforms.
Strategic Opportunities
- India:ISRO's commercial arm has opened PSLV slots to foreign nanosatellite rideshare at price points below Falcon 9 alternatives, positioning the country as a launch arbitrage hub for European university missions.
- Internet of Things backhaul:Narrowband satellite-to-sensor links for remote asset monitoring represent an underexploited application vertical beyond imagery and communications.
- Green propulsion incentives:The EU Green Deal's space sector funding prioritizes non-toxic thruster development, rewarding iodine and water-electrolysis propulsion architectures over traditional hydrazine systems.
Industry Challenges
- Embedded systems firmware certification:DO-178C and ECSS-E-ST-40C software assurance standards impose 12-18 month validation timelines on flight computer updates, clashing with rapid constellation refresh cycles.
- RF spectrum coordination complexity:ITU filing procedures for non-geostationary constellations require advance publication of full operational parameters, locking engineering specifications before final payload design freeze.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanosatellite Market |
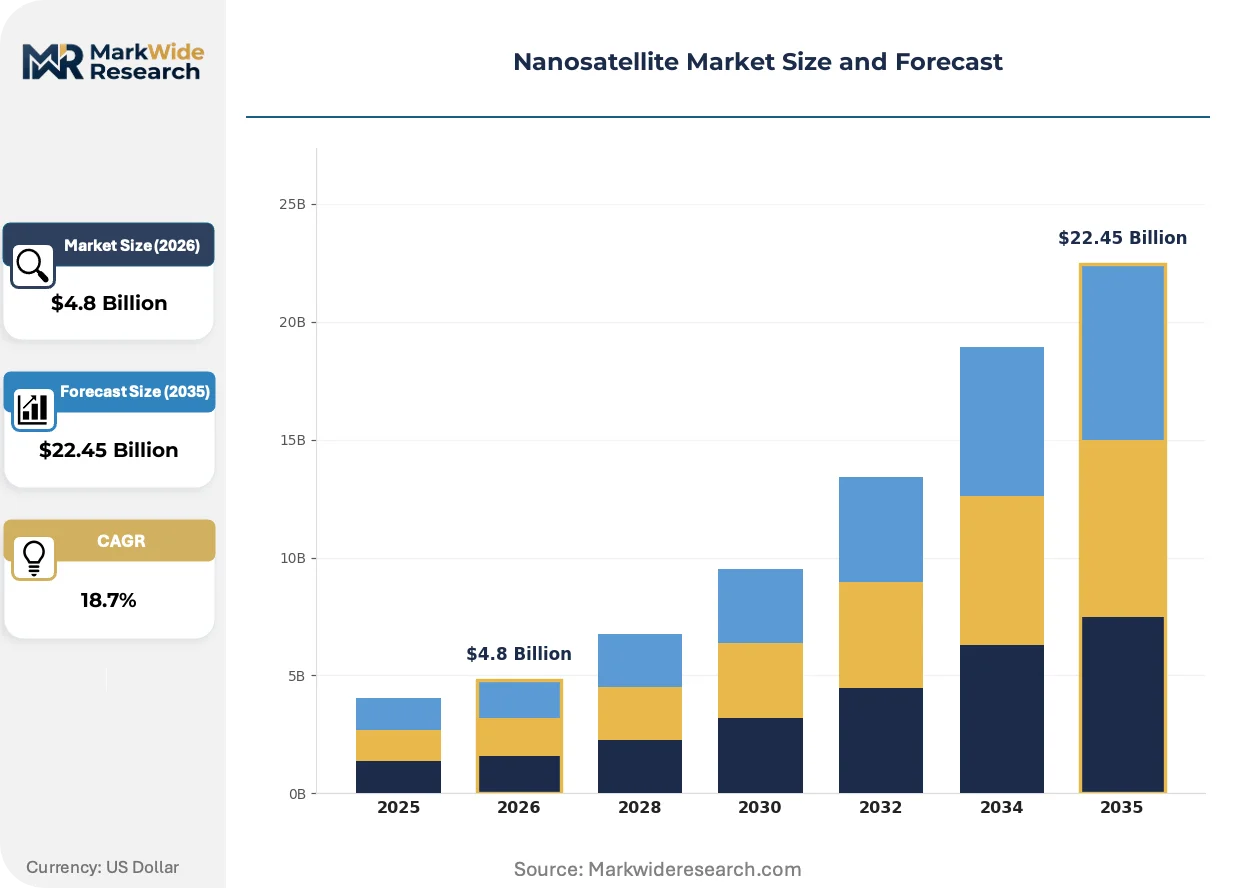
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cubesats, Picosats, Nanosatellites, Microsatellites End User: Government, Commercial, Educational Institutions, Research Organizations Application: Earth Observation, Telecommunications, Data Relay, Scientific Research Technology: Propulsion Systems, Communication Systems, Power Systems, Sensors |
| Companies Covered | Axelspace Corporation, Raytheon Technologies, Planet Labs, Astrocast, ConstellR, GomSpace, ICEYE, GalaxySpace, NanoAvionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanosatellite Market Strategic Shifts & Innovations
Standardized mechanical interfaces and commercial off-the-shelf component ecosystems are dissolving the boundary between university CubeSat heritage and professional-grade Earth observation platforms.
Electric propulsion is fragmenting the propulsion supplier landscape. Iodine-fueled resistojets and Hall-effect thrusters now deliver 100-300 mN thrust in sub-2 kg packages. Constellation operators in the United States and Japan are retrofitting orbit-raising capability into 3U buses previously limited to drag-based deorbit. This technology is fragmenting procurement patterns as operators bypass traditional chemical thruster vendors for venture-backed electric alternatives.
REACH restrictions on persistent organic pollutants are reshaping spacecraft materials selection. ESA's adoption of EU chemical regulations for agency-funded missions now bars certain conformal coatings and solder fluxes from flight hardware. European prime contractors are qualifying alternative material sets, with qualification costs concentrated in Germany and France where national space agency procurement rules apply.
Subscription-based analytics contracts are displacing raw imagery resale. Agriculture technology buyers in the United States now demand processed yield-forecasting outputs rather than multispectral raster files. This compression of the value chain is visible most acutely in the American Midwest, where crop insurance underwriters have consolidated purchasing around three dominant analytics platforms.
Nanosatellite Market Segmentation
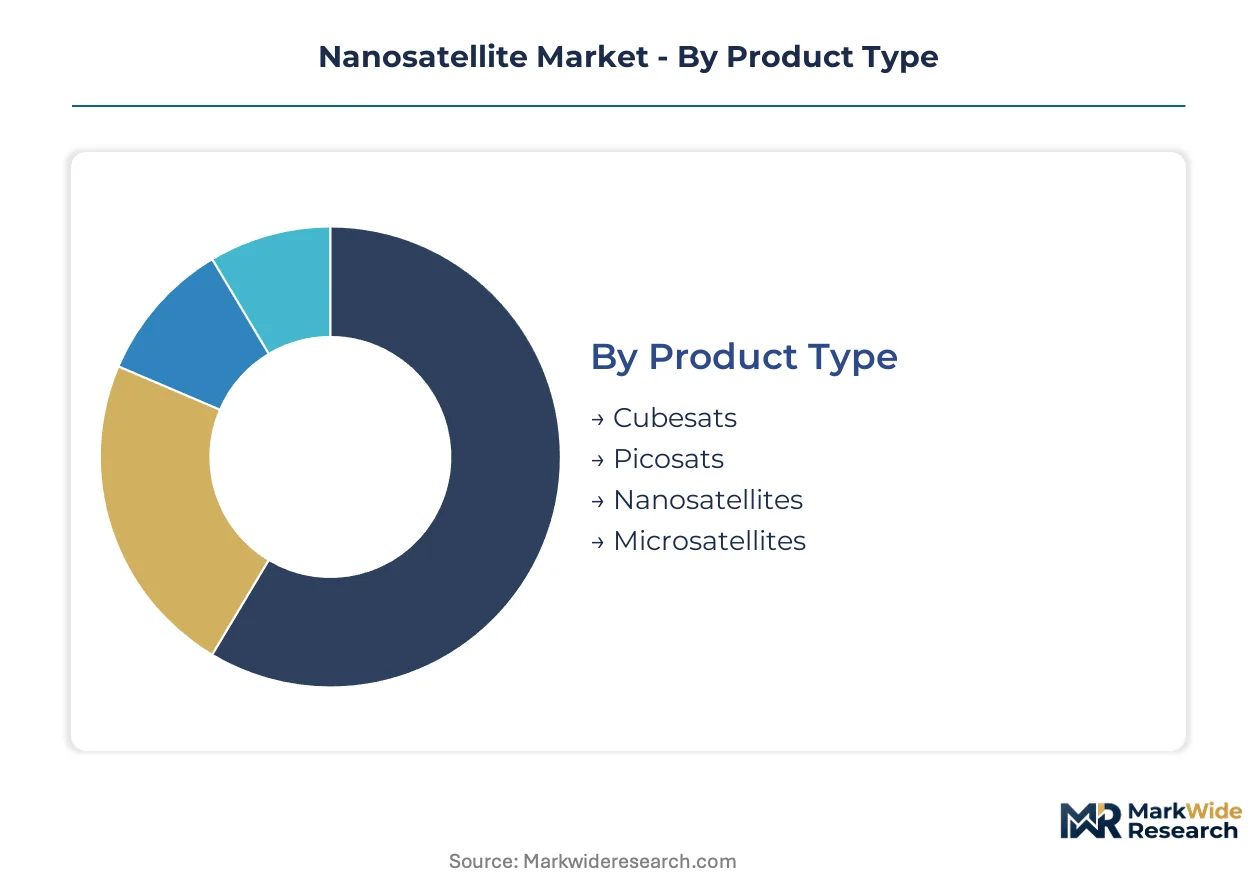
Segmentation in the nanosatellite market reveals how procurement channels, qualification requirements, and application economics reshape vendor strategies. Each dimension exposes distinct margin structures and capital deployment patterns that operators must navigate.
Product Type:
Cubesats flow through rideshare launch aggregators and university procurement offices, while larger form factors reach constellation operators through direct prime contractor relationships.
- Cubesats:Standardized 1U-12U aluminum frames built on commercial off-the-shelf electronics dominate university heritage missions and technology demonstration flights. Demand concentrates in American and Japanese educational institutions seeking rapid orbital access without bespoke engineering.
- Microsatellites:10-100 kg platforms accommodate deployable synthetic-aperture radar and propulsion subsystems for commercial Earth observation networks. Operators in China and the United States favor this class for revenue-generating constellations requiring station-keeping capability.
- Picosats:Sub-1 kg platforms serve limited-duration sensor validation missions with minimal power budgets.
- Nanosatellites:The 1-10 kg category bridges Cubesat standardization with professional-grade subsystem integration for government research contracts.
Cubesats dominate installed base. Microsatellites are where expansion concentrates.
End User:
Customer type determines contract structure, with government buyers demanding ISO 19683 qualification and commercial operators prioritizing refresh cycle velocity over heritage documentation.
- Commercial:Earth observation ventures and telecommunications constellation operators purchase on subscription revenue timelines, compressing satellite refresh cycles to eighteen months. FCC Part 25 streamlining in the United States accelerates their deployment schedules.
- Government:National space agencies and defense departments fund technology demonstration and signals intelligence missions requiring full ECSS-E-ST-40C software assurance. Procurement concentrates in the United States, China, and Japan as sovereign capability investments.
- Educational Institutions:University programs leverage Cubesat heritage for workforce development and orbital access democratization.
- Research Organizations:Climate and astronomy consortia commission specialized sensor platforms with extended operational lifetimes.
Government buyers anchor qualification infrastructure investment. Commercial operators are expanding most quickly.
Application:
Application segmentation separates raw data resale from processed analytics, with value chain compression most visible in agriculture and insurance verticals.
- Earth Observation:Multispectral and synthetic-aperture radar payloads generate subscription-based analytics for agriculture yield forecasting and maritime risk assessment. American crop insurance underwriters have consolidated purchasing around dominant analytics platforms.
- Telecommunications:Narrowband Internet of Things backhaul for remote asset monitoring represents an underexploited vertical beyond traditional communications.
- Data Relay:Store-and-forward networks serve polar and oceanic regions lacking terrestrial infrastructure.
- Scientific Research:Space weather and climate monitoring missions require specialized sensor calibration and extended operational timelines.
Earth Observation commands premium pricing. Telecommunications is climbing the fastest.
Technology:
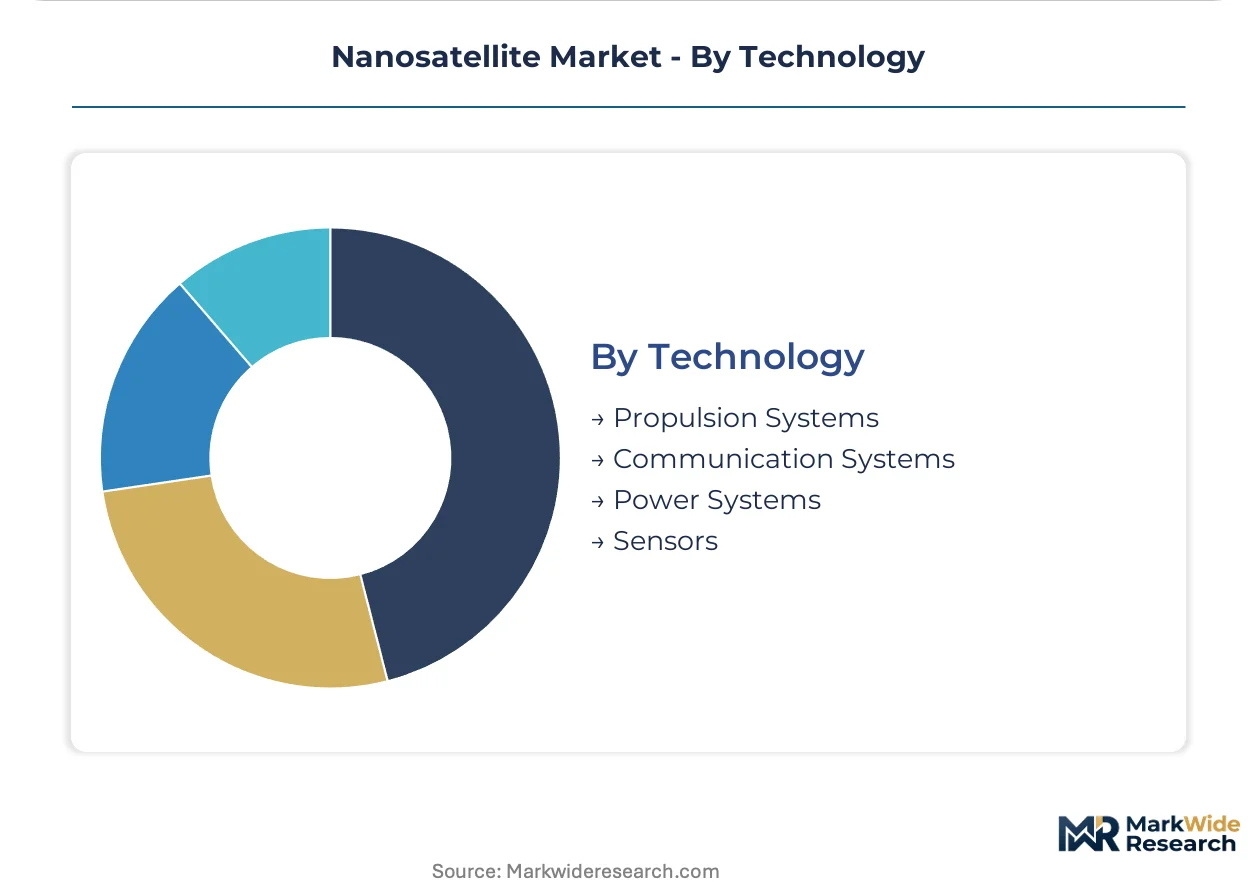
Technology segmentation tracks how subsystem miniaturization and green propulsion incentives reshape vendor procurement patterns across geographies.
- Propulsion Systems:Iodine-fueled resistojets and Hall-effect thrusters deliver 100-300 mN thrust in sub-2 kg packages for orbit-raising and deorbit compliance. ESA debris mitigation guidelines and EU Green Deal funding accelerate adoption over hydrazine alternatives.
- Sensors:Miniaturized synthetic-aperture radar now fits 6U form factors, opening all-weather imaging to agriculture and maritime insurance underwriters previously locked out by optical limitations.
- Communication Systems:Software-defined radios and inter-satellite laser links enable constellation mesh networking.
- Power Systems:Body-mounted and deployable solar arrays with lithium-ion energy storage support extended mission durations.
Propulsion Systems absorb disproportionate R&D investment. Sensors capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial Earth observation operators concentrate procurement in the United States, China, and Japan, while launch services arbitrage draws European university missions toward Indian rideshare slots.
United States
FCC Part 25 streamlining accelerates station authorization timelines for small satellites under 180 kg, compressing constellation deployment schedules. FAA Office of Commercial Space Transportation governs launch licensing with evolving orbital debris mitigation requirements. San Francisco anchors vertically integrated manufacturing clusters where rapid refresh cycles dominate procurement patterns.
China
Domestic launch cost reductions through Long March rocket reusability programs enable MIIT-licensed operators to field national Earth observation networks. SAMR administers product quality certification alongside radio frequency licensing for constellation ventures. Beijing-Tianjin-Hebei corridor concentrates state-funded spacecraft assembly capacity for sovereign capability investments.
Japan
METI-funded technology demonstration missions sustain demand for 1U-3U Cubesat platforms with extended operational lifetimes. National space agency procurement rules enforce ECSS-E-ST-40C software assurance standards on flight computer updates. Tokyo-Yokohama metropolitan area hosts precision component suppliers serving regional constellation operators.
India
ISRO's commercial arm opens PSLV rideshare slots to foreign nanosatellite missions at price points below Falcon 9 alternatives. The country's national space regulator coordinates spectrum allocation for non-geostationary constellations through advance publication protocols. Sriharikota launch complex positions the subcontinent as an arbitrage hub for European university technology demonstration flights.
Germany
EU Green Deal space sector funding prioritizes non-toxic thruster development through iodine and water-electrolysis propulsion architectures. ESA debris mitigation guidelines shape spacecraft design requirements for agency-funded missions. Bavaria and Baden-Württemberg concentrate qualification infrastructure for REACH-compliant material sets alternative to restricted conformal coatings.
Nanosatellite Market Key Industry Players
Player mix skews toward vertically integrated constellation operators and specialized subsystem vendors. Tiered competition separates premium-tier vendors with ISO 19683-qualified cleanroom infrastructure from volume producers serving university procurement offices. Dominant strategic archetypes include rapid-refresh cycle manufacturers and green propulsion specialists. Competitive moves center on automated test sequence deployment and modular subsystem standardization rather than bespoke satellite builds.
Among vertically integrated operators, Planet Labs and ICEYE occupy positions reflecting distinct payload specialization vectors, while GomSpace anchors European supply through Danish qualification infrastructure. Raytheon Technologies exemplifies defense-heritage diversification into small satellite platforms. These three entities represent the spectrum from commercial Earth observation subscription models to agency-funded technology demonstration heritage.
| Leading Market Players |
|---|
| Axelspace Corporation |
| Raytheon Technologies |
| Planet Labs |
| Astrocast |
| ConstellR |
| GomSpace |
| ICEYE |
| GalaxySpace |
| NanoAvionics |
| Others |
Cost & Logistics Intelligence
Eighteen-month satellite refresh cycles compress component procurement windows and concentrate pricing power with ISO 19683-qualified cleanroom vendors in Denmark and the United States. This lead-time compression elevates aluminum 6061-T6 frame stock and propulsion subsystem suppliers to bottleneck positions where allocation decisions determine constellation deployment velocity.
Pricing Analysis
Cost-plus contracts with aluminum LME indexation dominate procurement for Cubesat frames and solar array substrates. Three-tier pricing structure across heritage-qualified, commercial-grade, and university-tier levels separates government missions demanding ECSS-E-ST-40C software assurance from price-sensitive educational buyers. Cost compression in commercial Earth observation tiers is intensifying because constellation operators prioritize refresh velocity over subsystem longevity. University procurement offices exhibit highest price sensitivity, while national space agencies absorb premiums for qualification documentation.
Supply Chain Analysis
Inventory buffers for aerospace-grade aluminum 6061-T6 and lithium-ion cells rarely exceed ninety days given volatile energy-intensive smelting constraints. Manufacturing concentrates in the United States, Denmark, and Japan for vibration-test infrastructure and precision component fabrication. Raw material dependencies center on aluminum frame stock, gallium arsenide solar cells, and iodine propellant formulations. Single-source vulnerability persists for Hall-effect thruster xenon alternatives. Distribution runs through rideshare launch aggregators and direct prime contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward commercial constellation operators consolidating purchasing around three dominant Earth observation analytics platforms. This concentration compresses vendor margins and elevates refresh-cycle velocity above heritage certification as the primary procurement criterion.
For Market Incumbents: Fortify ISO 19683 cleanroom capacity in Aalborg or San Francisco to defend against emerging electric propulsion specialists. Lock in multi-year aluminum 6061-T6 offtake agreements before energy price volatility escalates. Prioritize automated test sequence deployment to match eighteen-month refresh demands from Planet Labs-tier customers. For New Entrants and Emerging Players: FCC Part 25 streamlining offers a certification fast-track for sub-180 kg station authorizations. Narrowband Internet of Things backhaul for remote asset monitoring presents the most penetrable white-space target beyond saturated imagery markets. Pursue ISRO PSLV rideshare slots as the go-to-market angle for European university technology demonstration missions. For Investors and Strategic Acquirers: Long-term, this sits as a launch-arbitrage play because ISRO commercial pricing undercuts Falcon 9 alternatives and PSLV capacity expansion is accelerating. Target iodine-fueled propulsion specialists with ESA Green Deal funding alignment. Watch ESA debris mitigation guideline enforcement as the inflection signal for deorbit-capable platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19683 Cleanroom Certification | Qualification infrastructure scarcity in Denmark and Japan elevates certified vendors to bottleneck positions. |
| Iodine Propulsion Development | EU Green Deal funding accelerates non-toxic thruster adoption over hydrazine systems for ESA missions. |
| PSLV Rideshare Partnership | ISRO commercial slots position India as launch arbitrage hub below Falcon 9 price points. |
| Automated Test Sequence Deployment | Constellation refresh compression from five years to eighteen months demands modular manufacturing workflows. |
| Synthetic-Aperture Radar Miniaturization | 6U all-weather imaging payloads unlock agriculture and maritime insurance subscription analytics. |
Research Approach
Cross-validation between constellation operator procurement directors and launch service provider capacity planners anchors the qualitative findings in this analysis. Primary interviews with satellite subsystem engineers, FCC licensing attorneys, cleanroom facility managers, and Earth observation analytics buyers combined with secondary validation against FCC Part 25 filing databases, ESA procurement records, and ISRO commercial launch manifests. Bottom-up unit economics for Cubesat component costs and top-down constellation deployment schedules triangulate market sizing.
Sensitivity analysis across aluminum price volatility bands and launch slot availability scenarios stress-tests projection robustness. Segmentation dimensions modeled include form factor tier, end-user procurement structure, application revenue model, and propulsion technology architecture. CAGRs derive from deployment schedule aggregation and refresh cycle velocity assumptions. Industry-specific inputs encompass FCC licensing timeline distributions and ESA debris mitigation compliance cost curves.
Underlying assumptions cover sustained Long March reusability progress and PSLV foreign payload slot expansion, with deviation risk concentrated in cleanroom infrastructure bottlenecks and REACH material restriction scope creep. Forecasts reflect documented assumptions without forward-looking precision claims. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
China Satellite Communication Market
Satellite
Europe Small Satellite Market
Satellite
North America Satellite Manufacturing Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Africa Satellite Connectivity Market
Satellite
Global Satellite Modem Market
Satellite
Low-Cost Satellite Market
Satellite
Satellite Data Service Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Satellite Attitude and Orbit Control System Market