
 Cordless Vacuum Cleaner Market | 2026-2036
Cordless Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Vacuum Cleaner Market Analytics
EU Ecodesign regulations is restructuring the cost-of-entry calculus for cordless vacuum cleaner manufacturers by mandating minimum energy efficiency thresholds and repairability standards. Dyson Ltd. leverages proprietary digital motor technology to sustain premium positioning against these compliance costs. SharkNinja Operating LLC anchors its competitive stance through direct-to-consumer channel control in North America. Bosch differentiates via German-engineered filtration systems that exceed baseline regulatory requirements.
A cordless vacuum cleaner is a portable cleaning device powered by rechargeable battery packs, typically lithium-ion cells rated between 18V and 54V, utilizing cyclonic or direct suction mechanisms to separate debris from airflow without a tethered power cord. The primary purpose spans residential debris removal, commercial facility maintenance, and light industrial particulate extraction where mobility and rapid deployment matter. Stick configurations dominate volume shipments due to their compromise between maneuverability and dust capacity, while robotic units represent the fastest-expanding margin pool as autonomous navigation algorithms mature. Handheld variants occupy a stable niche for automotive and tight-space applications where full-size units prove impractical.
FCC certification governs electromagnetic emissions for wireless-enabled robotic models in the United States, while EU REACH restrictions on hazardous substances constrain battery chemistry and plastic composition choices for brands serving European households. China's GB standards for appliance safety and the country's dual carbon goals pressure local manufacturers toward higher-efficiency motor designs and recyclable material streams. Stakeholders must monitor how divergent regional efficiency benchmarks reshape platform development costs and determine whether modular battery architectures can satisfy multiple compliance regimes without fragmenting production economics.
Market Dynamics
Lithium-ion battery energy density improvements are compressing motor size requirements while EU Ecodesign mandates force modular repairable architectures, restructuring how manufacturers allocate R&D spend between performance and compliance.
Growth Catalysts
- EU Ecodesign regulations:Mandated repairability standards and minimum energy efficiency thresholds accelerate replacement cycles for non-compliant legacy units across German and French households.
- Stick configuration dominance:Urban apartment dwellers in Shanghai and Shenzhen prioritize maneuverability-weight compromises, driving volume shipments of slim-form lithium-powered models.
- Autonomous navigation maturation:Simultaneous localization and mapping algorithms enable robotic units to penetrate premium residential segments previously served by manual stick alternatives.
Market Restraints
- Cobalt supply concentration:Democratic Republic of Congo dominance in cobalt ore extraction creates battery chemistry cost volatility and ethical sourcing compliance burdens.
- EU REACH substance restrictions:Hazardous substance limits on plastics and battery materials constrain formulation flexibility, extending product development timelines for European-bound SKUs.
- Tethered central vacuum substitution:New construction in North American suburban markets retains built-in ducted systems, capping cordless penetration in single-family detached housing.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives reduce import dependency and enable cost-engineered stick models for middle-class urban households.
- Commercial facility maintenance automation:Robotic units with fleet management software capture light industrial particulate extraction contracts from contract cleaning services.
- Direct-to-consumer channel expansion:Bypassing traditional retail markups in North America allows margin capture and customer data ownership for digitally native brands.
Industry Challenges
- Cross-regional certification fragmentation:Divergent FCC electromagnetic emission limits, EU CE marking requirements, and China's GB safety standards force redundant testing protocols.
- Modular battery architecture complexity:Designing swappable packs that satisfy multiple voltage and thermal management regimes without fragmenting production economics strains engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Vacuum Cleaner Market |
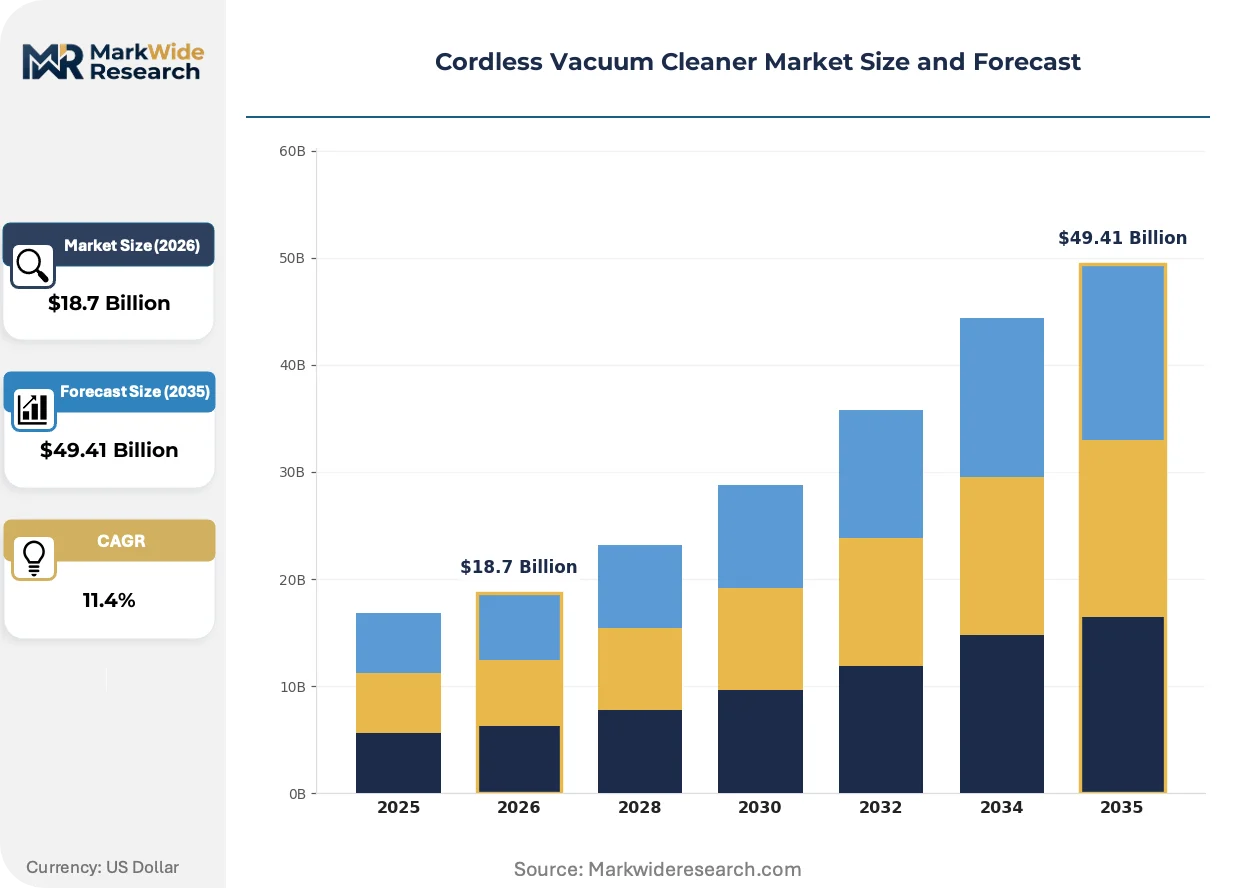
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Handheld, Stick, Robotic Feature: Battery Life, Suction Power, Filtration System, Weight End User: Residential, Commercial, Industrial, Professional Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Mass Merchants |
| Companies Covered | Dyson Ltd., SharkNinja Operating LLC, LG Electronics, Bissell Inc., Samsung Electronics, Electrolux, Philips, Bosch, TTI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Vacuum Cleaner Market Evolving Landscape
Digital motor control systems and solid-state battery prototyping are compressing the performance gap between cordless and corded suction power, while regulatory repairability mandates force industrial design trade-offs previously avoided.
Brushless DC motor control algorithms are converging with real-time battery management systems to sustain peak suction output across declining charge states. Residential stick manufacturers in Japan and South Korea deploy these integrated electronics to maintain rated airflow performance through entire cleaning cycles. The technology convergence is converging with premium pricing tiers as performance consistency becomes a differentiable specification against cost-optimized competitors.
China's dual carbon goals pressure domestic manufacturers toward higher-efficiency motor designs and recyclable material streams under MEE oversight. Appliance exporters must document carbon intensity across supply chains to maintain eligibility for government procurement and state-backed financing. Local brands respond by accelerating in-house magnet wire winding capabilities and polymer recycling partnerships to satisfy audit requirements.
Subscription-based filter replacement programs are displacing traditional aftermarket retail for consumables in North American direct-to-consumer channels. Robotic vacuum buyers accept automated replenishment scheduling tied to usage telemetry, unbundling the hardware margin from recurring revenue streams. This behavioral shift concentrates most visibly in California and Texas metropolitan markets where smart home ecosystem penetration exceeds national averages.
Cordless Vacuum Cleaner Market Segmentation
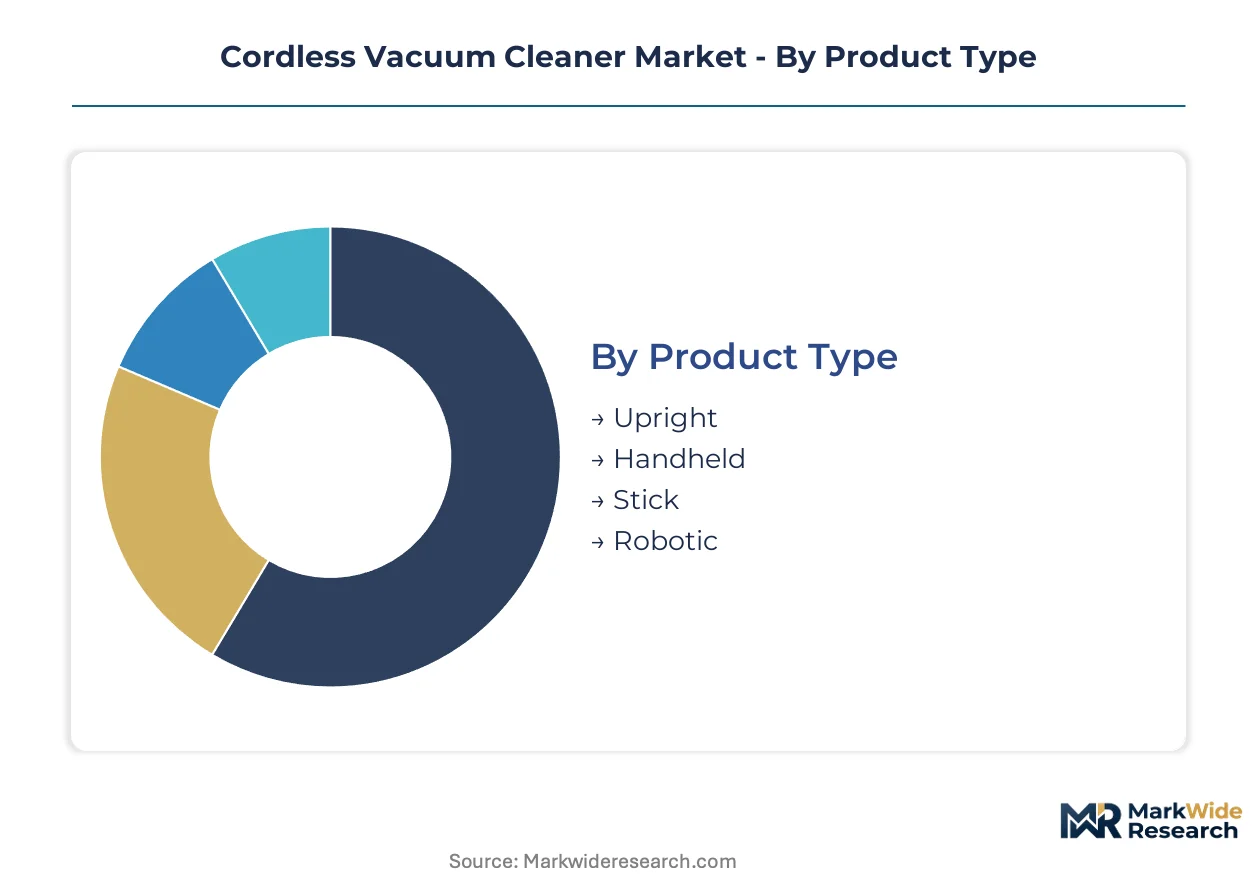
Cordless vacuum cleaner purchasing decisions hinge on trade-offs between maneuverability constraints and suction performance requirements across distinct use environments. Manufacturers align platform architectures to these divergent specifications rather than pursuing universal designs.
Product Type:
Buyers prioritize form-factor compatibility with dwelling dimensions and storage constraints above absolute suction metrics.
- Stick:Slim lithium-powered chassis with articulated joints dominate urban apartment penetration in Shanghai and Shenzhen where closet storage is limited. Chinese domestic manufacturers compete aggressively on cost-engineered variants for middle-class households prioritizing maneuverability-weight compromises.
- Robotic:Autonomous units with simultaneous localization and mapping algorithms capture premium residential segments previously served by manual alternatives. Fleet management software enables contract cleaning services in light industrial settings to automate particulate extraction across multiple facilities.
- Handheld:Compact battery packs rated 18V-36V serve automotive detailing and tight-space applications where full-size units prove impractical.
- Upright:Larger dust capacity and extended runtime appeal to suburban single-family dwellings with greater storage tolerance.
Stick configurations lead on scale; robotic units lead on momentum.
Feature:
Performance specifications differentiate pricing tiers as regulatory mandates force measurable efficiency disclosures.
- Battery Life:Lithium-ion energy density improvements compress motor size requirements while EU Ecodesign mandates push modular repairable architectures. Runtime consistency across declining charge states has emerged as a differentiable specification in Japanese and South Korean premium tiers.
- Suction Power:Brushless DC motor control algorithms converging with real-time battery management sustain peak airflow output through entire cleaning cycles. Digital motor systems narrow the performance gap against corded alternatives.
- Filtration System:German-engineered HEPA configurations exceed baseline EU regulatory requirements for allergen retention in European households.
- Weight:Gram reduction in chassis and battery pack design targets elderly users and multi-level dwelling navigation.
Battery life commands the largest R&D allocation; suction power delivers the steepest expansion trajectory in premium positioning.
End User:
Application intensity determines durability requirements and replacement cycle frequency across customer types.
- Residential:Urban apartment dwellers in dense Chinese and Indian metropolitan markets drive volume adoption of slim-form stick models. Replacement cycles accelerate as EU Ecodesign regulations phase out non-compliant legacy units across German and French households.
- Commercial:Facility maintenance contracts favor robotic units with centralized fleet oversight for light industrial particulate extraction. Contract cleaning services in North American metropolitan markets adopt automated replenishment scheduling tied to usage telemetry.
- Professional:Specialized detailing operators demand rapid-deployment handheld units for automotive and tight-space applications.
- Industrial:Heavy-debris environments with continuous runtime requirements retain tethered systems, capping cordless penetration.
Residential segments anchor volume; commercial applications are climbing the fastest on automation adoption.
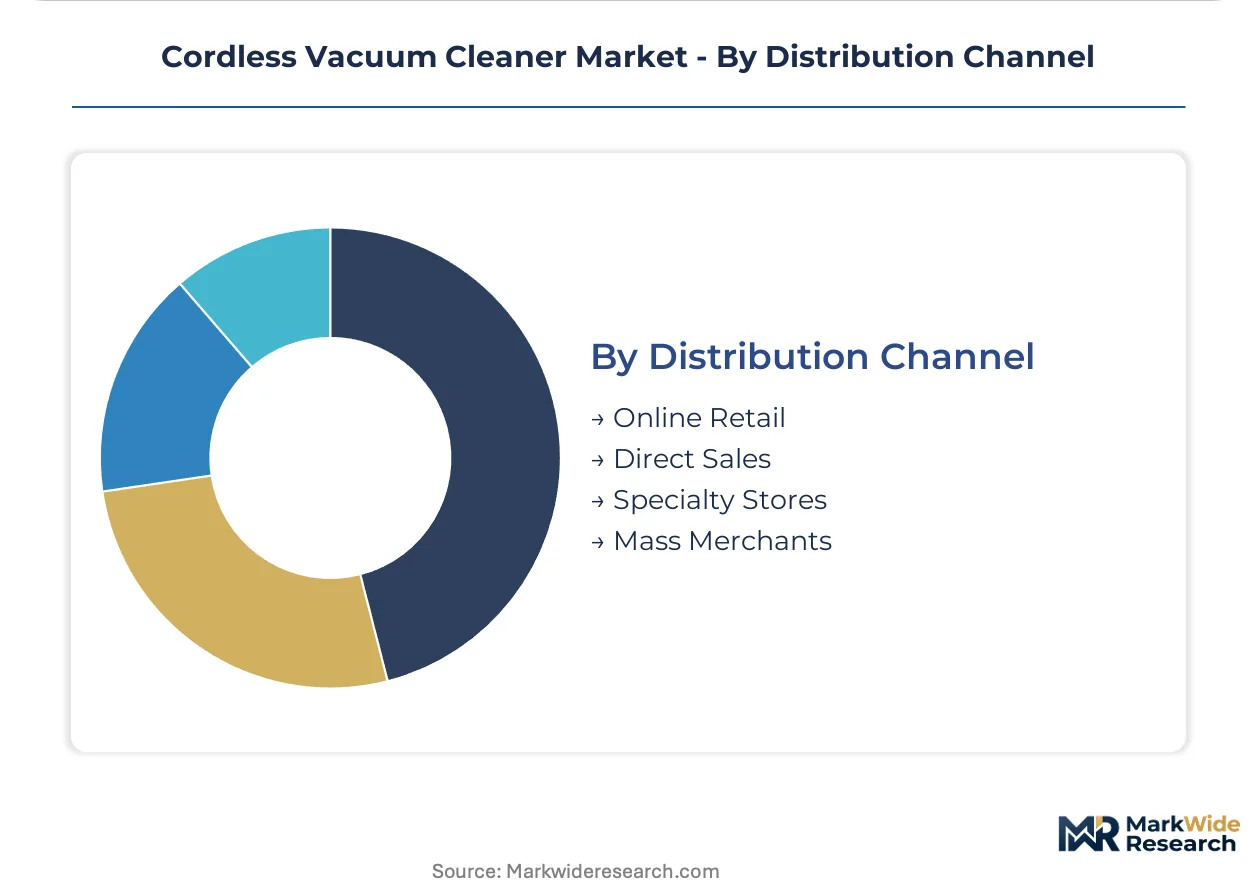
Distribution Channel:
Channel economics determine margin capture and customer data ownership for manufacturers.
- Direct Sales:Digitally native brands bypass traditional retail markups in North America to capture margin and build proprietary customer datasets. Subscription-based filter replacement programs concentrate in California and Texas metropolitan markets.
- Online Retail:E-commerce platforms aggregate comparison shopping for specification-focused buyers evaluating battery runtime and filtration ratings.
- Specialty Stores:Hands-on demonstration environments support premium positioning for robotic units requiring navigation algorithm explanation.
- Mass Merchants:High-volume cost-optimized stick models move through big-box retail for price-sensitive household penetration.
Direct sales leads on margin extraction; online retail is gaining share fastest on comparison-driven purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Shenzhen, Stuttgart, and Seoul anchor cordless vacuum cleaner development clusters where battery chemistry expertise intersects with precision motor manufacturing capabilities.
China
Urban apartment dwellers in Shanghai and Shenzhen prioritize slim-form stick models with maneuverability-weight compromises. The Ministry of Ecology and Environment enforces dual carbon goals that pressure manufacturers toward recyclable material streams and carbon intensity documentation. Domestic brands in the Pearl River Delta accelerate in-house magnet wire winding to satisfy government procurement eligibility.
Germany
Households across German metropolitan markets face accelerated replacement cycles as EU Ecodesign regulations phase out non-compliant legacy units. ECHA REACH restrictions constrain hazardous substance limits on plastics and battery materials for European-bound SKUs. Engineering clusters in Stuttgart and Munich concentrate German-engineered filtration systems that exceed baseline regulatory requirements.
United States
Suburban single-family construction in Texas and Florida retains built-in ducted vacuum systems, capping cordless penetration in detached housing segments. FCC certification governs electromagnetic emissions for wireless-enabled robotic models entering American households. Direct-to-consumer channel control concentrates in California metropolitan markets where smart home ecosystem penetration enables subscription-based filter replacement programs.
Japan
Premium residential segments in Tokyo and Osaka demand runtime consistency across declining charge states as a differentiable specification. METI efficiency standards drive integrated electronics deployment to maintain rated airflow performance through entire cleaning cycles. Brushless DC motor control algorithms converge with real-time battery management systems in Kanto region manufacturing facilities.
India
Middle-class urban households in Mumbai and Delhi-NCR drive cost-engineered stick model adoption as residential cleaning electrification accelerates. The PLI scheme for advanced chemistry cells reduces import dependency and enables domestic battery manufacturing for price-competitive variants. Maharashtra and Karnataka industrial corridors attract component suppliers seeking proximity to emerging demand centers.
Cordless Vacuum Cleaner Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where premium positioning and cost-engineered volume segments operate with distinct margin profiles. The vendor base organizes around three strategic archetypes: technology-led premium brands, manufacturing-scale cost optimizers, and digitally native direct-to-consumer entrants. M&A activity concentrates on battery technology access and autonomous navigation capabilities, while strategic partnerships proliferate around modular repairable architectures forced by EU compliance mandates.
Within the premium technology tier, Dyson Ltd. and Bosch exemplify engineering-intensive positioning anchored in proprietary motor and filtration capabilities. SharkNinja Operating LLC occupies a position bridging premium features with direct-to-consumer channel control in North American markets. These three anchors illustrate how competitive differentiation fragments across technological specialization, supply chain configuration, and customer relationship ownership rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Dyson Ltd. |
| SharkNinja Operating LLC |
| LG Electronics |
| Bissell Inc. |
| Samsung Electronics |
| Electrolux |
| Philips |
| Bosch |
| TTI |
| Others |
Value Network & Pricing Analysis
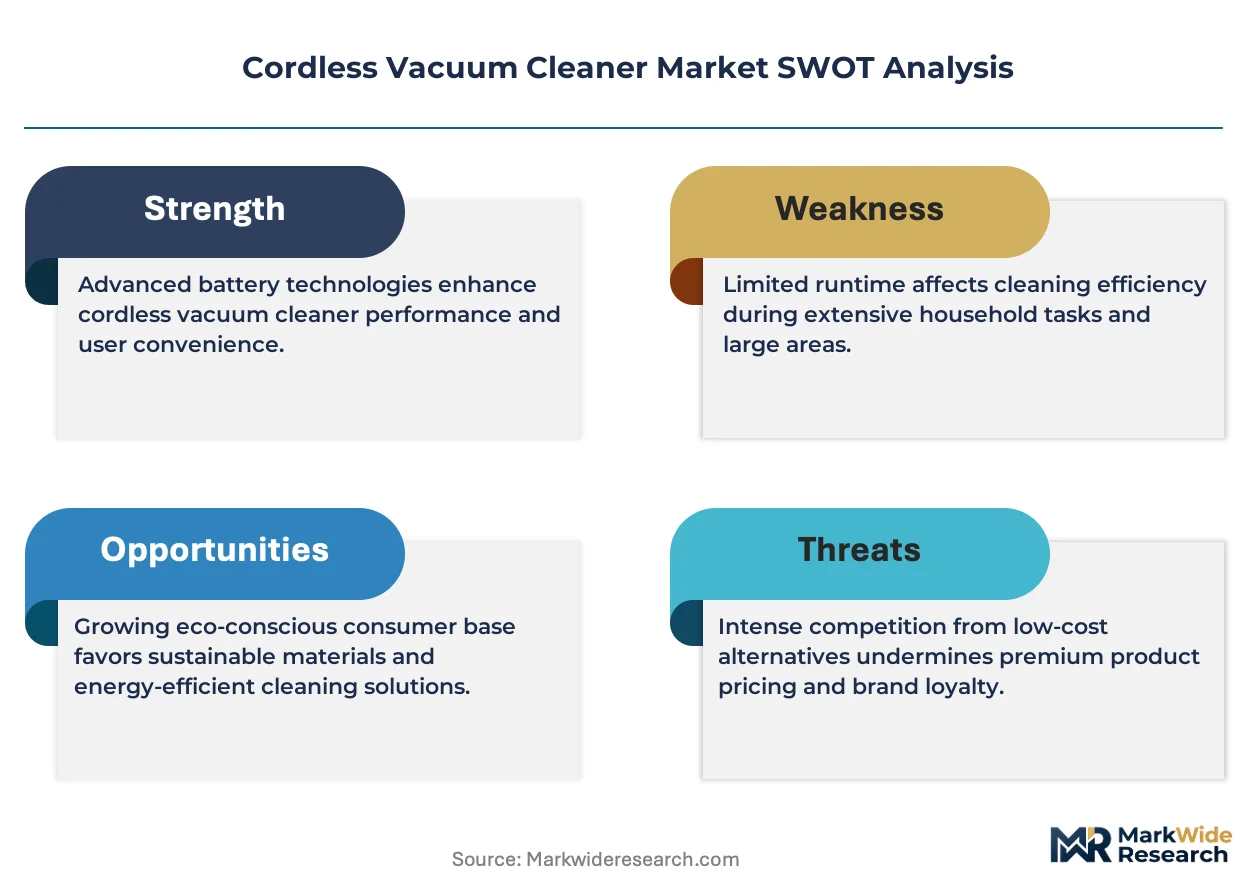
Lithium carbonate spot pricing volatility cascades through cordless vacuum cleaner supply chains, compressing margins on cost-engineered stick models while enabling premium-tier brands to absorb chemistry cost swings through subscription bundling and filter replacement programs.
Pricing Analysis
Bundled hardware-subscription splits separate Dyson and SharkNinja's recurring revenue models from transactional competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor wattage and battery chemistry grade. Price differentiation hinges on HEPA certification tier and direct-to-consumer channel control. Pricing pressure stems from Chinese domestic manufacturers flooding mid-market stick segments. Urban apartment dwellers in Shanghai exhibit highest price sensitivity; commercial facility managers purchasing robotic fleets show lowest.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan manufacturing zones are tightening labor costs for precision motor winding operations. Supply concentrates in China for lithium-ion cell assembly, Vietnam for plastic chassis injection molding, and Germany for filtration system engineering. The chain draws from cobalt ore from the Democratic Republic of Congo, rare earth magnets from Inner Mongolia, and polymer resins from South Korean petrochemical complexes. Single-source vulnerability in cobalt extraction creates chemistry cost volatility. Distribution runs through direct-to-consumer platforms, mass merchant retail, and contract cleaning service procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Ecodesign compliance costs in Germany and France exceed India's PLI scheme subsidy offsets, creating divergent margin structures for manufacturers with multi-regional footprints.
For Market Incumbents: Cement proprietary digital motor capabilities through in-house magnet wire winding investments in the Pearl River Delta. Lock in modular battery architecture standardization before EU repairability mandates fragment platform economics. Defend against Chinese cost-engineered entrants by accelerating subscription-based filter replacement programs in California metropolitan markets. For New Entrants and Emerging Players: Direct-to-consumer channel expansion offers the lowest customer acquisition cost route for digitally native brands targeting North American suburban households. White-space exists in India's cost-engineered stick segment as PLI scheme domestic cell production matures. Fleet management software for commercial robotic units in contract cleaning services represents the most penetrable B2B application. For Investors and Strategic Acquirers: Consolidation pressure builds where autonomous navigation algorithm capabilities concentrate in robotic vacuum specialists. Long-term viability favors manufacturers with backward integration into battery cell chemistry and captive filtration system engineering. Acquisition target archetype: mid-cap specialists with EU CE marking pathways and direct-to-consumer data assets. Watch solid-state battery prototyping timelines as inflection indicator for performance-tier disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Manufacturing | PLI scheme eligibility in India and MEE carbon audits in China secure procurement cost advantages. |
| Modular Repairable Architecture Investment | EU Ecodesign compliance accelerates replacement cycles across German and French households. |
| Direct-to-Consumer Channel Expansion | Subscription filter programs in California and Texas metropolitan markets capture recurring revenue. |
| Fleet Management Software Development | Contract cleaning services in North American light industrial settings automate multi-facility deployment. |
| Solid-State Battery Prototyping Partnership | Energy density gains compress motor size requirements and narrow corded-cordless performance gaps. |
Research Methodology
Multiple input streams — executive interviews with cordless vacuum cleaner product managers, procurement leads at contract cleaning services, and lithium-ion battery supply planners — were reconciled against secondary validation from customs trade data, SEC appliance manufacturer filings, and EU Ecodesign compliance registries. Primary fieldwork captured pricing dynamics across direct-to-consumer, mass merchant, and specialty retail channels. Bottom-up shipment estimates by product configuration and top-down category value assessments were triangulated for consistency.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, battery voltage tier, filtration certification grade, end-use intensity, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle data and efficiency mandate phase-in schedules. Forecast inputs incorporated lithium carbonate price trajectory assumptions and autonomous navigation algorithm maturity indicators.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions around EU Ecodesign enforcement timing, cobalt supply chain stability, and smart home ecosystem penetration rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Gas Ranges Market
Appliances
Portable Dishwasher Market
Appliances
US Washing Machine Parts Market
Appliances
Global Massage Chairs Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Refrigerator Door Seal Market
Appliances
Global Home Ice Maker Market
Appliances
Electric Hand Dryer Market
Appliances
Commercial Microwave Ovens Market
Appliances
Under Counter Dishwasher Market
Appliances
Window Air Conditioners Market
Appliances
UAE Gas Hobs Market
Appliances
Bathroom Heaters Market
Appliances
Laundry Appliances Market
Appliances
Electric Rice Cooker Market
Appliances
French Door Refrigerator Market