
 North America Refurbished and Used Mobile Phones Market | 2026-2036
North America Refurbished and Used Mobile Phones Market Size, Share, and Industry Trends Forecast 2026-2036
North America Refurbished and Used Mobile Phones Market Insights
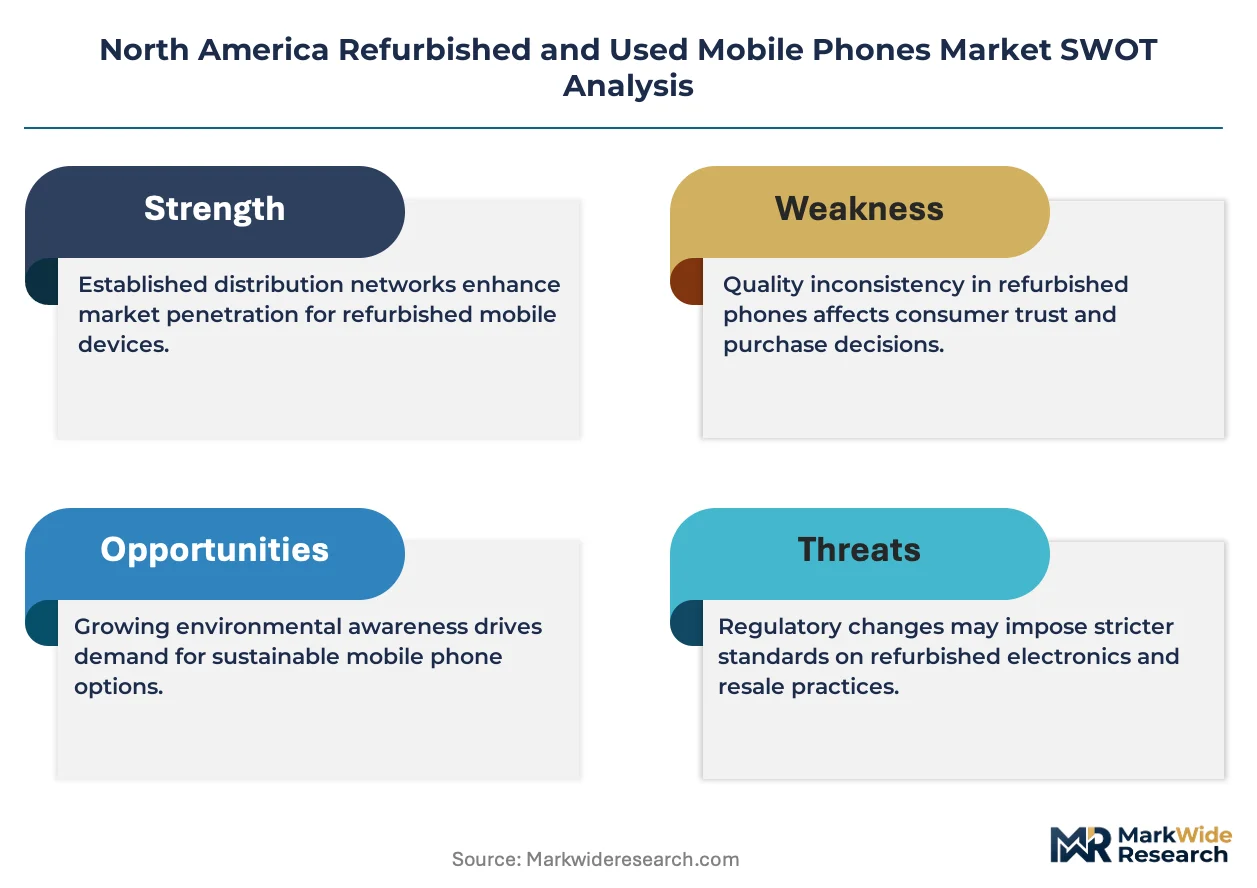
R2 (Responsible Recycling) certification is redrawing competitive boundaries in the refurbished phone supply chain. Amazon.com Inc. leverages its fulfillment infrastructure to control reverse logistics and inspection workflows. Back Market specializes in marketplace aggregation, connecting certified refurbishers directly to retail consumers across the United States and Canada. Best Buy Co. Inc. anchors its Geek Squad refurbishment program to in-store trade-in ecosystems, creating a closed-loop device recovery channel.
Refurbished and used mobile phones are previously owned wireless communication devices restored to functional condition through component replacement, software reinstallation, and diagnostic testing, with battery health thresholds and cosmetic grading systems determining resale tier placement. The primary commercial purpose centers on extending device lifecycles while delivering cost savings relative to new hardware acquisition. Smartphones dominate volume flows within the product type dimension, though graded-condition units command premium margins from condition-sensitive buyers. Online retail channels capture the fastest growth trajectory among distribution pathways, driven by direct-to-consumer logistics and transparent condition disclosures.
The FCC enforces equipment authorization standards that refurbished devices must meet for legal resale, while state-level extended producer responsibility frameworks in California and New York mandate collection and recycling targets for original equipment manufacturers. R2 and e-Stewards certifications function as de facto market access credentials, filtering uncertified operators from B2B procurement pools. Stakeholders must monitor evolving right-to-repair legislation across Canadian provinces and U.S. states, as statutory access to OEM parts and diagnostic tools reshapes refurbishment economics and competitive moats.
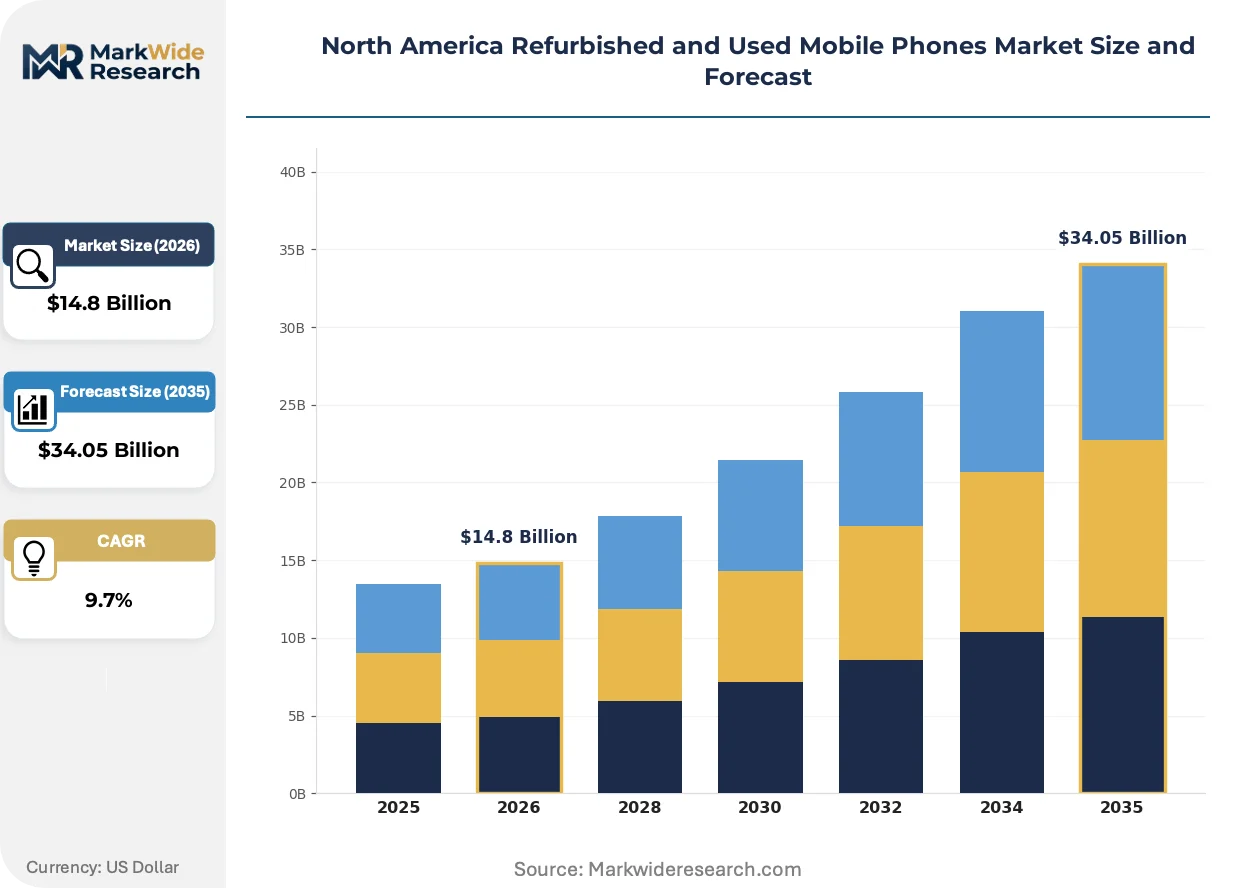
Market Dynamics
Reverse logistics concentration across Texas and California is compressing refurbishment cycle times while FCC equipment authorization rules elevate quality thresholds that filter marginal operators from B2B procurement pools.
Growth Catalysts
- R2 Certification Mandates:Mid-size enterprise procurement teams now require R2 or e-Stewards credentials as de facto market access conditions, channeling volume toward certified refurbishers and away from informal traders.
- Extended Producer Responsibility Frameworks:California and New York state laws impose collection and recycling targets on original equipment manufacturers, generating feedstock supply for certified refurbishment channels.
- Geographic Clustering of Reverse Logistics Hubs:Concentration of processing facilities near Dallas-Fort Worth and Los Angeles metropolitan areas reduces inbound freight costs and accelerates device-to-resale velocity.
Market Restraints
- OEM Parts Access Restrictions:Limited statutory right-to-repair provisions in most US states and Canadian provinces restrict access to proprietary diagnostic tools and genuine replacement components, elevating refurbishment costs.
- Battery Supply Concentration:Dependence on concentrated Asian cell manufacturers for lithium-ion replacement batteries exposes refurbishers to input cost volatility and supply intermittency.
- FCC Authorization Friction:Device-level testing and certification requirements for refurbished electronics create compliance timelines that delay inventory velocity and tie up working capital.
Strategic Opportunities
- Canadian Provincial Right-to-Repair Expansion:Pending legislation in Ontario and Quebec would mandate OEM parts availability, reducing input costs and enabling in-house component-level repairs currently outsourced.
- Enterprise Fleet Refresh Cycles:Corporate mobility programs with 24-to-36-month replacement schedules generate predictable high-grade device feedstock with documented provenance and minimal cosmetic degradation.
- Direct-to-Consumer Marketplace Platforms:Online retail channels with transparent condition grading and warranty terms capture buyer segments previously served by opaque informal resale markets.
Industry Challenges
- Diagnostic Technician Scarcity:Component-level motherboard repair and microsoldering skills required for premium-tier refurbishment remain concentrated among specialized technicians, constraining output scaling.
- Certification Audit Costs:R2 and e-Stewards accreditation requires ongoing third-party facility audits and documentation systems that impose fixed cost burdens disproportionately on smaller operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Refurbished and Used Mobile Phones Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Feature Phones, Phablets, Tablets Customer Type: Retail Consumers, Businesses, Educational Institutions, Nonprofits Condition: Refurbished, Used, Open Box, Graded Distribution Channel: Online Retail, Physical Stores, Wholesalers, Auction Platforms |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd, Amazon.com Inc., Verizon Communications Inc., AT&T Inc., Best Buy Co. Inc., eBay Inc., Walmart Inc., Back Market, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Refurbished and Used Mobile Phones Market Trends and Innovations
Automated diagnostic platforms and blockchain-based provenance tracking are compressing inspection timelines while reshaping trust mechanisms between refurbishers and institutional buyers across the trade.
AI-powered condition assessment software is decomposing traditional manual grading workflows by analyzing device cosmetic state through computer vision algorithms. Large-volume refurbishers in Texas and California processing hubs deploy these systems to standardize condition tiers across thousands of units daily. This technology is decomposing the historical reliance on subjective human graders, reducing inter-rater variance and accelerating inventory velocity through automated tier placement.
The FCC's equipment authorization framework for refurbished wireless devices is tightening electromagnetic compatibility testing requirements that previously exempted secondary-market hardware. Refurbishers must now submit devices for formal testing or operate under original equipment manufacturer certifications that limit modification scope. Enterprise procurement teams sourcing certified pre-owned fleets face extended lead times as suppliers navigate this compliance layer, with California-based operators investing in in-house testing capabilities to preserve margins.
Corporate mobility managers are consolidating device sourcing around certified pre-owned programs with standardized warranty terms and asset disposition services. Traditional OEM-direct procurement contracts with 24-month refresh cycles face displacement from third-party fleet management providers offering device-as-a-service models built on refurbished hardware pools. This pattern concentrates most visibly among mid-size professional services firms in the Texas-California corridor seeking to reduce per-employee hardware expenditure without sacrificing IT support reliability.
North America Refurbished and Used Mobile Phones Market Segmentation
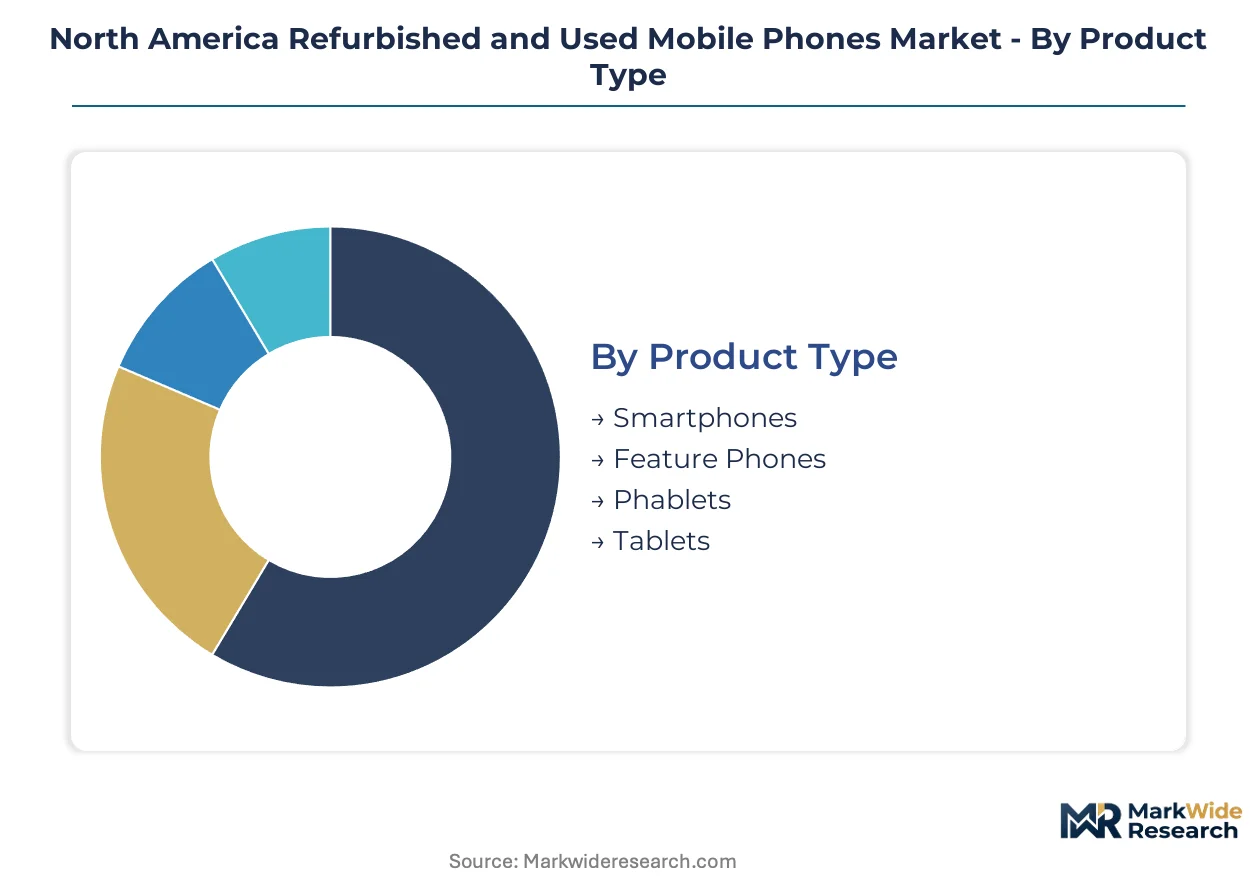
Segmentation in the North America refurbished and used mobile phones market reveals how regulatory requirements, procurement protocols, and resale channel economics create distinct commercial pockets. Understanding these divides enables suppliers to align certification investments, inventory grading, and logistics configuration with buyer expectations.
Product Type:
FCC equipment authorization rules apply differentially across device categories, with cellular-enabled hardware facing stricter electromagnetic compatibility testing than Wi-Fi-only tablets.
- Smartphones:Cellular-enabled devices with integrated operating systems dominate procurement volumes among enterprise mobility programs. Texas and California corridor enterprises source certified pre-owned smartphones in bulk for field workforce deployment, constrained by FCC authorization timelines that delay fleet refresh schedules.
- Feature Phones:Basic voice-and-text devices with limited computing capability serve niche demographics including senior populations and industrial safety zones. Demand concentrates in rural Canadian markets and US agricultural regions where smartphone complexity creates adoption friction and durability priorities override feature requirements.
- Phablets:Screen-size hybrids between smartphones and tablets appeal to mobile productivity users requiring expanded display real estate.
- Tablets:Wi-Fi-centric slates face reduced FCC testing burdens compared to cellular variants, accelerating refurbishment velocity for education sector procurement.
Established volume favors smartphones; emerging adoption favors tablets.
Customer Type:
Procurement sophistication varies sharply across buyer categories, with institutional purchasers imposing R2 certification mandates that informal retail channels rarely enforce.
- Retail Consumers:Individual buyers purchasing single units through marketplace platforms or carrier trade-in programs. Price sensitivity drives condition-grade tradeoffs, with online retail channels capturing preference through transparent cosmetic grading and warranty terms that reduce purchase risk.
- Businesses:Corporate mobility managers operating device-as-a-service programs with standardized refresh cycles. Mid-size professional services firms in the Texas-California corridor consolidate sourcing around certified pre-owned fleets with documented provenance and asset disposition services.
- Educational Institutions:K-12 districts and universities procuring bulk device pools for student one-to-one programs.
- Nonprofits:Mission-driven organizations distributing hardware to underserved populations, prioritizing cost minimization over cosmetic condition.
Margin concentration sits with businesses; volume expansion sits with retail consumers.
Condition:
Condition grading systems determine resale tier placement and warranty eligibility, with certified refurbished units commanding procurement preference in institutional channels.
- Refurbished:Devices restored to functional condition through component replacement, diagnostic testing, and software reinstallation. R2-certified refurbishers in Dallas-Fort Worth and Los Angeles processing hubs supply enterprise procurement teams requiring documented chain-of-custody and battery health thresholds above eighty percent.
- Used:Pre-owned devices sold as-is without restoration intervention, typically through auction platforms and informal resale markets. Price discounting attracts cost-constrained buyers willing to absorb functional uncertainty and limited recourse.
- Open Box:Units returned unused or minimally activated within retail return windows.
- Graded:Cosmetically assessed inventory tiered through A-B-C condition scales with corresponding price differentiation.
Certification requirements favor refurbished; price elasticity favors used.
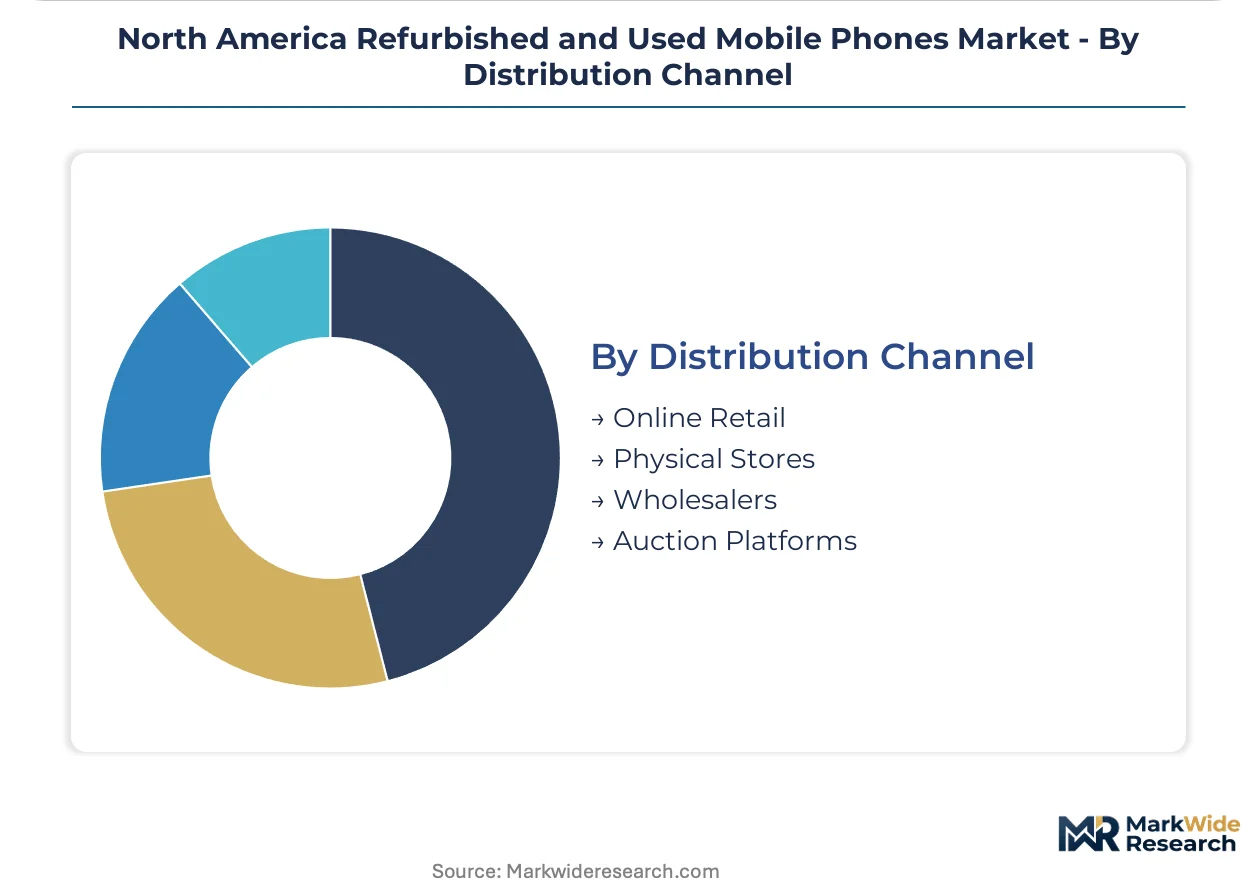
Distribution Channel:
Channel selection shapes inspection transparency, return logistics, and buyer trust mechanisms in ways that segment customer acquisition economics.
- Online Retail:Direct-to-consumer platforms with automated condition disclosure and integrated warranty fulfillment. Computer vision algorithms deployed by large-volume refurbishers standardize cosmetic grading across thousands of units daily, reducing inter-rater variance and compressing inventory velocity.
- Physical Stores:Brick-and-mortar locations enabling tactile inspection and immediate exchange, anchored by trade-in ecosystems that generate device feedstock. Geek Squad refurbishment programs create closed-loop recovery channels with in-person technical support attachment.
- Wholesalers:B2B intermediaries aggregating graded inventory for resale to smaller retailers and international export markets.
- Auction Platforms:Volume liquidation venues for insurance salvage, corporate fleet disposal, and carrier trade-in overflow with minimal condition guarantees.
Transparency advantages favor online retail; immediacy and service integration favor physical stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's equipment authorization framework and state-level extended producer responsibility statutes are reshaping refurbishment economics across the continent. Texas and California host the densest concentrations of reverse logistics infrastructure. Canadian provincial legislation is accelerating market formalization in Ontario and Quebec.
United States
Enterprise mobility programs at mid-size professional services firms drive bulk procurement of certified pre-owned smartphones. The FCC enforces electromagnetic compatibility testing requirements that filter marginal operators from B2B supply pools. Dallas-Fort Worth and Los Angeles metropolitan areas anchor the highest-density processing corridors, where R2-certified facilities compress device-to-resale cycle times.
Canada
Pending right-to-repair legislation in Ontario and Quebec would mandate OEM parts availability for independent refurbishers. Health Canada and Environment and Climate Change Canada administer e-waste collection frameworks that generate feedstock for certified channels. Toronto and Montreal serve as primary distribution nodes, with Vancouver emerging as a Pacific gateway for Asian-sourced replacement components.
California
The state's extended producer responsibility law imposes binding collection and recycling targets on original equipment manufacturers. CalRecycle oversees certification requirements that elevate quality thresholds above federal baselines. The Los Angeles-Long Beach logistics cluster hosts the largest concentration of battery testing and replacement facilities serving western US markets.
Texas
Corporate fleet refresh cycles from energy sector and technology employers generate predictable high-grade device feedstock. The Texas Commission on Environmental Quality administers electronics recycling standards that align with R2 certification protocols. The Dallas-Fort Worth metroplex functions as the central US reverse logistics hub, with inbound freight cost advantages for devices collected across the Great Plains and Southeast.
New York
State-level extended producer responsibility mandates mirror California's framework, creating dual-coastal regulatory pressure on OEMs. The New York State Department of Environmental Conservation enforces collection targets that expand certified refurbishment feedstock availability. The New York City metropolitan area serves as the primary East Coast distribution terminus, with secondary sorting operations concentrated in Buffalo and Albany.
North America Refurbished and Used Mobile Phones Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with captive reverse logistics infrastructure. Market structure concentrates around three strategic archetypes: original equipment manufacturers operating certified pre-owned programs, retail chains with integrated trade-in ecosystems, and marketplace platforms aggregating third-party refurbisher inventory. Dominant competitive moves include vertical integration into device recovery channels and technology licensing partnerships for automated diagnostic systems.
Among platform-based aggregators, Back Market exemplifies the marketplace archetype connecting certified refurbishers directly to retail consumers. Amazon.com Inc. and Best Buy Co. Inc. anchor the retail-integrated tier, with the former leveraging fulfillment infrastructure for reverse logistics control and the latter anchoring in-store trade-in ecosystems through its Geek Squad refurbishment program. Apple Inc. and Samsung Electronics Co. Ltd occupy positions as OEM-origin players with proprietary certified pre-owned channels.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd |
| Amazon.com Inc. |
| Verizon Communications Inc. |
| AT&T Inc. |
| Best Buy Co. Inc. |
| eBay Inc. |
| Walmart Inc. |
| Back Market |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at R2-certified processing hubs in Dallas-Fort Worth and Los Angeles determines price floors across the North American refurbished phone trade. Dense clustering of reverse logistics infrastructure compresses per-unit handling costs while FCC equipment authorization requirements filter marginal operators, concentrating pricing power among scaled refurbishers with in-house testing capabilities.
Pricing Analysis
Certification level creates the primary spread between transaction tiers in this market. Three-tier pricing structure across R2-certified premium, standard uncertified, and used-as-is economy levels segments buyer pools by risk tolerance and warranty requirements. Cost compression in the standard tier is intensifying because diagnostic technician scarcity elevates labor input costs. Retail consumers exhibit highest price sensitivity, while enterprise procurement teams prioritize documented chain-of-custody over unit cost minimization.
Supply Chain Analysis
Strategic stockpiling of lithium-ion battery inventories dominates working capital allocation across Texas and California processing hubs. Component sourcing draws from China, South Korea, and Japan for replacement cells and display assemblies. Single-source vulnerability to Asian cell manufacturer concentration exposes refurbishers to input cost volatility and supply intermittency. Distribution runs through online retail platforms with integrated warranty fulfillment, though physical store trade-in ecosystems generate captive device feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America refurbished and used mobile phones market sits in early-cycle recovery as enterprise fleet refresh programs normalize following pandemic-delayed hardware replacement schedules.
For Market Incumbents: Secure R2 certification renewals ahead of tightened audit protocols anticipated from state environmental agencies. Backward integration into battery testing capabilities preserves margin position against Asian cell supplier price volatility. Channel control through direct-to-consumer marketplace investments limits disintermediation risk from platform aggregators. For New Entrants and Emerging Players: Lead with Canadian provincial right-to-repair legislation as a geographic wedge, targeting Ontario and Quebec markets where pending OEM parts mandates reduce incumbent cost advantages. The nonprofit and educational institutional segments remain underpenetrated by certified refurbishers, offering volume contracts with lower cosmetic grade requirements. A go-to-market angle anchored to asset disposition services bundled with device procurement addresses corporate mobility manager workflow consolidation priorities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors scaled refurbishers with captive reverse logistics infrastructure and automated diagnostic platforms. Long-term viability rests on consolidation economics as certification audit costs disproportionately burden smaller operators. Acquisition targets should demonstrate R2 or e-Stewards credentials with established enterprise procurement relationships. The signal to watch is FCC equipment authorization timeline compression, which would accelerate inventory velocity and working capital efficiency across certified channels.| Strategic Initiative | Industry Significance |
|---|---|
| R2 Certification Investment | FCC and state environmental regulators elevate quality thresholds, filtering uncertified competitors from B2B procurement pools. |
| Automated Diagnostic Platform Deployment | Computer vision algorithms reduce inter-rater variance in cosmetic grading, compressing device-to-resale cycle times at scale. |
| Enterprise Fleet Management Partnership | Device-as-a-service models displace OEM-direct procurement contracts among mid-size professional services firms. |
| Battery Testing Capability Buildout | In-house cell health verification preserves margins against Asian lithium-ion supplier concentration and price volatility. |
| Canadian Geographic Expansion | Pending right-to-repair legislation in Ontario and Quebec mandates OEM parts availability, reducing input cost disadvantages. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase. Corporate mobility managers, refurbishment facility operators, R2 certification auditors, and reverse logistics coordinators provided operational perspective. Secondary validation drew from FCC equipment authorization databases, state environmental agency filings, carrier trade-in program disclosures, and customs records for replacement component imports. Bottom-up volume estimates triangulated against top-down market sizing from procurement spend analysis.
Across the projection horizon, the analytical framework models segmentation dimensions including device type, condition grade, customer category, and distribution channel. CAGRs were derived from trend extrapolation of enterprise fleet refresh cycles and consumer price elasticity patterns. Forecast inputs incorporated FCC regulatory timeline assumptions and lithium-ion battery supply concentration metrics.
The analysis sits within stated boundaries; outcomes outside sustained enterprise procurement normalization or accelerated right-to-repair legislative passage would require recalibration. Forecasts reflect assumptions around certification audit cost trajectories and Asian cell manufacturer pricing stability. Revision becomes warranted when FCC equipment authorization backlogs exceed thresholds that compress inventory velocity below working capital sustainability levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Wireless Mouse Market