
 Smart Massage Appliances Market | 2026-2036
Smart Massage Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Massage Appliances Market Insights
Market Context
REACH compliance in Europe is shifting the cost-of-entry calculus for smart massage appliance exporters, forcing reformulation of plastics and electronic components to eliminate restricted substances. SKG leverages its Shenzhen manufacturing base to navigate these regulatory layers while sustaining export volumes into EU markets. Breo anchors its competitive position through deep specialization in portable neck and eye massage devices with integrated heating elements. Westinghouse competes on brand recognition in North American retail channels, extending its legacy appliance trust into wellness categories.
Technical Definition and Structural Segments
Smart massage appliances are electromechanical wellness devices incorporating microprocessor-controlled motor systems, typically operating at 12–24V DC with programmable intensity profiles from 1,200 to 3,600 RPM, designed for musculoskeletal relaxation and circulatory stimulation in residential or light commercial settings. Massage chairs occupy the dominant revenue position within product type segmentation due to premium pricing and embedded AI-driven body-scanning calibration, while handheld devices capture the fastest volume trajectory among mobile professionals and travel-oriented consumers. Smartphone-controlled technology leads the connectivity dimension as Bluetooth pairing latency issues persist in budget-tier offerings, and online retail channels now control the majority of transaction flow for replacement and upgrade purchases across all end-user categories.
Regulatory Frame and Outlook
FCC electromagnetic emissions standards in the United States, CE marking requirements under the EU Medical Device Regulation for therapeutic claims, and China's GB 4706.1 safety standards collectively shape product certification timelines and market access feasibility. BIS certification in India adds a fourth compliance layer for manufacturers targeting Asia's second-largest consumer base. Stakeholders must monitor the evolving boundary between wellness and medical device classification, as reclassification in any major jurisdiction would trigger wholesale redesign of software validation protocols and clinical evidence requirements.
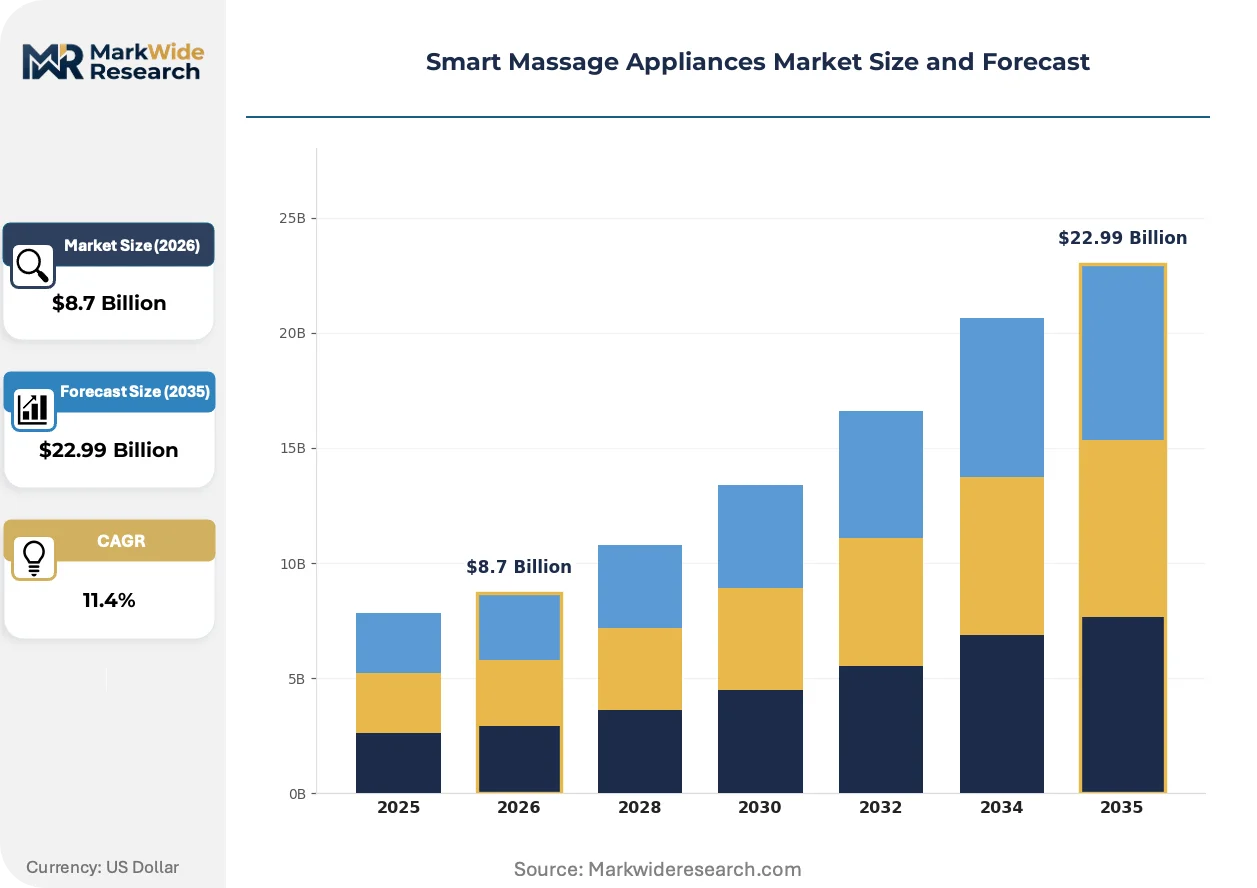
Market Dynamics
Recovery-focused wellness culture among athletes and fitness enthusiasts is compressing replacement cycles and elevating performance expectations for portable massage devices, while China's GB standards for electrical safety and smart interoperability are forcing simultaneous redesigns across product portfolios.
Growth Catalysts
- EU REACH compliance:Restricted substance rules are filtering out marginal competitors and consolidating export-qualified manufacturing capacity in Shenzhen and Dongguan industrial clusters.
- Athlete recovery protocols:Professional sports teams and CrossFit affiliates are specifying heated percussion devices with programmable RPM profiles for post-training circulation protocols.
- Bluetooth Low Energy 5.2:Reduced pairing latency is enabling real-time biometric feedback loops that synchronize massage intensity with heart rate variability data from wearables.
Market Restraints
- Neodymium magnet supply:Rare earth processing concentration in China's Inner Mongolia region creates input cost volatility for high-torque brushless motor assemblies.
- EU Medical Device Regulation friction:Therapeutic claim classifications trigger eighteen-month CE marking timelines that delay product launches relative to pure wellness positioning.
- Manual therapy substitution:Licensed massage therapists in Germany and Japan are resisting device adoption in clinical settings, preserving addressable market boundaries.
Strategic Opportunities
- India BIS certification pathway:Early movers establishing testing relationships with Mumbai and Bengaluru laboratories will capture premium positioning before domestic manufacturing scales.
- Corporate wellness procurement:HR departments at technology firms are bundling portable neck massagers with ergonomic workstation packages for remote employee stipends.
- AI-driven body scanning:Integration of pressure-mapping arrays with machine learning calibration is enabling chair systems that adapt to individual musculoskeletal topology without manual programming.
Industry Challenges
- Firmware validation protocols:Multi-jurisdiction software documentation requirements for GB 4706.1, FCC Part 15, and EU MDR are stretching quality assurance headcounts and timeline predictability.
- Cross-border component traceability:Polymer suppliers must document REACH-compliant formulation changes through three-tier subcontractor networks, complicating audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Massage Appliances Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Massage Chairs, Foot Massagers, Neck Massagers Technology: Smartphone-Controlled, Bluetooth-Enabled, AI-Driven, Vibration Technology End User: Individuals, Athletes, Therapists, Seniors Distribution Channel: Online Retail, Specialty Stores, Health Clubs, Pharmacies |
| Companies Covered | SKG, Breo, Jingdong Jingzao, Bear, KENTRO, Hommy, YESOUL, Shangheng, Westinghouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Massage Appliances Market Trends and Innovations
Electromechanical precision and connectivity architectures are converging to redefine user expectations for personalization and data integration, compressing the gap between consumer wellness and clinical-grade outcomes.
Variable frequency drive controllers with adaptive load sensing are rewriting performance benchmarks for handheld percussion devices. Marathon runners and triathletes are specifying units with 3,200 RPM ceiling speeds and stall-force detection above sixty pounds. This capability threshold is compressing price premiums for mid-tier manufacturers unable to source equivalent motor assemblies.
China's GB/T 36972 interoperability standards for smart home ecosystems are mandating open API architectures that break proprietary control app silos. Domestic manufacturers in Shenzhen must now support simultaneous pairing with Xiaomi, Huawei, and Tuya platforms. Export-oriented suppliers are absorbing compliance costs to maintain access to domestic volume while streamlining SKU complexity for EU and North American markets.
Subscription-enabled content libraries for guided recovery protocols are displacing one-time hardware transactions in premium chair segments. Peloton-style membership models from Los Angeles and Seoul wellness startups are bundling physiotherapist-curated programs with hardware financing. This shift is most visible in South Korea's MFDS-regulated therapeutic device channel, where reimbursement-adjacent positioning accelerates adoption among chronic pain patients.
Smart Massage Appliances Market Segmentation
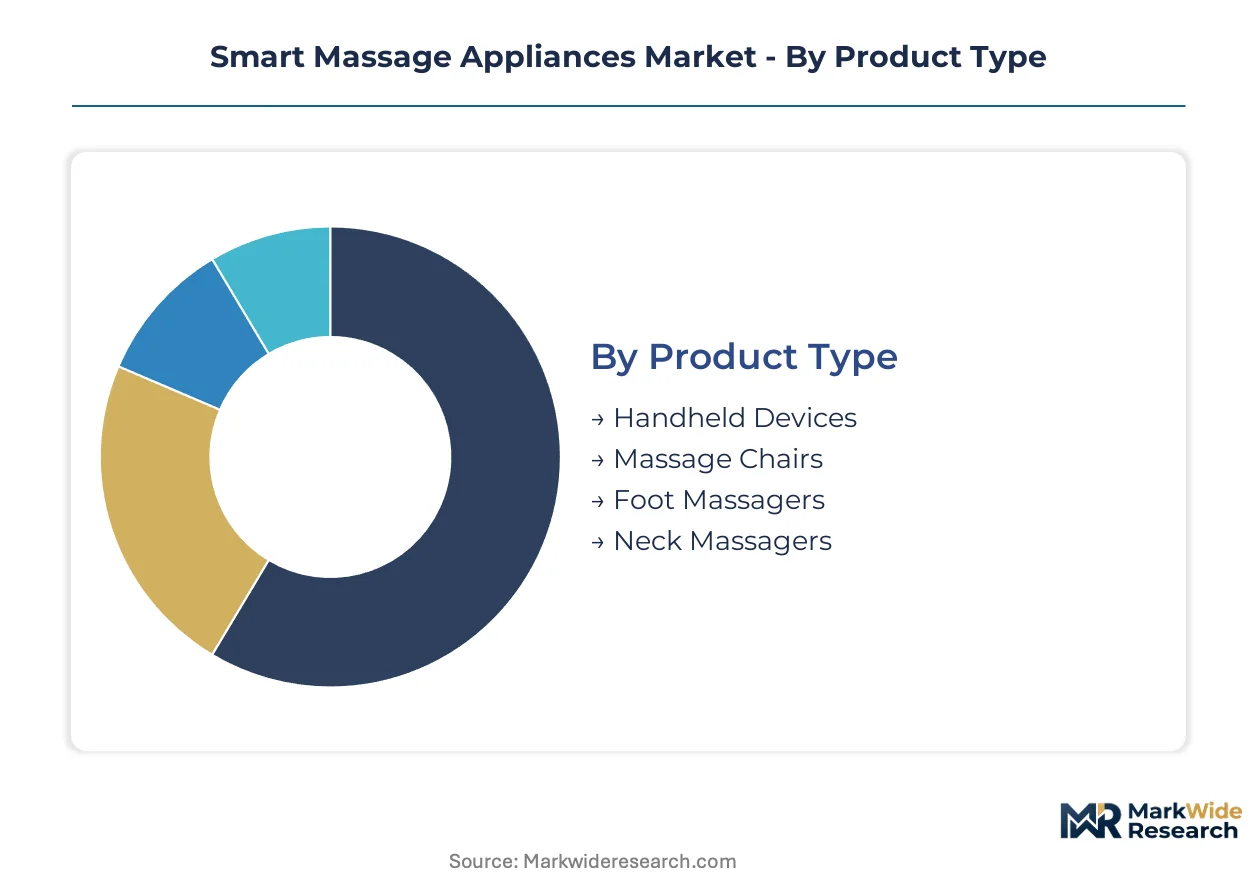
Segmentation in smart massage appliances reveals how technical specifications, connectivity architectures, and procurement contexts reshape competitive boundaries. Manufacturers must align motor performance tiers with distinct recovery protocols while navigating channel-specific certification requirements.
Product Type:
Electromechanical complexity and spatial footprint determine pricing architecture and replacement cycle dynamics across residential and light commercial deployments.
- Massage Chairs:Full-body systems integrate 12–24V DC motor arrays with AI-driven body-scanning calibration and pressure-mapping arrays. Demand concentrates in China's tier-one cities and South Korea's MFDS-regulated therapeutic channel where reimbursement-adjacent positioning accelerates chronic pain patient adoption. Premium pricing sustains despite extended purchase cycles.
- Handheld Devices:Portable percussion units with 3,200 RPM ceiling speeds and stall-force detection above sixty pounds serve marathon runners and CrossFit affiliates specifying post-training circulation protocols. Volume expansion is climbing the fastest among mobile professionals and travel-oriented consumers compressing mid-tier price premiums.
- Foot Massagers:Shiatsu-style roller mechanisms with infrared heating elements target residential wellness routines in Japan's aging demographic clusters.
- Neck Massagers:U-shaped portable designs with integrated heating elements dominate corporate wellness procurement bundling with ergonomic workstation packages.
Mature deployment sits with massage chairs. Newer deployment is concentrated in handheld devices.
Technology:
Connectivity latency and algorithmic personalization capabilities separate premium positioning from commodity substitution in controller architectures.
- Smartphone-Controlled:Bluetooth Low Energy 5.2 integration enables real-time biometric feedback loops synchronizing massage intensity with heart rate variability data from wearables. Demand concentrates among athletes and fitness enthusiasts in EU markets where REACH-compliant component sourcing filters marginal competitors.
- AI-Driven:Machine learning calibration adapts pressure-mapping arrays to individual musculoskeletal topology without manual programming. Adoption is expanding most quickly in South Korea's subscription-enabled content library models bundling physiotherapist-curated recovery protocols.
- Bluetooth-Enabled:Basic pairing functionality persists in budget-tier offerings despite latency limitations constraining real-time feedback applications.
- Vibration Technology:Fixed-frequency motor assemblies without adaptive load sensing occupy entry-level price bands in India's emerging BIS certification pathway.
Established penetration sits with Bluetooth-enabled architectures. Steepest expansion trajectory is concentrated in AI-driven systems.
End User:
Performance specifications and procurement authority diverge sharply between self-directed consumers and institutional specification channels.
- Athletes:Professional sports teams and CrossFit affiliates specify heated percussion devices with programmable RPM profiles, compressing replacement cycles and elevating performance expectations. Demand concentrates in Germany's licensed therapist resistance zones and North American retail channels where brand recognition extends legacy appliance trust into wellness categories.
- Individuals:Self-directed purchasers through online retail channels control majority transaction flow for replacement and upgrade purchases across all connectivity tiers.
- Therapists:Clinical setting adoption faces resistance from licensed massage therapists in Germany and Japan preserving addressable market boundaries.
- Seniors:Chronic pain management positioning in South Korea's MFDS-regulated channel drives reimbursement-adjacent procurement decisions.
Volume concentration sits with individual purchasers. Specification authority is migrating toward athletes.
Distribution Channel:
Channel selection determines certification timeline exposure and customer acquisition cost structures across replacement versus first-purchase contexts.
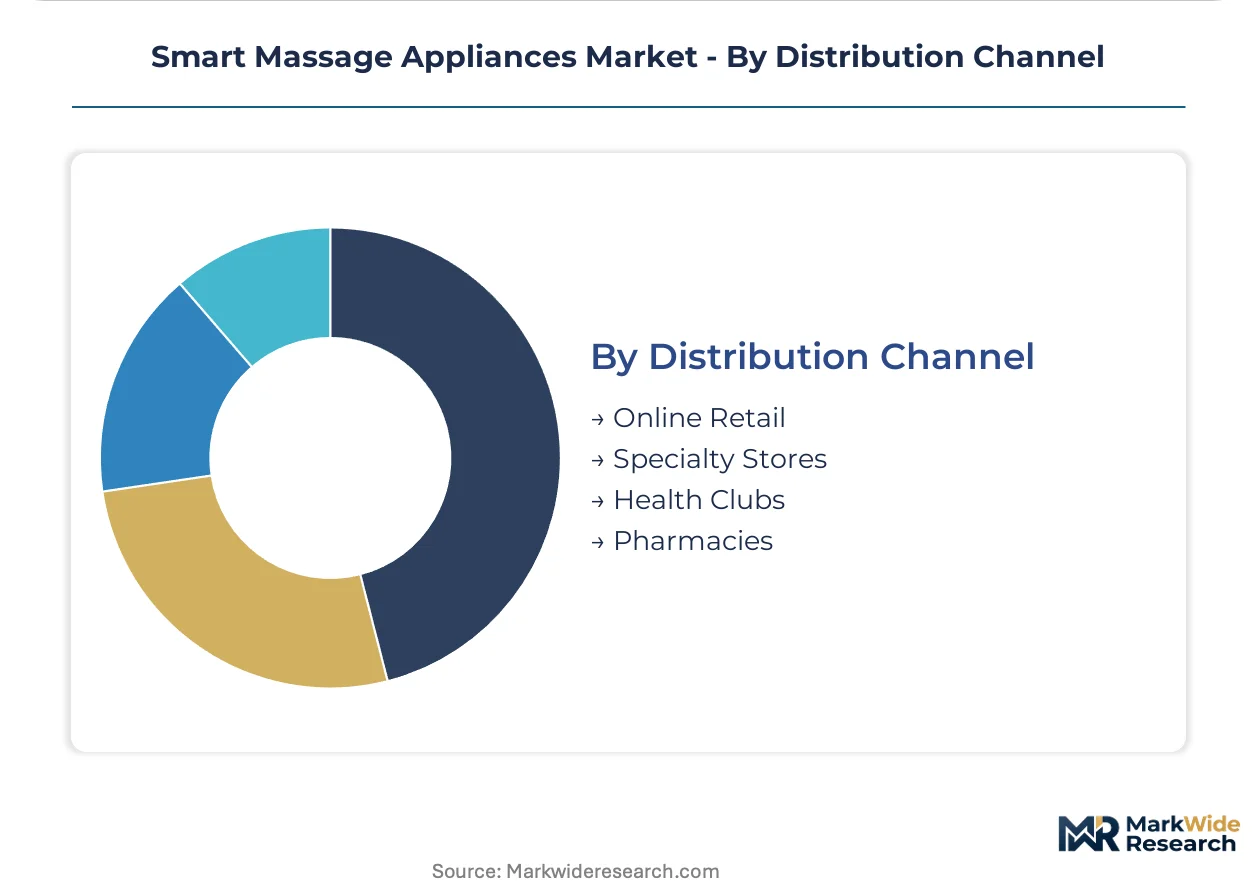
- Online Retail:Platform-controlled transaction flow dominates replacement and upgrade purchases with FCC Part 15 and CE marking documentation requirements embedded in listing protocols. Shenzhen and Dongguan industrial clusters consolidate export-qualified manufacturing capacity serving this channel.
- Specialty Stores:Hands-on demonstration environments support premium chair sales with extended purchase consideration cycles in China's coastal manufacturing clusters.
- Health Clubs:Post-training recovery station deployment targets CrossFit affiliates and professional sports team procurement specifications.
- Pharmacies:Therapeutic claim positioning triggers EU Medical Device Regulation eighteen-month CE marking timelines delaying product launches relative to pure wellness positioning.
Transaction volume sits with online retail. Margin protection is concentrating in specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities and coastal manufacturing clusters concentrate the heaviest demand for smart massage appliances, with recovery-focused wellness culture driving specification upgrades across residential and light commercial deployments.
China
Athletes and fitness enthusiasts in Shanghai and Beijing are compressing replacement cycles for heated percussion devices. GB standards for electrical safety and smart interoperability under MIIT are tightening compliance timelines for manufacturers. Shenzhen and Dongguan industrial clusters consolidate export-qualified production capacity serving both domestic and EU-bound volumes.
United States
CrossFit affiliates and professional sports teams specify programmable RPM profiles for post-training circulation protocols. FCC electromagnetic emissions standards under Part 15 shape certification timelines for Bluetooth-enabled controllers. Los Angeles wellness startups are piloting subscription-enabled content libraries bundling physiotherapist-curated recovery programs.
Germany
Licensed massage therapists in clinical settings resist device adoption, preserving addressable market boundaries for pure wellness positioning. EU Medical Device Regulation triggers eighteen-month CE marking timelines for therapeutic claim classifications. Bavaria's industrial fabricators supply precision motor assemblies for high-torque brushless systems.
South Korea
Chronic pain patients drive reimbursement-adjacent procurement through MFDS-regulated therapeutic device channels. Seoul-based wellness startups are bundling hardware financing with AI-driven body-scanning calibration. The capital region concentrates subscription-enabled content library deployment for premium chair segments.
India
Corporate wellness procurement at technology firms bundles portable neck massagers with ergonomic workstation stipends for remote employees. BIS certification requirements add compliance layers for manufacturers targeting Asia's second-largest consumer base. Mumbai and Bengaluru laboratories are establishing testing relationships with early movers seeking premium positioning.
Smart Massage Appliances Market Competitive Landscape
Shenzhen-based producers anchor the export-qualified manufacturing tier; North American and European specialists hold brand recognition positions in retail and therapeutic channels. The vendor structure fragments across three tiers: integrated manufacturers with captive component sourcing, brand licensors extending legacy appliance trust, and pure-play specialists in portable form factors. Strategic moves concentrate on geographic certification stacking and subscription-enabled content library development.
Among China-based fabricators, SKG leverages its Shenzhen manufacturing base to navigate regulatory layers while sustaining export volumes. Breo exemplifies deep specialization in portable form factors with integrated heating elements. Westinghouse occupies a position extending legacy appliance brand recognition into wellness categories across North American retail channels.
| Leading Market Players |
|---|
| SKG |
| Breo |
| Jingdong Jingzao |
| Bear |
| KENTRO |
| Hommy |
| YESOUL |
| Shangheng |
| Westinghouse |
| Others |
Pricing and Supply Chain Analysis
Bluetooth Low Energy 5.2 integration is compressing cost economics for real-time biometric feedback controllers while simultaneously concentrating qualified manufacturing capacity in Shenzhen and Dongguan industrial clusters. This dual effect is reshaping margin structures across premium and mid-tier positioning as REACH-compliant component sourcing filters marginal competitors from EU-bound export channels.
Pricing Analysis
Volume concentration sits with handheld percussion devices while margin protection concentrates in AI-driven massage chair systems. Three-tier pricing structure across premium, standard, and economy levels separates subscription-enabled content library bundles from basic Bluetooth-enabled units. Price differentiation hinges on certification grade—EU MDR therapeutic claim positioning commands eighteen-month CE marking premiums against pure wellness positioning. Cost compression in mid-tier handheld segments is intensifying because stall-force detection above sixty pounds has become a baseline specification. Individual purchasers through online retail channels exhibit highest price sensitivity, whereas corporate wellness procurement at technology firms shows lowest sensitivity due to ergonomic workstation bundling.
Supply Chain Analysis
Single-source vulnerability sits with neodymium magnet processing concentration in China's Inner Mongolia region, creating input cost volatility for high-torque brushless motor assemblies. Component sourcing draws from China, South Korea, and Japan for precision motor controllers, pressure-mapping arrays, and polymer formulations. Raw material dependencies include rare earth magnets, lithium-ion cells for portable units, and REACH-compliant polymer compounds. Regulatory restriction risk runs through evolving EU Medical Device Regulation boundary definitions that could trigger wholesale software validation protocol redesigns. Distribution runs through online retail platforms dominating replacement and upgrade purchases, with specialty stores protecting premium chair margins through hands-on demonstration environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart massage appliances represent a consolidation play as REACH compliance and GB standard interoperability requirements force simultaneous redesigns across product portfolios, squeezing out manufacturers lacking Shenzhen-based export-qualified capacity.
For Market Incumbents: Hedge against neodymium supply volatility through captive relationships with Inner Mongolia processors or alternative motor topology development. Deepen backward integration into pressure-mapping array production to protect margin structures from component cost swings. Accelerate AI-driven body-scanning calibration R&D to maintain premium positioning against mid-tier compression. For New Entrants and Emerging Players: Launch via direct-to-corporate wellness procurement channels bundling portable neck massagers with remote employee ergonomic stipends. Target India's BIS certification pathway through early testing relationships with Mumbai and Bengaluru laboratories before domestic manufacturing scales. Penetrate South Korea's subscription-enabled content library segment through physiotherapist-curated recovery protocol partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated wellness platform operators seeking hardware financing bundling capabilities. Five-to-ten year viability favors manufacturers with simultaneous GB 4706.1, FCC Part 15, and EU MDR certification stacking. Watch for MFDS therapeutic device reclassification signals as inflection indicators for reimbursement-adjacent positioning expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 36972 Interoperability Compliance | Open API architectures break proprietary control app silos across Xiaomi, Huawei, and Tuya platforms. |
| Subscription-Enabled Content Library Launch | Peloton-style membership models from Seoul and Los Angeles startups bundle physiotherapist-curated recovery protocols. |
| India BIS Certification Stacking | Early movers establishing Mumbai and Bengaluru laboratory relationships capture premium positioning before domestic scale. |
| AI-Driven Body-Scanning Integration | Machine learning calibration adapts pressure-mapping arrays to individual musculoskeletal topology without manual programming. |
| Corporate Wellness Procurement Partnership | Technology firm HR departments bundle portable neck massagers with ergonomic workstation packages for remote employees. |
Research Methodology
Trade databases, regulatory filing repositories, and customs records formed the secondary backbone for supply chain mapping and certification timeline analysis. Primary interviews with product development executives at Shenzhen-based manufacturers, regulatory affairs leads navigating EU MDR and REACH compliance, procurement managers at CrossFit affiliates and professional sports teams, and biomedical engineers specifying clinical setting equipment were combined with secondary validation. Bottom-up and top-down triangulation cross-checked shipment volumes against production capacity disclosures.
Bottom-up modeling anchored volume projections in motor assembly sourcing patterns and replacement cycle compression among athlete segments, while top-down validation tested aggregate figures against wellness category spending trends. Segmentation dimensions included product type complexity tiers, connectivity architecture generations, end-user procurement authority levels, and channel-specific certification requirements. CAGRs were derived from fitted growth curves calibrated to GB standard implementation timelines and Bluetooth Low Energy adoption S-curves. Key forecast inputs included neodymium price volatility indices and MFDS therapeutic device channel reimbursement policy evolution.
Raw material supply disruption, regulatory reclassification between wellness and medical device categories, and consumer discretionary spending contraction are the dominant revision risks across the projection horizon. Forecasts reflect documented assumptions about certification timeline standardization and interoperability mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Laundry Kiosk Market
Appliances
Mexico Washing Machine Market
Appliances
Europe Induction Hobs Market
Appliances
Global Massage Chairs Market
Appliances
Qatar Microwave Ovens Market
Appliances
Electric Yogurt Maker Market
Appliances
Laundry Dryer Market
Appliances
Refrigerator Door Seal Market
Appliances
Small Electric Kettles Market
Appliances
Colombia Appliances and Electronics Market
Appliances
Europe Garment Steamers Market
Appliances
Germany Consumer Appliances Market
Appliances
Large Cooking Appliance Market
Appliances
North America Microwave Oven Market
Appliances
Middle East Water Heater Market
Appliances
Mobile Refrigerators Market