
 UK Pet Nutraceuticals Market | 2026-2036
UK Pet Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pet Nutraceuticals Market Insights
Veterinary clinics is realigning the UK Pet Nutraceuticals Market as professional endorsement channels gain priority over retail self-selection. Mars, Incorporated leverages its veterinary practice networks to channel prescription-grade supplements through certified clinicians. Dechra Pharmaceuticals PLC anchors its position through pharmaceutical-grade manufacturing standards that satisfy VMD compliance thresholds.
Pet nutraceuticals comprise bioactive compounds including vitamins, minerals, probiotics, and omega fatty acids formulated in tablets, powders, chews, and liquids to support physiological functions beyond basic nutrition. These products undergo cold-press or extrusion processes to preserve microbial viability in probiotic strains. Omega fatty acids dominate current revenue pools due to established veterinary consensus on dermatological and joint benefits, while probiotics represent the fastest-expanding category as gut-brain axis research advances. Chews command premium shelf positioning in specialty pet shops, whereas powders gain traction among cat owners seeking meal-topping flexibility.
The Veterinary Medicines Directorate and Food Standards Agency jointly govern ingredient safety and health claim substantiation, with VMD oversight intensifying for products crossing into medicinal thresholds. FSA labeling requirements now mandate quantitative nutritional declarations that expose formulation disparities between premium and economy tiers. Stakeholders must monitor pending VMD consultations on novel ingredient classifications, as reclassification would force reformulation investments or route restrictions through veterinary prescription channels.
Market Dynamics
The UK Pet Nutraceuticals Market is restructuring around veterinary channel capture, as clinic dispensing programs displace retail self-selection and professional endorsement becomes the primary trust mechanism for functional ingredient purchases.
Growth Catalysts
- Veterinary dispensing expansion:Clinic networks are building in-house supplement programs that channel prescription-grade products through certified clinicians, creating professional gatekeeper relationships that retail channels cannot replicate.
- FSA-VMD joint guidance:Tightening substantiation requirements for health claims are filtering out unsubstantiated economy-tier competitors and elevating products with pharmaceutical-grade documentation.
- Gut-brain axis research:Advancing microbiome science is accelerating probiotic category expansion as veterinary consensus builds around behavioral and cognitive benefits beyond digestive health.
Market Restraints
- Omega-3 input cost volatility:Marine lipid supply chains face pressure from fishery quota restrictions and climate-driven stock fluctuations, compressing margins for fish-oil-based formulations.
- VMD reclassification risk:Pending consultations on novel ingredient thresholds could force route restrictions through veterinary prescription channels, raising distribution costs for functional chews and powders.
- Human supplement substitution:Cost-conscious owners repurpose human-grade omega and probiotic products for companion animals, bypassing pet-specific formulation premiums entirely.
Strategic Opportunities
- Greater London premium concentration:Ownership rates for insured, high-spending companion animals in the South East exceed national benchmarks, creating concentrated demand pools for subscription-based supplement delivery.
- Meal-topping powder formats:Cat owner preferences for flexible dosing and palatability masking present white space for microencapsulated probiotic powders with extended shelf stability.
- Cold-chain probiotic viability:Advances in lyophilization and moisture-barrier packaging are enabling ambient-stable formulations that reduce veterinary clinic inventory complexity.
Industry Challenges
- Veterinary nutrition specialist scarcity:Clinic dispensing programs require staff trained in supplement-drug interaction protocols, and qualified candidates remain concentrated in specialist referral hospitals.
- Dual-agency compliance timelines:Products crossing FSA food and VMD medicinal thresholds face parallel review processes that extend time-to-market by 8-14 months versus single-jurisdiction launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pet Nutraceuticals Market |
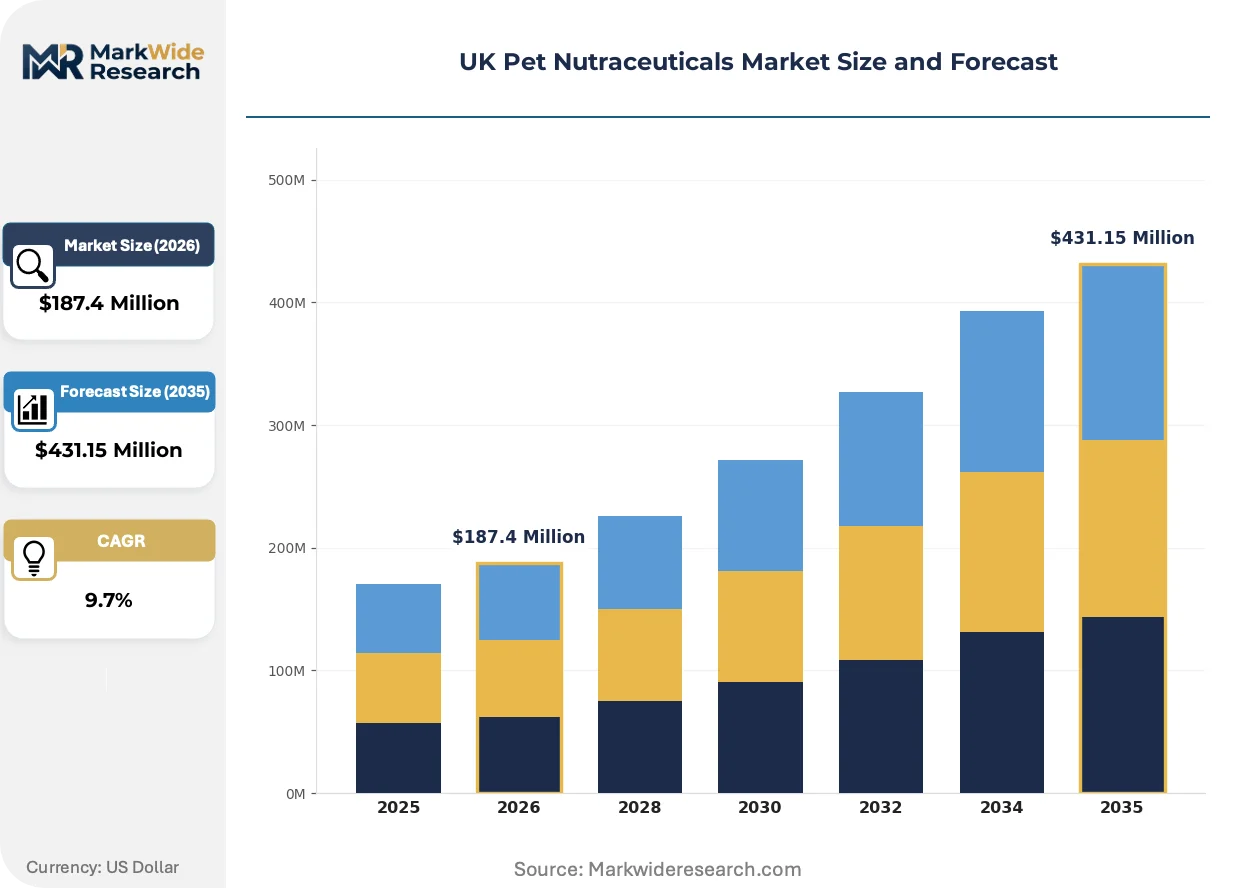
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Omega Fatty Acids End User: Dog Owners, Cat Owners, Veterinary Clinics, Pet Stores Distribution Channel: Online Stores, Retail Pharmacies, Supermarkets, Specialty Pet Shops Formulation: Tablets, Powders, Chews, Liquids |
| Companies Covered | Mars, Incorporated, Nestlé Purina PetCare, Vetoquinol SA, Virbac SA, Alltech, Inc., Dechra Pharmaceuticals PLC, Nutramax Laboratories, Inc., Elanco Animal Health Incorporated, Hill's Pet Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pet Nutraceuticals Market Trends and Innovations
Formulation science and channel control are converging to reshape how bioactive compounds reach companion animals, with preservation technology and professional gatekeeping emerging as the decisive competitive axes.
Lyophilized probiotic strains with moisture-activated reconstitution are overtaking traditional freeze-dried formats in veterinary clinic procurement. Specialist prescribers are prioritizing ambient-stable formulations that eliminate cold-chain dependencies without sacrificing colony-forming unit counts. This preservation advance is compressing the addressable market for refrigerated probiotics while expanding rural clinic access.
The Veterinary Medicines Directorate's pending novel ingredient consultation is forcing reformulation investments across the omega fatty acid segment. Manufacturers must pre-substantiate anti-inflammatory claims with clinical trial data or accept prescription-only distribution routes. Small-batch domestic producers in Yorkshire and the Midlands are accelerating VMD pre-submission dialogues to secure grandfathered status.
Subscription direct-to-owner models are displacing intermittent retail purchases among insured pet households in Greater London and the South East. Digital veterinary platforms are bundling supplement recommendations with telehealth consultations, capturing recurring revenue streams that physical specialty shops cannot match. This channel migration is most visible among millennial and Generation Z owners of brachycephalic breeds with chronic dermatological needs.
UK Pet Nutraceuticals Market Segmentation
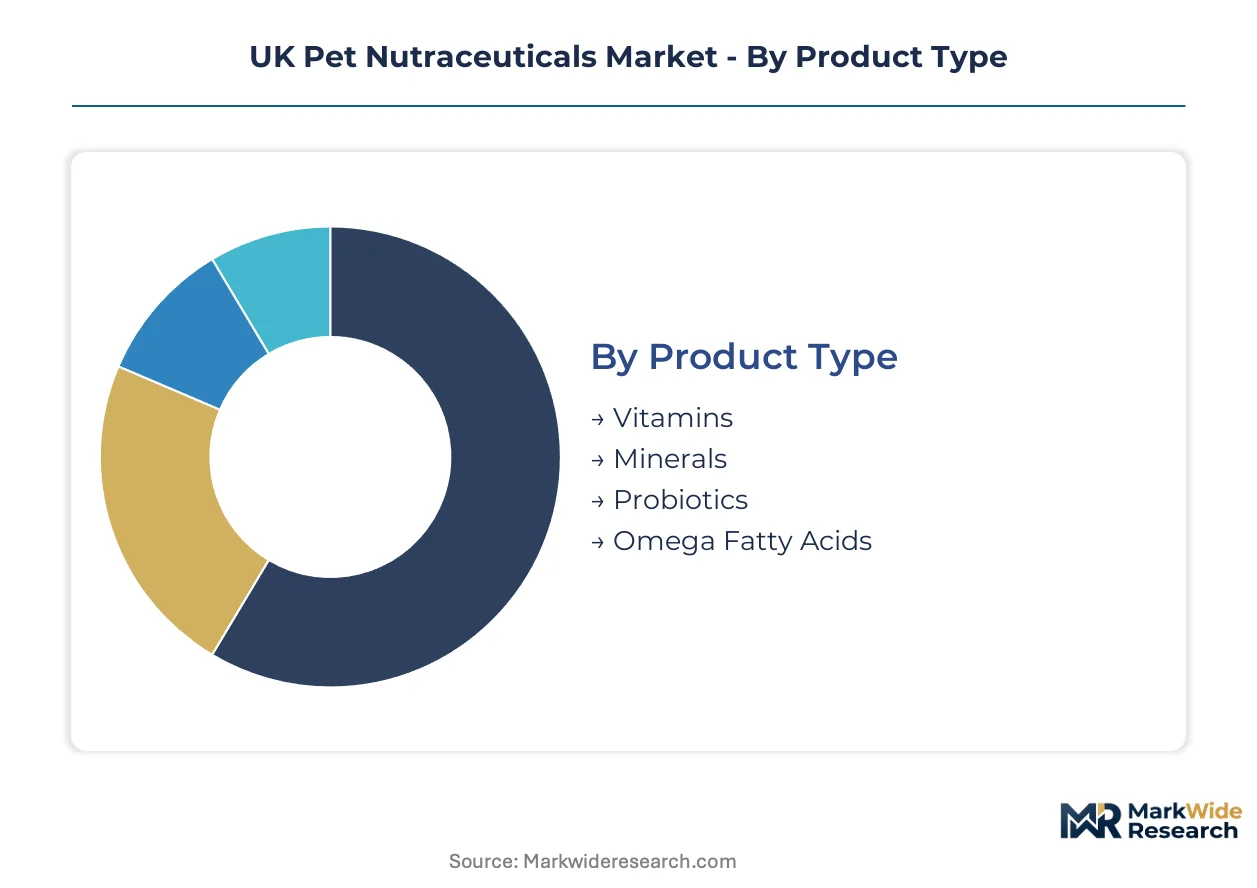
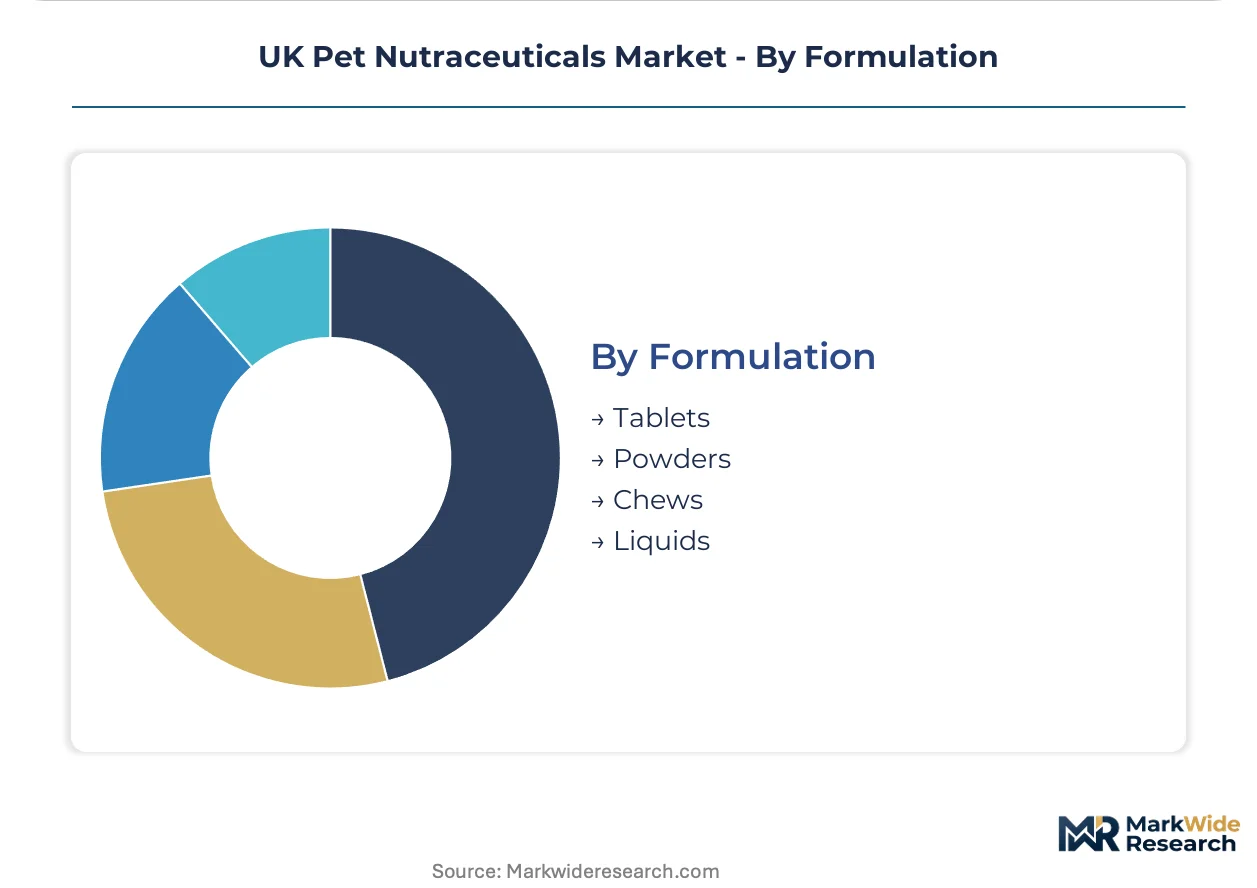
Segmentation in the UK Pet Nutraceuticals Market reveals how formulation science, channel control, and species-specific dosing requirements create distinct competitive arenas. Manufacturers must align product architecture with veterinary dispensing workflows and owner administration preferences to capture value.
Product Type:
Upgrade cycles in companion animal supplementation follow veterinary consensus formation, with clinicians driving switching behavior through prescription protocols and professional endorsement.
- Omega Fatty Acids:Marine-derived EPA and DHA formulations dominate current revenue pools due to established dermatological and osteoarthritis protocols in canine practice. Demand concentrates in insured dog households across Greater London and the South East, where veterinary specialists prescribe therapeutic-grade fish oil for chronic inflammatory conditions. FSA-VMD joint guidance on anti-inflammatory claim substantiation is forcing manufacturers to pre-validate efficacy data or accept prescription-only distribution routes.
- Probiotics:Multi-strain formulations targeting the gut-brain axis represent the steepest expansion trajectory as microbiome research advances behavioral applications beyond digestive health. Yorkshire and Midlands-based producers are accelerating VMD pre-submission dialogues to secure ambient-stable lyophilized formats for clinic dispensing programs.
- Vitamins:Single and multi-vitamin complexes address deficiency correction in homemade and raw-fed diets, with cat owners in urban centers driving tablet and powder demand.
- Minerals:Calcium, phosphorus, and trace element supplements support skeletal development in large-breed puppies and renal diet management in senior cats.
Omega Fatty Acids sits at the top of the volume ranking, with Probiotics climbing the fastest.
End User:
Cost tier differentiation separates insured households with veterinary channel access from self-directed purchasers navigating retail complexity.
- Veterinary Clinics:Professional gatekeepers channel prescription-grade supplements through certified clinicians, building recurring revenue through dispensing programs that retail cannot replicate. Clinic networks in specialist referral hospitals concentrate qualified nutrition staff capable of managing supplement-drug interaction protocols.
- Dog Owners:Brachycephalic breed households with chronic dermatological needs drive subscription-based omega fatty acid purchases through digital veterinary platforms bundling telehealth consultations.
- Cat Owners:Meal-topping flexibility preferences favor microencapsulated probiotic powders with extended shelf stability, particularly among urban multi-cat households.
- Pet Stores:Specialty shops retain relevance for economy-tier vitamin and mineral sales, though professional endorsement channels are displacing self-selection for functional ingredients.
Veterinary Clinics command the premium tier by margin, with Dog Owners delivering the largest absolute volume base.
Distribution Channel:
Supply concentration in digital infrastructure is compressing physical retail relevance as subscription models capture recurring purchasing behavior.
- Online Stores:Direct-to-owner subscription platforms displace intermittent retail purchases among insured millennial and Generation Z pet owners. Digital veterinary platforms bundle supplement recommendations with telehealth consultations, capturing recurring revenue streams.
- Specialty Pet Shops:Premium chew formats retain shelf positioning for impulse purchases and palatability trials, though clinic dispensing programs erode their functional ingredient share.
- Retail Pharmacies:Human supplement crossover creates substitution risk as cost-conscious owners repurpose omega and probiotic products for companion animals.
- Supermarkets:Economy-tier vitamin and mineral tablets serve price-sensitive owners of small companion animals with basic nutritional needs.
Online Stores are expanding most quickly by transaction velocity, with Specialty Pet Shops defending the highest average transaction value.
Formulation:
Application-driven format selection reflects species-specific administration challenges and owner compliance constraints.
- Chews:Palatable extruded formats command premium positioning in specialty pet shops and veterinary clinic lobbies, with palatability masking enabling consistent dosing in finicky eaters.
- Powders:Microencapsulated probiotic formulations with moisture-activated reconstitution gain traction among cat owners seeking meal-topping flexibility without volume displacement.
- Tablets:Precision dosing and extended shelf stability support vitamin and mineral applications in multi-pet households with varied supplementation needs.
- Liquids:High-bioavailability omega fatty acid suspensions enable titrated dosing for therapeutic applications in large-breed dogs with joint degeneration.
Chews hold the volume leadership position, with Powders gaining share fastest among feline-focused formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined compliance pathways. The UK's dual-agency oversight creates cost-of-compliance gaps that favor domestic formulation against cross-border importation.
Greater London and the South East
Insured companion animal density exceeds national benchmarks across metropolitan clusters, with subscription-based supplement penetration highest in Kensington, Chelsea, and Surrey postal districts. The VMD's London headquarters proximity accelerates pre-submission dialogue for novel ingredient classifications. Specialist veterinary referral hospitals in North London and the M4 corridor concentrate qualified nutrition staff capable of managing complex dispensing programs.
Midlands
Yorkshire and East Midlands cold-press manufacturing clusters supply lyophilized probiotic formulations to veterinary clinic networks nationwide. FSA labeling enforcement from Birmingham regional offices mandates quantitative nutritional declarations that expose formulation tier disparities. Leicester and Nottingham packaging specialists develop moisture-barrier technologies for ambient-stable microencapsulated powders.
North England
Manchester and Leeds urban centers drive demand for meal-topping flexibility formats among multi-cat households in dense rental accommodations. The VMD's regional inspectorate maintains stricter surveillance of cross-border omega-3 imports through Hull and Immingham ports. Newcastle veterinary schools anchor research partnerships with local manufacturers on gut-brain axis applications.
Scotland
Aberdeen and Edinburgh veterinary practices lead adoption of pharmaceutical-grade manufacturing standards for prescription-channel supplements. Marine lipid processors on the Scottish coast face fishery quota pressures that compress input costs for EPA and DHA formulations. Scottish Government rural development programs support cold-chain infrastructure for probiotic distribution to Highland clinic networks.
Wales
South Wales manufacturing corridors specialize in extruded chew formats for palatability-driven canine compliance. The FSA Wales office coordinates with VMD on joint guidance implementation for cross-jurisdictional products. Cardiff and Newport logistics hubs service rural veterinary practices with ambient-stable formulation deliveries.
UK Pet Nutraceuticals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade documentation requirements favoring integrated players over outsourced formulation. The vendor base concentrates around three tiers: multinational pet care conglomerates with veterinary practice networks, domestic pharmaceutical-grade specialists, and regional cold-press manufacturers. Strategic moves center on VMD pre-submission dialogues for novel ingredient grandfathering and subscription platform acquisitions for direct-to-owner channel control.
Within the pharmaceutical-grade tier, Dechra Pharmaceuticals PLC exemplifies compliance-first positioning through VMD manufacturing standard adherence. Mars, Incorporated anchors the integrated conglomerate archetype with veterinary channel capture capabilities. Among North American specialists, Nutramax Laboratories, Inc. and Elanco Animal Health Incorporated occupy positions that represent the prescription-grade supplement segment's competitive density.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Nestlé Purina PetCare |
| Vetoquinol SA |
| Virbac SA |
| Alltech, Inc. |
| Dechra Pharmaceuticals PLC |
| Nutramax Laboratories, Inc. |
| Elanco Animal Health Incorporated |
| Hill's Pet Nutrition |
| Others |
Pricing and Supply Chain Analysis
Veterinary dispensing program expansion is compressing retail markup layers and forcing manufacturers to absorb cold-chain logistics costs for ambient-stable formulations. This procurement shift concentrates buying power with clinic networks while squeezing margin structures for economy-tier competitors lacking pharmaceutical-grade documentation.
Pricing Analysis
Clinic dispensing markups command premium positioning through professional endorsement channels that retail self-selection cannot replicate. Three-tier pricing structure across pharmaceutical-grade, veterinary-certified, and economy levels separates products by VMD compliance depth and clinical trial substantiation. Pricing pressure stems from human supplement substitution as cost-conscious owners repurpose omega and probiotic products for companion animals. Dog owners in insured households show lowest price sensitivity, while cat owners purchasing meal-topping powders exhibit moderate elasticity.
Supply Chain Analysis
Marine lipid supply rests on Norwegian and Peruvian fishery processors facing quota restrictions and climate-driven stock fluctuations. Lyophilized probiotic strains draw from Yorkshire and Midlands cold-press manufacturing clusters with domestic packaging specialization. Single-source vulnerability concentrates in omega-3 inputs where fishery quota compression creates input cost volatility. Distribution runs through veterinary clinic networks for prescription-grade products, with direct-to-owner subscription platforms capturing recurring revenue from insured households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Pet Nutraceuticals Market compounds value through regulatory tightening, with FSA-VMD joint guidance on health claim substantiation driving demand toward documented, pharmaceutical-grade products that economy-tier competitors cannot supply.
For Market Incumbents: Anticipate VMD reclassification consultations by accelerating pre-submission dialogues for novel ingredient grandfathering and securing ambient-stable lyophilized formats. Backward integration into Yorkshire and Midlands cold-press manufacturing clusters reduces dependency on outsourced probiotic preservation. Channel control through veterinary practice network acquisitions defends margin position against retail erosion. For New Entrants and Emerging Players: Launch via subscription direct-to-owner platforms targeting Greater London and South East insured households with microencapsulated probiotic powders for meal-topping flexibility. White space concentrates in cat-focused ambient-stable formulations where incumbent veterinary channels underpenetrate urban multi-cat households. Go-to-market angle should bundle telehealth consultation access with recurring supplement delivery. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic pharmaceutical-grade specialists possessing VMD manufacturing standard adherence and pre-submission dialogue track records. Five-to-ten year viability favors integrated players over outsourced formulation given tightening substantiation requirements. Signal to watch is pending VMD novel ingredient consultation outcomes that would force route restrictions and consolidate share among compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| VMD Pre-Submission Dialogue | Secures grandfathered status for novel ingredients before consultation closes. |
| Ambient-Stable Formulation Investment | Eliminates cold-chain costs and expands rural clinic network access. |
| Veterinary Channel Acquisition | Captures professional gatekeeper relationships that retail cannot replicate. |
| Subscription Platform Buildout | Locks recurring revenue from insured millennial and Generation Z households. |
| Backward Integration into Manufacturing | Controls lyophilization capacity and reduces outsourced preservation dependency. |
Research Methodology
Bottom-up veterinary clinic dispensing modeling reconciled against top-down omega fatty acid and probiotic supply tracking forms the analytical core. Primary interviews with veterinary nutrition specialists, clinic procurement managers, FSA compliance officers, and pet food formulation scientists combined with secondary validation from VMD consultation documents, FSA labeling guidance, customs import records, and veterinary practice network disclosures. Triangulation across stakeholder inputs and regulatory filings ensures coverage of both demand-side channel shifts and supply-side compliance investments.
Input-output matrices project volume and value across the analysis window by segmenting product type, end user, distribution channel, and formulation format. CAGRs derive from veterinary dispensing program penetration curves, gut-brain axis research adoption timelines, and FSA-VMD joint guidance implementation schedules. Modeled inputs include marine lipid supply quota fluctuations, lyophilization capacity expansion in Yorkshire and Midlands clusters, and subscription platform customer acquisition costs.
Several conditions sit outside the modeled scope, including unforeseen VMD reclassification decisions, fishery quota policy reversals, and macroeconomic shocks to pet insurance penetration. Forecasts reflect assumptions about regulatory timeline adherence and veterinary specialist hiring rates. A small set of named triggers warrants ongoing watch: VMD novel ingredient consultation outcomes, Scottish marine processor consolidation, and human supplement crossover elasticity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Cognitive Health Ingredients Market