
 Cissus Quadrangularis Market | 2026-2036
Cissus Quadrangularis Market Size, Share, and Industry Trends Forecast 2026-2036
Cissus Quadrangularis Market Outlook
Aftermarket service revenue around quality certification and third-party testing is fragmenting across the Cissus Quadrangularis value chain. VitaJing leverages its direct-to-practitioner channel to sustain premium positioning in clinical-grade extracts. Double Wood Supplements anchors its North American presence through rigorous COA transparency and Amazon-native fulfillment infrastructure. Barlowe's Herbal Elixirs differentiates via small-batch sourcing relationships with Indian cultivators in Gujarat and Rajasthan.
Cissus Quadrangularis is a perennial vine of the Vitaceae family, containing bioactive ketosteroids and flavonoids concentrated in its dried stem segments; standardized extracts typically quantify 2.5-5% ketosteroids by gravimetric assay for joint-support and bone-density applications. Dietary Supplements command the largest revenue share due to sustained consumer spending on musculoskeletal wellness, while Extracts outpace Pills and Powders in margin contribution because of higher bioactive concentration and dosage flexibility. The Distribution Channel dimension shows Online Retail capturing incremental volume from fitness enthusiasts, though Pharmacies retain stronger trust signals among healthcare providers prescribing botanical protocols.
The US FDA's New Dietary Ingredient notification requirements and India's FSSAI licensing framework for herbal products create divergent compliance cost structures that filter market entrants by capital depth. ISO 17025 accreditation for analytical laboratories has become a de facto gate for contract manufacturing partnerships with nutraceutical brands. Stakeholders must monitor evolving pharmacovigilance obligations in export destination markets before committing to capacity expansion or cultivator contract structures.
Market Dynamics
Clean-label botanical certification is concentrating procurement power among nutraceutical brands with captive testing infrastructure, forcing smaller extract suppliers to absorb compliance costs or exit contract manufacturing partnerships entirely.
Growth Catalysts
- India's PLI scheme for herbal products:The production-linked incentive framework subsidizes standardized extract capacity expansion in Gujarat and Rajasthan cultivation clusters. Domestic manufacturers leverage this to bid for North American nutraceutical contracts.
- Ketosteroid quantification by HPLC-UV:Analytical standardization at 2.5-5% bioactive concentration enables shelf-stable claims for joint-support formulations. Sports nutrition brands adopt these specifications for pre-workout recovery SKUs.
- Sports nutrition channel expansion:Functional food manufacturers in Thailand and Vietnam integrate Cissus Quadrangularis into protein fortification lines. Southeast Asian gym chains now stock botanical recovery products at point-of-sale.
Market Restraints
- Wild-harvest stem supply volatility:Monsoon-dependent collection in India's Western Ghats creates 15-20% annual yield variation. Extractors cannot hedge input costs through futures markets.
- US FDA NDI notification backlog:New Dietary Ingredient pre-market submissions face 180-day review timelines. Smaller suppliers lack capital reserves to sustain revenue gaps during approval windows.
- Collagen peptide substitution:Hydrolyzed bovine and marine collagen dominate bone-density supplement shelves. Cissus extracts compete for identical shelf positioning without equivalent consumer awareness.
Strategic Opportunities
- Veterinary osteoarthritis applications:Equine supplement manufacturers seek botanical alternatives to NSAIDs for joint maintenance. Kentucky and Florida racing stables represent untested demand pockets.
- Direct-to-practitioner telehealth channels:Integrative medicine platforms prescribe clinical-grade extracts for post-fracture rehabilitation. Practitioners bypass retail markup through wholesale purchasing portals.
- EU Novel Food authorization pathway:EFSA's 2023 guidance on traditional food from third countries creates expedited market entry for documented usage histories. Indian suppliers with Ayurvedic documentation access this route.
Industry Challenges
- ISO 17025 analytical talent scarcity:Contract laboratories capable of ketosteroid gravimetric assay command premium rates. Brands face six-month queues for certificate-of-analysis turnaround.
- Phytochemical batch consistency:Stem segment drying protocols vary across Gujarat cooperatives. Standardized extract potency drifts beyond label claim tolerances without in-process controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cissus Quadrangularis Market |
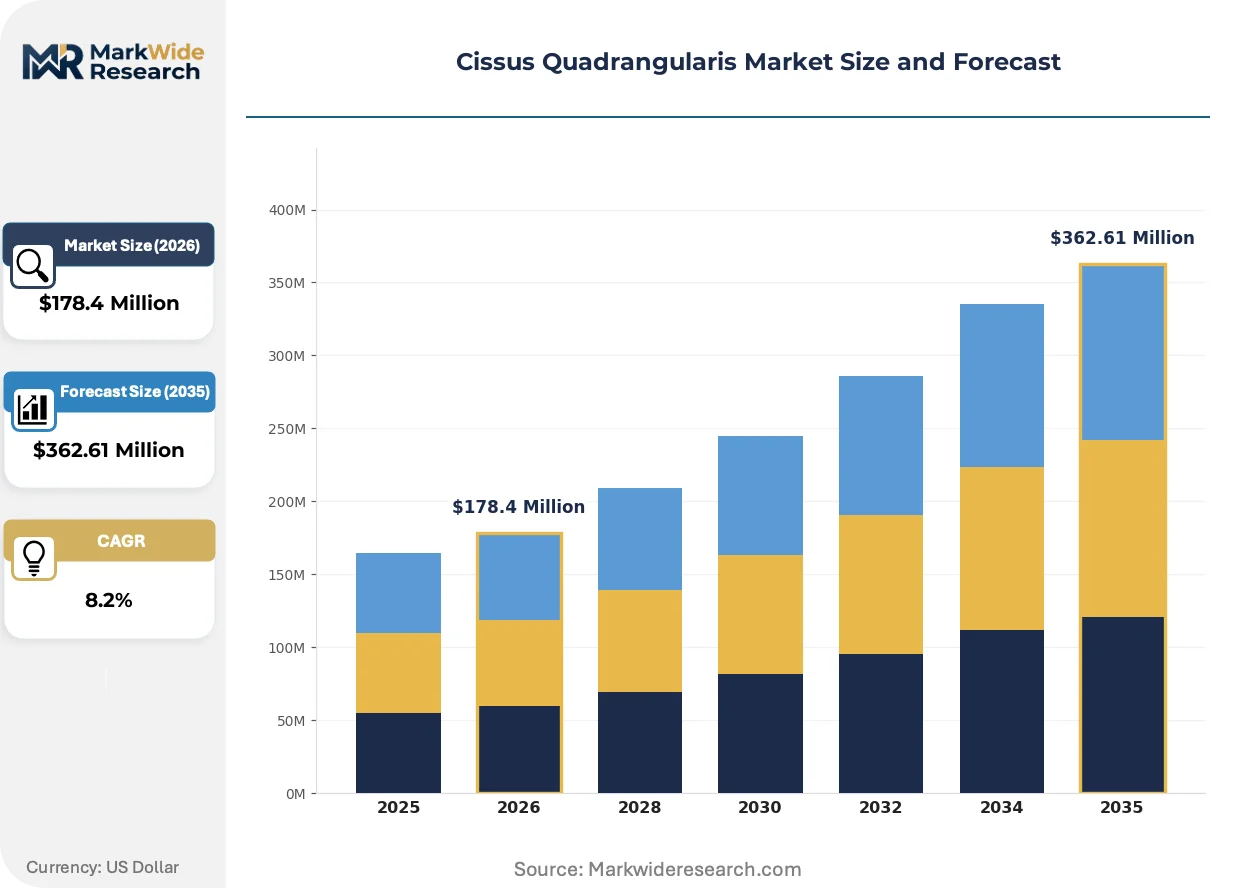
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $362.61 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Dietary Supplements, Food Additives, Herbal Remedies, Pharmaceuticals Product Type: Pills, Powders, Extracts, Capsules End User: Healthcare Providers, Nutraceutical Companies, Retail Consumers, Fitness Enthusiasts Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | VitaJing, Barlowe's Herbal Elixirs, Double Wood Supplements, bixa BOTANICAL, Keter Wellness, True Nutrition, Activa Naturals, VitaMonk, LongLifeNutri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cissus Quadrangularis Market Strategic Shifts
Supercritical CO2 extraction and blockchain-enabled provenance tracking are compressing traditional solvent-based processing and paper-based chain-of-custody documentation. These shifts favor capitalized operators with integrated quality infrastructure.
Supercritical CO2 extraction systems operate at 35-50°C and 100-300 bar pressure, preserving heat-labile flavonoid profiles while eliminating residual solvent contamination. North American contract manufacturers retrofit existing botanical lines to accommodate this equipment. Conventional ethanol maceration is rendering obsolete for premium supplement tiers where clean-label positioning commands 40% price premiums.
India's FSSAI licensing framework now mandates Good Manufacturing Practice audits for herbal product export authorization. The 2024 amendment requires real-time adverse event reporting through a centralized pharmacovigilance portal. Dietary supplement exporters to the United States must maintain dual compliance documentation, increasing administrative overhead but filtering counterfeit supply from unlicensed traders.
Practitioner-grade procurement now bypasses traditional distribution intermediaries through direct API-access platforms. Functional medicine clinics in Texas and California purchase bulk extract for in-house compounding. Amazon-native fulfillment, while capturing fitness-enthusiast volume, loses high-margin clinical accounts to specialized botanical wholesalers with pharmacist consultation support.
Cissus Quadrangularis Market Segmentation
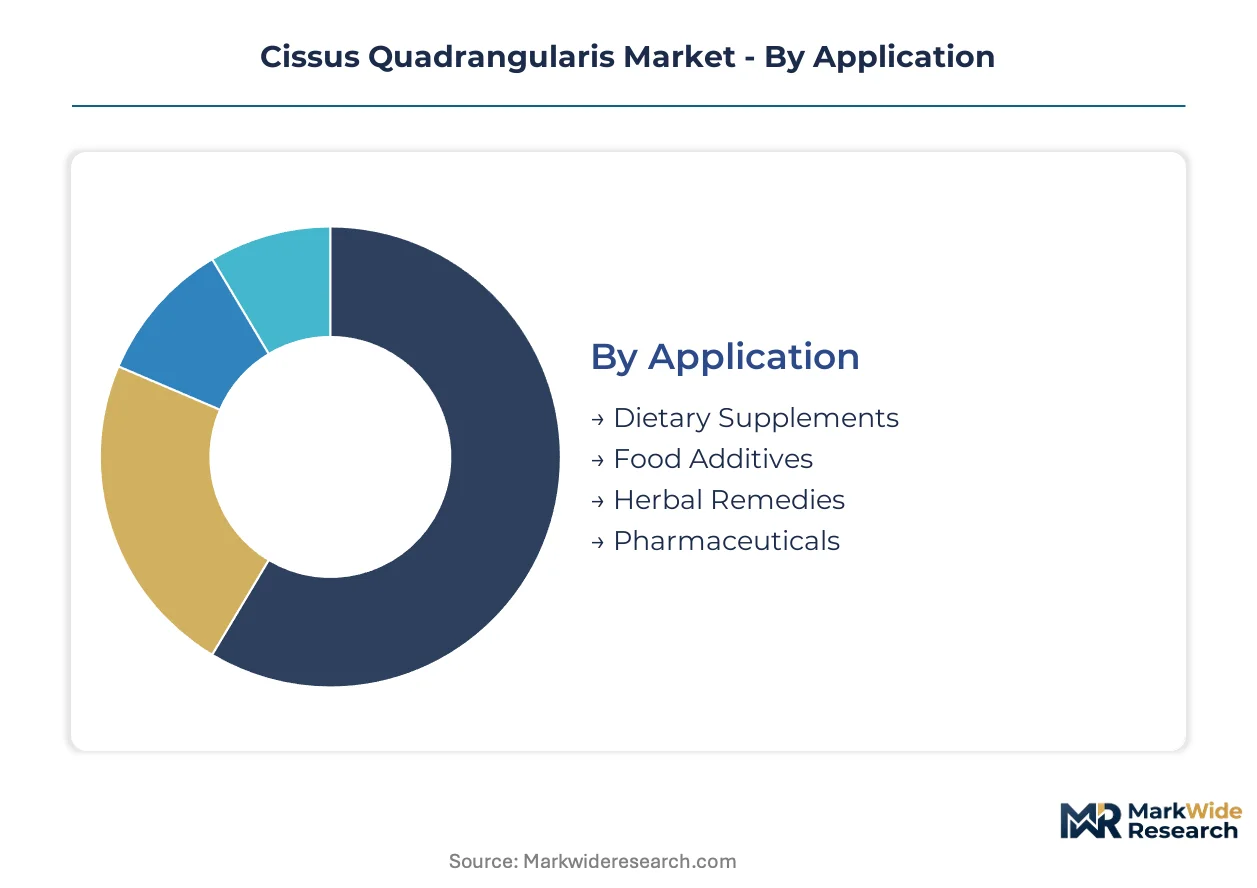
Segmentation in the Cissus Quadrangularis market reveals how ketosteroid standardization and procurement channel preferences split commercial value across radically different buyer workflows. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier strategy.
Application:
Musculoskeletal wellness applications span consumer self-care through prescription-grade protocols, with ketosteroid concentration thresholds determining regulatory pathway and pricing power.
- Dietary Supplements:Standardized extracts at 2.5-5% ketosteroid content target joint-support and bone-density positioning. North American nutraceutical brands concentrate procurement here, drawn by the US FDA's New Dietary Ingredient notification pathway and established consumer familiarity with botanical alternatives to glucosamine.
- Food Additives:Functional food manufacturers in Thailand and Vietnam integrate Cissus into protein fortification lines for gym-chain point-of-sale distribution. Sports nutrition channel expansion drives demand, though flavor masking and heat stability during processing constrain formulation flexibility.
- Herbal Remedies:Traditional Ayurvedic practitioners in Gujarat and Rajasthan prescribe raw stem preparations for fracture healing protocols.
- Pharmaceuticals:Clinical-grade extracts for post-fracture rehabilitation require ISO 17025-certified analytical documentation and pharmacovigilance compliance.
The dominant share belongs to Dietary Supplements, while Food Additives is closing the gap fastest.
Product Type:
Physical form dictates bioactive concentration, shelf stability, and the capital intensity required for manufacturing compliance.
- Extracts:Supercritical CO2-processed concentrates preserve heat-labile flavonoid profiles while eliminating residual solvent contamination. Clean-label positioning commands substantial price premiums over conventional ethanol maceration, with North American contract manufacturers retrofitting lines to capture this tier.
- Capsules:Hard-shell gelatin and vegetarian variants dominate practitioner-grade procurement through direct-to-clinic wholesale portals. Integrative medicine platforms in Texas and California favor this format for in-house compounding workflows.
- Pills:Compressed tablet forms suit mass-market retail distribution with lower per-unit production costs.
- Powders:Bulk extract for functional food integration and equine supplement manufacturing in Kentucky racing stables.
Extracts capture the highest margin contribution, with Capsules expanding most quickly through telehealth channel bypass of retail markup.
End User:
Buyer sophistication ranges from institutional procurement with captive testing infrastructure to individual consumers navigating Amazon-native fulfillment.
- Nutraceutical Companies:Brands with in-house ISO 17025 analytical capabilities concentrate procurement power, forcing smaller extract suppliers to absorb compliance costs or exit contract manufacturing partnerships. India's PLI scheme for herbal products enables these buyers to source standardized capacity from Gujarat and Rajasthan cultivation clusters.
- Healthcare Providers:Integrative medicine practitioners prescribe clinical-grade extracts for post-fracture rehabilitation, bypassing retail markup through specialized botanical wholesalers with pharmacist consultation support.
- Fitness Enthusiasts:Online retail captures this volume through Amazon-native fulfillment infrastructure, though trust signals lag behind pharmacy channels.
- Retail Consumers:Self-directed purchasers respond to clean-label certification and COA transparency in health store environments.
Nutraceutical Companies command the largest procurement volume, while Healthcare Providers are gaining share fastest through direct API-access platforms.
Distribution Channel:
Channel selection determines compliance documentation requirements and the depth of buyer-seller relationships possible.
- Online Retail:Amazon-native fulfillment infrastructure captures fitness-enthusiast volume with rapid delivery expectations. Double Wood Supplements anchors presence here through rigorous COA transparency, though clinical accounts migrate to specialized wholesalers.
- Pharmacies:Retail and hospital pharmacy channels retain stronger trust signals among healthcare providers prescribing botanical protocols. India's FSSAI licensing framework mandates GMP audits for herbal product export authorization, filtering counterfeit supply.
- Health Stores:Specialty retailers emphasize small-batch sourcing relationships and practitioner-grade positioning.
- Direct Sales:Telehealth-integrated wholesale portals enable integrative medicine clinics to purchase bulk extract for in-house compounding.
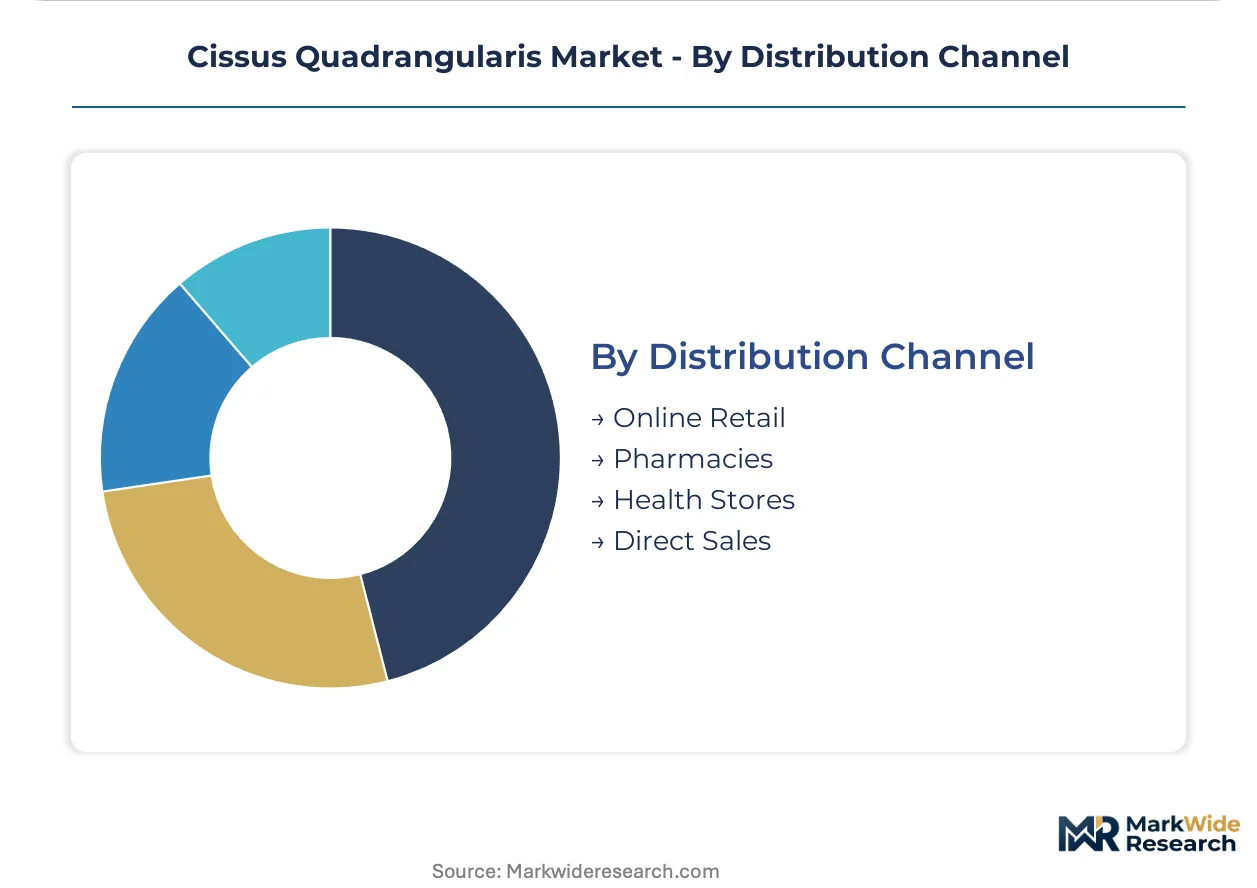
Online Retail holds the volume lead, with Direct Sales climbing the fastest as practitioner procurement bypasses traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw stem supply chains concentrate in India's Western Ghats cultivation clusters, with extraction capacity expanding through Gujarat and Rajasthan processing zones. North American nutraceutical procurement anchors import demand, while Southeast Asian functional food integration accelerates through Thailand and Vietnam manufacturing corridors.
United States
Sports nutrition brands and integrative medicine clinics drive extract procurement for joint-support formulations. The FDA's New Dietary Ingredient notification pathway governs pre-market compliance, with 180-day review timelines filtering smaller suppliers. Texas and California functional medicine clusters purchase bulk clinical-grade material through direct API-access platforms.
India
Ayurvedic practitioners in Gujarat and Rajasthan sustain traditional raw stem demand alongside modern extract exports. The FSSAI licensing framework mandates GMP audits for herbal product export authorization, with 2024 amendments requiring real-time pharmacovigilance reporting. Ahmedabad and Rajkot processing hubs retrofit supercritical CO2 extraction lines for North American contract manufacturing.
Thailand
Gym-chain point-of-sale distribution and protein fortification lines integrate Cissus extracts into sports nutrition SKUs. The national food and drug administration oversees functional food additive approvals with escalating documentation requirements for botanical ingredients. Bangkok metropolitan manufacturers blend extracts into ready-to-drink recovery beverages for domestic and regional export markets.
Vietnam
Fitness-enthusiast demand through e-commerce channels and local sports nutrition brands propels extract imports. The Ministry of Health regulates dietary supplement registration with tightening enforcement on traditional medicine claims. Ho Chi Minh City distributors serve as transshipment nodes for Southeast Asian gym-chain supply contracts.
Germany
Naturopathic practitioners and pharmacy channels sustain steady demand for standardized botanical extracts. EFSA's 2023 guidance on traditional food from third countries creates expedited Novel Food authorization pathways for documented Ayurvedic usage histories. Frankfurt and Hamburg import wholesalers manage EU distribution logistics for Indian-sourced clinical-grade material.
Cissus Quadrangularis Market Competitive Environment
Clinical-grade specialists and Amazon-native direct-to-consumer operators split the market along certification depth and channel infrastructure lines. The competitive structure remains fragmented across tiered quality grades, with ISO 17025-accredited laboratories and captive testing infrastructure determining procurement relationships. Three archetypes dominate: practitioner-channel clinical suppliers, mass-market e-commerce brands with COA transparency, and small-batch Ayurvedic sourcing specialists. Dominant competitive moves include backward integration into Gujarat cultivation contracts and technology licensing for supercritical extraction retrofitting.
Among North American direct-to-consumer operators, Double Wood Supplements exemplifies the Amazon-native fulfillment archetype with rigorous certificate-of-analysis transparency, while VitaJing occupies the clinical-grade practitioner-channel position. Barlowe's Herbal Elixirs represents the small-batch sourcing specialist model with Indian cultivator relationships. These three companies anchor distinct strategic vectors without consolidated market control.
| Leading Market Players |
|---|
| VitaJing |
| Barlowe's Herbal Elixirs |
| Double Wood Supplements |
| bixa BOTANICAL |
| Keter Wellness |
| True Nutrition |
| Activa Naturals |
| VitaMonk |
| LongLifeNutri |
| Others |
Value Chain & Pricing Dynamics
Wild-harvest stem collection in India's Western Ghats funnels margin capture toward extraction specialists with captive testing infrastructure, while downstream brands absorb ISO 17025 compliance premiums to sustain shelf positioning in North American nutraceutical channels.
Pricing Analysis
Aftermarket certification and third-party testing revenue tiers now drive lifetime value more than raw extract volume. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade practitioners from Amazon-native fitness enthusiasts and traditional Ayurvedic raw material buyers. Price differentiation rests on ketosteroid assay precision and FSSAI export licensing depth. Cost compression in standard-tier contract manufacturing intensifies as India's PLI scheme expands Gujarat processing capacity. Nutraceutical companies with in-house analytical capabilities exhibit lowest price sensitivity; unlicensed traders face margin elimination.
Supply Chain Analysis
Extended payment terms from North American nutraceutical brands to Indian extractors now stretch working capital cycles across the value chain. Raw stem supply draws from India, with secondary sourcing corridors in Sri Lanka and Bangladesh emerging. Supercritical CO2 equipment, HPLC-UV assay consumables, and FSSAI-licensed processing capacity constitute critical input dependencies. Single-source vulnerability concentrates around monsoon-dependent Western Ghats wild-harvesting. Distribution runs through direct-to-practitioner wholesale portals for clinical grades and Amazon-native fulfillment for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited analytical talent scarcity constrains capacity expansion across all supplier tiers, privileging incumbents with captive laboratory infrastructure and forcing new entrants toward specialized white-space positioning.
For Market Incumbents: Build certification moats through backward integration into Gujarat cultivation contracts and exclusive supercritical CO2 equipment licensing. Collagen peptide substitution in bone-density supplements threatens shelf positioning; defend through ketosteroid quantification transparency and direct API-access platform control over integrative medicine procurement. For New Entrants and Emerging Players: Build out veterinary osteoarthritis applications in Kentucky and Florida racing stables as the most penetrable demand pocket. Equine supplement manufacturers seek botanical NSAID alternatives with minimal incumbent competition. Target direct-to-practitioner telehealth channels with pharmacist consultation support as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed nutraceutical roll-ups consolidating Amazon-native brands lacking clinical-grade certification depth. Five-to-ten year viability hinges on regulatory compliance scalability rather than volume capture. Watch FDA NDI notification backlog clearance rates as the signal for supplier tier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Contracts | Gujarat and Rajasthan stem supply agreements secure input cost stability against monsoon volatility. |
| Supercritical CO2 Extraction Retrofitting | North American contract manufacturers preserve flavonoid profiles for clean-label premium positioning. |
| ISO 17025 Laboratory Accreditation | Analytical certification becomes de facto gate for nutraceutical brand partnerships and COA credibility. |
| Direct-to-Practitioner Platform Launch | Telehealth-integrated wholesale portals bypass retail markup for Texas and California functional medicine clinics. |
| EU Novel Food Authorization Pursuit | EFSA's traditional food pathway enables expedited market entry for Ayurvedic-documented Indian suppliers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA NDI notification databases, FSSAI export licensing records, and EFSA traditional food guidance documents. Conversations with extraction facility operators in Ahmedabad and Rajkot, nutraceutical procurement managers at North American brands, integrative medicine practitioners in Texas and California, and ISO 17025 laboratory directors informed supply chain and pricing dynamics. Bottom-up volume modeling from Gujarat cultivation cluster capacity and top-down value estimation from North American import trade data were cross-validated.
Forecast inputs span ketosteroid standardization tier adoption curves, sports nutrition channel expansion rates in Thailand and Vietnam, and regulatory pathway completion timelines. Segmentation dimensions include application type, product form, end-user sophistication, and distribution channel structure across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Pharmacovigilance reporting mandates and PLI scheme uptake rates provided industry-specific forecast anchors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by PE-backed roll-ups or sudden FDA enforcement shifts would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
South America Pet Nutraceuticals Market