
 Immunostimulants Market | 2026-2036
Immunostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Immunostimulants Market Foresight
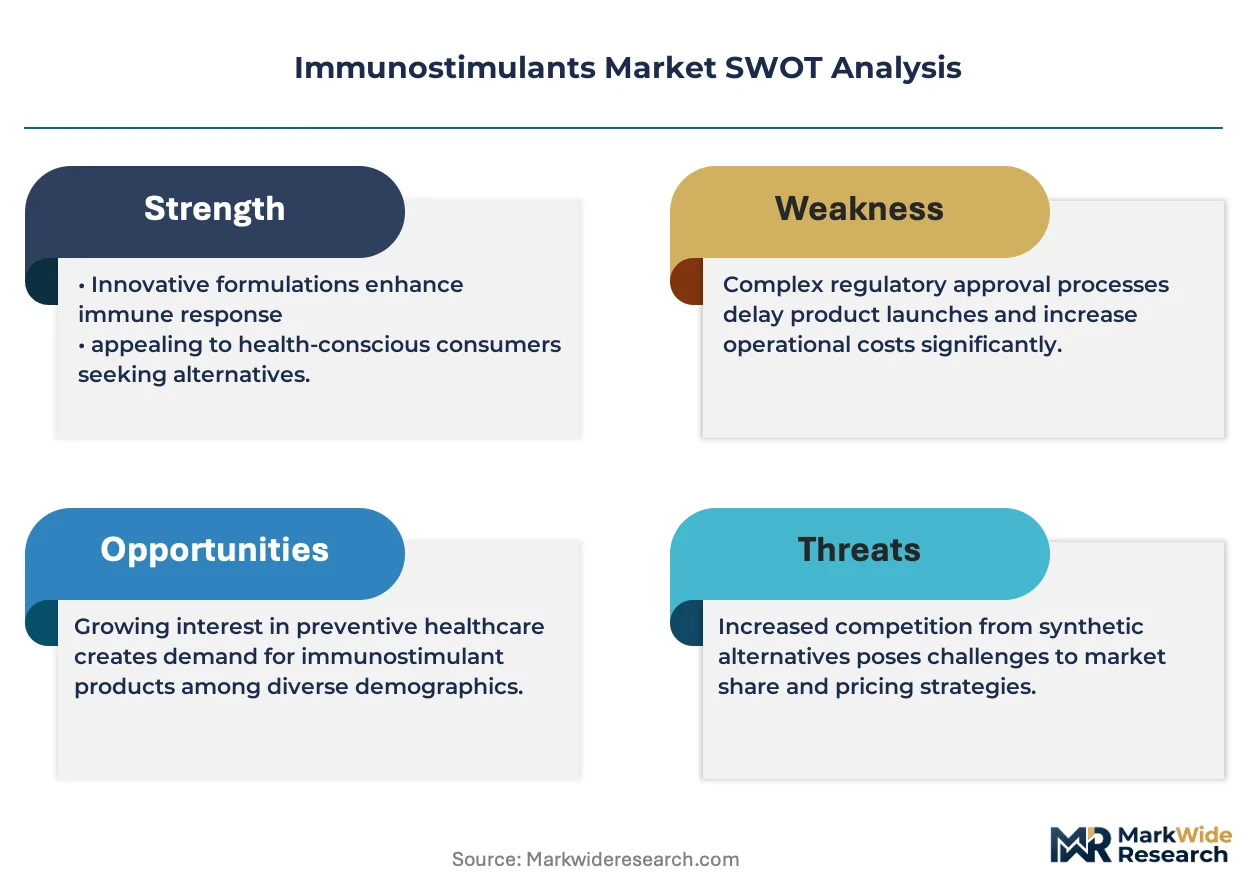
Project finance for late-stage immunostimulants development is fragmenting competitive entry, as smaller biotech firms gain access to non-dilutive capital structures previously reserved for large pharmaceutical balance sheets. F. Hoffmann-La Roche Ltd leverages its integrated diagnostics division to pair biomarker testing with therapy selection, sustaining premium positioning across oncology indications. Novartis AG anchors its portfolio in CAR-T and cytokine platforms, while Merck & Co., Inc. competes through checkpoint inhibitor combinations that incorporate immunostimulatory adjuvants.
Immunostimulants comprise biologically active substances that enhance innate or adaptive immune responses through cytokine induction, antigen presentation, or effector cell activation, typically manufactured via recombinant protein expression or synthetic peptide synthesis for parenteral administration. Biologics command the largest revenue share due to validated efficacy in melanoma and hematologic malignancies, though combination therapies represent the fastest-expanding category as developers stack mechanisms to overcome tumor resistance. Intravenous delivery dominates hospital-based administration, while subcutaneous formulations gain traction in homecare settings where patient convenience and cost containment converge.
The FDA's Breakthrough Therapy designation and the EMA's PRIME scheme compress regulatory review timelines, directly shaping investment allocation toward immunostimulant candidates with early biomarker signals. WHO prequalification standards and national pharmacovigilance requirements in Japan through PMDA further condition market access and post-approval surveillance obligations. Stakeholders must monitor evolving reimbursement criteria for combination regimens and the shifting competitive intensity between biosimilar cytokines and novel mechanism agents.
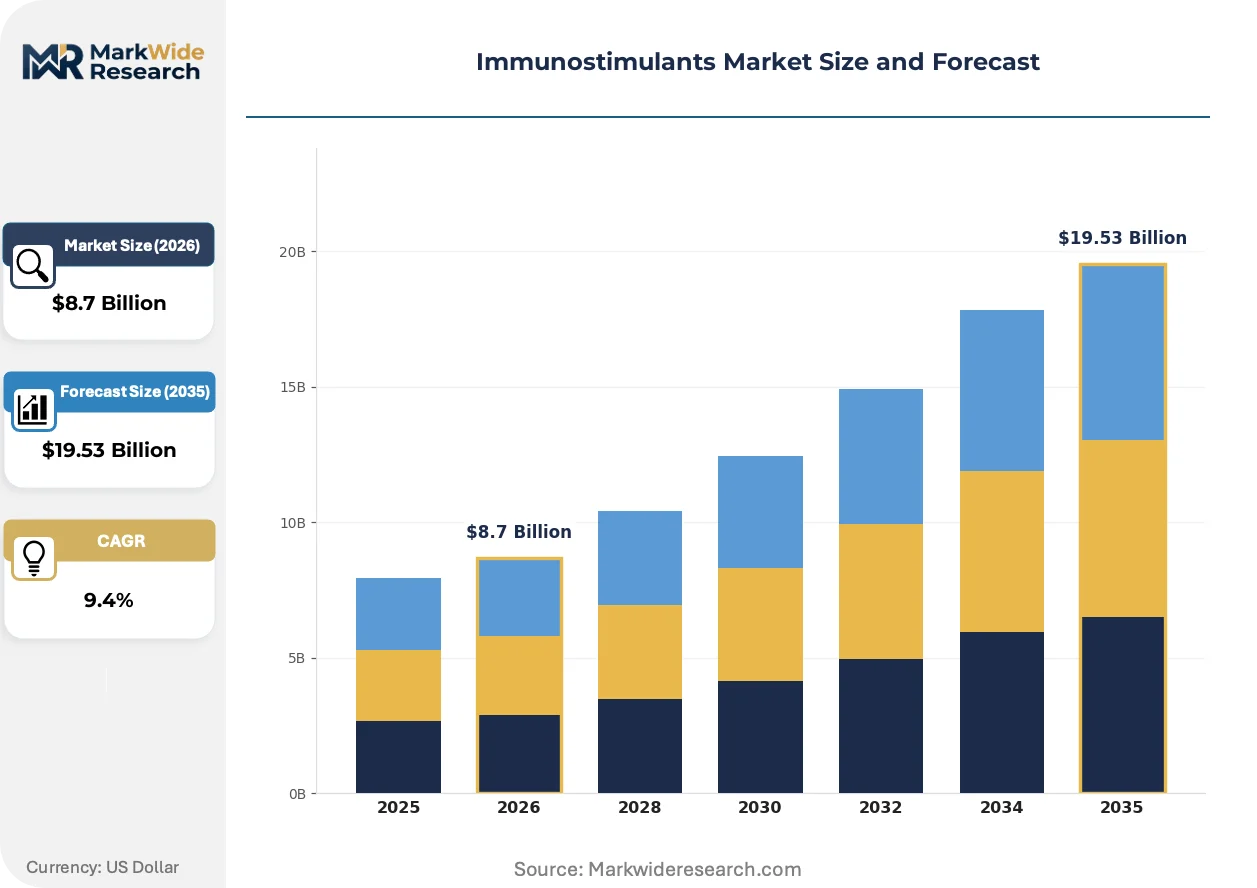
Market Dynamics
The FDA's accelerated approval pathway is compressing development timelines for immunostimulant candidates, forcing incumbents to defend positioning through faster biomarker validation and earlier prescriber engagement.
Growth Catalysts
- Medicare reimbursement expansion:The United States Centers for Medicare & Medicaid Services has broadened coverage for biologic immunostimulants in outpatient oncology settings, directly lifting hospital procurement volumes.
- EMA PRIME scheme:Priority Medicines designation in Europe compresses regulatory review for breakthrough immunostimulants, redirecting venture capital toward late-stage European development programs.
- Checkpoint inhibitor combinations:Oncology departments are stacking immunostimulatory adjuvants with PD-1/PD-L1 inhibitors to overcome tumor resistance, creating protocol-level demand pull.
Market Restraints
- Cold-chain distribution costs:Parenteral biologics require continuous temperature-controlled logistics, with specialized freight carriers commanding premium rates that compress net margins.
- Single-source cytokine supply:Recombinant protein expression concentrates among contract manufacturing organizations in Switzerland and Singapore, creating geographic concentration risk.
- Japan PMDA pharmacovigilance:Post-approval surveillance obligations for immunostimulants extend development-to-commercialization timelines by 18-24 months relative to other therapeutic categories.
Strategic Opportunities
- Subcutaneous formulation expansion:Homecare administration of immunostimulants bypasses infusion center capacity constraints, opening reimbursement arbitrage between hospital and outpatient settings.
- India CDSCO fast-track:The country's national pharmaceutical regulator has streamlined biosimilar cytokine approvals, enabling first-mover positioning in a price-sensitive volume market.
- AI-driven patient stratification:Machine learning integration with biomarker testing is virtualizing trial design, reducing enrollment periods for combination immunostimulant studies.
Industry Challenges
- Cell therapy manufacturing talent scarcity:CAR-T and cytokine platform production requires specialized bioprocess engineers, with workforce gaps concentrated in viral vector purification and closed-system automation.
- Combination regimen IP complexity:Stacking mechanisms across multiple patent estates creates licensing friction, particularly where checkpoint inhibitors and immunostimulatory adjuvants originate from competing holders.
- Legacy EHR integration:Biomarker-guided therapy selection requires real-time diagnostic-to-prescription data flows that most hospital information systems cannot support without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunostimulants Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Synthetic Agents, Natural Products, Combination Therapies Application: Oncology, Infectious Diseases, Autoimmune Disorders, Allergy Treatments Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Laboratories, Homecare Settings |
| Companies Covered | F. Hoffmann-La Roche Ltd, Novartis AG, Merck & Co., Inc., Amgen Inc., Pfizer Inc., Bristol-Myers Squibb Company, Johnson & Johnson, Sanofi, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunostimulants Market Shifts & Advancements
Three converging forces are restructuring how immunostimulants reach patients: manufacturing virtualization, regulatory acceleration mechanisms, and site-of-care migration. These shifts favor developers with integrated diagnostics capabilities and flexible delivery formulations.
Digital twin technology is virtualizing bioprocess optimization for recombinant cytokine production. Contract development organizations are deploying physics-based simulations to predict cell culture yield before pilot-scale runs, compressing CMC timelines by 30-40 percent. Large molecule developers with captive digital twin capabilities are pulling ahead in speed-to-IND metrics.
REACH authorization requirements in Europe are tightening traceability for synthetic peptide immunostimulants, forcing reformulation of certain adjuvant candidates. Manufacturers are substituting petroleum-derived solvents with bio-based alternatives to maintain registration eligibility. The reformulation burden falls heaviest on mid-stage developers without dedicated regulatory toxicology teams.
Hospital purchasing cooperatives in the United States are consolidating immunostimulant procurement under single-source contracts with price-protection clauses. Integrated delivery networks are displacing independent oncology practices as the dominant channel, concentrating negotiating leverage among three national group purchasing organizations. This channel shift is most visible in Medicare Advantage populations where capitated payments reward site-neutral administration.
Immunostimulants Market Segmentation
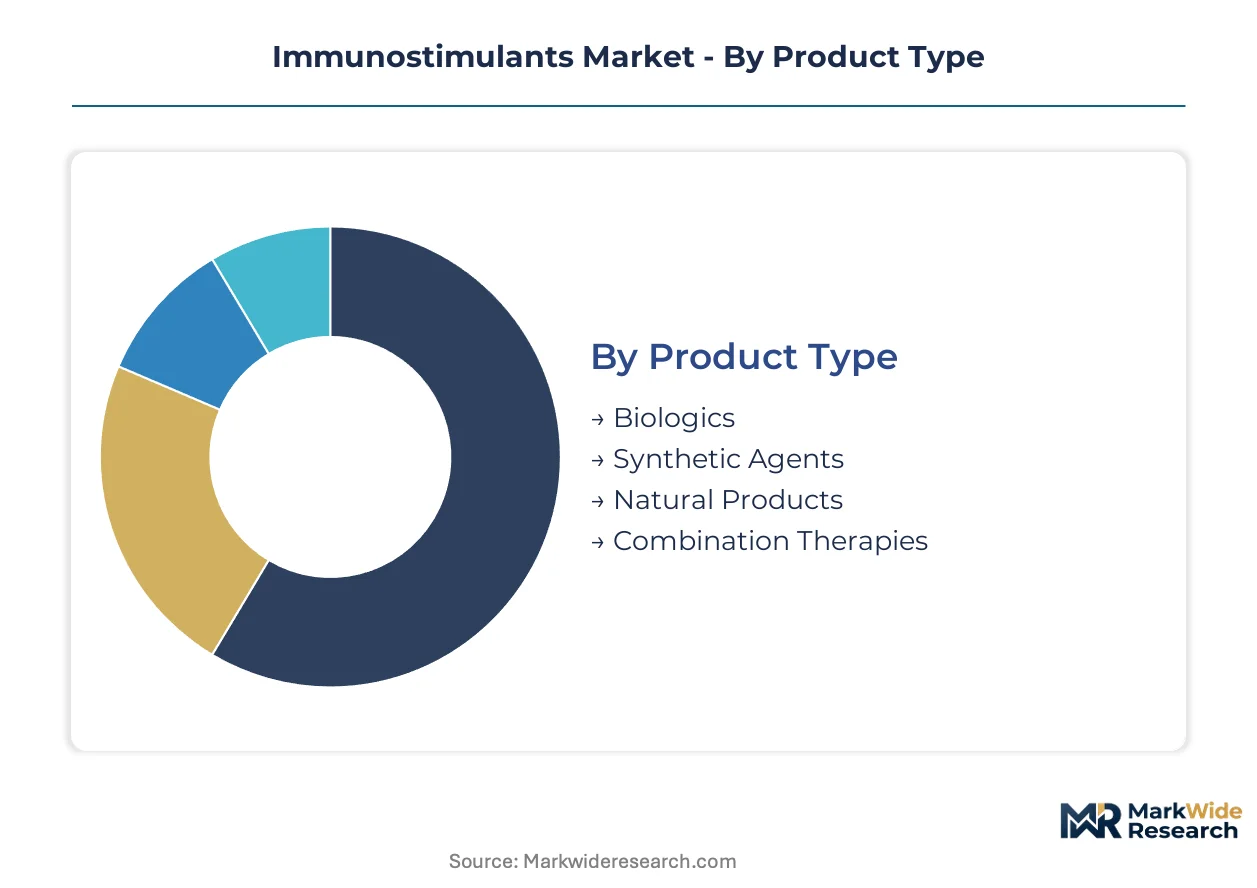
Segmentation in immunostimulants reveals divergent margin profiles and regulatory pathways. Cycle times vary dramatically between hospital-administered biologics and patient-managed formulations, reshaping capital allocation across development portfolios.
Product Type:
Cycle times compress fastest for synthetic agents with well-characterized chemistry, while biologics endure extended CMC timelines due to cell line optimization and viral clearance validation.
- Biologics:Recombinant cytokines and monoclonal antibodies manufactured via mammalian cell culture or microbial fermentation. Demand concentrates in United States hospital oncology departments where Medicare reimbursement supports premium pricing for validated melanoma and hematologic malignancy indications.
- Combination Therapies:Stacked mechanisms pairing checkpoint inhibitors with immunostimulatory adjuvants. Development velocity accelerates in European programs leveraging EMA PRIME designation, though IP licensing friction across multiple patent estates constrains some programs.
- Synthetic Agents:Peptide-based and small-molecule immunomodulators with defined chemical structures enabling abbreviated regulatory pathways.
- Natural Products:Botanical extracts and microbial derivatives with complex composition profiles requiring extensive characterization.
Biologics anchors the volume base while Combination Therapies gains share at the steepest rate.
Application:
Cost tiers stratify sharply between oncology's premium biologic regimens and infectious disease programs targeting volume markets with price-sensitive procurement.
- Oncology:Immune checkpoint modulation and CAR-T adjuvant applications commanding highest per-patient values. United States integrated delivery networks concentrate procurement through three national group purchasing organizations with price-protection clauses.
- Infectious Diseases:Vaccine adjuvants and pathogen-directed immunomodulation for emerging viral threats. CDSCO fast-track approvals in India enable first-mover positioning in biosimilar cytokine segments with compressed commercialization timelines.
- Autoimmune Disorders:Cytokine regulation for rheumatoid arthritis, multiple sclerosis, and inflammatory bowel disease with chronic administration profiles.
- Allergy Treatments:Desensitization protocols and Th1-skewing adjuvants with seasonal demand patterns and pediatric formulation requirements.
Oncology commands the premium tier while Infectious Diseases expands most quickly on volume-driven procurement.
Delivery Mode:
Patient convenience and site-of-care economics are rebalancing utilization between facility-based infusion and self-administered alternatives.
- Intravenous:Hospital and infusion center administration of large-molecule biologics requiring controlled delivery rates. Capacity constraints in United States outpatient oncology settings create wait-time bottlenecks that compress throughput.
- Subcutaneous:Prefilled syringe and autoinjector formulations enabling homecare transition. Reimbursement arbitrage between hospital and outpatient settings drives prescriber preference in Medicare Advantage capitated populations.
- Oral:Small-molecule immunomodulators with gastrointestinal absorption challenges limiting bioavailability.
- Topical:Cutaneous delivery for localized immune response modification in dermatologic applications.
Intravenous retains the procedural volume base while Subcutaneous climbs the fastest on site-of-care migration.
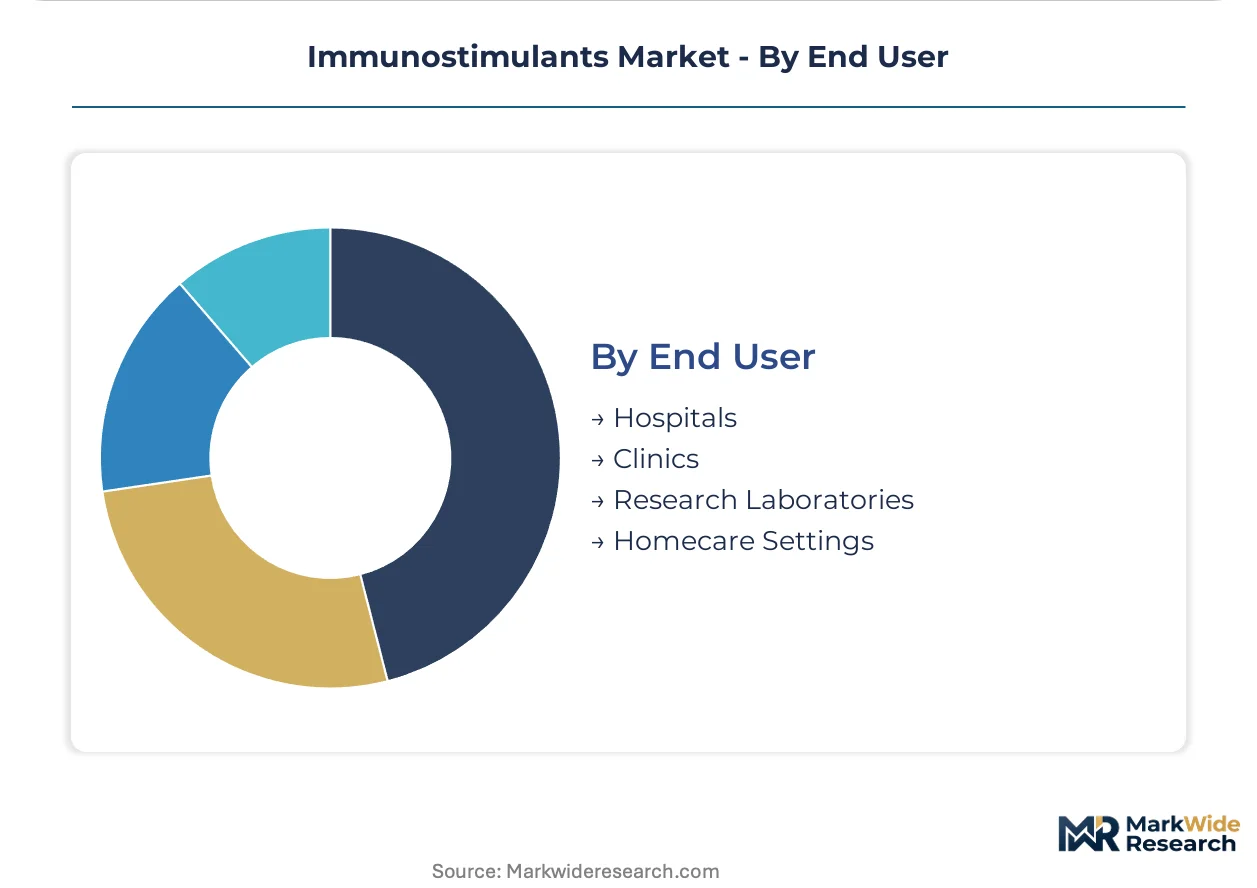
End User:
Procurement sophistication varies from institutional tender processes to direct-to-patient distribution with divergent compliance obligations.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees governing formulary placement. Japan's PMDA pharmacovigilance requirements extend post-approval surveillance timelines by 18-24 months relative to other categories.
- Homecare Settings:Specialty pharmacy distribution with nurse-supported self-administration. Cold-chain distribution costs for parenteral biologics compress net margins despite patient convenience premiums.
- Clinics:Independent and hospital-affiliated outpatient facilities with limited infusion capacity.
- Research Laboratories:Preclinical and clinical trial supply with investigational new drug documentation requirements.
Hospitals anchor the revenue base while Homecare Settings gains share at the steepest rate on administration cost containment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in immunostimulants reflect concentrated biologics manufacturing in Switzerland and Singapore against heavy United States import dependency for hospital-administered therapies. Trade flows favor net exporters with contract manufacturing infrastructure, while reimbursement-rich markets absorb premium-priced biologics.
United States
Medicare reimbursement expansion for outpatient oncology biologics drives hospital procurement volumes through integrated delivery networks. FDA accelerated approval pathways compress regulatory timelines for breakthrough immunostimulants. The Greater Boston biotech corridor anchors CAR-T platform development with specialized viral vector manufacturing capacity.
Switzerland
Contract manufacturing organizations concentrate recombinant protein expression for global biologics supply. Swissmedic maintains stringent batch release standards that extend export certification timelines. The Basel region hosts integrated diagnostics-therapy developers pairing biomarker testing with immunostimulant selection.
Japan
PMDA pharmacovigilance obligations extend post-approval surveillance by 18-24 months relative to other therapeutic categories. METI funding supports domestic cell therapy manufacturing infrastructure to reduce import dependency. The Kanto region around Tokyo concentrates hospital-based infusion center networks for biologic administration.
India
CDSCO fast-track approvals for biosimilar cytokines enable first-mover positioning in price-sensitive volume markets. The country's national pharmaceutical regulator streamlines documentation requirements for recombinant protein products. Maharashtra and Gujarat host contract development organizations serving export markets with abbreviated regulatory pathways.
Germany
EMA PRIME designation redirects venture capital toward late-stage European immunostimulant development programs. REACH authorization requirements tighten traceability for synthetic peptide adjuvants, forcing solvent reformulation. The Munich-Frankfurt corridor concentrates precision medicine clusters integrating biomarker testing with therapy protocols.
Immunostimulants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The market structures around three tiers: multinational conglomerates with integrated diagnostics divisions, mid-cap biotech firms accessing non-dilutive project finance, and contract manufacturers capturing margin through captive bioprocess capacity. Strategic moves concentrate on biomarker-guided therapy pairing and subcutaneous formulation development to bypass infusion center constraints.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd and Novartis AG occupy positions spanning diagnostics integration and CAR-T platform development. Merck & Co., Inc. sits within the checkpoint inhibitor combination tier, representing the archetype of immunostimulatory adjuvant stacking with PD-1/PD-L1 mechanisms. These three exemplify divergent competitive vectors: diagnostics-therapy pairing, cell therapy manufacturing scale, and combination regimen intellectual property positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Merck & Co., Inc. |
| Amgen Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Sanofi |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
The Singapore-Switzerland air freight corridor for temperature-controlled biologics commands premium rates that cascade through hospital procurement contracts, compressing margins for parenteral immunostimulants while enabling price stratification between cold-chain-dependent biologics and ambient-stable synthetic alternatives.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations for immunostimulants through formulary placement protocols that stratify value across biomarker-validated biologics, standard cytokine platforms, and economy-tier biosimilars. Price differentiation rests on FDA breakthrough therapy designation status and EMA PRIME eligibility, with certification tier acting as the primary sorting mechanism. Pricing pressure intensifies as integrated delivery networks consolidate purchasing under single-source contracts with price-protection clauses. Medicare Advantage capitated populations exhibit highest price sensitivity, while academic medical centers with research funding demonstrate lowest sensitivity due to protocol-driven demand.
Supply Chain Analysis
Single-source cytokine manufacturing concentration between Switzerland and Singapore creates geographic vulnerability for recombinant protein supply, with contract manufacturing organizations controlling viral vector purification capacity. Raw material dependencies center on Chinese-sourced cell culture media, German-engineered bioreactor systems, and Swiss-derived purification resins. Tariff exposure between the United States and China on laboratory equipment intensifies cost pressure for mid-stage developers. Distribution runs through specialized cold-chain logistics providers serving hospital networks and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent immunostimulant developers face substitution pressure from AI-designed synthetic peptide platforms that bypass biologic manufacturing complexity, requiring defensive repositioning around integrated diagnostics and manufacturing virtualization.
For Market Incumbents: Harden biomarker-guided therapy pairing through captive diagnostic divisions, mirroring F. Hoffmann-La Roche Ltd's integrated model. Secure subcutaneous formulation capabilities to capture site-of-care migration away from infusion centers. Vertical integration into digital twin-enabled bioprocess optimization defends margin position against contract manufacturing cost escalation.
For New Entrants and Emerging Players: CDSCO fast-track biosimilar cytokine approvals in India represent the most penetrable entry point for price-sensitive volume markets. Homecare administration of prefilled autoinjector formulations in Medicare Advantage populations offers second-mover positioning. Partner with established specialty pharmacy distributors to bypass hospital formulary gatekeeping.
For Investors and Strategic Acquirers: Mid-cap biotech firms with non-dilutive project finance structures and late-stage EMA PRIME-designated assets offer acquisition exposure to regulatory acceleration value. Long-term viability hinges on combination regimen IP positioning as checkpoint inhibitor stacking becomes standard oncology protocol. Watch FDA breakthrough therapy designation velocity as inflection signal for portfolio reallocation toward immunostimulant adjuvants.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Diagnostics Integration | F. Hoffmann-La Roche Ltd pairs testing with therapy selection to sustain premium oncology positioning. |
| Subcutaneous Formulation Development | Homecare administration bypasses infusion center capacity constraints in United States Medicare networks. |
| EMA PRIME Designation Pursuit | European regulatory acceleration redirects venture capital toward late-stage immunostimulant programs. |
| CDSCO Fast-Track Biosimilar Entry | India's streamlined approvals enable first-mover positioning in price-sensitive cytokine volume markets. |
| Digital Twin Bioprocess Deployment | Physics-based simulations compress CMC timelines by predicting cell culture yield before pilot runs. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient-flow modeling and top-down reimbursement trend analysis triangulated on volume and value estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product type, application, delivery mode, and end user alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to baseline immunostimulant adoption rates, incorporating Medicare reimbursement expansion velocity and EMA PRIME designation throughput as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in biotech venture capital availability or CMS reimbursement policy would shift the trajectory materially. Forecasts reflect documented assumptions on regulatory pathway compression and cold-chain logistics cost evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Postbiotics Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
Magtein Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Global Eye Health Supplement Market