
 Native Collagen Market | 2026-2036
Native Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Native Collagen Market Outlook
Modular dosing formats is recalibrating buyer choice across nutraceutical and medical device channels. GELITA AG leverages its bovine-derived gelatin specialization to anchor supply relationships with European functional food manufacturers. Rousselot sustains competitive density through marine collagen extraction capabilities and backward integration into sustainable fishery sourcing. Advanced BioMatrix, Inc. differentiates by occupying the precision medical segment with sterile collagen matrices for tissue engineering applications.
Native collagen comprises triple-helical protein structures extracted from animal connective tissues without denaturation, retaining molecular weights typically exceeding 300 kDa for structural integrity in biomedical scaffolds and high-viscosity food systems. Gelatin dominates volume flows as the mature workhorse for food stabilization and capsule manufacturing, while collagen peptides capture margin expansion through enzymatic hydrolysis that yields bioavailable fractions for nutricosmetic positioning. Marine-sourced native collagen represents the fastest-growing source category, propelled by kosher and halhal certification advantages plus perceived sustainability credentials among Asia-Pacific formulators.
EFSA novel food assessments and EU REACH chemical safety registrations govern raw material qualification for European collagen suppliers, while FDA GRAS self-affirmation pathways shape U.S. market entry timelines for new source variants. ISO 17025 laboratory accreditation requirements are becoming non-negotiable for medical device-grade collagen contracts, filtering out smaller unqualified processors. Stakeholders must monitor evolving EFSA health claim substantiation standards for collagen-specific beauty and mobility benefits, as these rulings will determine permissible marketing language and premium pricing justification across retail and professional channels.
Market Dynamics
EFSA novel food authorization pathways and ISO 17025 accreditation requirements are tightening purity benchmarks, filtering unqualified processors while concentrating procurement relationships around certified gelatin specialists and marine extraction facilities.
Growth Catalysts
- Medical-grade scaffold demand:Tissue engineering applications require triple-helical native collagen exceeding 300 kDa molecular weight, pulling volume toward sterile matrix suppliers with biocompatibility certifications.
- REACH chemical safety registrations:EU raw material qualification protocols are accelerating supplier consolidation, rewarding processors with backward integration into sustainable fishery sourcing and kosher-certified marine operations.
- Nutricosmetic formulation expansion:Enzymatic hydrolysis capabilities enabling bioavailable collagen peptide fractions are capturing margin expansion in joint health and skin elasticity positioning across German functional food channels.
Market Restraints
- Bovine-derived input volatility:Gelatin supply chains face price instability from cattle herd fluctuations and rendering plant capacity constraints across European abattoir networks.
- Marine sourcing concentration:Sustainable fishery backward integration limits viable supply to North Atlantic and Pacific processing clusters, creating geographic vulnerability to quota restrictions.
- Denaturation sensitivity:Triple-helical structure preservation requires cold-chain handling and rapid processing post-extraction, constraining viable production to facilities with continuous-flow capabilities.
Strategic Opportunities
- Halal-certified marine expansion:Indonesia and Malaysia present underpenetrated demand for kosher-halal dual-certified collagen in pharmaceutical capsule and nutraceutical applications.
- Precision medical segment:Sterile collagen matrices for 3D bioprinting and organoid scaffolding offer premium positioning beyond commodity food-grade volumes.
- EU Green Deal alignment:Circular economy incentives for fishery byproduct valorization are creating regulatory tailwinds for marine extraction investments with carbon footprint documentation.
Industry Challenges
- ISO 17025 laboratory accreditation timelines:Medical device-grade contracts require 18-24 month validation cycles for collagen purity and endotoxin testing protocols.
- Cross-species immunogenicity assessment:Bovine and porcine sourcing requires species-of-origin documentation and prion safety dossiers that strain regulatory affairs capacity.
- Legacy food-grade capacity reconfiguration:Retrofitting gelatin plants for pharmaceutical-grade sterile processing demands capex outlays for cleanroom infrastructure and automated filling lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Collagen Market |
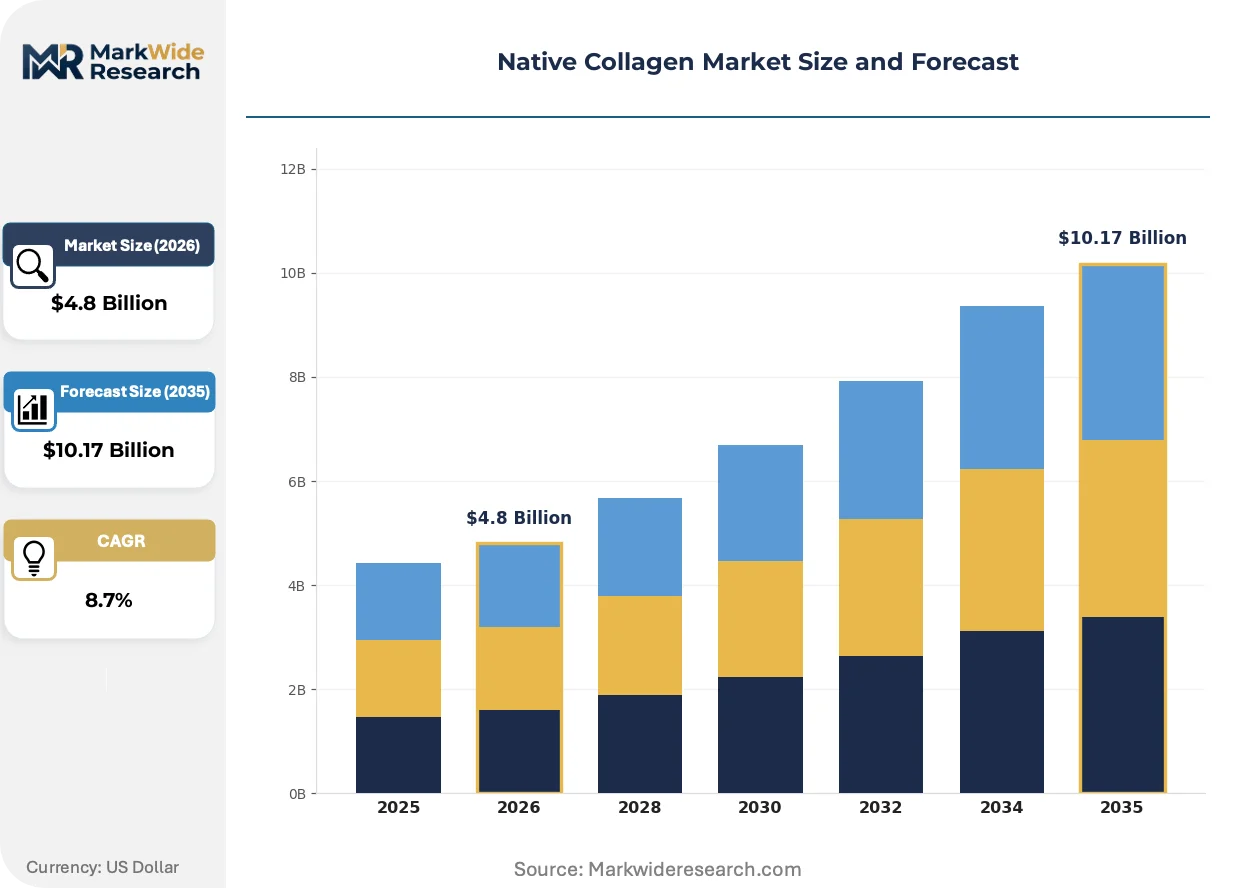
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Undenatured Type II Collagen, Collagen Peptides Source: Bovine, Porcine, Marine, Chicken Form: Powder, Liquid, Capsule, Tablet Application: Nutraceuticals, Cosmetics, Functional Foods, Medical Devices |
| Companies Covered | Rousselot, GELITA AG, Weishardt, Tessenderlo Group NV, Nitta Gelatin Inc., LAPI GELATINE S.p.A., Advanced BioMatrix, Inc., HolistaCollTech Ltd., Collagen Solutions Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Collagen Market Strategic Shifts
Enzymatic hydrolysis protocols and cold-extraction technologies are redrawing competitive boundaries between commodity gelatin suppliers and precision medical-grade processors. Three developments merit close tracking.
Non-denaturing cold-extraction technologies preserve triple-helical integrity for biomedical scaffold applications. Tissue engineering laboratories and regenerative medicine startups are adopting these matrices at accelerating pace for 3D cell culture and organoid development. This capability is rewriting supplier selection criteria, compressing procurement relationships toward processors with pharmaceutical-grade cleanroom infrastructure and ISO 13485 medical device quality systems.
EFSA health claim substantiation standards for collagen-specific beauty and mobility benefits are tightening marketing permissibility across European retail channels. The industrial consequence is a bifurcation between commodity peptide suppliers and those investing in randomized controlled trial dossiers for joint health positioning. German and French nutricosmetic formulators are most affected, redirecting R&D budgets toward clinical endpoint studies that justify premium pricing against unverified competitors.
Direct-to-practitioner distribution models are displacing traditional ingredient broker networks for medical-grade collagen. Orthopedic clinics and aesthetic medicine practices now source sterile matrices through specialized distributors with cold-chain logistics rather than general chemical suppliers. This channel compression is most visible in Switzerland and the Netherlands, where private clinic procurement autonomy enables rapid supplier switching based on batch documentation quality.
Native Collagen Market Segmentation
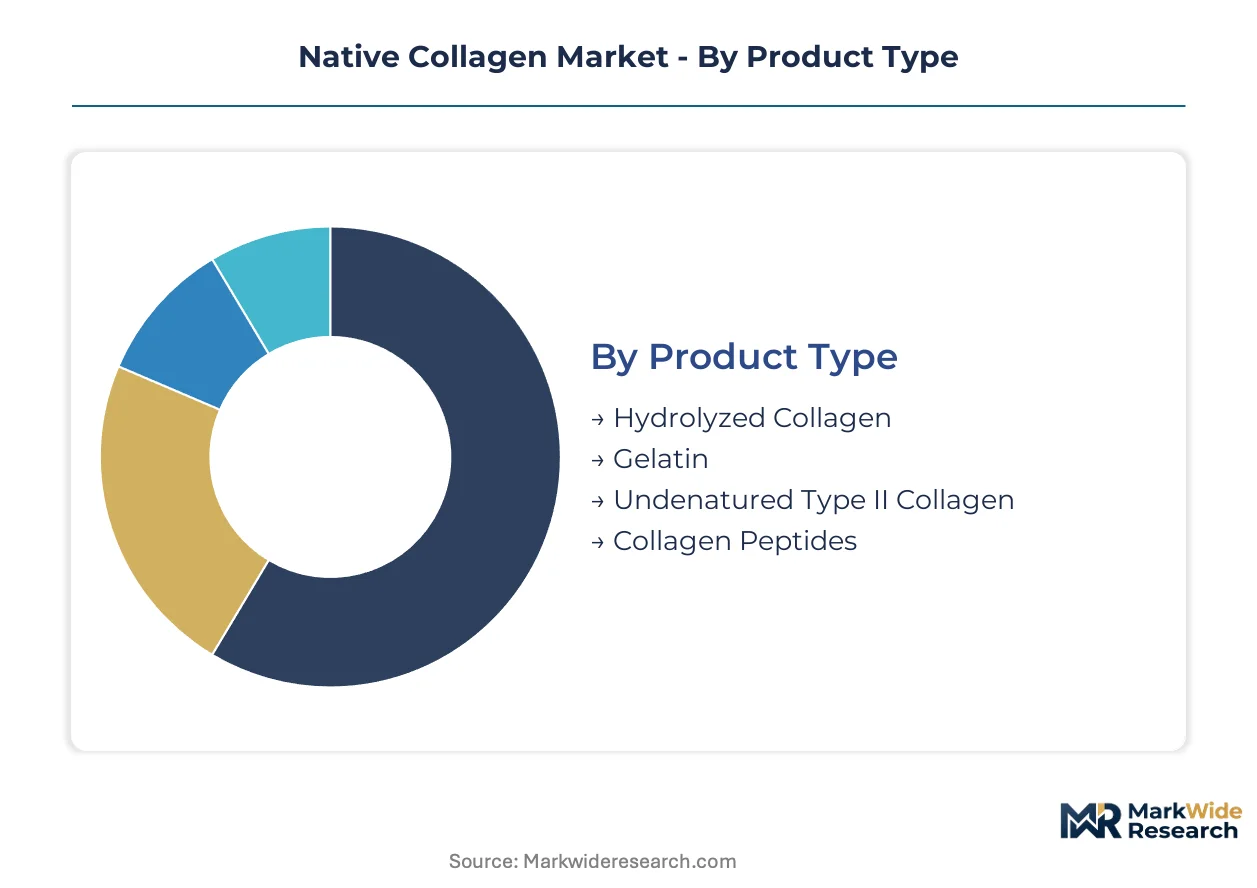
Native collagen's triple-helical integrity requirements create sharp technical boundaries between commodity gelatin flows and precision medical-grade matrices. Each segmentation axis carries distinct certification burdens, cold-chain dependencies, and margin structures that reshape supplier selection criteria across European functional food and regenerative medicine channels.
Product Type:
Enzymatic processing intensity and molecular weight preservation define the technical differentiation ladder across collagen formats.
- Gelatin:Partially hydrolyzed collagen fractions with molecular weights between 50-100 kDa serve as the workhorse stabilizer for capsule shells and confectionery gels. German pharmaceutical capsule manufacturers anchor procurement volumes here, though rendering plant capacity constraints across European abattoir networks inject supply volatility.
- Collagen Peptides:Enzymatically hydrolyzed to bioavailable fractions under 10 kDa, these fractions command premium positioning in nutricosmetic joint health formulations. French and German functional food channels concentrate demand, driven by EFSA health claim substantiation requirements that reward clinical dossier investment.
- Hydrolyzed Collagen:Intermediate molecular weight distributions suit beverage fortification and powder applications where solubility trumps structural integrity.
- Undenatured Type II Collagen:Preserved triple-helical structure from avian cartilage targets specialized joint health applications with immunomodulatory positioning.
Gelatin leads on scale; collagen peptides lead on momentum.
Source:
Species-of-origin documentation requirements and religious certification advantages redistribute procurement gravity across extraction feedstocks.
- Marine:Kosher-halal dual certification and perceived sustainability credentials accelerate adoption among Asia-Pacific formulators. North Atlantic and Pacific fishery clusters supply the raw material, though quota restrictions constrain geographic expansion.
- Bovine:Mature supply infrastructure from European and North American rendering networks supports volume flows, yet prion safety dossiers and species-of-origin documentation strain regulatory affairs capacity.
- Porcine:Cost-competitive gelatin production serves food-grade applications where religious restrictions are absent.
- Chicken:Avian cartilage sourcing enables undenatured Type II collagen extraction for specialized joint health positioning.
Bovine sourcing dominates current volume; marine extraction gains share fastest.
Form:
Handling requirements and dose precision needs segment delivery formats across professional and retail channels.
- Powder:Bulk nutraceutical manufacturing and functional food fortification favor this format for blending flexibility and cost efficiency.
- Liquid:Ready-to-drink positioning in beauty and wellness applications demands cold-chain stability and preservative system optimization.
- Capsule:Pharmaceutical-grade gelatin shells require kosher-halal certification for premium positioning in Indonesian and Malaysian markets.
- Tablet:Compression-grade collagen peptides serve mass-market joint health positioning with manufacturing simplicity.
Powder commands manufacturing scale; liquid formats climb fastest on convenience positioning.
Application:
Regulatory stringency and reimbursement pathways create divergent margin profiles across end-use verticals.
- Medical Devices:Sterile collagen matrices exceeding 300 kDa molecular weight command premium positioning in tissue engineering and 3D bioprinting. ISO 13485 quality systems and ISO 17025 laboratory accreditation filter supplier资格, compressing procurement toward Swiss and Dutch precision medical specialists.
- Nutraceuticals:Enzymatic hydrolysis capabilities enable bioavailable peptide fractions for joint health and skin elasticity claims. EFSA novel food authorization pathways govern European market entry, rewarding dossier investment with premium pricing justification.
- Cosmetics:Topical and ingestible beauty applications leverage collagen peptide bioavailability for nutricosmetic positioning.
- Functional Foods:Gelatin stabilization and peptide fortification serve convenience-oriented nutrition formats with milder regulatory barriers.
Nutraceuticals anchor volume demand; medical devices capture the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Native collagen extraction originated in European abattoir and rendering networks during the early industrialization of gelatin production. Germany and France pioneered pharmaceutical-grade processing standards that now govern global quality benchmarks.
Germany
Pharmaceutical capsule manufacturers and medical device sterilization facilities drive concentrated demand in the Rhine-Ruhr and Bavarian industrial corridors. EFSA novel food authorization pathways filter market entry for collagen peptide suppliers, rewarding dossier investment with premium positioning. The Frankfurt-Mainz biotech cluster anchors sterile matrix production for tissue engineering applications.
United States
FDA GRAS self-affirmation pathways accelerate new source variant commercialization for nutraceutical and cosmetic channels. Bovine-derived gelatin supply chains face rendering plant capacity constraints across Midwestern abattoir networks. Boston and San Diego regenerative medicine hubs pull medical-grade collagen volumes toward 3D bioprinting applications.
China
NMPA medical device registration requirements and GB standards for collagen sourcing tighten import substitution pressures on domestic processors. Marine collagen extraction from North Pacific fishery byproducts expands in Shandong and Liaoning coastal provinces. The Yangtze River Delta concentrates cosmetic-grade peptide hydrolysis capacity for Asia-Pacific nutricosmetic export.
Japan
PMDA quality system regulations and METI circular economy incentives valorize fishery byproduct streams for marine collagen extraction. Kansai region processors specialize in low-molecular-weight peptide fractions for aging-population joint health formulations. Osaka-based suppliers command premium positioning through JIS-standardized purity documentation.
Switzerland
Swissmedic medical device certification requirements and private clinic procurement autonomy enable rapid supplier switching based on batch documentation quality. Geneva and Zurich aesthetic medicine practices source sterile matrices through specialized distributors with cold-chain logistics. Precision medical collagen positioning captures margins beyond commodity food-grade volumes.
Native Collagen Market Competitive Environment
The competitive structure tilts toward integrated gelatin specialists with backward control over rendering networks and abattoir relationships. Scale advantages concentrate in European processors with decades of pharmaceutical-grade certification lineage, while marine extraction capabilities redistribute competitive gravity toward North Atlantic and Pacific fishery clusters. Three archetypes dominate: legacy gelatin conglomerates with diversified species sourcing, marine-focused specialists with kosher-halal dual certification, and precision medical-grade processors with ISO 13485 quality systems. Supplier consolidation accelerates through M&A targeting rendering plant capacity and sterile processing infrastructure.
Among European-integrated specialists, GELITA AG and Rousselot occupy positions that exemplify scale-driven archetypes with species-diversified sourcing portfolios. Advanced BioMatrix, Inc. represents the precision medical tier, anchoring sterile matrix supply relationships with tissue engineering laboratories and regenerative medicine channels. These three entities illustrate the bifurcation between commodity volume processors and certification-heavy medical-grade suppliers.
| Leading Market Players |
|---|
| Rousselot |
| GELITA AG |
| Weishardt |
| Tessenderlo Group NV |
| Nitta Gelatin Inc. |
| LAPI GELATINE S.p.A. |
| Advanced BioMatrix, Inc. |
| HolistaCollTech Ltd. |
| Collagen Solutions Plc |
| Others |
Value Chain & Pricing Dynamics
Backward integration into North Atlantic fishery networks and European abattoir rendering operations anchors pricing power for native collagen processors. Captive supply of kosher-halal certified marine feedstock and pharmaceutical-grade bovine inputs insulates certified suppliers from commodity spot volatility while commanding premium positioning in medical device contracts.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-grade levels stratifies native collagen procurement. Price differentiation rests on ISO 17025 laboratory accreditation status and EFSA novel food authorization completeness, with sterile matrix suppliers capturing margins threefold above commodity gelatin processors. Cost compression in food-grade bovine gelatin is intensifying because rendering plant capacity constraints across German and French abattoir networks limit supply elasticity. Pharmaceutical capsule manufacturers exhibit lowest price sensitivity due to regulatory switching costs, while functional food blenders negotiate aggressively on peptide volume commitments.
Supply Chain Analysis
Domestic-content requirements under EU REACH chemical safety registrations and China's NMPA medical device localization mandates are reshaping sourcing patterns for multinational collagen suppliers. Production gravity centers on Germany, China, and Japan, with each jurisdiction developing captive extraction capacity to reduce import dependency. Raw material flows draw from North Atlantic fishery byproduct streams, European cattle rendering networks, and Shandong coastal marine processing clusters. Single-source vulnerability concentrates in kosher-halal dual-certified marine supply, where sustainable fishery quota restrictions in Pacific and Atlantic waters constrain expansion. Distribution runs through specialized cold-chain logistics providers for medical-grade matrices, while commodity peptides flow through ingredient broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in native collagen hinges on enzymatic hydrolysis capability investments that upgrade food-grade gelatin output into premium peptide fractions. Cold-extraction technology deployment for triple-helical preservation opens medical device positioning beyond commodity volumes.
For Market Incumbents: Deploy ISO 13485 quality system certification as a defensive moat against emerging precision medical specialists. Consolidate rendering plant relationships across Bavarian and Rhine-Ruhr industrial corridors to secure bovine input stability against cattle herd fluctuation risks. Accelerate sterile processing infrastructure capex before legacy food-grade capacity reconfiguration costs escalate. For New Entrants and Emerging Players: Specialized distributors with cold-chain logistics represent the most viable channel partnership for penetrating Swiss and Dutch aesthetic medicine clinics. Indonesia and Malaysia present underpenetrated white-space for halal-certified marine collagen in pharmaceutical capsule applications. Direct-to-practitioner positioning bypasses entrenched ingredient broker networks that dominate European nutraceutical channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale marine extraction specialists because kosher-halal dual certification scarcity creates durable competitive positioning against commodity bovine processors. Acquisition targets should demonstrate backward integration into sustainable fishery sourcing with carbon footprint documentation aligned to EU Green Deal incentives. Watch EFSA health claim substantiation rulings on collagen-specific beauty and mobility benefits as the inflection signal determining premium pricing justification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Fishery Sourcing | Secures kosher-halal dual certification advantages for Asia-Pacific pharmaceutical capsule demand. |
| ISO 13485 Medical Device Quality System Certification | Enables sterile matrix supply relationships with Swiss and Dutch tissue engineering laboratories. |
| EFSA Health Claim Dossier Investment | Justifies premium peptide pricing in German and French nutricosmetic joint health positioning. |
| Cold-Extraction Technology Deployment | Preserves triple-helical integrity for 3D bioprinting applications above 300 kDa molecular weight thresholds. |
| Direct-to-Practitioner Distribution Launch | Bypasses general chemical suppliers for orthopedic clinic and aesthetic medicine procurement autonomy. |
Study Parameters
Bottom-up nutraceutical and medical device demand modeling reconciled against top-down marine and bovine extraction capacity tracking forms the analytical core of this study. Primary interviews with gelatin plant managers, pharmaceutical procurement leads at capsule manufacturers, regulatory affairs directors navigating EFSA novel food pathways, and biomedical engineers at tissue engineering laboratories were cross-validated against secondary sources including EFSA novel food authorization databases, EU REACH registration filings, FDA GRAS self-affirmation notices, and ISO 17025 laboratory accreditation registries.
Input-output matrices mapping enzymatic hydrolysis intensity, molecular weight preservation tiers, and certification grade requirements to end-use demand segments drove volume and value projections across the analysis window. Segmentation dimensions modeled include product type, source species, application vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA health claim substantiation timelines and NMPA medical device registration pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sustainable fishery quota restrictions, cattle herd disease outbreaks affecting rendering plant input supply, and evolving ISO quality benchmark revisions. Forecasts reflect documented assumptions regarding EFSA authorization pathway durations and cold-chain logistics cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Magtein Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Nattokinase Market