
 Cognitive Health Ingredients Market | 2026-2036
Cognitive Health Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Health Ingredients Market Analysis
Subscription-based personalized nutrition programs is expanding the addressable market beyond traditional retail channels. Thorne leverages direct-to-consumer physician partnerships to sustain premium positioning. Four Sigmatic anchors its growth in functional mushroom-based cognitive formulations. Stratum Nutrition differentiates through clinically validated ingredient platforms.
Cognitive health ingredients comprise bioactive compounds including phospholipids, amino acids, herbal extracts, and vitamins formulated to support memory, focus, and neuroprotection, typically standardized to active marker compounds such as phosphatidylserine or bacopa glycosides. These ingredients serve nutraceutical, functional food, and dietary supplement manufacturers targeting cognitive performance across adult demographics. Phospholipids command the highest margin pools due to manufacturing complexity and clinical substantiation requirements. Herbal extracts represent the fastest-growing category as adaptogenic positioning gains traction in functional beverages and clean-label supplements.
The FDA's New Dietary Ingredient notification process and the FTC's substantiation requirements for cognitive claims create compliance barriers that favor established suppliers with clinical documentation. The EFSA's health claims framework in Europe restricts permitted cognitive benefit statements, compressing marketing latitude for entrants. Stakeholders must monitor evolving substantiation standards across jurisdictions to determine portfolio prioritization and regional launch sequencing.
Market Dynamics
The FDA's New Dietary Ingredient notification requirements compress product development timelines and favor suppliers with pre-existing clinical dossiers, creating asymmetric access barriers between established phospholipid manufacturers and emerging adaptogenic extract entrants.
Growth Catalysts
- Nootropic formulation demand:Adult consumers in the United States prioritize memory and focus supplements, expanding the addressable base beyond clinical populations into mainstream wellness.
- FTC substantiation clarity:The Commission's enforcement guidance on cognitive claims provides compliance roadmaps that reduce regulatory uncertainty for documented ingredients.
- Functional beverage integration:Clean-label adaptogenic positioning in ready-to-drink formats opens incremental volume channels beyond traditional capsules and tablets.
Market Restraints
- Phospholipid input concentration:Soy and sunflower lecithin supply chains concentrate in specific agricultural regions, exposing margin pools to commodity volatility and crop yield fluctuations.
- EFSA health claims restriction:The European framework permits only narrow cognitive benefit statements, compressing marketing latitude and forcing portfolio prioritization toward other jurisdictions.
- Clinical validation cost burden:Randomized controlled trials for novel bioactives require seven-figure investments, freezing out early-stage ingredient developers without pharmaceutical backing.
Strategic Opportunities
- Subscription channel expansion:Direct-to-consumer personalized nutrition programs bypass retail margin stacking and capture recurring revenue with higher lifetime value metrics.
- Physician partnership models:Professional-grade distribution through integrative medicine practitioners commands price premiums and reduces consumer education burdens.
- Functional mushroom convergence:Lion's mane and cordyceps extracts bridge traditional herbal positioning with modern nootropic science, opening formulation white space in both supplements and beverages.
Industry Challenges
- Dual-jurisdiction dossier management:Maintaining parallel FDA NDI notifications and EFSA novel food approvals strains regulatory affairs capacity at mid-tier suppliers.
- Active marker standardization:Bacopa glycoside and phosphatidylserine content variability across raw material lots forces costly in-house testing infrastructure.
- Legacy ERP integration:Batch record systems designed for commodity ingredients struggle to trace botanical provenance and certificate-of-analysis documentation required for premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Health Ingredients Market |
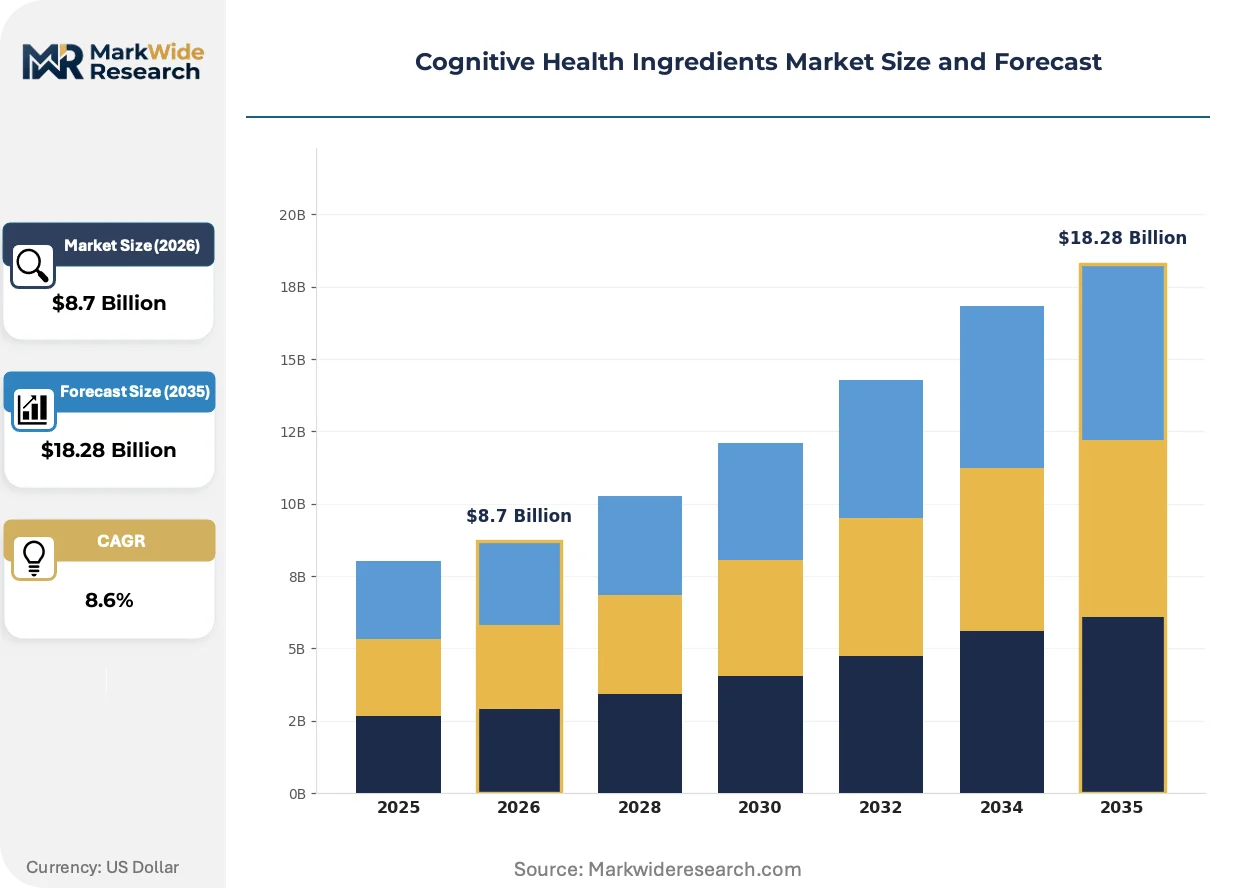
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $18.28 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Amino Acids, Phospholipids, Vitamins Application: Functional Foods, Dietary Supplements, Beverages, Nutraceuticals End User: Adults, Seniors, Students, Athletes Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Four Sigmatic, Moon Juice, Ekang Nutra, Thorne, Life Extension, Stratum Nutrition, Host Defense, Laird Superfood, Intermountain Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Health Ingredients Market Emerging Trajectories
Ingredient traceability technologies and bioavailability enhancement methods are compressing the traditional gap between pharmaceutical-grade and nutraceutical-grade cognitive compounds, forcing suppliers to recalibrate quality signaling and pricing architecture.
Microencapsulation and liposomal delivery systems are decentralizing the historical dominance of standard powder extracts by enabling water-dispersible phospholipid formats. Beverage manufacturers in North America and Western Europe are adopting these platforms at accelerating pace, collapsing the formulation barrier that previously confined high-margin ingredients to softgel and capsule formats. This dispersion is compressing channel-specific margin premiums and forcing ingredient suppliers to develop application-technical service capabilities.
EFSA's evolving Novel Food catalog and the FDA's expanded enforcement discretion on certain botanicals are reshaping launch sequencing strategies for European and American markets. The industrial consequence is a bifurcated dossier approach where suppliers now front-load European safety assessments to unlock subsequent US market entry. Botanical extract categories with pending EFSA opinions face delayed commercialization timelines relative to phospholipid platforms with established regulatory histories.
Practitioner-channel purchasing is consolidating around platforms that bundle continuing education with formulary access, displacing traditional distributor relationships in the professional segment. Integrative medicine clinics and functional medicine practices increasingly source through credentialled buying groups that demand exclusive SKUs and clinical training support. This concentration is most visible in the United States, where direct-to-practitioner models now capture significant volume in phosphatidylserine and omega-3 phospholipid categories previously dominated by retail pharmacy distribution.
Cognitive Health Ingredients Market Segmentation
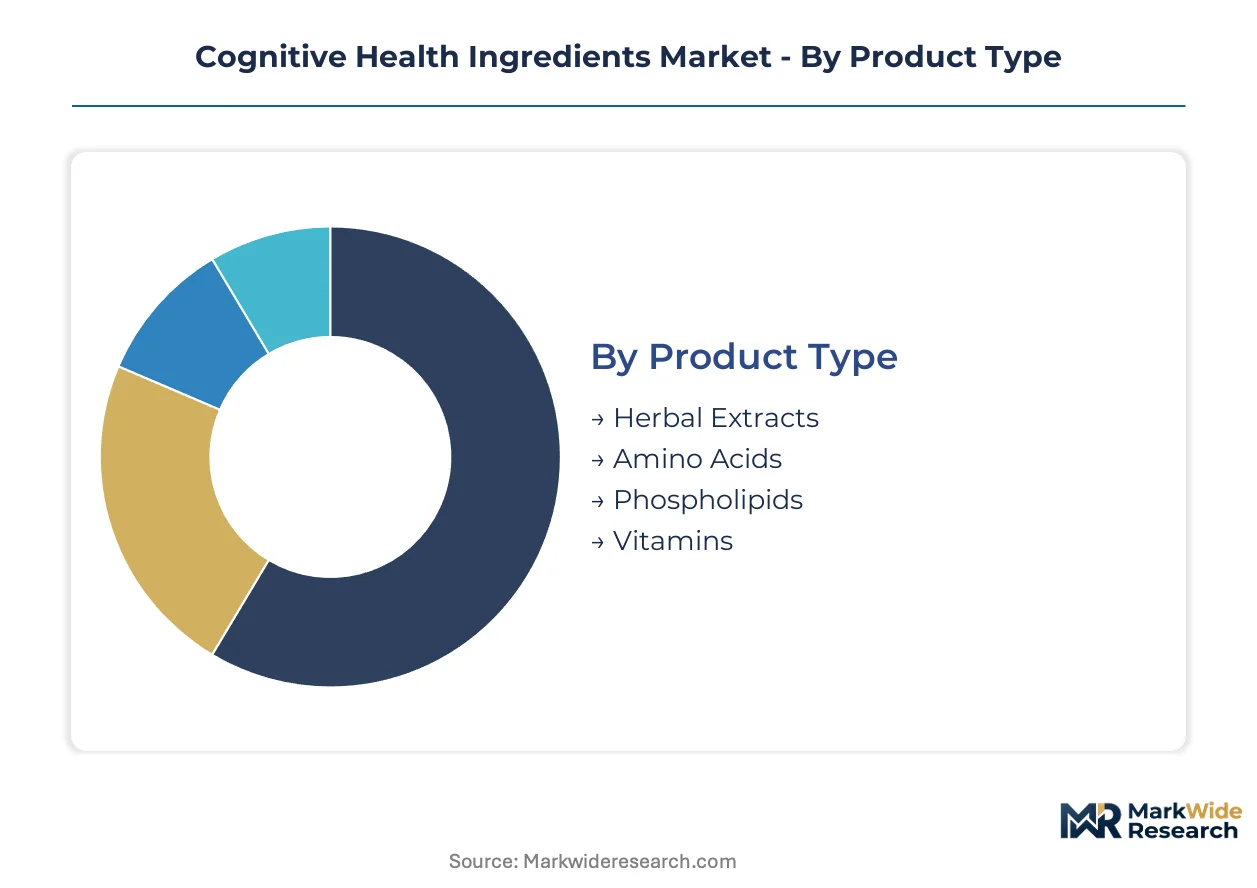
Cognitive health ingredients traverse multiple formulation contexts, from standalone capsules to embedded functional food matrices. Segmentation reveals how phospholipid suppliers, adaptogenic extract houses, and vitamin compounders target divergent technical requirements and margin structures across delivery formats.
Product Type:
Integration depth varies sharply: phospholipids and amino acids embed primarily as standalone actives in softgels, while herbal extracts increasingly penetrate beverage matrices requiring dispersion stability.
- Phospholipids:Phosphatidylserine and phosphatidylcholine fractions command premium positioning due to manufacturing complexity and clinical dossier requirements. Demand concentrates in the United States practitioner channel, where integrative medicine clinics prioritize memory-support formulations with documented bioactivity.
- Herbal Extracts:Bacopa, ginkgo, and lion's mane preparations bridge traditional positioning with nootropic science. Beverage manufacturers in North America adopt water-dispersible formats fastest, collapsing the formulation barrier that previously confined these actives to capsules.
- Amino Acids:L-theanine and acetyl-L-carnitine serve stackable nootropic formulations with established safety profiles.
- Vitamins:B-complex compounds and vitamin D3 support foundational cognitive maintenance positioning in mass-market supplements.
Phospholipids lead volumes today; herbal extracts are gaining share fastest.
Application:
Cost tier stratification separates premium nutraceutical positioning from mass-market functional food embedding, with beverage applications commanding intermediate technical service investments.
- Dietary Supplements:Capsule and tablet formats retain the highest ingredient purity specifications and clinical substantiation requirements. The FTC's cognitive claim enforcement guidance shapes formulation decisions here most directly.
- Functional Foods:Fortified bars, cereals, and dairy alternatives require heat-stable actives and masking technologies. Supply chains concentrate around North American co-manufacturers with beverage-adjredient expertise.
- Beverages:Ready-to-drink nootropic and adaptogenic formulations demand liposomal or microencapsulated delivery systems.
- Nutraceuticals:Medical-grade positioning through practitioner channels commands price premiums and reduces consumer education burdens.
Dietary supplements dominate revenue; beverages expand most quickly.
End User:
Customer type segmentation tracks life-stage cognitive priorities, from academic performance optimization through age-related neuroprotection.
- Adults:Working-age consumers drive mainstream nootropic adoption for focus and stress resilience, expanding the addressable base beyond clinical populations.
- Seniors:Memory maintenance formulations target the highest willingness-to-pay segment, with practitioner-channel purchasing consolidating around credentialed buying groups.
- Students:Academic performance positioning concentrates in online retail channels with subscription-based replenishment models.
- Athletes:Reaction-time and mental stamina applications bridge sports nutrition and cognitive health categories.
Adults anchor current demand; seniors show steepest spending trajectory per capita.
Distribution Channel:
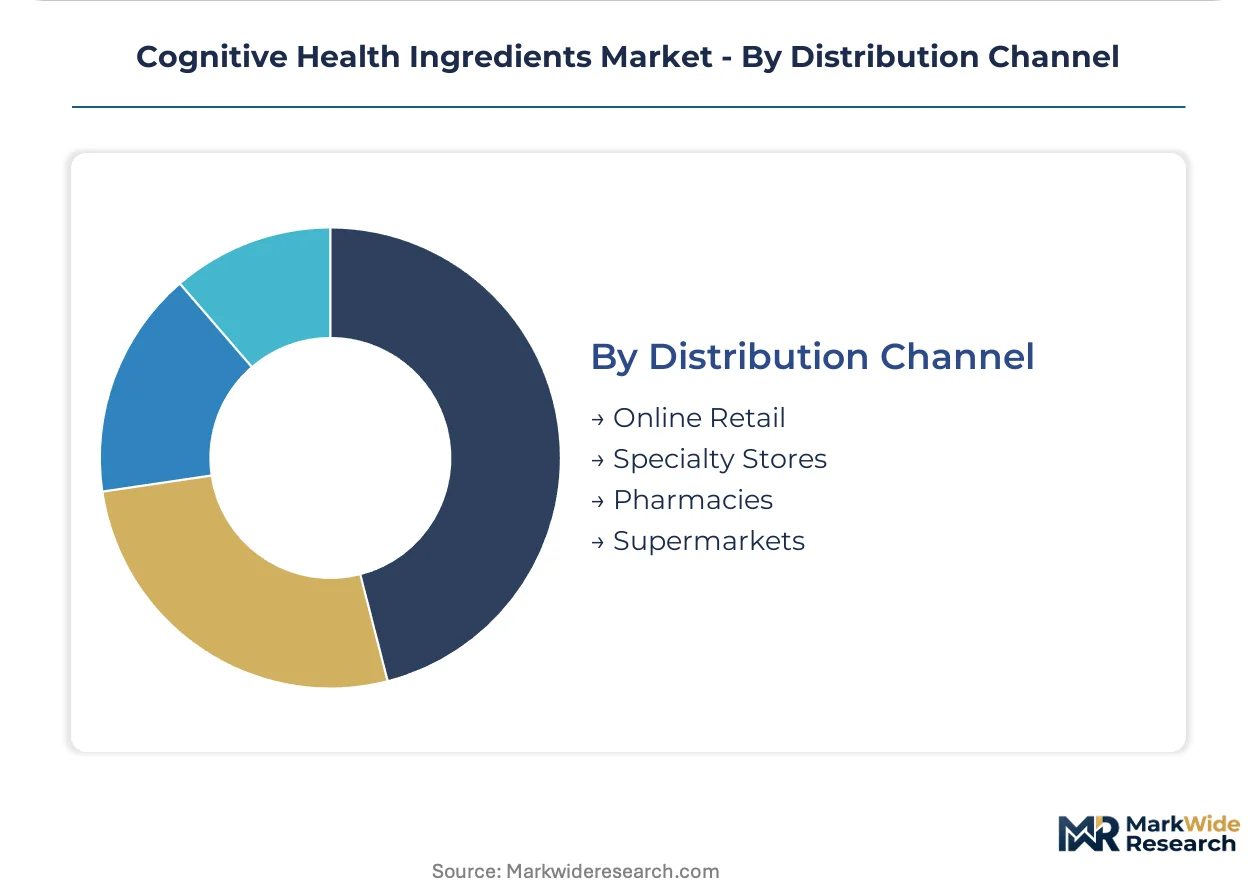
Geography of purchase increasingly fragments between direct-to-consumer platforms and professional-grade procurement systems.
- Online Retail:Subscription-based personalized nutrition programs bypass retail margin stacking and capture recurring revenue with higher lifetime value metrics.
- Specialty Stores:Natural products retailers emphasize clean-label adaptogenic positioning and functional mushroom convergence.
- Pharmacies:Mass retail pharmacy distribution faces displacement from practitioner-channel consolidation in phosphatidylserine and omega-3 phospholipid categories.
- Supermarkets:Mainstream grocery penetration remains limited to fortified functional foods with broad consumer recognition.
Online retail leads volume growth; specialty stores retain premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production footprints as ingredient suppliers relocate manufacturing to jurisdictions with streamlined novel-food approval pathways. Cost-of-compliance gaps between the FDA's New Dietary Ingredient notification process and EFSA's Novel Food catalog are accelerating facility investments in North American and select Asian markets.
United States
Practitioner-channel purchasing and direct-to-consumer subscription models drive ingredient demand, with integrative medicine clinics consolidating procurement around credentialed buying groups. The FDA's NDI notification requirements and FTC substantiation guidance shape formulation decisions and favor suppliers with pre-existing clinical dossiers. Manufacturing clusters concentrate in Utah and Colorado, where dietary supplement contract manufacturers have expanded liposomal and microencapsulation capabilities to serve beverage format growth.
Germany
EFSA's restrictive health claims framework compresses marketing latitude for cognitive benefit statements, forcing portfolio prioritization toward export markets. The country's pharmaceutical-grade ingredient heritage supports medical-nutrition positioning through pharmacy and practitioner channels. Industrial activity clusters in North Rhine-Westphalia and Bavaria, where contract manufacturers serve both domestic nutraceutical brands and pan-European functional food producers seeking heat-stable active delivery systems.
China
Domestic demand for nootropic and adaptogenic ingredients expands through e-commerce and cross-border channels, with consumer education investments bridging traditional herbal positioning and modern cognitive science claims. NMPA registration requirements and GB standards for functional foods create compliance thresholds that favor established domestic suppliers with documented safety profiles. Production gravity concentrates in Jiangsu and Zhejiang provinces, where phospholipid and botanical extract houses have scaled manufacturing to serve both domestic and export markets.
India
Ayurvedic heritage and growing working-age wellness consciousness converge to expand addressable demand for bacopa and ashwagandha-based cognitive formulations. FSSAI regulations for nutraceuticals and the CDSCO's evolving framework for functional ingredients shape product development timelines and import requirements. Manufacturing activity clusters in Gujarat and Maharashtra, where ingredient processors have invested in standardization infrastructure to meet export market specifications for active marker compounds.
Japan
Aging demographics and established functional food culture sustain premium positioning for phosphatidylserine and phosphatidylcholine ingredients targeting memory maintenance. PMDA and METI oversight of Foods with Function Claims creates a distinct regulatory pathway that rewards clinical substantiation with permitted benefit statements. Industrial concentration in the Kanto region around Tokyo supports both domestic brand formulation and ingredient export to Southeast Asian markets adopting Japanese regulatory models.
Cognitive Health Ingredients Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with phospholipid suppliers commanding consolidated positions due to manufacturing complexity barriers while adaptogenic extract houses face fragmented competition. The vendor base organizes into three strategic archetypes: clinical-dossier phospholipid manufacturers, functional-mushroom positioning specialists, and subscription-channel direct-to-consumer brands. Competitive moves concentrate on practitioner partnership programs and application-technical service capabilities for beverage format integration.
Within the clinical-validation tier, Thorne and Life Extension exemplify professional-grade positioning through integrative medicine channel access. Four Sigmatic and Moon Juice occupy positions at the functional-mushroom convergence point, bridging adaptogenic tradition with nootropic science in direct-to-consumer formats. Stratum Nutrition represents the ingredient-platform archetype, differentiating through clinically validated raw material supply to downstream formulators rather than finished brand presence.
| Leading Market Players |
|---|
| Four Sigmatic |
| Moon Juice |
| Ekang Nutra |
| Thorne |
| Life Extension |
| Stratum Nutrition |
| Host Defense |
| Laird Superfood |
| Intermountain Nutrition |
| Others |
Supply Flow & Price Mechanics
Clinical-grade phospholipid certification separates premium phosphatidylserine suppliers from commodity lecithin processors, and this bifurcation manifests in divergent margin structures and procurement strategies across the ingredient value chain. Practitioner-channel buyers absorb three-tier pricing premiums for FDA-notified ingredients while beverage manufacturers negotiate volume discounts on standardized herbal extracts.
Pricing Analysis
Distributor margin stacking compresses net-back prices for phospholipid suppliers serving retail pharmacy channels, while direct-to-practitioner models bypass intermediaries and preserve premium positioning. Three-tier pricing structure across premium, standard, and economy levels tracks clinical dossier depth and active marker standardization. Pricing pressure stems from sunflower lecithin commodity volatility and crop yield fluctuations in Ukraine and Argentina. Mass-market supplement brands exhibit highest price sensitivity; integrative medicine clinics prioritize documented bioactivity over unit cost.
Supply Chain Analysis
Ocean freight rate volatility and cold-chain requirements for phospholipid fractions add cost layers that concentrate margin pressure on European importers. Manufacturing gravity centers on the United States, China, and India, with phospholipid processing clusters in Utah and Colorado and botanical extraction concentrated in Jiangsu and Gujarat. Soy and sunflower lecithin feedstocks draw from agricultural regions exposed to climate volatility. Single-source vulnerability in phosphatidylserine manufacturing creates bottleneck risk. Distribution runs through credentialed buying groups consolidating practitioner-channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cognitive health ingredients market represents a late-cycle quality story where working-age wellness consumers are shifting demand toward clinically substantiated phospholipid formulations with documented bioactivity markers.
For Market Incumbents: To counter regulatory dossier inflation and emerging adaptogenic extract competitors, established phospholipid manufacturers should deepen backward integration into sunflower and soy lecithin sourcing to secure input cost stability. Incumbents must also expand application-technical service capabilities for beverage format integration, as liposomal delivery systems displace traditional softgel dominance. For New Entrants and Emerging Players: Water-dispersible lion's mane extraction technology offers a defensible entry point into the fastest-expanding beverage application segment. New entrants should prioritize white-space formulation partnerships with North American ready-to-drink nootropic brands before pursuing saturated capsule markets. Direct-to-consumer subscription models bypass retail margin stacking and enable recurring revenue capture with superior lifetime value economics. For Investors and Strategic Acquirers: Asymmetric upside sits with clinically validated ingredient platforms possessing pre-existing FDA NDI notifications and EFSA novel food approvals. Long-term viability favors suppliers with dual-jurisdiction dossier management capabilities and practitioner-channel distribution infrastructure. The signal to watch is consolidation velocity among credentialed buying groups consolidating integrative medicine procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Dossier Expansion | FDA NDI notifications and EFSA novel food approvals create asymmetric access barriers for premium phospholipid positioning. |
| Backward Integration into Feedstocks | In-house lecithin processing insulates margin pools from sunflower and soy commodity volatility in Ukraine and Argentina. |
| Beverage Format Technical Service | Liposomal and microencapsulation capabilities unlock water-dispersible phospholipid demand from North American RTD manufacturers. |
| Practitioner Partnership Programs | Integrative medicine channel access commands price premiums and reduces consumer education burdens for memory-support formulations. |
| Subscription Channel Development | Direct-to-consumer personalized nutrition programs capture recurring revenue with higher lifetime value metrics than retail distribution. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dietary supplement formulators, regulatory affairs directors at ingredient suppliers, integrative medicine practitioners, and beverage product development leads with secondary validation against FDA NDI notification databases, EFSA novel food opinions, FTC enforcement guidance documents, and customs trade records. Bottom-up ingredient demand modeling and top-down market sizing triangulated volume and value estimates.
Comparable-period anchoring tied projection assumptions to historical phospholipid and herbal extract demand patterns across the analysis window. Segmentation dimensions modeled include product type, application format, end-user life stage, and distribution channel geography. CAGRs derived from regression analysis of ingredient uptake trajectories, incorporating clinical substantiation investment cycles and regulatory approval timelines as industry-specific forecast inputs.
The model holds under stable regulatory substantiation standards and intact practitioner-channel consolidation; deviation in EFSA health claims framework expansion or FDA NDI enforcement discretion shifts would revise volume trajectories. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Magtein Market
Nutraceuticals
Piracetam Market
Nutraceuticals
Tetrahydropalmatine Market