
 US Collagen Market | 2026-2036
US Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
US Collagen Market Intelligence
Revenue from branded nutraceutical formulations is reshaping competitive positioning away from bulk gelatin supply. Vital Proteins LLC leverages its strong direct-to-consumer brand to capture this value shift. Meanwhile, established B2B players like GELITA AG sustain market share through large-scale manufacturing and supply agreements with food and pharmaceutical companies. Nitta Gelatin NA Inc. specializes in customized gelatin and collagen peptide solutions for specific industrial applications.
Collagen is the primary structural protein in animal connective tissues, characterized by a triple-helix structure rich in specific amino acids like glycine and proline. Its commercial purpose in the US is as a functional ingredient in nutraceuticals and cosmetics, valued for its physiological benefits. Bovine sources dominate the market due to supply chain scale, though marine collagen is gaining share rapidly. The nutraceuticals end-user segment commands the highest value, driven by strong consumer interest in joint and skin health applications.
The US market operates under the purview of the Food and Drug Administration (FDA), which regulates collagen as a food ingredient or dietary supplement. The Federal Trade Commission (FTC) governs the marketing claims associated with collagen products, scrutinizing unsupported statements about health benefits. Future growth depends on suppliers' ability to validate product efficacy through clinical data and ensure supply chain transparency for consumers.
Market Dynamics
The US collagen market's structure is defined by the bifurcation between bulk ingredient supply for food processing and high-value, branded nutraceuticals. This split creates distinct supply chains, pricing tiers, and competitive pressures for participants, separating commodity-focused players from direct-to-consumer brands.
Growth Catalysts
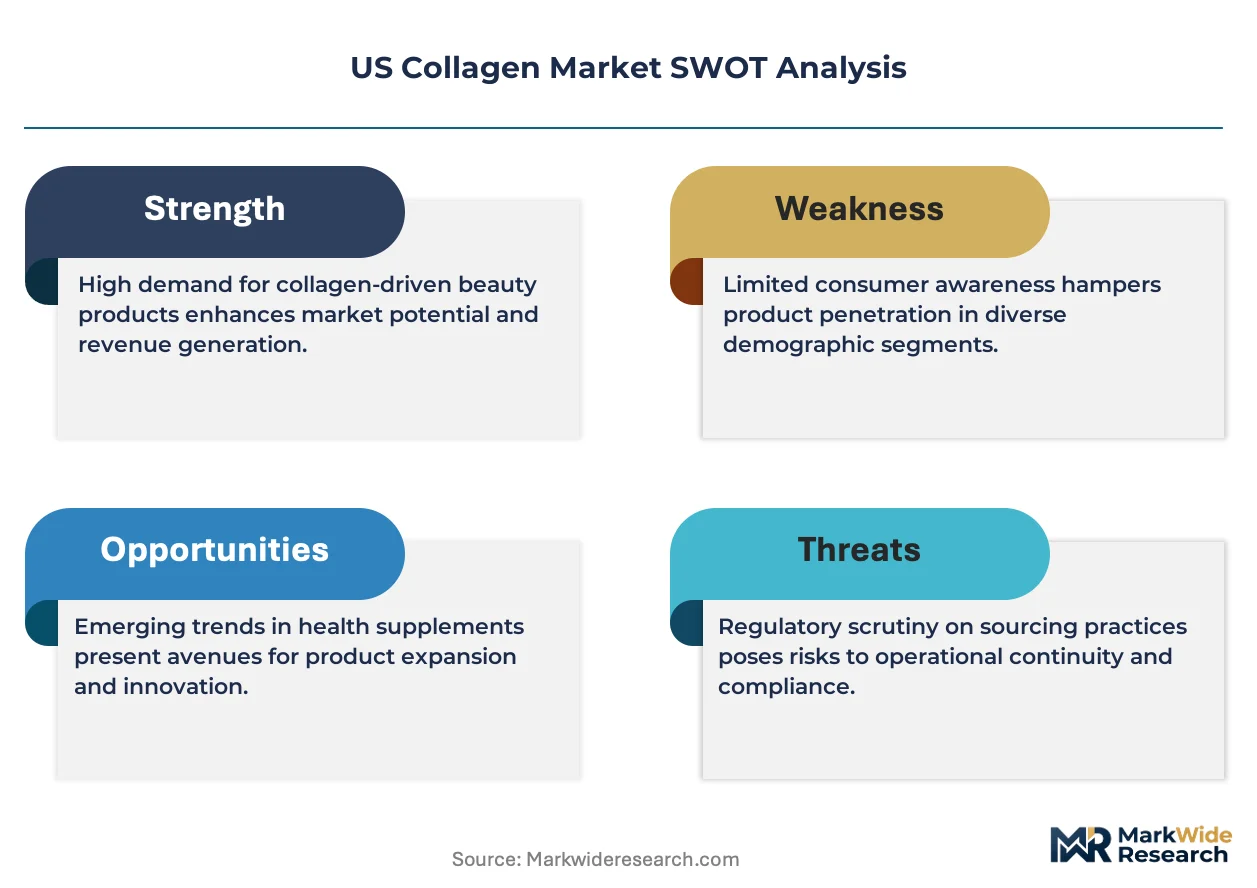
- FDA Regulatory Pathway:The FDA's Generally Recognized as Safe (GRAS) notification process provides a clear route to market for novel collagen ingredients, encouraging innovation in food and beverage applications.
- Preventative Health Demand:Consumer focus on preventative health drives demand in the nutraceuticals sector for products targeting joint support and skin wellness, particularly in states like California and Florida.
- Hydrolysis Technology:Advancements in hydrolysis techniques are creating more specialized collagen peptides with improved bioavailability, expanding their functional use in premium cosmetics and functional foods.
Market Restraints
- Raw Material Volatility:Fluctuation in bovine hide and bone prices, driven by the broader cattle and leather industries, creates significant input cost instability for US collagen producers.
- Plant-Based Substitution:The rise of vegan "collagen-booster" products, while not chemically collagen, competes for consumer attention and shelf space in the wellness and beauty-from-within markets.
- FTC Claims Scrutiny:The Federal Trade Commission's enforcement against unsupported health benefit claims requires careful marketing, limiting how brands can communicate product efficacy and creating compliance burdens.
Strategic Opportunities
- Medical-Grade Applications:Developing highly purified collagen for tissue engineering and advanced wound care represents an opportunity to enter high-value medical device and regenerative medicine markets.
- Sustainable Marine Sourcing:Establishing certified, transparent supply chains for fish-derived collagen can attract environmentally conscious consumers and justify premium pricing in the nutraceuticals segment.
- Clinical Nutrition Channels:Expansion into specialized distribution channels targeting dietitians and healthcare practitioners offers a new avenue for products supported by strong clinical efficacy data.
Industry Challenges
- Source Material Traceability:Ensuring and documenting full traceability regarding animal origin and welfare is a complex operational challenge necessary to meet rising consumer and regulatory demands for transparency.
- Peptide Profile Standardization:A lack of standardized testing methodologies for collagen peptide size and composition makes it difficult for formulators to compare ingredients and ensure product consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Collagen Market |
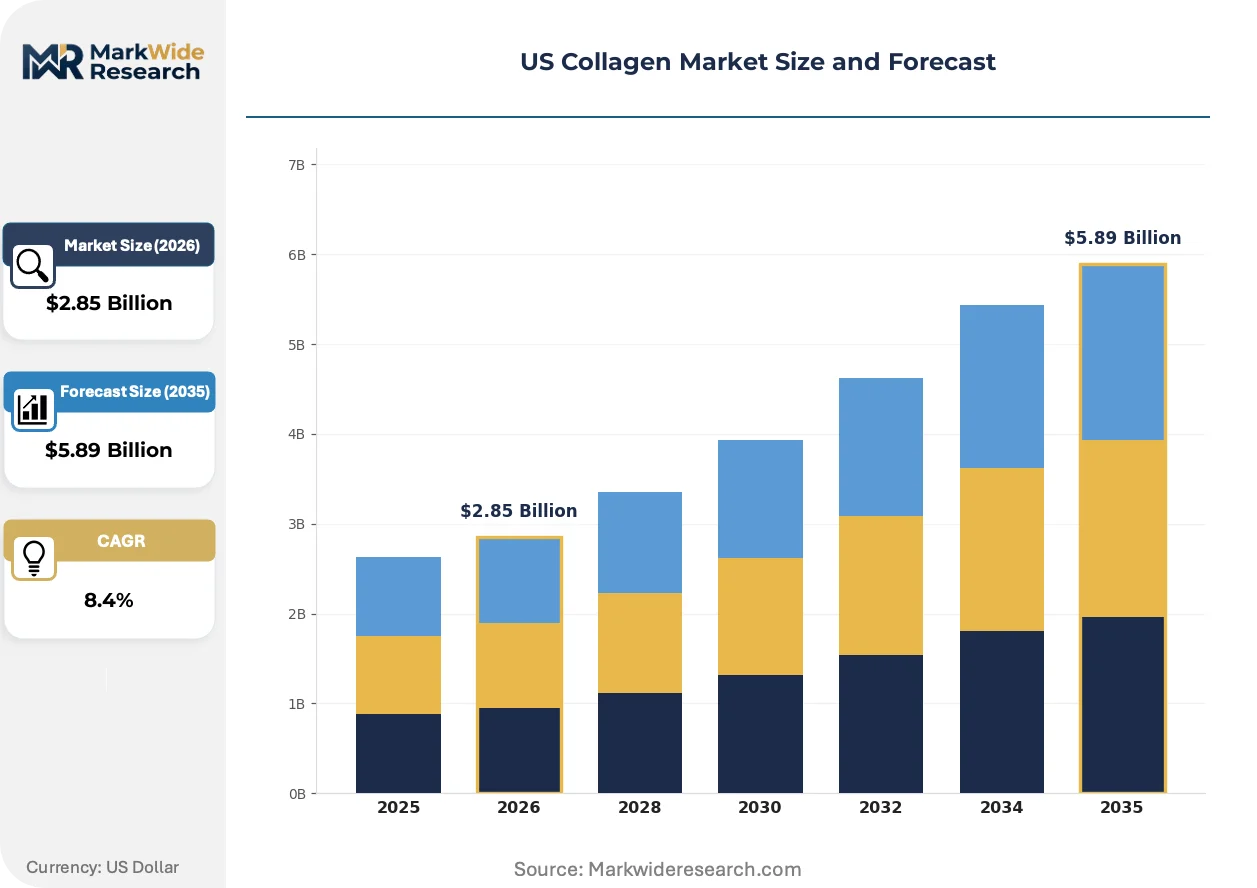
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Native Collagen End User: Nutraceuticals, Cosmetics, Food & Beverage, Pharmaceuticals Application: Skin Health, Joint Health, Bone Health, Muscle Recovery Source: Bovine, Porcine, Marine, Chicken |
| Companies Covered | Rousselot, GELITA AG, Nitta Gelatin NA Inc., Tessenderlo Group, Weishardt Holding SA, Collagen Solutions Plc, Collagen Matrix Inc., Darling Ingredients Inc., Vital Proteins LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Collagen Market Strategic Shifts & Innovations
The market's evolution is driven by a convergence of formulation science and digital consumer engagement. This shift prioritizes ingredient functionality and brand storytelling over simple bulk material supply, altering the basis of competition for all participants.
Precision fermentation is an emerging technology used to produce bio-identical collagen proteins without animal inputs. Niche biotech startups and ingredient developers are pioneering this method, attracting interest from the vegan and ethical consumer segments. This technology is virtualizing the traditional animal-based supply chain, creating a potential long-term alternative to bovine and marine sources.
The FDA's proposed updates to the definition of "healthy" on food labels are influencing product formulation. This regulatory shift encourages manufacturers to incorporate functional ingredients like collagen into foods that can meet new nutrient density criteria. The beverage and snack food segments are most affected, actively reformulating products to qualify for the "healthy" claim and appeal to wellness-oriented shoppers.
A significant behavioral shift is the move toward subscription-based, direct-to-consumer (DTC) purchasing models for nutraceuticals. This trend disintermediates traditional brick-and-mortar retail, allowing brands to own the customer relationship and gather valuable data. This model is most prominent in wellness-focused urban centers in states like California, where brand loyalty is built through digital community engagement.
US Collagen Market Segmentation
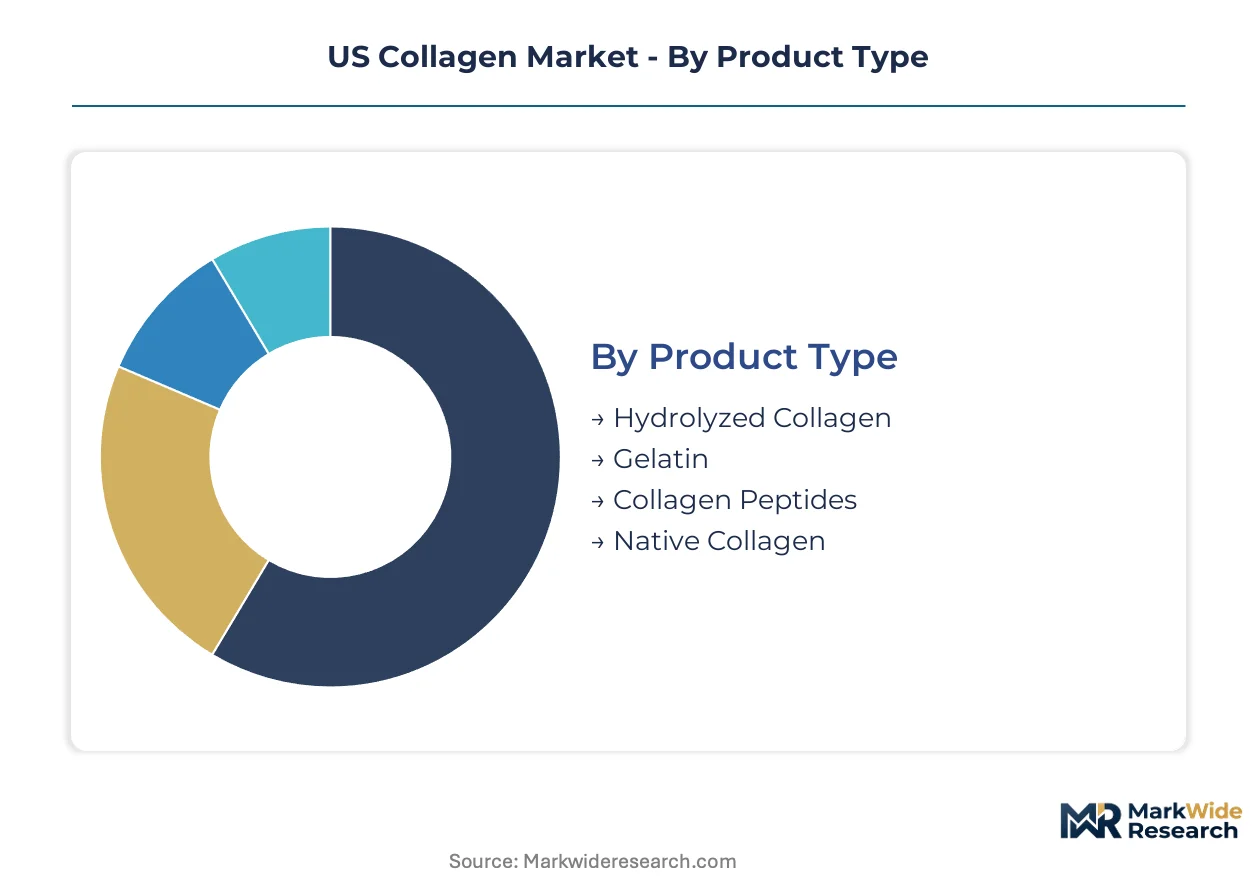
Segmentation of the US collagen market reveals distinct value propositions and competitive landscapes across various product forms, end-user applications, and raw material sources. Understanding these divisions helps stakeholders identify areas of high growth, specific consumer needs, and the regulatory nuances impacting each segment.
Product Type:
The product types in the US collagen market dictate the level of technical support and post-sale engagement required by formulators.
- Hydrolyzed Collagen:This form consists of smaller peptide chains, making it highly soluble and easily absorbed by the body. Demand concentrates in nutraceuticals for general wellness, driven by its ease of formulation into various products.
- Collagen Peptides:Defined by specific molecular weight profiles, these peptides are engineered for targeted physiological benefits such as improved bioavailability for skin elasticity or joint support. Premium cosmetics and functional beverages in the US represent a significant demand area.
- Gelatin:This is a gelling agent widely used in the food and pharmaceutical industries for its textural properties and encapsulation capabilities.
- Native Collagen:Retaining its triple-helix structure, native collagen finds application in more specialized areas like medical devices and tissue engineering due to its structural integrity.
By volume, Gelatin leads. By growth pace, Collagen Peptides is ahead.
End User:
End-user segments in the US collagen market define distinct application requirements and regulatory pathways.
- Nutraceuticals:This segment encompasses dietary supplements and functional foods, valued for their health benefits beyond basic nutrition. Wellness-focused consumers in states like California and Florida drive demand for joint and skin health applications.
- Cosmetics:Collagen is incorporated into topical creams, serums, and ingestible beauty products, targeting skin elasticity and anti-aging benefits. The beauty-from-within trend significantly fuels demand in this sector.
- Food & Beverage:Collagen functions as a protein fortifier, texture enhancer, and functional ingredient in various food and drink products across the US.
- Pharmaceuticals:This segment utilizes collagen for drug delivery systems, wound dressings, and other medical applications requiring biocompatible materials.
Growth in Nutraceuticals is driven by consumer wellness, while Food & Beverage maintains consistent demand.
Application:
The primary applications for collagen in the US market reflect prevalent consumer health concerns and product formulation strategies.
- Skin Health:Collagen products improve skin elasticity, hydration, and overall appearance, appealing to consumers seeking anti-aging solutions. Demand is strong within cosmetics and ingestible beauty products.
- Joint Health:This application focuses on supporting cartilage integrity and reducing discomfort, particularly among active adults and the aging population. Preventative health demand drives purchases in this area.
- Bone Health:Collagen aids in maintaining bone mineral density and preventing conditions like osteoporosis, often consumed as a supplement.
- Muscle Recovery:Athletes and fitness enthusiasts use collagen to support post-exercise repair and protein synthesis, aiding in muscle regeneration.
Consumer interest in Skin Health and Joint Health drives the majority of product innovation.
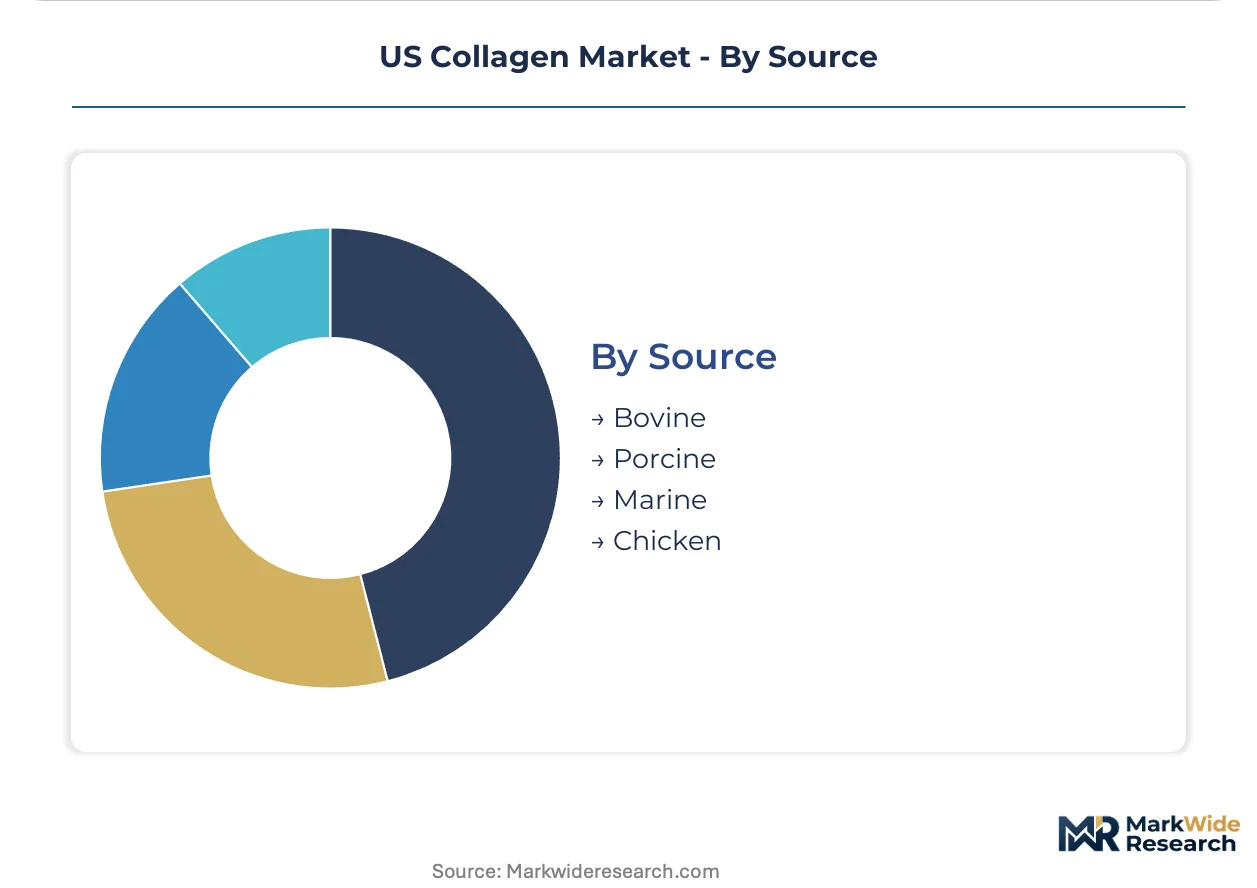
Source:
Collagen sources in the US market reflect established supply chain infrastructures and evolving consumer preferences for origin.
- Bovine:Derived primarily from cattle hides and bones, bovine collagen provides Type I and III collagen, prevalent in large-scale nutraceuticals and food applications. Its established supply chain scale ensures market dominance.
- Marine:Sourced from fish skin and scales, marine collagen is rich in Type I collagen and is perceived as highly pure and sustainable. Demand is increasing in premium beauty and wellness products.
- Porcine:This source offers an alternative to bovine collagen, also providing Type I and III, used in various food and supplement formulations.
- Chicken:Primarily a source of Type II collagen, chicken collagen is specifically targeted for joint health supplements due to its cartilage-derived composition.
While Bovine maintains market dominance, Marine exhibits a rapid expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity contrasts sharply across the US collagen market, with price-sensitive bulk buyers primarily focused on commodity gelatin and premium consumers in wellness-focused states driving demand for high-value collagen peptides. These distinct purchasing behaviors shape distribution strategies and product development efforts across various regional markets. Suppliers must tailor their offerings to meet diverse economic and health-conscious consumer segments.
California
Consumers in California exhibit strong demand for collagen products, particularly for skin and joint health applications, driven by a prevalent wellness culture and high disposable incomes. The California Department of Public Health oversees food and supplement safety, influencing product formulation and labeling. Los Angeles and San Francisco serve as key hubs for nutraceutical innovation and direct-to-consumer brand engagement.
Florida
Florida's aging population and focus on preventative health contribute significantly to collagen consumption, especially for joint support and bone health. The state's Department of Agriculture and Consumer Services enforces food and drug regulations, aligning with federal FDA guidelines. Retirement communities and health-conscious urban centers like Miami drive strong retail and online sales for collagen supplements.
New York Metro
The New York metropolitan area demonstrates robust demand for premium collagen peptides in cosmetic and functional beverage formulations, reflecting a trend towards beauty-from-within solutions. The New York State Department of Health monitors product safety and advertising claims within the state. New York City's fashion and beauty industries foster innovation and consumer adoption of high-end collagen products.
Midwest
The Midwest region, including states like Illinois and Ohio, shows consistent demand for gelatin and hydrolyzed collagen in the food and beverage industry for protein fortification and textural enhancement. The USDA and state-level food safety agencies regulate the processing and distribution of these ingredients. Chicago and other industrial centers host significant food processing facilities utilizing bulk collagen ingredients.
US Collagen Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the US collagen market. The market structure is bifurcated, separating large-scale commodity ingredient manufacturers from specialized peptide producers and consumer-facing brands. Strategic archetypes include established B2B ingredient suppliers, innovative peptide solution providers, and direct-to-consumer wellness product companies. Dominant competitive moves involve securing long-term supply agreements and investing heavily in brand building through digital marketing.
Among established B2B suppliers, GELITA AG exemplifies large-scale manufacturing capabilities, sustaining market share through extensive supply agreements with food and pharmaceutical companies. Nitta Gelatin NA Inc. occupies a position as a specialist, providing customized gelatin and collagen peptide solutions for specific industrial applications. Vital Proteins LLC represents the direct-to-consumer archetype, leveraging its strong brand presence and digital engagement to capture value in the branded nutraceuticals sector.
| Leading Market Players |
|---|
| Rousselot |
| GELITA AG |
| Nitta Gelatin NA Inc. |
| Tessenderlo Group |
| Weishardt Holding SA |
| Collagen Solutions Plc |
| Collagen Matrix Inc. |
| Darling Ingredients Inc. |
| Vital Proteins LLC |
| Others |
Cost & Logistics Intelligence
US inland freight corridors' cost dynamics influence the final pricing of collagen products, driven by the concentrated bovine raw material supply and diverse downstream product differentiation. This concentration impacts both commodity gelatin and high-value nutraceuticals.
Pricing Analysis
Long-term offtake agreements characterize pricing for bulk gelatin, securing consistent supply for food and pharmaceutical manufacturers. Value-based pricing applies to specialized collagen peptides, reflecting their targeted physiological benefits and enhanced bioavailability. Price differentiation stems from quality grade, brand premium for consumer products, and customization for specific industrial uses. Pricing softness affects commodity gelatin due to raw material volatility, while premium nutraceuticals maintain higher margins, appealing to less price-sensitive, wellness-focused consumers.
Supply Chain Analysis
Contract manufacturing capacity for collagen processing is concentrated in regions with large cattle industries, such as the US Midwest and parts of South America. The supply chain draws heavily from bovine hides and bones, alongside fish skins and scales for marine collagen. A significant supply chain risk involves raw material price volatility, influenced by the broader cattle and leather industries. Distribution runs through distinct B2B channels for bulk ingredients and direct-to-consumer or traditional retail for branded nutraceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US collagen market presents a fragmentation opportunity, driven by a significant consumer shift towards preventative health and personalized wellness solutions. This shift creates numerous niches for specialized product offerings.
For Market Incumbents: Build supply chain resilience through diversified sourcing agreements for bovine and marine raw materials. Incumbents like GELITA AG must invest in advanced hydrolysis technology to produce specialized peptides, countering the threat of plant-based substitutes. Enhancing clinical data validation for existing product lines reinforces brand credibility. Strategic R&D into precision fermentation for bio-identical collagen offers a long-term lever against raw material volatility.
For New Entrants and Emerging Players: Medical-grade applications for tissue engineering and advanced wound care represent a high-value white space for new entrants. Sustainable marine collagen sourcing with certified traceability offers another penetrable segment, attracting environmentally conscious consumers. Focusing on niche functional beverages in wellness-focused urban centers, especially via direct-to-consumer models, allows for strong brand building and digital community engagement.
For Investors and Strategic Acquirers: Carve-out targets emerge from specialty ingredient divisions of large food and pharmaceutical conglomerates seeking to divest non-core assets. The long-term viability for specialized collagen peptides remains strong over the next decade, driven by sustained consumer health trends. Investors should target innovative peptide solution providers boasting robust clinical efficacy data and transparent sourcing. Increased FDA GRAS notifications for novel collagen ingredients serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Validation | Establishes product efficacy and supports premium pricing for nutraceuticals. |
| Sustainable Marine Sourcing Certification | Attracts environmentally conscious consumers and justifies higher price points. |
| Precision Fermentation R&D | Develops animal-free collagen alternatives for vegan and ethical consumer segments. |
| Direct-to-Consumer Channel Expansion | Builds brand loyalty and captures valuable customer data in wellness markets. |
| Medical-Grade Product Development | Accesses high-value regenerative medicine and advanced wound care markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, FTC marketing claim enforcement records, and USDA livestock reports. This approach involved extensive interviews with nutraceutical brand managers, food R&D scientists, ingredient procurement leads, and regulatory affairs specialists. Data triangulation from both top-down market sizing and bottom-up component analysis ensures robust validation.
Forecast inputs considered include product type, end-user application, raw material source, and regional demand patterns across the analysis window. An analytical framework integrates historical data with projected market drivers, deriving Compound Annual Growth Rates through regression analysis. Key industry-specific inputs, such as consumer preventative health spending and hydrolysis technology adoption rates, inform future market trajectory.
Stress conditions across raw material price shocks and significant new regulatory restrictions on claims were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions, acknowledging unforeseen shifts in dietary trends or rapid plant-based innovation as potential risk factors. Quarterly review of consumer wellness indices and raw material commodity prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
UK Pet Nutraceuticals Market