
 North America Nutraceuticals Market | 2026-2036
North America Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nutraceuticals Market Analytics
Multi-source botanical sourcing is expanding across North American nutraceutical supply chains as manufacturers hedge against climate-driven crop volatility. Archer Daniels Midland Company leverages its grain-processing infrastructure to secure standardized extract supplies for functional food clients. Koninklijke DSM N.V. anchors its position through synthetic vitamin fermentation capacity in South Carolina and Canada. Nestlé S.A. competes by controlling branded finished-goods distribution through pharmacy and supermarket channels.
Nutraceuticals comprise bioactive compounds, vitamins, minerals, herbal extracts, and functional food ingredients formulated to deliver physiological benefits beyond basic nutrition, typically standardized to active-marker concentrations of 5-95% depending on the compound class. These products serve preventive health management, performance optimization, and chronic condition support across consumer and clinical settings. Functional Foods currently occupies the deepest margin pool as beverage and snack fortification commands premium shelf positioning in supermarkets and online retailers. Herbal Supplements sustains the fastest trajectory as adaptogenic and nootropic botanicals gain traction among health-conscious consumers and athletes seeking non-pharmaceutical cognitive and stress-modulation support.
The FDA enforces Current Good Manufacturing Practice regulations for dietary supplements while Health Canada's Natural and Non-prescription Health Products Directorate mandates site licensing and product licensing for Canadian-market entry, collectively elevating compliance costs that filter smaller operators from pharmacy and supermarket distribution. The FTC actively monitors structure-function claims, forcing brands to substantiate advertising or face consent decrees that restrict market access. Stakeholders must weigh the capital requirements of dual-track FDA-Health Canada compliance against the revenue premium of securing pharmacy shelf space in both markets.
Market Dynamics
The FDA's New Dietary Ingredient notification pathway compresses formulation timelines for novel botanical extracts while Health Canada's site licensing requirements add parallel compliance burdens. Manufacturers must navigate dual-track regulatory submissions to secure pharmacy shelf space across both markets.
Growth Catalysts
- Sports Nutrition Channel Expansion:Pharmacy chains across the United States and Canada now dedicate premium shelf space to performance-focused formulations. This retail penetration exposes nutraceuticals to chronic disease patients seeking non-pharmaceutical interventions.
- FDA's Structure-Function Framework:The regulatory pathway permits health claims without full drug approval, accelerating product commercialization. Brands leverage this mechanism to position adaptogenic botanicals for stress modulation.
- Personalized Wellness Programs:Metro corridors in California and Ontario cluster demand from patients managing diabetes, cardiovascular conditions, and cognitive decline. These programs integrate nutraceuticals with diagnostic monitoring.
Market Restraints
- Dual-Track Compliance Costs:Simultaneous FDA Current Good Manufacturing Practice adherence and Health Canada Natural and Non-prescription Health Products Directorate licensing filters smaller operators from mainstream distribution.
- Climate-Driven Botanical Volatility:Ashwagandha, rhodiola, and bacopa harvests face yield instability from drought cycles in Indian and Chinese growing regions. Manufacturers absorb margin pressure from multi-source hedging strategies.
- FTC Claim Substantiation:Active monitoring of structure-function advertising forces brands to maintain clinical documentation or face consent decrees restricting market access.
Strategic Opportunities
- Functional Food Fortification:Beverage and snack categories remain underpenetrated relative to supplement formats. Brands capturing supermarket premium positioning capture deeper margin pools than pharmacy channels.
- Nootropic Botanical Convergence:L-theanine, lion's mane, and citicoline combinations target knowledge workers and aging populations. Formulation innovation here outpaces regulatory categorization.
- Chronic Disease Integration:Ontario's healthcare system experiments with nutraceutical reimbursement for prediabetes management. Successful pilot programs would unlock institutional procurement volumes.
Industry Challenges
- Active-Marker Standardization:Botanical extracts require 5-95% concentration verification depending on compound class. Analytical chemistry capacity constraints delay batch release timelines.
- Supply Chain Reconfiguration:Near-shoring extract production from Asian suppliers to South Carolina fermentation facilities demands capital redeployment and technical workforce expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nutraceuticals Market |
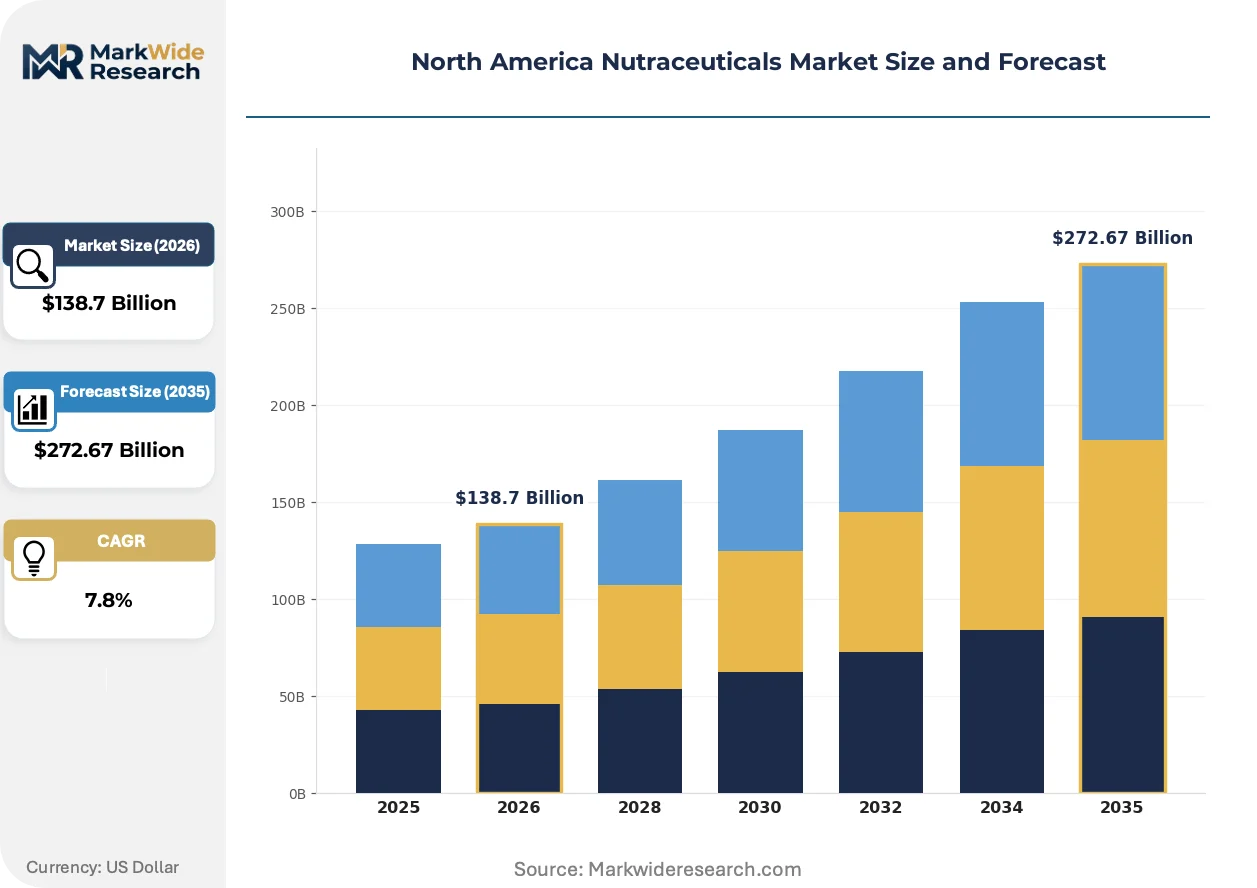
| Market Size in 2026 | $138.7 Billion |
| Market Size in 2035 | $272.67 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Functional Foods Distribution Channel: Health Food Stores, Supermarkets, Online Retailers, Pharmacies End User: Health-conscious Consumers, Elderly, Athletes, Chronic Disease Patients Formulation: Pills, Powders, Capsules, Liquids |
| Companies Covered | Nestlé S.A., Abbott Laboratories, Herbalife Nutrition Ltd., Amway Corp., PepsiCo Inc., General Mills, Inc., Archer Daniels Midland Company, Koninklijke DSM N.V., Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nutraceuticals Market Evolving Landscape
Biotechnology convergence with traditional botanical extraction is compressing development cycles for standardized active compounds. This fusion creates new competitive vectors between synthetic and natural ingredient suppliers.
Precision fermentation technology is unifying pharmaceutical-grade manufacturing discipline with botanical metabolite production. Contract manufacturers in South Carolina and Quebec adopt GMP bioreactor infrastructure previously reserved for drug substances. This capability convergence enables 95% purity thresholds for adaptogenic compounds at commercial scale.
The FTC's intensified scrutiny of cognitive health claims is reshaping advertising compliance workflows. Brands now front-load clinical substantiation before market entry rather than retroactive claim defense. California-based direct-to-consumer operators face the steepest adaptation costs as their historical marketing agility encounters regulatory friction.
Subscription-based replenishment models are displacing pharmacy impulse purchases for core supplement categories. Athletic consumers and chronic disease patients in Toronto and Los Angeles metro areas demonstrate highest retention rates. This channel shift compresses brand marketing spend toward digital acquisition while reducing retail slotting fee dependence.
North America Nutraceuticals Market Segmentation
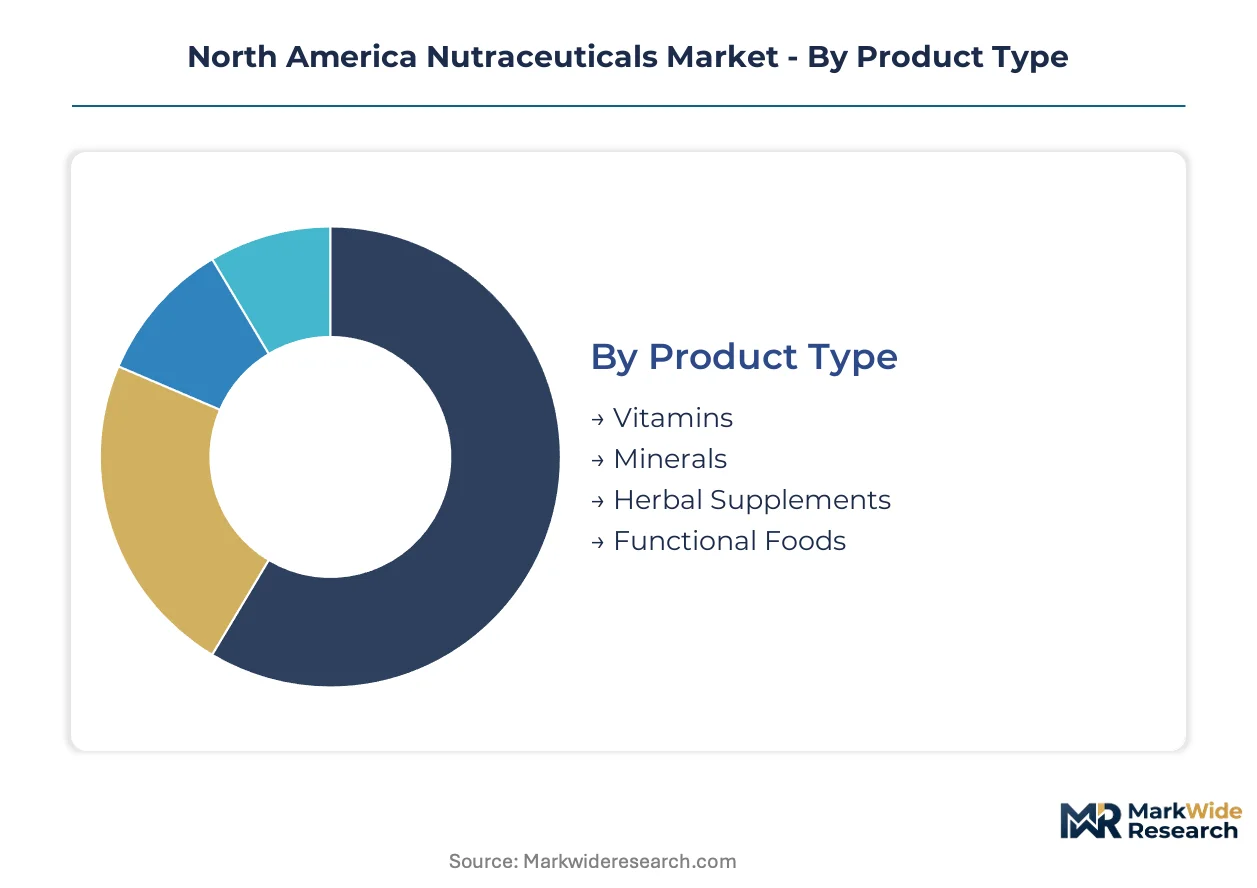
Regulatory fragmentation across the United States and Canada forces nutraceutical manufacturers to align product portfolios with distinct approval pathways. Each segment carries divergent compliance burdens that shape margin structures and market access timelines.
Product Type:
FDA's New Dietary Ingredient notifications apply selectively based on active compound novelty, while Health Canada's Natural Product Numbers govern all four subcategories with varying stringency.
- Functional Foods:Beverage and snack fortification commands premium supermarket positioning with 5-95% active-marker standardization. California and Ontario metro corridors cluster demand from chronic disease patients integrating these products with diagnostic monitoring programs.
- Herbal Supplements:Adaptogenic and nootropic botanicals including ashwagandha, rhodiola, and bacopa target stress modulation and cognitive support. Athletes in Toronto and Los Angeles demonstrate highest retention rates for subscription-based replenishment models.
- Vitamins:Synthetic fermentation-derived compounds from South Carolina facilities serve preventive health management across consumer segments.
- Minerals:Chelated and elemental forms support bone health and metabolic function in elderly populations.
Leading the category by volume: Functional Foods. Growing fastest: Herbal Supplements.
Distribution Channel:
Channel selection determines slotting fee exposure and customer acquisition economics, with digital platforms compressing marketing spend toward retention rather than retail placement.
- Pharmacies:CVS, Walgreens, and Shoppers Drug Mart chains now dedicate premium shelf space to sports nutrition and clinical-grade formulations. Dual-track FDA-Health Canada compliance filters smaller operators from this high-margin channel.
- Online Retailers:Direct-to-consumer platforms capture athletic consumers and chronic disease patients with subscription-based replenishment models. California-based operators face steepest FTC claim substantiation adaptation costs.
- Supermarkets:Beverage and snack fortification categories remain underpenetrated relative to supplement formats.
- Health Food Stores:Specialty retailers concentrate distribution for adaptogenic botanicals and precision-fermented active compounds.
Highest margin capture: Pharmacies. Steepest volume expansion: Online Retailers.
End User:
User segmentation aligns with physiological benefit positioning and chronic condition management integration across preventive and clinical applications.
- Chronic Disease Patients:Diabetes, cardiovascular, and cognitive decline management programs in Ontario and California integrate nutraceuticals with diagnostic monitoring. Successful prediabetes reimbursement pilots would unlock institutional procurement volumes.
- Athletes:Performance optimization demand concentrates in subscription replenishment models with highest retention rates in Toronto and Los Angeles metro areas.
- Health-conscious Consumers:Stress modulation and preventive wellness applications drive adaptogenic botanical adoption.
- Elderly:Bone health and metabolic support requirements sustain mineral and vitamin demand.
Largest addressable base: Health-conscious Consumers. Fastest penetration gains: Chronic Disease Patients.
Formulation:
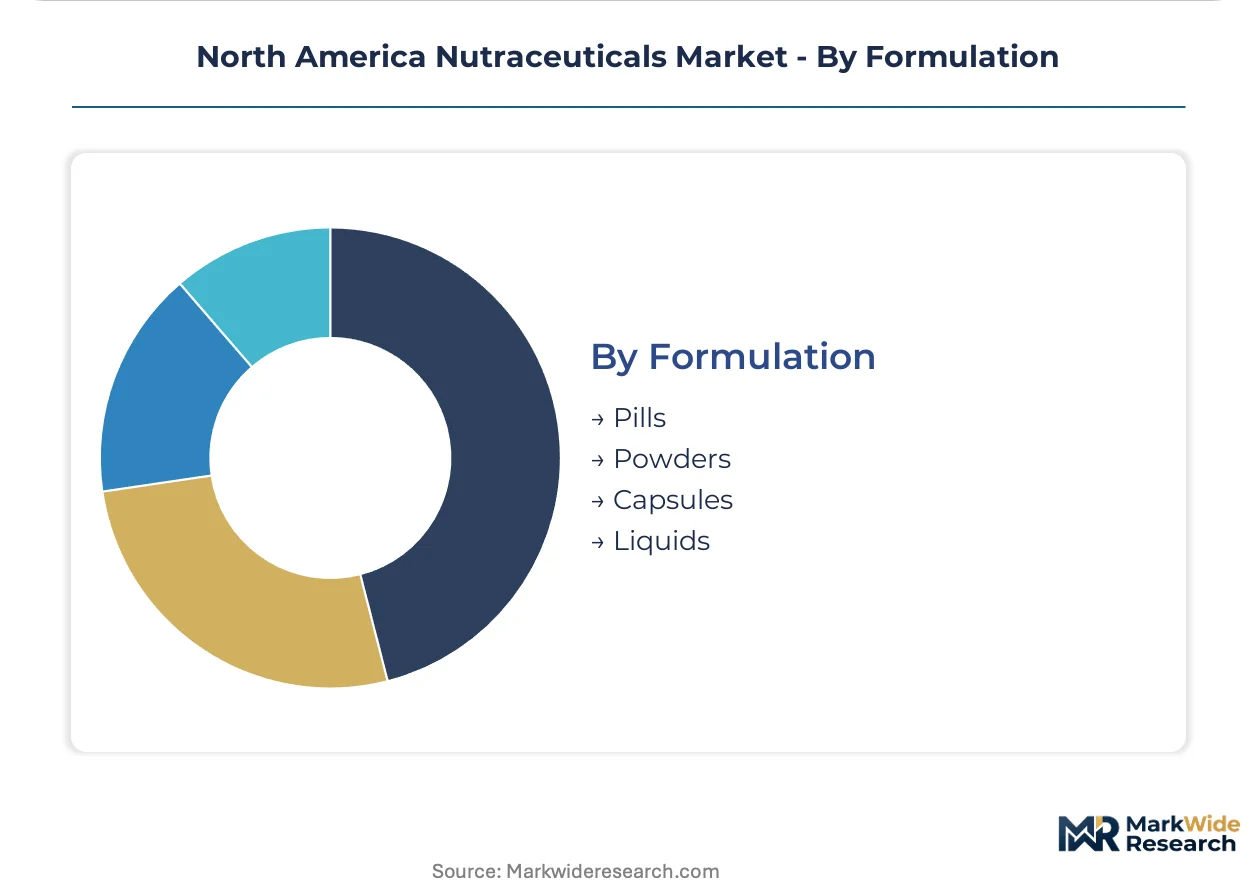
Format selection governs manufacturing complexity, stability requirements, and consumer compliance patterns across delivery mechanisms.
- Capsules:Gelatin and vegetable-based shells enable precise active-marker dosing with 5-95% concentration verification. Analytical chemistry capacity constraints delay batch release timelines for botanical extracts.
- Powders:Bulk formats serve sports nutrition applications with flexible dosing and flavor masking requirements.
- Pills:Compressed tablets dominate multivitamin and mineral categories with established manufacturing infrastructure.
- Liquids:Pediatric and geriatric compliance applications drive demand for alternative delivery formats.
Deepest manufacturing investment: Capsules. Format innovation frontier: Powders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian ashwagandha and Chinese rhodiola growing regions anchor raw-material flows into North American nutraceutical supply chains. Climate volatility across these source zones drives procurement hedging toward multi-continent sourcing. The region's $138.7 billion market base concentrates manufacturing and distribution infrastructure across three national territories.
United States
California metro corridors cluster demand from diabetes and cardiovascular management programs integrating nutraceuticals with diagnostic monitoring. FDA Current Good Manufacturing Practice regulations elevate compliance costs that filter smaller operators from CVS and Walgreens pharmacy shelf space. South Carolina fermentation facilities anchor synthetic vitamin production capacity serving national distribution networks.
Canada
Ontario healthcare experiments with nutraceutical reimbursement for prediabetes management, with Toronto metro areas showing highest subscription retention rates. Health Canada's Natural and Non-prescription Health Products Directorate mandates site licensing and product licensing for market entry, creating parallel compliance burdens to FDA pathways. Quebec precision-fermentation contract manufacturers adopt GMP bioreactor infrastructure for adaptogenic compound production.
Mexico
Northern border states concentrate maquiladora-adjacent contract manufacturing for US-market supplement packaging and formulation. COFEPRIS regulatory alignment with FDA standards facilitates cross-border supply chain integration for botanical extract finishing. Mexico City metro corridor serves as distribution hub for Central American market penetration by North American brands.
North America Nutraceuticals Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation facilities and extraction infrastructure multiply across South Carolina and Quebec. The vendor base stratifies into three tiers: multinational conglomerates controlling branded distribution, mid-cap specialists commanding precision-fermentation capabilities, and regional botanical extract suppliers. Strategic archetypes include grain-processing diversifiers leveraging agricultural infrastructure, synthetic biology platforms unifying pharmaceutical-grade discipline with botanical metabolite production, and direct-to-consumer operators facing FTC claim substantiation adaptation costs. M&A activity and vertical integration into captive supply chains represent the dominant competitive moves reshaping market structure.
Among diversified nutrition conglomerates, Nestlé S.A. and Abbott Laboratories occupy positions exemplifying branded finished-goods control through pharmacy and supermarket channels. Archer Daniels Midland Company anchors the agricultural-processing archetype, representing grain-based infrastructure leveraged for standardized extract supply security. Koninklijke DSM N.V. sits within the synthetic biology tier, exemplifying fermentation-derived vitamin capacity positioned for near-shoring advantages.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Abbott Laboratories |
| Herbalife Nutrition Ltd. |
| Amway Corp. |
| PepsiCo Inc. |
| General Mills, Inc. |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Cargill |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract manufacturers have consolidated South Carolina and Quebec fermentation capacity, translating capital discipline into premium pricing power for pharmaceutical-grade botanical extracts while squeezing margin buffers for unhedged raw-material buyers.
Pricing Analysis
Service bundling separates certified GMP-compliant production from unbundled commodity extraction, with FDA Current Good Manufacturing Practice adherence commanding substantial premiums over Health Canada-only licensed alternatives. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade active-marker concentrations reflects analytical verification costs and batch-release timeline differentials. Pricing pressure stems from climate-driven yield volatility in Indian ashwagandha and Chinese rhodiola harvests forcing multi-source hedging. Chronic disease patients through Ontario reimbursement pilots demonstrate lowest price sensitivity, while supermarket beverage fortification buyers face intense cost compression.
Supply Chain Analysis
Direct-to-consumer channels handle subscription replenishment demand from Toronto and Los Angeles metro athletic consumers, while pharmacy chains manage clinical-grade formulations for diabetes and cardiovascular management programs. Raw material flows concentrate in India, China, and domestic South Carolina fermentation facilities. Botanical extract production draws from drought-exposed Indian growing regions and rhodiola harvest zones in China and Siberia. Single-source vulnerability in adaptogenic raw materials threatens margin stability. Distribution runs through CVS, Walgreens, and Shoppers Drug Mart pharmacy networks alongside Amazon and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America nutraceuticals market functions as a cost-of-compliance story where FDA New Dietary Ingredient notification requirements and Health Canada site licensing erect barrier-to-entry moats favoring capitalized incumbents with dual-track regulatory infrastructure.
For Market Incumbents: Deploy precision-fermentation capacity expansion in South Carolina and Quebec to capture near-shoring advantages as Asian botanical supply volatility intensifies. Consolidate contract manufacturing relationships with pharmacy chains to defend shelf positioning against direct-to-consumer subscription entrants. Backward integration into captive ashwagandha and rhodiola cultivation hedges climate-driven raw material cost spikes. For New Entrants and Emerging Players: Launch via subscription-based replenishment models targeting athletic consumers in Toronto and Los Angeles metros where retention rates exceed pharmacy impulse purchase economics. Exploit underpenetrated supermarket beverage and snack fortification categories where premium positioning remains available. Pursue white-label manufacturing partnerships with established GMP facilities to bypass dual-track compliance capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap precision-fermentation specialists with Health Canada site licenses and existing FDA Master Files in South Carolina and Quebec. Long-term viability hinges on synthetic biology convergence with botanical metabolite production capability. Watch Ontario prediabetes reimbursement pilot outcomes as institutional procurement volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | South Carolina and Quebec GMP bioreactor infrastructure enables pharmaceutical-grade adaptogenic compound production at commercial scale. |
| Dual-Track Regulatory Compliance Investment | Simultaneous FDA and Health Canada licensing secures pharmacy shelf access across United States and Canadian markets. |
| Subscription-Based Direct-to-Consumer Launch | Toronto and Los Angeles metro athletic consumers demonstrate highest retention rates, compressing customer acquisition costs. |
| Backward Integration into Botanical Cultivation | Captive ashwagandha and rhodiola supply hedges climate-driven yield volatility from Indian and Chinese growing regions. |
| Functional Food Fortification Partnership | Supermarket beverage and snack categories offer premium positioning with deeper margin pools than pharmacy channels. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and retail audit data underwrites the qualitative findings in this study. Primary interviews with FDA regulatory affairs consultants, Health Canada site licensing specialists, CVS and Shoppers Drug Mart category buyers, South Carolina fermentation facility operations directors, and Ontario healthcare reimbursement policy analysts combined with secondary validation from FDA New Dietary Ingredient notifications, Health Canada Natural Product Numbers registry, and Nielsen retail tracking data. Bottom-up volume triangulation against top-down market sizing ensures consistency.
Comparable historical periods anchored the forecast window to pre-pandemic baseline demand patterns and post-regulatory-intensification growth trajectories. The analytical framework models product type, distribution channel, end user, and formulation segmentation dimensions across the projection horizon. CAGRs were derived from regression analysis against demographic health trends, regulatory enforcement intensity indices, and channel shift velocity parameters. Synthetic vitamin fermentation capacity utilization rates and botanical extract batch release timelines served as industry-specific forecast inputs.
Climate-driven crop failure, abrupt FDA enforcement action escalation, and Ontario reimbursement pilot cancellation are the dominant revision risks to base-case projections. Forecasts reflect assumptions regarding regulatory pathway stability and raw material supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Piracetam Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Eye Health Ingredients Market