
 Oxiracetam Market | 2026-2036
Oxiracetam Market Size, Share, and Industry Trends Forecast 2026-2036
Oxiracetam Market Analytics
Pharmaceutical-grade API purity tiers above 99.5% is collapsing the gap between research-chemical suppliers and GMP-certified manufacturers. CSPC leverages its vertical integration from bulk chemical synthesis to finished dosage forms. Haerbin Medisan anchors the northern China production corridor with specialized nootropic API capacity. North China Pharmaceutical Group competes on fermentation-derived process economics for racetam-class molecules.
Oxiracetam is a synthetic nootropic compound of the racetam family, characterized by a hydroxyl modification at the 4-position of the 2-oxopyrrolidine ring that enhances cholinergic neurotransmission and membrane fluidity. Manufacturers produce it through multi-step organic synthesis involving pyrrolidone alkylation followed by hydroxylation, with purity verification via HPLC and residual solvent testing per pharmacopeial standards. Tablet and capsule formulations dominate current revenue pools due to established bioequivalence data and patient compliance advantages, while powder segments attract compounding pharmacies and research institutions seeking dose flexibility. The cognitive enhancement application leads volume consumption, though Alzheimer's Disease represents the highest-margin clinical indication where regulatory approval unlocks reimbursement pathways.
China's NMPA classifies oxiracetam as a prescription psychotropic substance, requiring manufacturing licenses under GMP Annex 1 sterile guidelines and batch release documentation for domestic distribution. The EU REACH framework governs import registration for non-pharmaceutical chemical shipments, while FDA oversight through IND and NDA pathways shapes access to the United States clinical market. Stakeholders must monitor evolving scheduling decisions by national drug control agencies that could reclassify racetams from research chemicals to controlled substances, fundamentally altering distribution channel viability and end-user access models.
Market Dynamics
Pharmaceutical-grade purity requirements above 99.5% are consolidating API supply around GMP-certified manufacturers with validated hydroxylation processes, squeezing research-chemical intermediaries from downstream commercial channels.
Growth Catalysts
- Alzheimer's Disease reimbursement pathways:Regulatory approval for dementia indications unlocks prescription coverage in European markets, converting out-of-pocket nootropic demand into reimbursable clinical volume.
- East Asian contract manufacturing clusters:Shijiazhuang and Harbin production corridors capture European API procurement through REACH-registered bulk supply chains.
- Cholinergic mechanism validation:Accumulating clinical evidence for 4-hydroxy-2-oxopyrrolidine neurotransmission strengthens physician prescribing confidence in cognitive enhancement protocols.
Market Restraints
- Psychotropic scheduling friction:China's NMPA prescription classification imposes GMP Annex 1 sterile manufacturing licenses that exclude non-certified chemical suppliers from domestic distribution.
- Pyrolidone feedstock volatility:Petrochemical-derived pyrrolidone precursors expose synthesis economics to crude oil price fluctuations and refinery capacity constraints.
- Piracetam substitution pressure:Lower-cost unhydroxylated racetam alternatives compete for price-sensitive research and compounding segments without equivalent bioequivalence data requirements.
Strategic Opportunities
- Compounding pharmacy channel expansion:Powder formulation flexibility serves individualized dosing protocols in North American integrative medicine practices outside standard tablet supply chains.
- Fermentation-derived process economics:Biocatalytic hydroxylation routes under development promise to reduce organic solvent residuals and simplify pharmacopeial compliance documentation.
- India's CDMO infrastructure:Hyderabad and Visakhapatnam API parks offer alternative manufacturing geography with US FDA-inspected facilities for IND-enabling clinical supply.
Industry Challenges
- Residual solvent validation timelines:ICH Q3C guideline compliance for Class 2 solvents extends batch release documentation by 4-6 weeks, compressing working capital cycles.
- Stereoselective synthesis expertise scarcity:4(S)-hydroxy enantiomer purification requires specialized chiral chromatography capabilities concentrated in limited contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxiracetam Market |
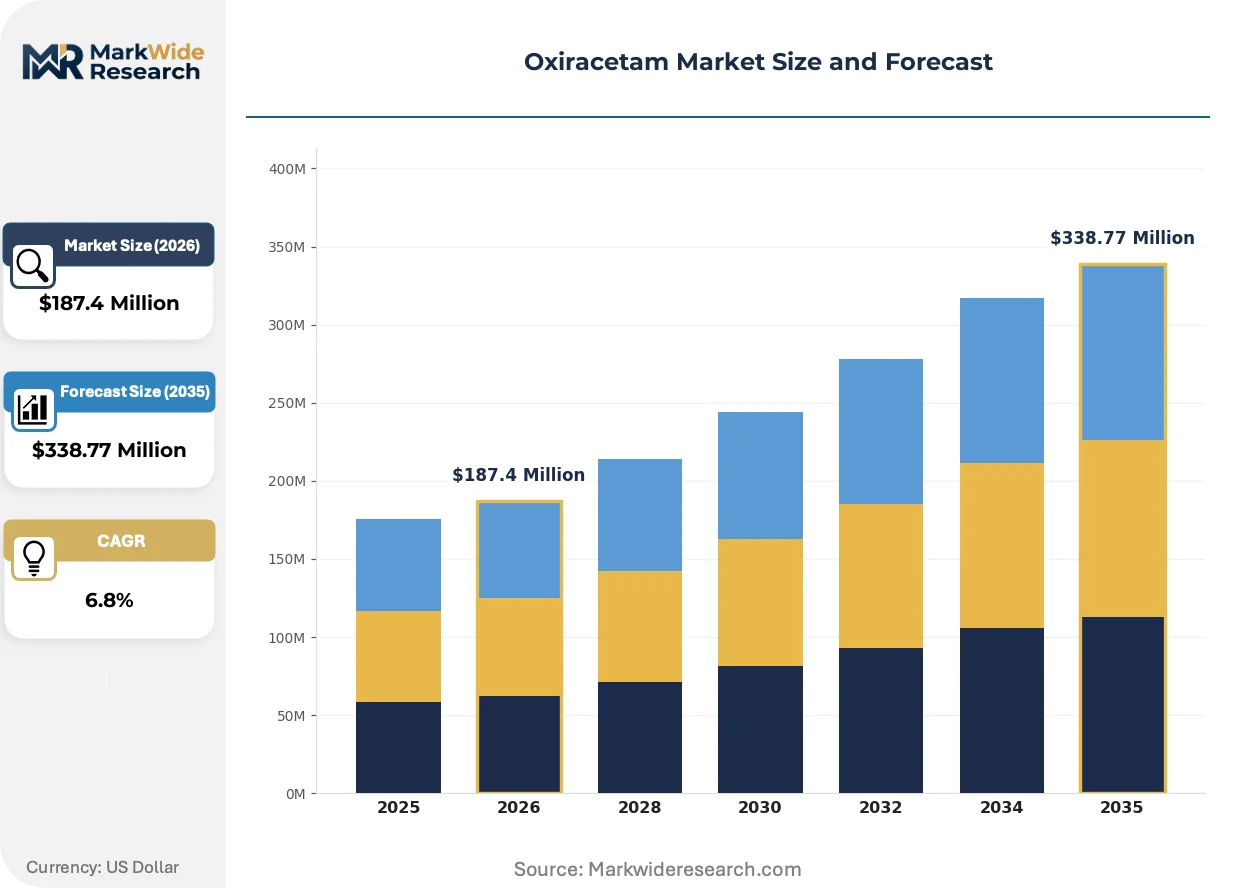
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powder, Liquid Application: Cognitive Enhancement, Alzheimer's Disease, ADHD, Mood Disorders End User: Pharmaceutical Companies, Research Institutions, Distributors, Healthcare Professionals Distribution Channel: Online Retail, Pharmacies, Hospitals, Wholesalers |
| Companies Covered | Haerbin Medisan, CSPC, North China Pharmaceutical Group, Guangdong Shixin Pharmaceutical, Ruiyang Pharmaceutical Co., Ltd, Langtian Pharmaceutical, Hunan Jianlang Pharmaceutical Co. Ltd, Shaanxi Laon Biotech Co., Ltd., Chongqing Fuan Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxiracetam Market Evolving Landscape
Continuous flow chemistry and biocatalytic hydroxylation are rewriting process economics for racetam-class molecules, while regulatory data integrity requirements reshape documentation workflows across GMP-certified facilities.
Continuous flow reactors are displacing batch synthesis for pyrrolidone alkylation steps, enabling real-time process analytical technology monitoring that reduces solvent consumption and accelerates impurity profile validation. European CDMOs with microreactor infrastructure capture high-purity API contracts from research institutions requiring documented batch consistency. This displacement is compressing capital recovery timelines for legacy stirred-tank investments while favoring modular manufacturing footprints.
REACH registration deadlines for non-pharmaceutical chemical shipments are forcing importers to consolidate supply relationships with full-data holders rather than nominal-only registrants. The European Chemicals Agency's substance evaluation workflow now targets racetam-class intermediates for extended toxicity dossier requirements. API traders serving European compounding pharmacies are responding by shifting procurement to manufacturers with complete Annex XV study packages.
Research institutions are unbundling bulk powder purchases from analytical service contracts, contracting third-party HPLC verification rather than accepting manufacturer certificates of analysis at face value. This disintermediation of quality assurance functions concentrates demand on testing laboratories with ISO 17025 accreditation for pharmacopeial methods. The pattern is most visible in North American academic procurement, where institutional review boards now mandate independent purity documentation for nootropic research protocols.
Oxiracetam Market Segmentation
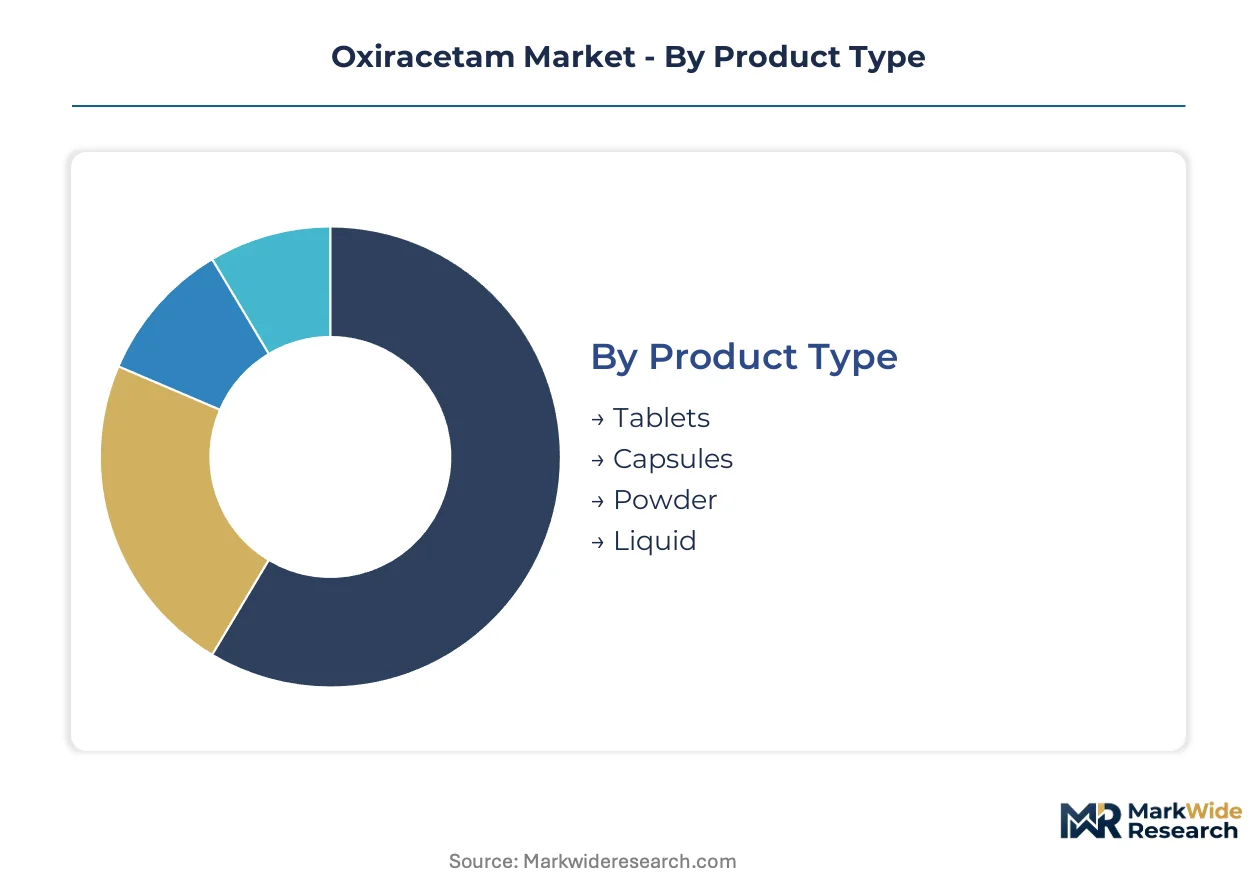
Segmentation in the oxiracetam market reveals divergent margin structures across formulation types and customer channels. Pharmaceutical-grade tablet and capsule formats command premium pricing through GMP certification requirements, while powder segments serve price-elastic research demand with minimal regulatory overhead.
Product Type:
Tablet formulations concentrate margin pools through established bioequivalence dossiers and prescription reimbursement pathways in European markets.
- Tablets:Compressed dosage forms with standardized potency specifications dominate clinical procurement. German and French hospital pharmacies drive volume through centralized tender processes that favor documented dissolution profiles.
- Capsules:Gelatin and HPMC shell formulations offer moisture protection for hygroscopic API. North American integrative medicine practices prefer capsules for compounding flexibility, though gelatin sourcing faces EFSA scrutiny over bovine-derived materials.
- Powder:Bulk API for research protocols and extemporaneous compounding.
- Liquid:Solution and suspension formats for pediatric and geriatric populations with swallowing difficulties.
Tablets hold installed capacity. Powder is rotating up the share rankings.
Application:
Alzheimer's Disease indications capture the steepest margin expansion trajectory through orphan drug designation pathways and specialized reimbursement codes.
- Alzheimer's Disease:Dementia-focused clinical protocols require documented cholinergic mechanism validation. EMA centralized procedures for racetam-class compounds in neurodegenerative indications attract sponsor investment from mid-cap European pharmaceutical developers.
- Cognitive Enhancement:Off-label nootropic use concentrates in East Asian markets with less restrictive prescription enforcement. South Korean and Japanese consumers access oxiracetam through cosmetic pharmacy channels that blur regulatory boundaries between drug and supplement classification.
- ADHD:Pediatric and adult attention deficit protocols compete with established stimulant therapies.
- Mood Disorders:Adjunctive use in depression and anxiety comorbidities lacks robust clinical evidence.
Alzheimer's Disease anchors premium pricing. Cognitive Enhancement is expanding most quickly in volume terms.
End User:
Research Institutions generate the highest per-kilogram pricing through small-batch procurement with expedited analytical documentation requirements.
- Pharmaceutical Companies:Integrated developers and CDMOs purchase bulk API for formulation development and commercial manufacturing. CSPC and North China Pharmaceutical Group serve this segment through long-term supply agreements with penalty clauses for batch failure.
- Research Institutions:Academic neuroscience laboratories and contract research organizations require COA-verified material for IND-enabling studies. ISO 17025-accredited third-party testing now substitutes for manufacturer certificates in North American procurement protocols.
- Distributors:Wholesale intermediaries serving compounding pharmacies and hospital procurement.
- Healthcare Professionals:Direct prescribing for cognitive enhancement in jurisdictions with permissive off-label practice.
Pharmaceutical Companies hold installed capacity. Research Institutions are climbing the fastest in revenue contribution.
Distribution Channel:
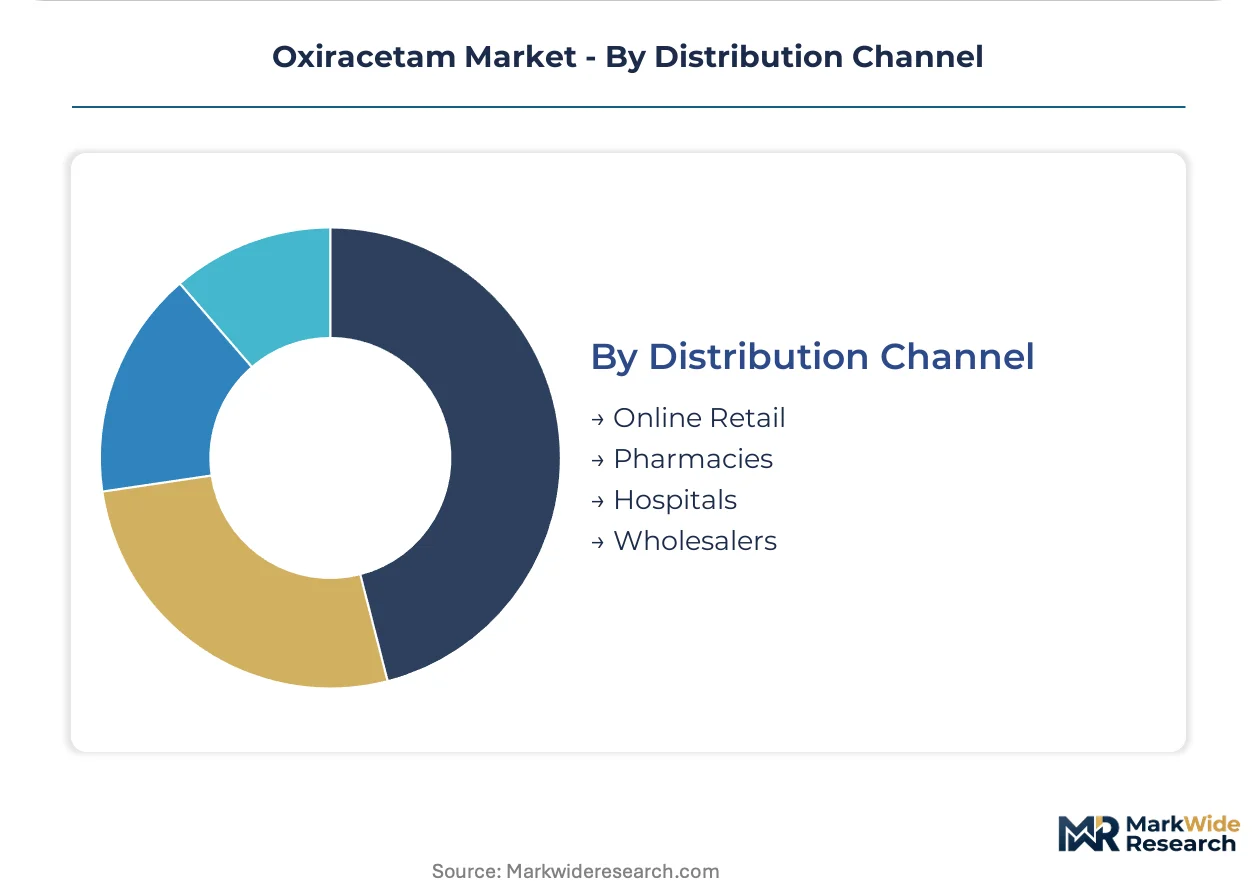
Hospital procurement concentrates volume through centralized purchasing organizations that negotiate multi-year API supply contracts.
- Hospitals:Inpatient and outpatient pharmacy departments operate under national formulary restrictions. China's NMPA prescription classification channels oxiracetam through tertiary hospital pharmacies with psychotropic substance licensing.
- Online Retail:Cross-border e-commerce platforms serve research chemical demand in regulatory gaps. ECHA REACH enforcement has eliminated nominal-only registrants from European direct-to-consumer shipments, consolidating supply to full-data holders.
- Pharmacies:Community and hospital outpatient dispensing with prescription verification.
- Wholesalers:Regional distribution networks for bulk inventory management and cold chain logistics.
Hospitals hold installed capacity. Online Retail is gaining share fastest despite regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis for racetam-class molecules clusters in East Asian manufacturing corridors where pyrrolidone feedstock access intersects with GMP-certified sterile processing capacity. REACH-registered European importers source predominantly from Shijiazhuang and Harbin production zones.
China
Shijiazhuang and Harbin anchor bulk API output for European export markets. NMPA psychotropic classification mandates GMP Annex 1 sterile licenses that filter out non-certified chemical suppliers. CSPC and North China Pharmaceutical Group dominate northern corridor capacity with validated hydroxylation processes.
Germany
Hospital pharmacy procurement through centralized tender processes drives tablet and capsule volume. EMA centralized procedures for dementia indications attract mid-cap developers pursuing orphan drug designation. REACH enforcement has eliminated nominal-only registrants from API import channels.
United States
Research institutions and compounding pharmacies generate premium pricing for COA-verified powder. FDA IND and NDA pathways shape clinical market access, with IRB-mandated independent HPLC verification now standard for nootropic research protocols. ISO 17025-accredited testing laboratories capture disintermediated quality assurance demand.
India
Hyderabad and Visakhapatnam API parks offer US FDA-inspected CDMO alternatives to Chinese supply. CDSCO oversight aligns with ICH Q3C residual solvent guidelines. Fermentation-derived biocatalytic routes under development target reduced organic solvent residuals for pharmacopeial compliance.
South Korea
Cosmetic pharmacy channels blur regulatory boundaries between drug and supplement classification for cognitive enhancement demand. MFDS scheduling decisions influence reimbursement pathway viability. Japanese and domestic consumers access oxiracetam through permissive off-label distribution networks.
Oxiracetam Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the oxiracetam API segment. GMP-certified manufacturers with validated chiral chromatography capabilities command premium pricing for pharmaceutical-grade purity above 99.5%, while research-chemical intermediaries compete on volume for powder segments with minimal regulatory overhead. The market structure separates into three strategic archetypes: vertically integrated pharmaceutical conglomerates, specialized nootropic API specialists, and fermentation-focused process innovators. Competitive moves concentrate on capacity expansion in East Asian manufacturing corridors and REACH registration consolidation for European market access.
Among Chinese pharmaceutical conglomerates, CSPC represents the vertically integrated archetype with captive synthesis-to-dosage-form capabilities, while Haerbin Medisan anchors the northern China production corridor as a specialized nootropic API manufacturer. North China Pharmaceutical Group exemplifies fermentation-derived process economics for racetam-class molecules. These three companies collectively illustrate the geographic and technological concentration shaping supply-side dynamics.
| Leading Market Players |
|---|
| Haerbin Medisan |
| CSPC |
| North China Pharmaceutical Group |
| Guangdong Shixin Pharmaceutical |
| Ruiyang Pharmaceutical Co., Ltd |
| Langtian Pharmaceutical |
| Hunan Jianlang Pharmaceutical Co. Ltd |
| Shaanxi Laon Biotech Co., Ltd. |
| Chongqing Fuan Pharmaceutical |
| Others |
Value Network & Pricing Analysis
Capacity utilization above 85% in Shijiazhuang and Harbin GMP-certified facilities is compressing marginal cost curves for pharmaceutical-grade oxiracetam API, elevating price floors for research-chemical intermediaries while consolidating procurement power among REACH-registered European importers. This scale concentration simultaneously tightens batch-release documentation timelines and widens purity-premium spreads between 99.5% pharmaceutical tiers and unverified powder segments.
Pricing Analysis
NMPA psychotropic classification dictates the pricing tier structure across domestic Chinese distribution, with GMP Annex 1 sterile manufacturing licenses filtering non-certified suppliers from hospital pharmacy channels. Three-tier pricing structure across pharmaceutical-grade, compounding-grade, and research-chemical levels separates certified API with validated hydroxylation from nominal-registrant powder. Cost compression in research-chemical tiers is intensifying because REACH enforcement eliminated nominal-only registrants from European direct-to-consumer shipments. Compounding pharmacies in North America exhibit highest price sensitivity, while Alzheimer's Disease clinical sponsors demonstrate lowest sensitivity due to orphan drug reimbursement pathways.
Supply Chain Analysis
Pyrrolidone feedstock availability from Shandong petrochemical corridors underwrites synthesis economics for northern China API manufacturers, with hydroxylation step validation representing the critical chokepoint for pharmaceutical-grade output. Geographic supply concentrates in China, India, and Germany, with Hyderabad and Visakhapatnam offering US FDA-inspected CDMO alternatives. Raw material dependencies span petrochemical-derived pyrrolidone, chiral chromatography resins, and pharmacopeial-grade solvents. Single-source vulnerability in 4(S)-hydroxy enantiomer purification capabilities concentrates risk among limited contract manufacturing organizations. Distribution runs through hospital procurement organizations, REACH-registered bulk importers, and ISO 17025-accredited testing laboratories serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in Alzheimer's Disease reimbursement pathways is accelerating clinical sponsor investment, with EMA centralized procedures for racetam-class compounds converting out-of-pocket nootropic demand into reimbursable prescription volume across European markets.
For Market Incumbents: Compound GMP certification advantages by expanding chiral chromatography capacity in Harbin and Shijiazhuang corridors before biocatalytic hydroxylation routes mature. Defend against piracetam substitution pressure through bioequivalence dossier investment for tablet formulations. Prioritize REACH Annex XV study package completion to capture nominal-registrant volume exiting European channels. For New Entrants and Emerging Players: CDSCO fast-track approval for US FDA-inspected Hyderabad facilities offers lowest-barrier entry into IND-enabling clinical supply chains. Target North American compounding pharmacy powder demand with ISO 17025-accredited third-party testing partnerships. Penetrate through research institution procurement protocols mandating independent HPLC verification rather than manufacturer certificates of analysis. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated API-to-dosage-form manufacturers with validated sterile processing and long-term hospital supply agreements. Five-to-ten year viability favors fermentation-derived process innovators reducing organic solvent residuals. Monitor biocatalytic hydroxylation route maturation as inflection signal for organic synthesis asset obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Annex 1 Sterile License Expansion | NMPA compliance unlocks domestic Chinese hospital pharmacy distribution channels for psychotropic-classified API. |
| REACH Full-Data Registration Completion | ECHA substance evaluation workflow consolidation eliminates nominal-only registrants from European import channels. |
| Biocatalytic Hydroxylation Route Development | Fermentation-derived processes reduce ICH Q3C Class 2 solvent residuals and accelerate batch release timelines. |
| ISO 17025 Testing Laboratory Partnership | Independent HPLC verification captures disintermediated quality assurance demand from North American research institutions. |
| EMA Centralized Procedure Sponsorship | Orphan drug designation pathways for Alzheimer's Disease indications convert out-of-pocket demand into reimbursable clinical volume. |
Research Methodology
Desk research of NMPA psychotropic classification guidelines, EMA centralized procedure documentation, and REACH Annex XV study requirements preceded structured interviews with GMP-certified API manufacturing executives, regulatory affairs specialists at CDMOs, hospital pharmacy procurement managers, and compounding pharmacy operators. Secondary validation drew from FDA IND and NDA pathway filings, ECHA substance evaluation records, and ICH Q3C residual solvent guideline updates. Bottom-up segmentation modeling triangulated against top-down macro pharmaceutical API trade flow analysis.
Variance decomposition across product type, application indication, end-user archetype, and distribution channel dimensions shaped volume and value outputs over the projection horizon. CAGRs were derived from pharmaceutical-grade purity tier penetration curves, REACH registration consolidation timelines, and Alzheimer's Disease reimbursement pathway adoption rates. Forecast inputs incorporated pyrrolidone feedstock price elasticity, chiral chromatography capacity constraints, and biocatalytic hydroxylation route development milestones.
Underlying assumptions cover NMPA psychotropic classification stability, REACH enforcement continuity, and EMA centralized procedure throughput capacity, with deviation risk concentrated in national drug control agency scheduling decisions that could reclassify racetams from research chemicals to controlled substances. Practitioners should keep alternative scenarios live as regulatory scheduling frameworks and biocatalytic process economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Europe Nutricosmetics Market