
 Phosphatidylserine Market | 2026-2036
Phosphatidylserine Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphatidylserine Market Outlook
Specialty ingredient distribution is reshaping how phosphatidylserine reaches nutraceutical compounders and finished goods manufacturers. Lonza Group leverages its global life sciences infrastructure to sustain supply chain reliability across multiple continents. Lipoid GmbH anchors European production capacity with advanced phospholipid extraction capabilities. Chemi Nutra competes through specialized phosphatidylserine formulations targeting premium cognitive health applications.
Phosphatidylserine is a phospholipid comprising glycerol, two fatty acid chains, and a serine head group, typically extracted from soy or sunflower lecithin through enzymatic conversion or solvent fractionation, functioning as a critical cell membrane component with demonstrated cortisol-modulating and cognitive support properties. The powder segment dominates bulk ingredient procurement due to manufacturing flexibility and lower unit economics for large-scale formulators. Softgels command premium positioning among elderly end users seeking convenient dosing formats, while sports nutrition applications represent the fastest-growing demand channel as athletes adopt evidence-based nootropic supplementation.
EFSA novel food opinions and FDA GRAS self-affirmation pathways create divergent compliance burdens for suppliers seeking transatlantic market access. REACH registration requirements for synthetic phosphatidylserine intermediates add cost layers for European manufacturers. Japan's FOSHU approval framework and Health Canada's Natural Health Product regulations further fragment regulatory entry points. Stakeholders must monitor evolving substantiation standards for cognitive health claims across jurisdictions to anticipate reformulation requirements and labeling adjustments.
Market Dynamics
Regulatory divergence between FDA GRAS self-affirmation and EFSA novel food pathways is fragmenting market entry strategies and forcing suppliers to maintain parallel compliance infrastructures.
Growth Catalysts
- Sports nutrition channel expansion:Athletes in North America and Western Europe are adopting phosphatidylserine for cortisol modulation during training cycles, creating pull-through from performance-focused dietary supplement brands.
- EFSA novel food opinions:Clarified safety thresholds for sunflower-derived phosphatidylserine have reduced entry uncertainty for European suppliers seeking novel food authorization.
- Enzymatic conversion technology:Advanced biocatalytic processes are lowering extraction costs and improving fatty acid profile consistency compared to traditional solvent fractionation methods.
Market Restraints
- Soy lecithin input volatility:Agricultural commodity price swings for non-GMO soybeans compress margin predictability for legacy extraction operations.
- German production concentration:Lipoid GmbH's dominance in European phospholipid capacity creates single-source vulnerability for compounders requiring uninterrupted bulk supply.
- Synthetic phosphatidylserine intermediates:REACH registration requirements for petrochemical-derived precursors add compliance layers that natural-extraction competitors avoid.
Strategic Opportunities
- Japan FOSHU approval pathway:Cognitive health claims backed by clinical substantiation could unlock premium positioning in Asia-Pacific's most regulated functional food market.
- Pediatric formulation development:Underexplored applications in attention support for school-age children represent whitespace beyond current elderly-focused positioning.
- Direct-to-practitioner distribution:Functional medicine clinicians seeking evidence-backed interventions are bypassing traditional retail channels for practitioner-exclusive SKUs.
Industry Challenges
- Clinical substantiation expertise:Shortage of regulatory scientists capable of structuring EFSA-compliant novel food dossiers delays market entry timelines.
- Cross-jurisdictional labeling reconciliation:Divergent cognitive health claim permissibility between FDA, EFSA, and Health Canada forces SKU proliferation or lowest-common-denominator positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphatidylserine Market |
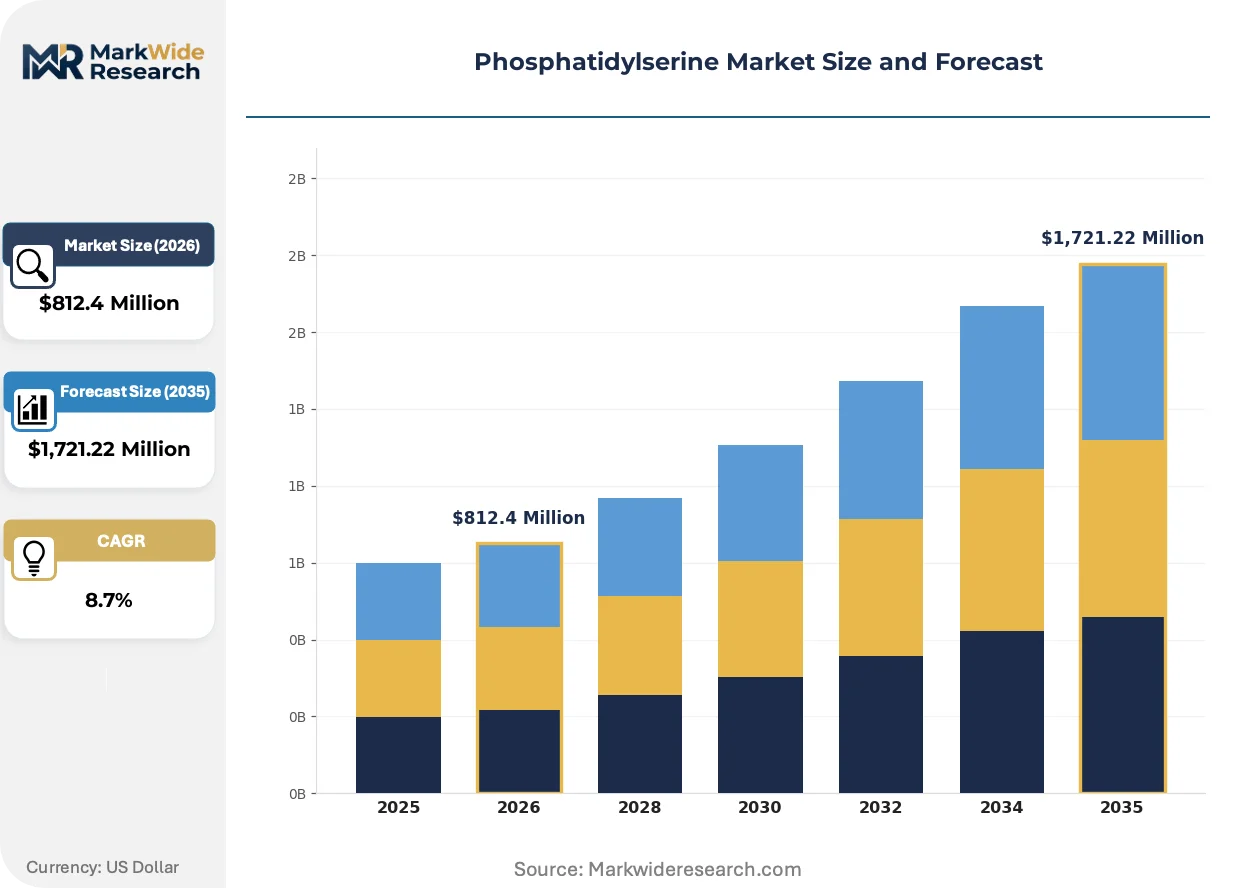
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,721.22 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Tablets, Softgels Application: Dietary Supplements, Functional Foods, Sports Nutrition, Cognitive Health Source Type: Soy-Based, Sunflower-Based, Synthetic, Others End User: Health Conscious Consumers, Athletes, Elderly, Healthcare Professionals |
| Companies Covered | Lonza Group, Lipoid GmbH, Chemi Nutra, Novastell, Lipogen Products Ltd, Enzymotec Ltd, Doosan Corporation, Nagase ChemteX Corporation, Bontac Bio-engineering Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphatidylserine Market Strategic Shifts
Formulation science and regulatory science are converging to reshape how phosphatidylserine reaches end users, with extraction methods and delivery formats undergoing simultaneous transformation.
Sunflower-derived phosphatidylserine is displacing soy-based alternatives in premium positioning due to allergen labeling advantages and non-GMO verification simplicity. European formulators are adopting sunflower sources at accelerated pace to preempt EFSA scrutiny of phytoestrogen content in soy extracts. The technology is migrating from specialty cognitive health applications toward broader sports nutrition and stress management categories as fatty acid profile standardization improves.
EFSA's evolving novel food opinion framework is compressing approval timelines for well-substantiated submissions while raising evidentiary bars for mechanistic claims. Manufacturers are pre-submission consulting with EFSA's Novel Food Task Force to avoid iterative resubmission cycles. Small and mid-sized suppliers without dedicated regulatory affairs capacity are outsourcing dossier preparation to specialized CROs, fragmenting competitive advantage toward capitalized players.
Compounders are consolidating supplier relationships around vertically integrated phospholipid specialists capable of certifiable traceability from raw material to finished powder. Bulk buyers are replacing spot-market purchasing with multi-year supply agreements incorporating quality consistency clauses. This consolidation is most visible in Germany and the Netherlands, where large-scale softgel manufacturers are locking in sunflower lecithin supply chains ahead of anticipated EFSA novel food queue backlogs.
Phosphatidylserine Market Segmentation
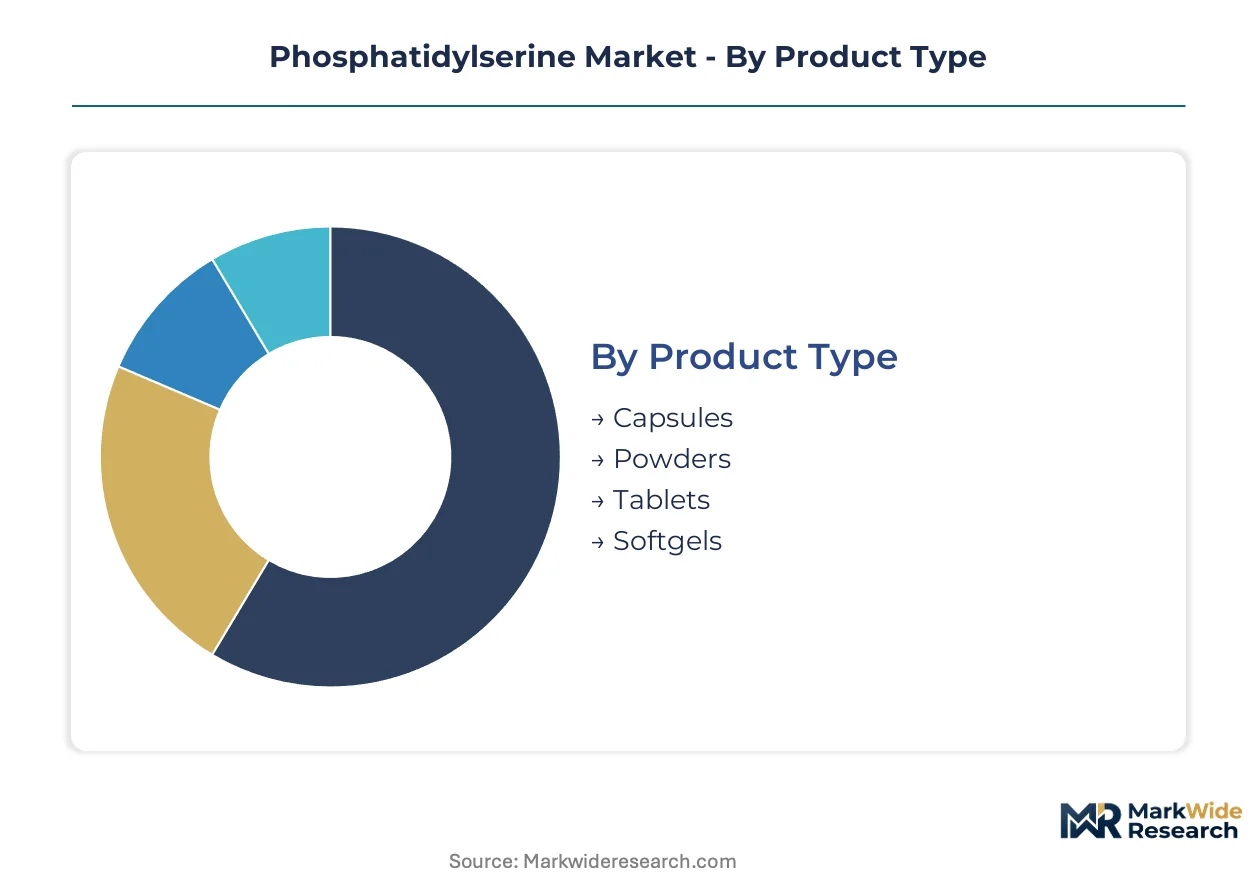
Phosphatidylserine's commercial structure fragments across four critical dimensions that determine pricing power, regulatory pathway complexity, and customer acquisition costs. Each segmentation axis reveals distinct margin profiles and competitive moats that suppliers must navigate strategically.
Product Type:
Use-case spectrum spans from bulk manufacturing inputs to finished consumer formats, with each tier demanding different technical specifications and distribution infrastructure.
- Powders:Unformulated bulk phosphatidylserine offers compounders maximum flexibility in dosage customization and co-formulation with other nootropics. Demand concentrates among German and Dutch contract manufacturers serving pan-European softgel producers seeking to lock in multi-year supply agreements with quality consistency clauses.
- Softgels:Pre-dosed gelatin capsules command premium positioning through convenience and oxidation protection for elderly end users prioritizing ease of administration. North American direct-to-consumer brands are pulling volume toward this format as subscription models displace retail pharmacy distribution.
- Capsules:Hard-shell vegetable capsules serve mid-tier positioning for health-conscious consumers seeking non-gelatin alternatives without softgel price premiums.
- Tablets:Compressed formulations occupy economy positioning where cost-per-dose sensitivity outweighs bioavailability optimization.
The dominant share belongs to powders, while softgels are closing the gap fastest.
Application:
Customer type determines formulation sophistication, with clinical substantiation requirements escalating across the value chain from general wellness to condition-specific positioning.
- Dietary Supplements:Capsule and softgel finished goods dominate shelf space in US health food retailers and European pharmacies, with brands competing on EFSA-compliant label claims and FDA GRAS self-affirmation documentation.
- Cognitive Health:Condition-specific formulations targeting memory support and cortisol modulation carry the steepest premium multiples, with clinical trial investment separating premium positioning from commodity botanical competitors.
- Sports Nutrition:Athletes in North America and Western Europe are adopting phosphatidylserine for training-cycle stress management, with performance-focused brands building pull-through via influencer partnerships and team sponsorships.
- Functional Foods:Beverage and bar fortification remains nascent due to phospholipid stability challenges during thermal processing and limited water solubility without emulsification systems.
Cognitive health commands the highest margin tier, yet sports nutrition is expanding most quickly as athlete adoption accelerates.
Source Type:
Supply concentration and regulatory familiarity vary dramatically by raw material origin, with natural extraction facing novel food scrutiny that synthetic alternatives bypass.
- Sunflower-Based:Non-GMO verification simplicity and allergen labeling advantages are accelerating displacement of soy-derived alternatives in European premium positioning. Lipoid GmbH's advanced phospholipid extraction capabilities anchor German production leadership.
- Soy-Based:Legacy extraction infrastructure and established supply chains maintain cost competitiveness, though EFSA scrutiny of phytoestrogen content and agricultural commodity price volatility compress margin predictability.
- Synthetic:Petrochemical-derived precursors avoid agricultural input volatility but trigger REACH registration requirements that natural competitors circumvent.
- Others:Bovine and marine sources occupy niche kosher and halal certification segments with limited scale.
Sunflower-based sources are gaining share fastest, while soy-based retains volume leadership through legacy infrastructure.
End User:
Volume scale and price sensitivity diverge sharply across consumer segments, with professional channel intermediation creating distinct margin structures.
- Elderly:Convenience-driven softgel preference and established supplement adherence patterns support premium pricing, with Medicare-eligible demographics in the US and aging European populations driving core demand.
- Health Conscious Consumers:Mid-tier powder and capsule purchasers research ingredient sourcing and third-party testing certifications before brand commitment.
- Athletes:Evidence-based purchasing decisions favor brands with published cortisol modulation studies, with collegiate and professional sports programs creating institutional procurement channels.
- Healthcare Professionals:Functional medicine clinicians bypass retail markup through practitioner-exclusive SKUs, requiring clinical dossiers that smaller suppliers cannot support.
Elderly consumers anchor volume, while healthcare professional channels are climbing the fastest as clinical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where Lipoid GmbH commands supply chain leverage, while US formulators absorb premium freight costs for EFSA-compliant sunflower-derived inputs. This asymmetry shapes procurement strategies across Atlantic markets.
United States
Sports nutrition brands and cognitive health formulators drive demand through direct-to-consumer subscription models. FDA GRAS self-affirmation pathways require parallel documentation infrastructure for transatlantic suppliers. Greater Boston and San Diego clusters host contract research organizations structuring clinical substantiation dossiers for cortisol modulation claims.
Germany
Lipoid GmbH anchors European phospholipid extraction capacity with advanced enzymatic conversion capabilities. EFSA novel food opinions for sunflower-derived phosphatidylserine streamline regulatory entry for domestic compounders. The Rhine-Main manufacturing corridor concentrates softgel production for pan-European distribution.
Japan
Aging demographics and established supplement adherence patterns support premium softgel positioning. METI oversees FOSHU approval frameworks for cognitive health functional foods. Tokyo-Osaka corridor houses importers navigating bilingual label reconciliation between domestic and export specifications.
China
Domestic enzymatic conversion technology development targets cost parity with European extraction methods. NMPA registration requirements for imported novel food ingredients create compliance barriers for foreign suppliers. Yangtze River Delta contract manufacturers serve re-export markets with blended phospholipid formulations.
Canada
Natural Health Product regulations demand distinct substantiation standards from US GRAS pathways. Health Canada licensing requirements compress margin structures for cross-border brands. Vancouver and Toronto clusters specialize in practitioner-exclusive distribution bypassing retail markup.
Phosphatidylserine Market Competitive Environment
Vertically integrated phospholipid specialists and regional extraction technology providers split the market between supply security and cost optimization. European production gravity favors legacy solvent fractionation operations with established EFSA dossier expertise. Three archetypes dominate: integrated life sciences conglomerates with captive phospholipid divisions, dedicated phospholipid extraction specialists with novel food regulatory capacity, and Asian enzymatic technology developers. Competitive moves concentrate on multi-year supply agreement lock-ins and backward integration into sunflower lecithin sourcing.
Among integrated life sciences conglomerates, Lonza Group exemplifies supply chain reliability across multiple continents through diversified manufacturing infrastructure. Lipoid GmbH anchors the dedicated specialist tier with German production leadership and regulatory familiarity with EFSA novel food opinions. Chemi Nutra occupies premium formulation positioning through specialized cognitive health applications. These three represent the dominant competitive anchors shaping procurement consolidation patterns among bulk compounders.
| Leading Market Players |
|---|
| Lonza Group |
| Lipoid GmbH |
| Chemi Nutra |
| Novastell |
| Lipogen Products Ltd |
| Enzymotec Ltd |
| Doosan Corporation |
| Nagase ChemteX Corporation |
| Bontac Bio-engineering Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European enzymatic conversion facilities is compressing lead times for sunflower-derived phosphatidylserine and elevating spot-market premiums above contract baselines. German compounders are absorbing freight arbitrage costs to secure EFSA-compliant inputs ahead of novel food queue backlogs, while North American buyers face steeper landed costs for traceable supply.
Pricing Analysis
The customization-premium spread separates bulk powder procurement from finished softgel positioning by a factor driven by certification grade and after-sales clinical dossier support. Three-tier pricing structure across premium, standard, and economy levels stratifies by fatty acid profile consistency and third-party testing depth. Cost compression in standard-grade soy-derived tiers is intensifying because agricultural commodity volatility compresses margin predictability for legacy extraction operations. Healthcare professional channels exhibit least price sensitivity due to reimbursement pass-through mechanics, while sports nutrition direct-to-consumer brands absorb highest sensitivity as subscription models displace retail pharmacy markups.
Supply Chain Analysis
Upstream sunflower lecithin sourcing draws from Ukraine, Argentina, and Black Sea corridor crushing operations with varying non-GMO verification infrastructure. Phospholipid extraction depends on enzymatic conversion catalysts and solvent fractionation equipment with divergent capital intensity. Single-source vulnerability concentrates in Lipoid GmbH's German production leadership, where any capacity interruption would cascade through pan-European softgel manufacturers. Distribution runs through vertically integrated phospholipid specialists offering certifiable traceability rather than spot-market commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphatidylserine procurement is shifting toward service-attach models where clinical substantiation consulting and regulatory dossier preparation generate recurring revenue expanding faster than bulk ingredient volumes. Manufacturers bundling EFSA novel food navigation with supply agreements are capturing margin premiums beyond commodity extraction economics.
For Market Incumbents: Entrench supply security through backward integration into sunflower lecithin crushing capacity in Black Sea sourcing regions, preempting input cost volatility that synthetic competitors circumvent. Deepen regulatory affairs infrastructure to compress EFSA novel food approval timelines, defending against emerging Asian enzymatic technology developers with cost-parity ambitions. For New Entrants and Emerging Players: Establish a beachhead in pediatric cognitive health formulations, an underexplored whitespace beyond current elderly-focused positioning where clinical trial investment barriers remain lower. Target practitioner-exclusive distribution channels with evidence-backed attention support SKUs, leveraging functional medicine clinician demand for bypassing retail markup. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated phospholipid specialists with captive novel food regulatory capacity, where multi-year supply agreements incorporate quality consistency clauses. Acquisition candidates with EFSA dossier expertise and German production assets offer superior long-term viability over spot-market traders. Watch for sunflower lecithin supply agreement lock-ins as inflection signal for pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sunflower Lecithin | Captures margin from Ukrainian and Argentine crushing operations while securing non-GMO verification traceability. |
| EFSA Novel Food Dossier Investment | Compresses approval timelines for sunflower-derived phosphatidylserine through pre-submission Task Force consultation. |
| Multi-Year Supply Agreement Lock-Ins | Replaces spot-market purchasing with quality consistency clauses among Dutch and German softgel manufacturers. |
| Pediatric Formulation Development | Unlocks whitespace in attention support for school-age children beyond elderly cognitive health saturation. |
| Practitioner-Exclusive SKU Launch | Bypasses retail markup through functional medicine clinician channels requiring clinical dossier bundling. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EFSA novel food opinion databases, FDA GRAS notification filings, and European customs trade data for phospholipid imports. Primary interviews engaged phospholipid extraction plant managers, regulatory affairs leads at nutraceutical compounders, procurement directors at German softgel manufacturers, and novel food dossier specialists at contract research organizations. Secondary validation incorporated Lipoid GmbH technical disclosures, REACH registration records for synthetic intermediates, and Health Canada Natural Health Product licensing data. Bottom-up demand modeling from end-use consumption patterns triangulates against top-down supply capacity assessments across enzymatic conversion facilities.
Forecast inputs incorporate product type segmentation across powders, softgels, capsules, and tablets; application dimensions spanning dietary supplements, cognitive health, sports nutrition, and functional foods; source type stratification by sunflower, soy, and synthetic origins; and end-user categories from elderly consumers to healthcare professionals. CAGRs derive from regression analysis of historical price-volume relationships and elasticity assumptions across the projection horizon. Industry-specific inputs include EFSA novel food approval queue velocity and sunflower lecithin agricultural yield variance.
Sensitivities concentrate around EFSA evidentiary standard elevation, sunflower crop yield disruption in Black Sea sourcing regions, and synthetic phosphatidylserine cost parity achievement through enzymatic technology transfer. Cross-checking against European phospholipid trade flow data and FOSHU approval timelines in Japan is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Tetrahydropalmatine Market