
 Coenzyme Q10 Market | 2026-2036
Coenzyme Q10 Market Size, Share, and Industry Trends Forecast 2026-2036
Coenzyme Q10 Market Analysis
Buyer concentration in the Coenzyme Q10 market is consolidating around large nutraceutical contract manufacturers and direct-to-consumer wellness brands. Kaneka Corporation dominates pharmaceutical-grade ubiquinol production through proprietary yeast fermentation technology. DSM Firmenich AG leverages its integrated nutrition platform to supply CoQ10 across human and animal health divisions. Pharma Nord A/S anchors European demand through its documented bioavailability research and pharmacy channel control.
Coenzyme Q10 is a lipid-soluble benzoquinone compound synthesized endogenously in human mitochondria, with commercial production relying on microbial fermentation or chemical synthesis to yield 98-99% purity ubiquinone for dietary supplements and pharmaceutical applications. Softgels occupy the dominant product type position due to superior fat-soluble nutrient delivery, while water-soluble formulations represent the fastest-growing segment as manufacturers address bioavailability limitations for aging populations. Nutraceutical companies constitute the most concentrated end-user pool, with direct procurement volumes expanding faster than retail consumer fragmentation across online stores and nutrition shops.
The FDA's Dietary Supplement Health and Education Act framework governs CoQ10 marketing claims and New Dietary Ingredient status in the United States, while EFSA evaluates health claim substantiation for European market access. Japan's Ministry of Health, Labour and Welfare maintains quasi-drug classification pathways that differentiate Kaneka's ubiquinol from standard supplement-grade material. Stakeholders must monitor evolving pharmacovigilance requirements for antioxidant ingredients and assess fermentation capacity expansion against synthetic route cost competitiveness.
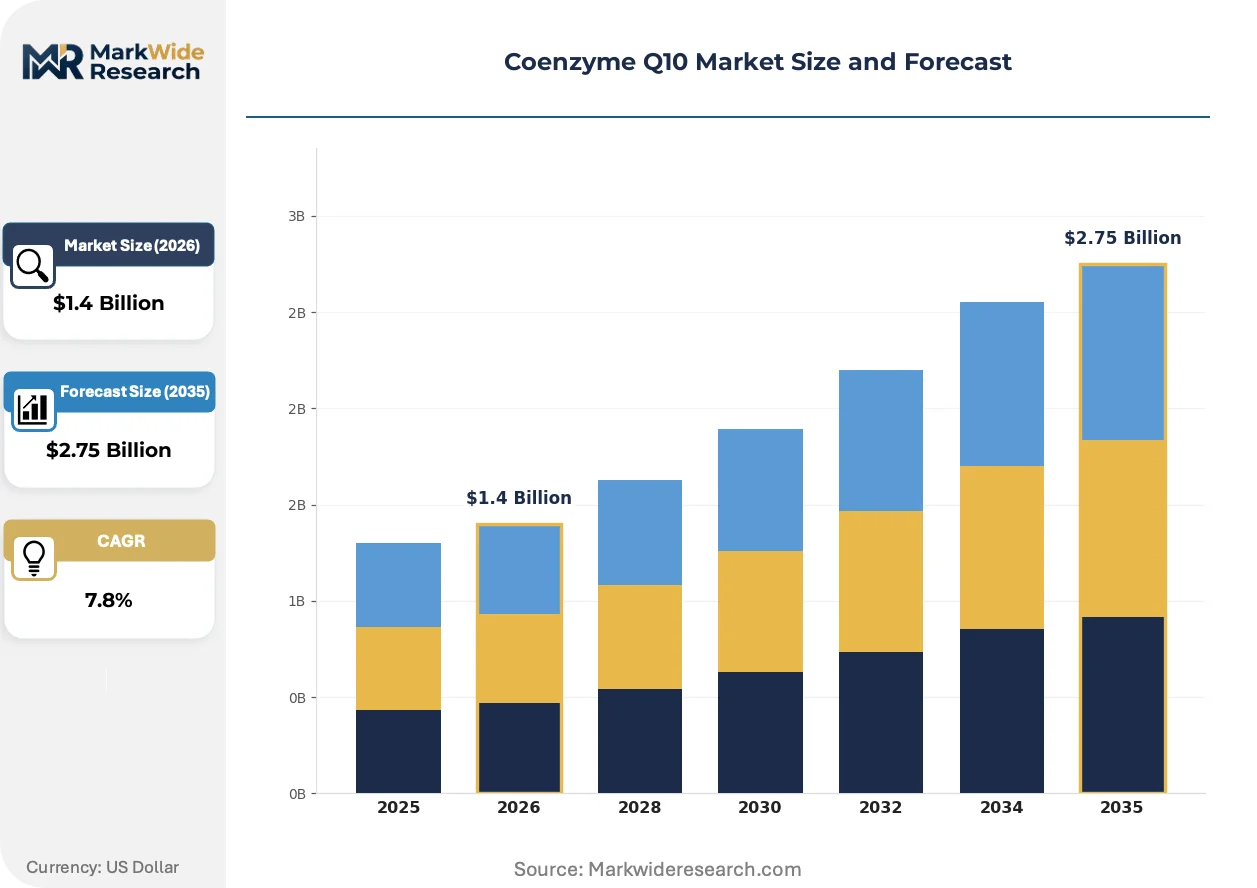
Market Dynamics
Fermentation capacity concentration in Japan and synthetic route competition from China are compressing margin structures for mid-tier nutraceutical contract manufacturers. Buyers now demand pharmaceutical-grade ubiquinol documentation that only vertically integrated producers can deliver.
Growth Catalysts
- Cardiovascular formulation demand:Aging demographics in developed economies are expanding prescription-adjacent supplement protocols. Clinicians increasingly recommend CoQ10 for statin-associated muscle symptoms.
- EFSA health claim substantiation:European manufacturers are investing in bioavailability studies to secure authorized claims for energy-yielding metabolism. This creates differentiation against unverified competitor products.
- Yeast fermentation yield improvements:Strain optimization and bioprocess engineering are reducing unit costs for natural-source ubiquinone. Premium positioning now depends on origin documentation rather than purity alone.
Market Restraints
- Kaneka Corporation supply concentration:Pharmaceutical-grade ubiquinol relies on a single fermentation source. Buyers face allocation risk during capacity constraints or quality holds.
- Solanesol raw material volatility:Tobacco-derived solanesol prices fluctuate with agricultural yields and alternative crop economics. Synthetic producers hedge through petroleum-based isoprenoid chemistry.
- FDA NDI notification friction:Novel delivery formats encounter extended review timelines. Water-soluble and nano-emulsion variants face particular scrutiny under the Dietary Supplement Health and Education Act framework.
Strategic Opportunities
- Indian pharmaceutical export channel:Formulation facilities in Hyderabad and Ahmedabad seek CoQ10 for cardiovascular combination therapies. Domestic production remains minimal, creating import dependency.
- Pet food functionalization:Veterinary nutrition brands are adding CoQ10 for senior canine cardiac support. Regulatory pathways through the Association of American Feed Control Officials remain less burdensome than human supplement frameworks.
- Sports nutrition bioavailability positioning:Endurance athletes demonstrate measurable plasma CoQ10 response to advanced delivery systems. Direct-to-consumer brands can command premium pricing with third-party absorption data.
Industry Challenges
- Fermentation scale-up expertise scarcity:Qualified bioprocess engineers command compensation premiums. Contract manufacturers struggle to staff yeast-based ubiquinone production lines.
- USP-NF monograph compliance timelines:Reference standard procurement and method validation extend product launch schedules. Smaller brands lack resources for simultaneous multi-market dossier preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coenzyme Q10 Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Capsules, Powders, Tablets End User: Healthcare Professionals, Retail Consumers, Nutraceutical Companies, Fitness Enthusiasts Distribution Channel: Online Stores, Supermarkets, Pharmacies, Nutrition Shops Formulation: Oil-Based, Water-Soluble, Ultrafine Powder, Emulsions |
| Companies Covered | ZMC USA LLC, GNC Holdings LLC, Kaneka Corporation, Nature's Bounty Co, Nisshin Seifun Group Inc., Gnosis, Pharma Nord A/S, Jarrow Formulas Inc., DSM Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coenzyme Q10 Market Emerging Trajectories
Delivery technology innovation and regulatory documentation requirements are fragmenting competitive positioning. Manufacturers now compete on plasma concentration data rather than ingredient purity alone.
Microencapsulation and liposomal formulation technologies are decentralizing bioavailability advantage from raw material origin to processing capability. Mid-sized contract manufacturers in Italy and Germany are adopting these methods to compete with Japanese fermentation-derived products. The technology is decentralizing premium pricing power toward formulation specialists with clinical validation capabilities.
EFSA's evolving guidance on antioxidant health claims is tightening evidentiary standards for European market access. Manufacturers must now submit human intervention studies rather than mechanistic data. Food supplement brands targeting Germany and France are restructuring R&D budgets toward clinical trial investment.
Direct procurement by wellness platforms is compressing traditional distribution layers. Amazon and specialized longevity retailers now negotiate bulk supply agreements directly with DSM Firmenich and Kaneka distributors. This pattern is most visible in North American and Australian markets where subscription commerce dominates supplement purchasing.
Coenzyme Q10 Market Segmentation
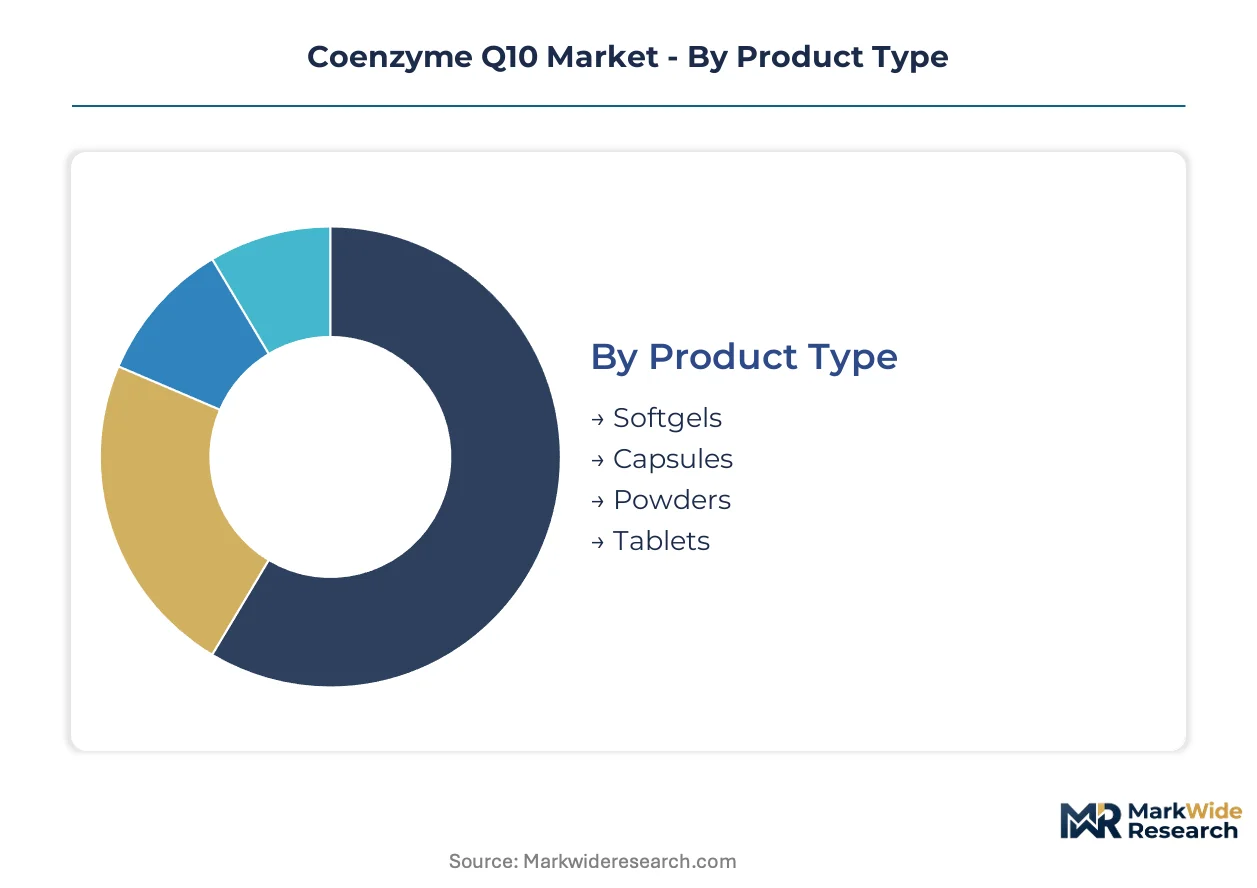
Coenzyme Q10 market segmentation reflects divergent capital requirements across manufacturing modalities. Fermentation infrastructure, formulation technology, and distribution logistics each demand distinct investment profiles that shape competitive entry barriers.
Product Type:
Softgel production lines require the heaviest capital outlay due to encapsulation machinery and cleanroom infrastructure. Tablet compression and powder blending occupy lower investment tiers with faster equipment depreciation cycles.
- Softgels:Gelatin or vegetable-based shells deliver lipid-soluble ubiquinone in oil suspensions for optimal intestinal absorption. Nutraceutical contract manufacturers in the United States and Germany concentrate procurement here, driven by clinician preference for documented bioavailability in cardiovascular protocols.
- Capsules:Two-piece hard shells accommodate powder or granule fills with lower moisture sensitivity than softgels. Indian pharmaceutical exporters favor this format for combination therapies targeting statin-associated muscle symptoms, where dose flexibility matters.
- Powders:Bulk ubiquinone crystals suit functional food fortification and compounding pharmacies. Japanese ingredient suppliers dominate this specification-grade segment for bakery and beverage applications.
- Tablets:Compressed formulations with binders and disintegrants serve cost-sensitive retail channels. Chinese synthetic producers supply tablet-grade material at price points inaccessible to fermentation-derived alternatives.
Most installed capacity flows through Softgels. Expansion is steepest in Water-Soluble formulations.
End User:
Customer concentration determines pricing power and technical service intensity. Direct procurement by large-volume buyers compresses margin structures for mid-tier suppliers unable to offer pharmaceutical-grade documentation.
- Nutraceutical Companies:Contract manufacturers and branded supplement houses purchase CoQ10 as active pharmaceutical ingredient or finished dosage form. These buyers demand certificates of analysis, stability data, and fermentation origin documentation that only Kaneka Corporation and DSM Firmenich AG consistently deliver.
- Healthcare Professionals:Clinicians and hospital pharmacies prescribe CoQ10 for statin-associated muscle symptoms and heart failure adjuvant therapy. German and Swiss medical channels require EFSA-aligned health claim substantiation that filters out unverified competitor products.
- Retail Consumers:Individual purchasers through pharmacies and online platforms show fragmented brand loyalty. Amazon and longevity-focused subscription services now bypass traditional distribution layers with direct Kaneka distributor agreements.
- Fitness Enthusiasts:Endurance athletes and biohackers seek advanced delivery systems with plasma concentration data. Direct-to-consumer brands command premium positioning through third-party absorption studies in North American and Australian markets.
Revenue concentrates with Nutraceutical Companies. Healthcare Professionals deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel selection dictates regulatory burden and working capital requirements. Pharmacy and supermarket routes demand extended payment terms and promotional funding that strain smaller suppliers.
- Pharmacies:Brick-and-mortar and hospital dispensaries stock pharmacy-grade ubiquinol with documented bioavailability. Pharma Nord A/S anchors European penetration through this channel with pharmacy-exclusive positioning in Denmark and Germany.
- Online Stores:E-commerce platforms and direct-to-consumer subscription services eliminate distributor markups. Amazon's bulk procurement agreements with DSM Firmenich distributors reshape North American pricing transparency.
- Nutrition Shops:Specialty retailers and health food chains cater to informed supplement users seeking practitioner-grade products. Australian and Japanese markets maintain strong independent nutrition shop networks resistant to pure price competition.
- Supermarkets:Mass-market retail placement requires economy-tier pricing and high-volume production scale. Chinese synthetic producers supply this channel with tablet and capsule formats at margins inaccessible to fermentation-derived material.
Volume concentrates through Online Stores. Pharmacy channel expansion is gaining share fastest in European markets.
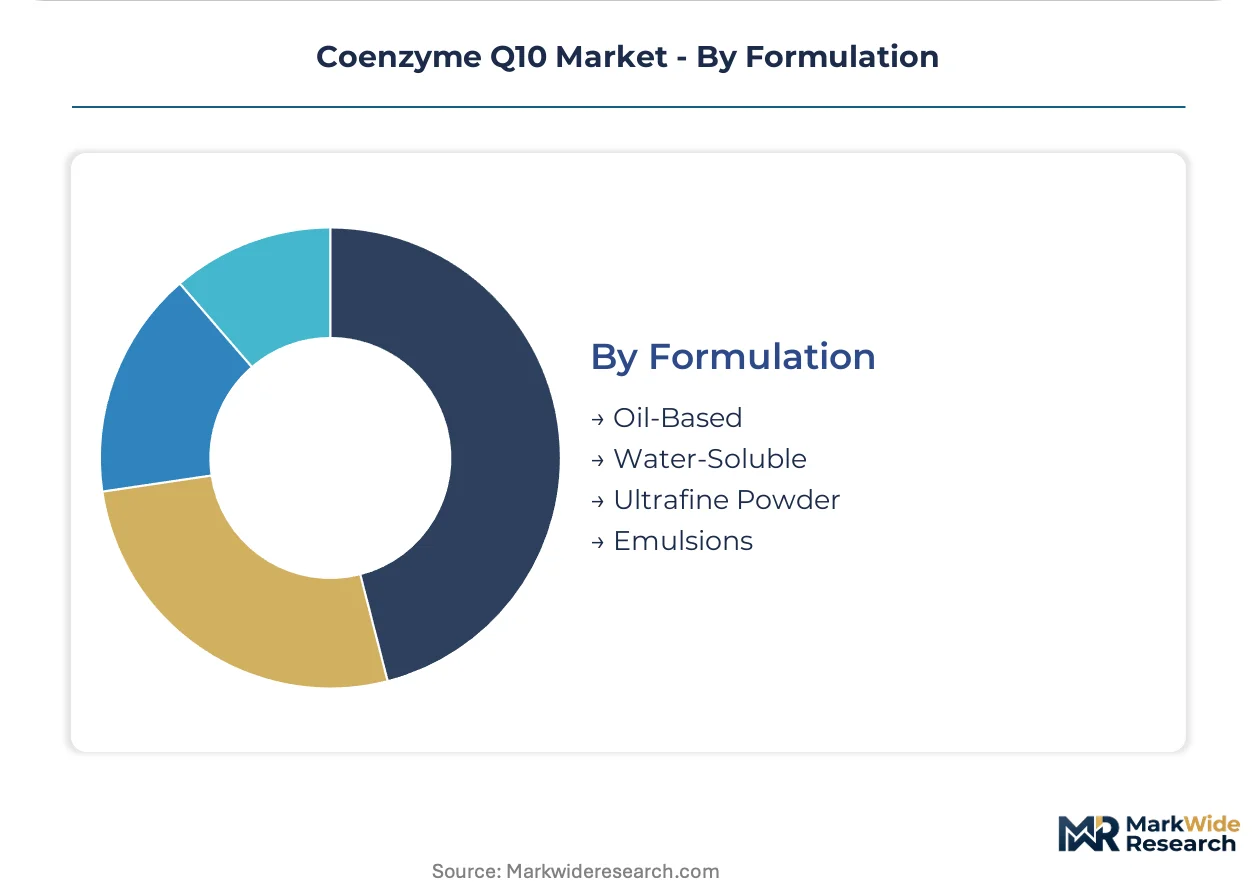
Formulation:
Technology investment separates premium positioning from commodity competition. Advanced delivery systems require R&D partnerships with universities or clinical research organizations that smaller manufacturers cannot sustain.
- Oil-Based:Ubiquinone dissolved in vegetable oils or medium-chain triglycerides leverages natural fat-solubility for lymphatic absorption. This mature technology dominates Japanese and European pharmaceutical-grade supply chains.
- Water-Soluble:Micellar, nano-emulsion, or cyclodextrin-complexed formats address bioavailability limitations for aging populations with compromised lipid digestion. Italian and German contract manufacturers adopt microencapsulation to compete with Japanese fermentation origin claims.
- Ultrafine Powder:Particle size reduction below 10 microns enhances dissolution rates for beverage and sachet applications. Sports nutrition brands in Australia and the United States specify this grade for pre-workout formulations.
- Emulsions:Oil-in-water dispersions suit functional food fortification where visual clarity and taste masking matter. Japanese beverage manufacturers lead adoption for ready-to-drink longevity products.
Production volume concentrates in Oil-Based formats. Water-Soluble capacity expansion is climbing the fastest as manufacturers target aging demographics with compromised fat digestion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium ubiquinol supply chains while Chinese synthetic producers compete aggressively on cost, creating divergent market structures across major economies.
United States
Cardiovascular supplement protocols and statin-associated muscle symptom management drive clinician-directed demand. FDA's New Dietary Ingredient notification requirements under DSHEA shape product entry pathways for novel delivery formats. Nutraceutical contract manufacturers in New Jersey and California concentrate procurement volumes for direct-to-consumer wellness brands.
Japan
Kaneka Corporation's fermentation-derived ubiquinone anchors domestic consumption and export markets for pharmaceutical-grade material. Ministry of Health, Labour and Welfare maintains quasi-drug classification pathways that differentiate premium ubiquinol from standard supplement grades. Tokyo-Osaka industrial corridor hosts specialized bioprocess engineering talent pools for yeast-based production scale-up.
Germany
Pharmacy channel control and documented bioavailability research underpin European demand concentration. EFSA health claim substantiation requirements filter unverified competitor products from authorized energy-yielding metabolism claims. Contract manufacturers in Bavaria and North Rhine-Westphalia adopt microencapsulation technologies to compete with Japanese origin positioning.
China
Synthetic route competition from petroleum-based isoprenoid chemistry compresses global margin structures for mid-tier suppliers. National Medical Products Administration governs pharmaceutical-grade material registration while standard supplement grades face lighter provincial oversight. Zhejiang and Jiangsu provinces concentrate chemical synthesis capacity for tablet-grade export production.
India
Formulation facilities in Hyderabad and Ahmedabad seek CoQ10 for cardiovascular combination therapies with minimal domestic production. Central Drugs Standard Control Organization regulates import dependency for active pharmaceutical ingredients. Maharashtra and Gujarat pharmaceutical clusters drive procurement growth for prescription-adjacent supplement protocols.
Coenzyme Q10 Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation concentrates around vertically integrated fermentation operators and formulation-technology leaders. Three archetypes dominate: Japanese-origin fermentation specialists, European pharmacy-channel anchors, and Chinese synthetic-scale producers. Capacity expansion and bioavailability documentation represent the dominant competitive moves as buyers demand pharmaceutical-grade certification.
Within the fermentation-origin tier, Kaneka Corporation and DSM Firmenich AG exemplify vertically integrated supply control. ZMC USA LLC represents North American distribution-focused positioning. Pharma Nord A/S anchors European pharmacy-channel penetration through documented bioavailability research. These three occupy positions that illustrate the market's segmentation between origin-authenticated premium supply and scale-driven synthetic competition.
| Leading Market Players |
|---|
| ZMC USA LLC |
| GNC Holdings LLC |
| Kaneka Corporation |
| Nature's Bounty Co |
| Nisshin Seifun Group Inc. |
| Gnosis |
| Pharma Nord A/S |
| Jarrow Formulas Inc. |
| DSM Firmenich AG |
| Others |
Supply Flow & Price Mechanics
Solanesol raw material costs cascade from tobacco agricultural yields through fermentation-derived ubiquinone pricing tiers, with Japanese-origin pharmaceutical-grade material commanding substantial premiums over Chinese synthetic alternatives in clinician-directed procurement channels.
Pricing Analysis
Capacity additions in China are reshaping price floors for tablet-grade synthetic material while fermentation-origin ubiquinol maintains premium positioning. Three-tier pricing structure across pharmaceutical-grade, supplement-grade, and economy-grade levels separates Kaneka-authorized distributors from mid-tier contract manufacturers. Cost compression in the synthetic segment is intensifying because petroleum-based isoprenoid chemistry achieves scale economies inaccessible to yeast fermentation. Retail consumers through supermarket channels demonstrate highest price sensitivity; healthcare professionals prescribing for statin-associated muscle symptoms show lowest sensitivity due to reimbursement-adjacent positioning.
Supply Chain Analysis
Single-source vulnerability sits with Kaneka Corporation's fermentation capacity in Japan for pharmaceutical-grade ubiquinol. Geographic supply concentration clusters in Japan, China, and Germany, with raw material dependencies on tobacco-derived solanesol, petroleum-based isoprenoid precursors, and gelatin or vegetable-based encapsulation materials. Supply chain risk centers on regulatory restriction through FDA NDI notification friction for novel delivery formats. Distribution runs through direct procurement agreements between large nutraceutical contract manufacturers and fermentation-origin suppliers, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA's DSHEA framework and Japan's quasi-drug classification creates margin expansion opportunities for manufacturers with multi-market dossier capabilities, as EFSA's tightening health claim substantiation requirements filter out undercapitalized competitors in European pharmacy channels.
For Market Incumbents: Deploy fermentation origin documentation as a defensive moat against synthetic route competition from Chinese producers. Secure allocation agreements with Kaneka Corporation distributors to mitigate single-source supply risk. Invest in microencapsulation and liposomal formulation R&D to decentralize bioavailability advantage from raw material provenance to processing capability. For New Entrants and Emerging Players: Capture the Indian pharmaceutical export channel for cardiovascular combination therapies where domestic production remains minimal and import dependency creates procurement gaps. Target veterinary nutrition applications through AAFCO regulatory pathways as a less burdensome entry point than human supplement frameworks. Lead with third-party plasma concentration data for sports nutrition positioning in Australian and North American direct-to-consumer markets. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier contract manufacturers lack pharmaceutical-grade documentation capabilities and face margin compression from vertically integrated fermentation operators. Long-term viability favors acquisition targets with clinical validation partnerships and multi-regulatory dossier preparation resources. Watch EFSA authorized health claim expansion as the inflection indicator for European pharmacy channel penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Yeast-based ubiquinone scale-up in Japan reinforces supply security for pharmaceutical-grade material. |
| Microencapsulation Technology Licensing | Italian and German contract manufacturers adopt liposomal delivery to compete with origin-authenticated products. |
| Direct-to-Consumer Channel Development | Amazon's bulk procurement agreements with DSM Firmenich distributors reshape North American pricing transparency. |
| Clinical Bioavailability Study Investment | Human intervention trials satisfy EFSA evidentiary standards for energy-yielding metabolism claims in Germany. |
| Veterinary Nutrition Product Line Extension | Senior canine cardiac support applications through AAFCO pathways face lighter regulatory burden than human supplements. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with nutraceutical contract manufacturing executives, pharmacy procurement managers, regulatory affairs specialists at fermentation suppliers, and veterinary nutrition brand directors informed supply-side dynamics. Secondary sources included FDA NDI notification databases, EFSA health claim opinions, Japanese Ministry of Health quasi-drug registrations, and customs trade data for solanesol and ubiquinone imports. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition separated volume growth from price mix effects across product type, end user, distribution channel, and formulation technology segments. CAGRs derived from regression analysis against aging demographic projections, statin prescription rates, and clinician recommendation survey data. Industry-specific inputs incorporated fermentation yield improvement curves, synthetic route cost trajectories, and regulatory approval timeline distributions for novel delivery formats throughout the forecast period.
Raw material agricultural volatility, regulatory guidance revision timelines, and bioprocess engineering talent scarcity are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented stakeholder inputs and modeled segmentation dynamics rather than single-point projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
Magtein Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Cordyceps Militaris Extract Market