
 Pet Nutraceuticals Market | 2026-2036
Pet Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Nutraceuticals Market Insights
The EU Green Deal is rebalancing ingredient sourcing priorities across European pet nutraceutical supply chains. Mars Incorporated leverages captive R&D facilities in Germany to develop novel probiotic strains for canine digestive health. Nestlé Purina PetCare Company anchors its North American position through backward integration into omega-3 oil refining. Alltech, Inc. differentiates via fermentation-derived nutritional actives produced at scale in Kentucky.
Pet nutraceuticals comprise bioactive compounds, including vitamins, minerals, probiotics, and omega fatty acids, formulated to support physiological functions beyond basic nutrition in companion animals; these products typically deliver standardized concentrations of active ingredients measured in colony-forming units or milligram doses per kilogram of body weight. Probiotics and omega fatty acids command premium positioning due to clinically documented efficacy in dermatological and gastrointestinal applications. Chewable formulations attract the highest margin pools as pet owners prioritize palatability and dosing convenience over cost. Powder segments sustain volume leadership in veterinary channels where precision dosing remains critical.
The FDA Center for Veterinary Medicine and the Association of American Feed Control Officials govern ingredient safety and label claims in the United States, while the EU's Feed Additives Regulation mandates pre-market authorization for novel functional compounds. These frameworks elevate compliance costs for entrants but simultaneously validate premium pricing for substantiated health claims. Stakeholders must monitor evolving substantiation requirements for microbiome-targeted products as regulatory bodies sharpen scrutiny on live culture stability claims.
Market Dynamics
Veterinary clinics across Germany, the United States, and Japan now integrate condition-specific supplements into standard treatment protocols, compressing the historical divide between pharmaceutical and nutritional interventions for companion animals.
Growth Catalysts
- EU Green Deal packaging mandates:The EU's sustainability rules are forcing rapid reformulation of supplement delivery formats, accelerating biodegradable chewable development.
- Omega fatty acid demand concentration:China and Brazil now anchor volume imports for companion animal omega-3 sourcing, reshaping Atlantic-Pacific trade flows.
- Live culture stability standards:Sharpened FDA Center for Veterinary Medicine scrutiny on probiotic viability claims validates premium positioning for substantiated products.
Market Restraints
- Novel compound authorization costs:The EU's Feed Additives Regulation mandates pre-market authorization that elevates compliance burdens for functional ingredient entrants.
- Wild-caught fish oil volatility:Peruvian anchovy harvest fluctuations transmit directly into omega-3 concentrate pricing and margin compression.
- Veterinary channel concentration:North American clinic networks exercise procurement leverage that squeezes independent supplement manufacturers.
Strategic Opportunities
- Brazilian market underpenetration:The country's expanding middle-class pet ownership base lacks localized probiotic manufacturing, creating import partnership potential.
- Fermentation-derived actives convergence:Precision fermentation combined with metabolomic screening enables novel bioactive discovery outside traditional botanical extraction.
- Direct-to-consumer subscription channels:Chewable format palatability advantages suit recurring delivery models that bypass veterinary markup structures.
Industry Challenges
- Microbiome research talent scarcity:Companion animal gut ecology expertise concentrates in academic veterinary programs, constraining commercial R&D staffing.
- Multi-jurisdiction label harmonization:Divergent FDA, EFSA, and state-level claim substantiation requirements force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Nutraceuticals Market |
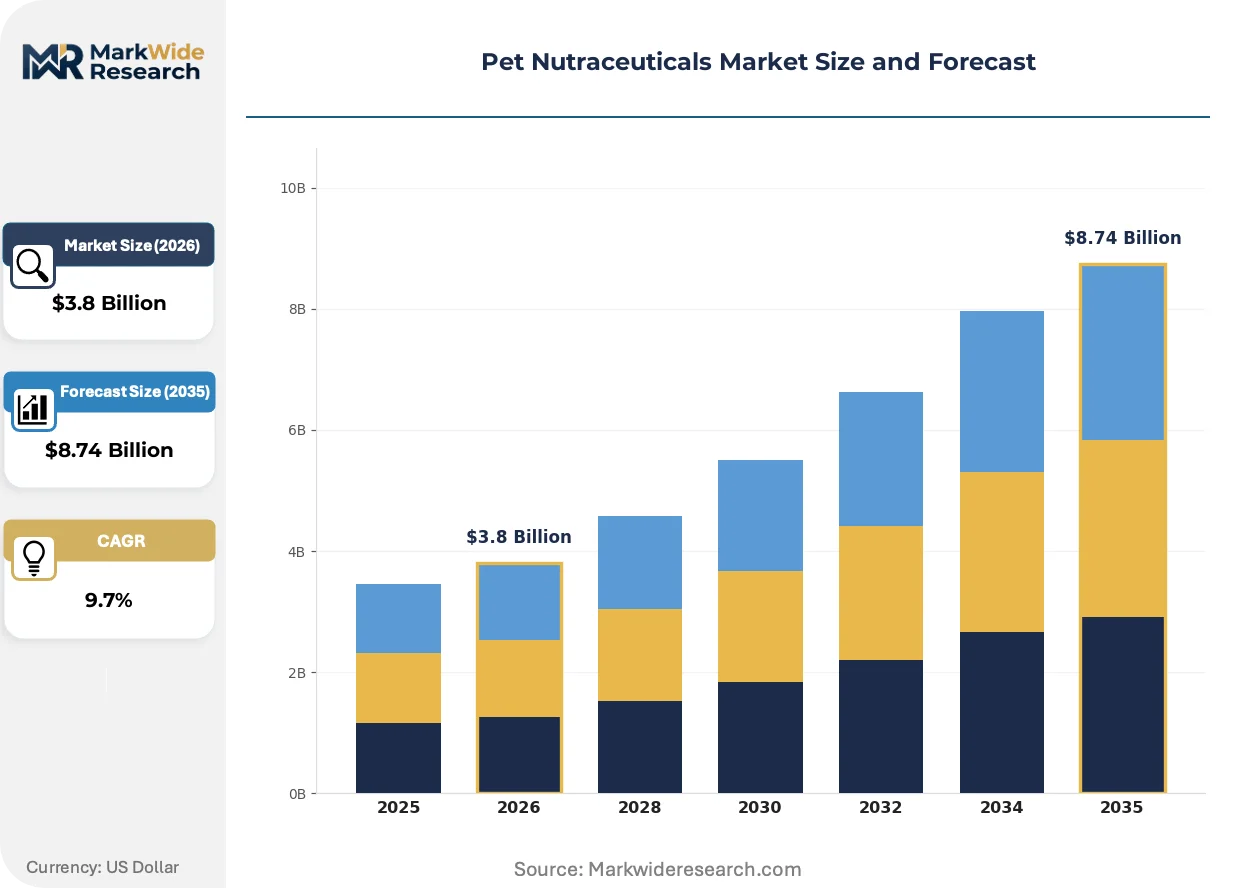
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Omega Fatty Acids Formulation: Powder, Capsule, Liquid, Chewable End User: Pet Owners, Veterinarians, Pet Shops, Online Retailers Target Animal: Dogs, Cats, Birds, Others |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare Company, Vetoquinol SA, Alltech, Inc., Archer Daniels Midland Company, Colgate-Palmolive Company, General Mills Inc., Zoetis Inc., Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Nutraceuticals Market Trends and Innovations
Formulation science and delivery mechanism engineering now dominate competitive differentiation as palatability and bioavailability supplant basic ingredient marketing in pet owner purchasing decisions.
Precision fermentation platforms for nutritional actives is rewriting the economics of high-purity omega fatty acid and probiotic strain production. Kentucky-based production facilities now supply standardized metabolite profiles that pharmaceutical-grade manufacturers in Germany and Japan are adopting at accelerating rates. This biotechnology shift is compressing the cost gap between synthetic and natural-source actives.
The EU Green Deal's packaging sustainability rules are mandating biodegradable film coatings and plant-based capsule materials for all new supplement registrations. European manufacturers face eighteen-month reformulation timelines that North American exporters must match to maintain continental market access. Chewable and powder segments are responding with edible packaging innovations and bulk dispensing systems.
Pet owner purchasing behavior is fragmenting across subscription direct-to-consumer platforms and veterinary-exclusive professional lines. Traditional retail pet specialty channels are losing share to telehealth-integrated supplement recommendations that bundle diagnostic testing with personalized dosing protocols. This channel rotation is most advanced in United States metropolitan markets where veterinary telemedicine adoption exceeds clinic visit frequency.
Pet Nutraceuticals Market Segmentation
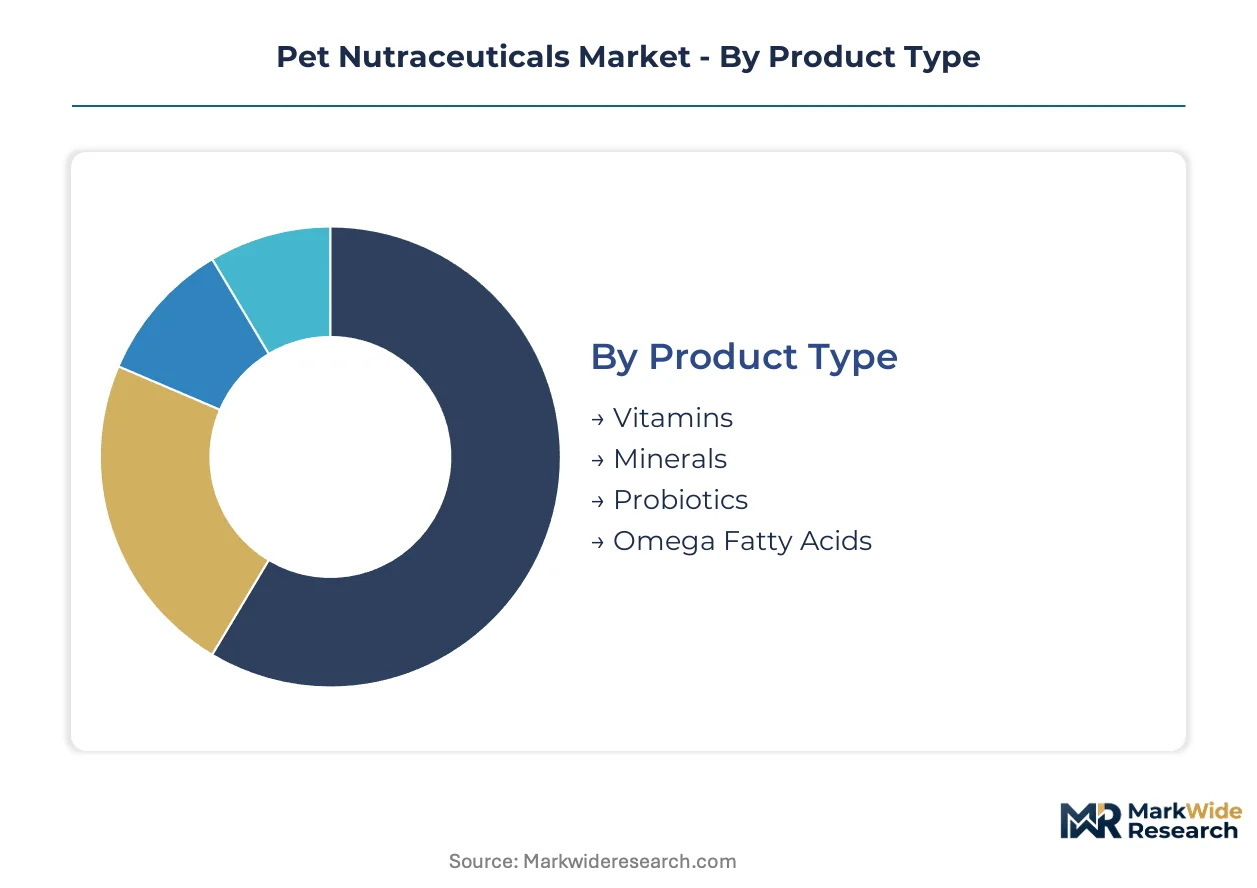
Segmentation in pet nutraceuticals reveals distinct capital requirements, formulation complexity, and channel economics across product categories. Manufacturers prioritize chewable and probiotic segments where palatability patents and live culture stability command premium positioning.
Product Type:
Probiotics and omega fatty acids demand the heaviest upfront investment in fermentation infrastructure and molecular distillation capacity.
- Probiotics:Live bacterial cultures measured in colony-forming units require climate-controlled production facilities and cold-chain distribution networks. Veterinary clinics in Germany and the United States now stock refrigerated probiotic formulations as standard gastrointestinal therapy, with FDA Center for Veterinary Medicine scrutiny on viability claims validating substantiated products.
- Omega Fatty Acids:EPA and DHA concentrates derived from marine or algal sources undergo supercritical CO2 extraction to achieve pharmaceutical-grade purity. China and Brazil now drive volume imports for companion animal applications, with Peruvian anchovy harvest fluctuations transmitting directly into concentrate pricing.
- Vitamins:Synthetic and natural-source fat-soluble and water-soluble compounds standardized to USP or EP monographs.
- Minerals:Chelated and inorganic forms including calcium, phosphorus, and trace elements for skeletal and metabolic support.
Omega fatty acids absorb the bulk of installed extraction capacity; probiotics are expanding most quickly as microbiome research validates clinical applications.
Formulation:
Chewable formats capture the widest margin pools through palatability engineering, while powders sustain volume leadership in precision-dosing veterinary channels.
- Chewable:Soft-moist extrusions and molded tablets incorporating flavor masking and bioavailability enhancers. Pet owners in United States metropolitan markets prioritize dosing convenience over cost, with subscription direct-to-consumer channels accelerating recurring delivery adoption.
- Powder:Micronized actives with standardized particle size distribution for homogeneous mixing into feed or water. Veterinary clinics rely on bulk powder dispensing for weight-based dosing protocols, particularly in Japan where precision measurement remains culturally emphasized.
- Capsule:Hard gelatin and plant-based shells containing single or multi-ingredient blends, facing EU Green Deal pressure for biodegradable film coatings.
- Liquid:Emulsified or aqueous suspensions for topical administration or mixing, common in avian and exotic animal applications.
Powder formulations dominate current production volumes; chewable segments are gaining share fastest through direct-to-consumer channel migration.
End User:
Veterinary channel concentration in North America creates procurement leverage that squeezes independent manufacturers, while pet specialty retail faces telehealth displacement.
- Veterinarians:Professional-exclusive lines with diagnostic-integrated dosing protocols. Clinic networks across Germany, the United States, and Japan now integrate condition-specific supplements into standard treatment, compressing the historical divide between pharmaceutical and nutritional interventions.
- Pet Owners:Direct purchasing through subscription platforms and retail channels, with telehealth-integrated recommendations bundling diagnostic testing and personalized protocols.
- Pet Shops:Branded and private-label shelf-stable formulations targeting mass-market price points.
- Online Retailers:Marketplace and direct-brand platforms leveraging chewable palatability for recurring delivery models that bypass veterinary markup structures.
Veterinarians anchor current revenue concentration; online retailers are climbing the fastest as channel rotation accelerates.
Target Animal:
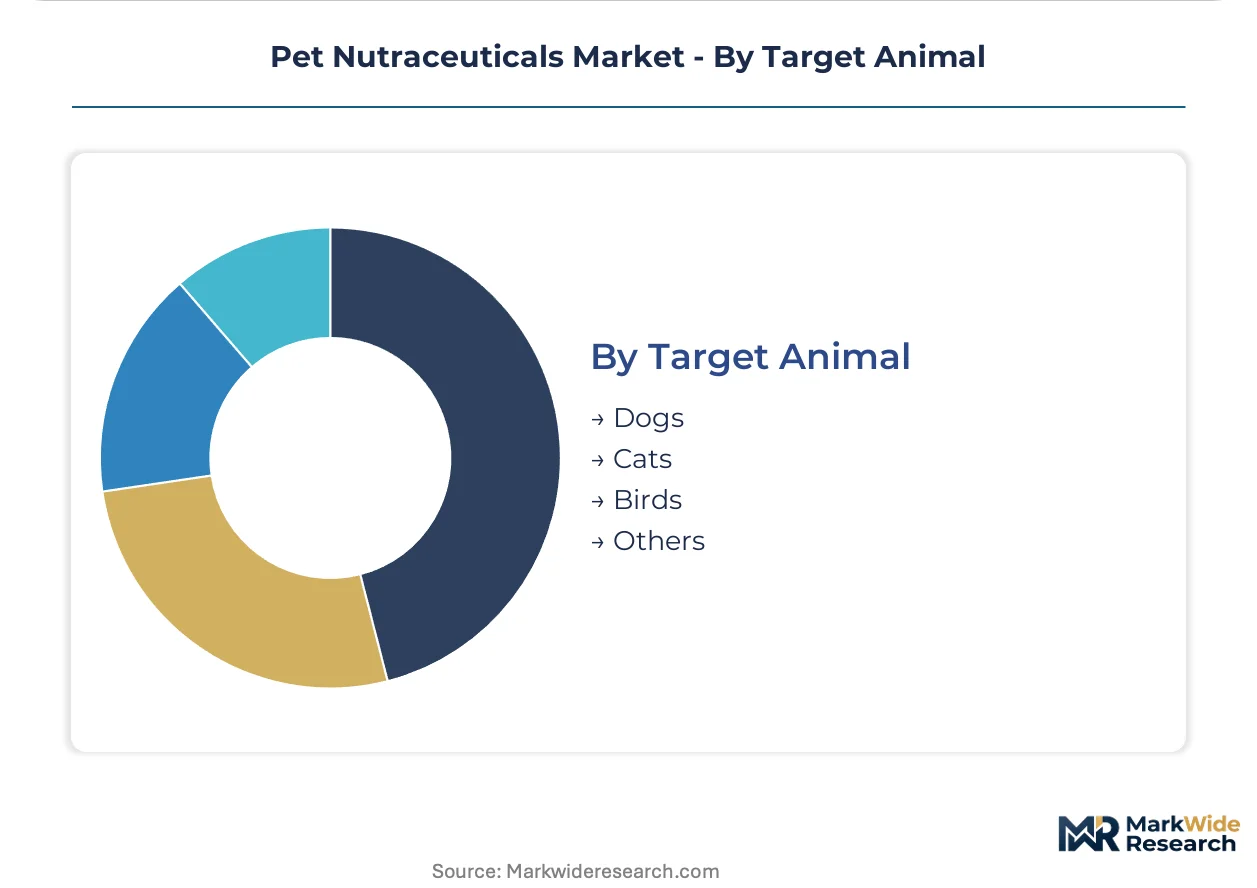
Canine formulations command the deepest R&D investment due to body size variation and digestive physiology complexity across breeds.
- Dogs:Weight-scaled dosing across giant to toy breeds drives SKU proliferation, with Mars Incorporated developing novel probiotic strains in German captive R&D facilities for canine digestive health applications.
- Cats:Obligate carnivore metabolism requires taurine-enhanced and liver-flavored formulations with distinct palatability profiles from canine equivalents.
- Birds:Species-specific beak-adapted delivery and water-soluble powder concentrates for avian metabolic support.
- Others:Small mammal, reptile, and equine formulations addressing niche physiological requirements.
Canine segments hold the majority of formulation patents; feline applications are expanding most quickly as cat ownership rises in urban households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kentucky's fermentation corridor anchors North American production of standardized nutritional actives, with precision platforms supplying pharmaceutical-grade manufacturers across three continents.
United States
Veterinary telemedicine adoption in metropolitan markets bundles diagnostic testing with personalized supplement protocols, compressing traditional retail channels. The FDA Center for Veterinary Medicine sharpens scrutiny on live culture stability claims for probiotic products. Mars Incorporated operates captive R&D facilities developing novel canine digestive health formulations.
Germany
EU Green Deal packaging mandates force eighteen-month reformulation timelines for biodegradable chewable development. EFSA substantiation requirements elevate compliance costs but validate premium positioning for clinically documented products. Bavaria hosts fermentation-derived active ingredient production serving continental veterinary clinic networks.
China
Expanding middle-class pet ownership drives volume imports of omega-3 concentrates for companion animal applications. The country's national feed safety regulator tightens pre-market authorization for novel functional compounds. Yangtze River Delta logistics hubs coordinate Atlantic-Pacific trade flow rebalancing for fatty acid sourcing.
Brazil
Rising urban pet ownership creates import partnership potential where localized probiotic manufacturing remains underdeveloped. ANVISA governs ingredient safety and label claims for veterinary nutritional products. São Paulo's distribution networks anchor South American omega fatty acid demand concentration.
Japan
Precision measurement protocols in veterinary channels sustain powder formulation volume leadership for weight-based dosing. PMDA and METI coordinate oversight of functional ingredient health claims. Tokyo-Osaka corridor clinics integrate condition-specific supplements into standard gastrointestinal therapy protocols.
Pet Nutraceuticals Market Competitive Landscape
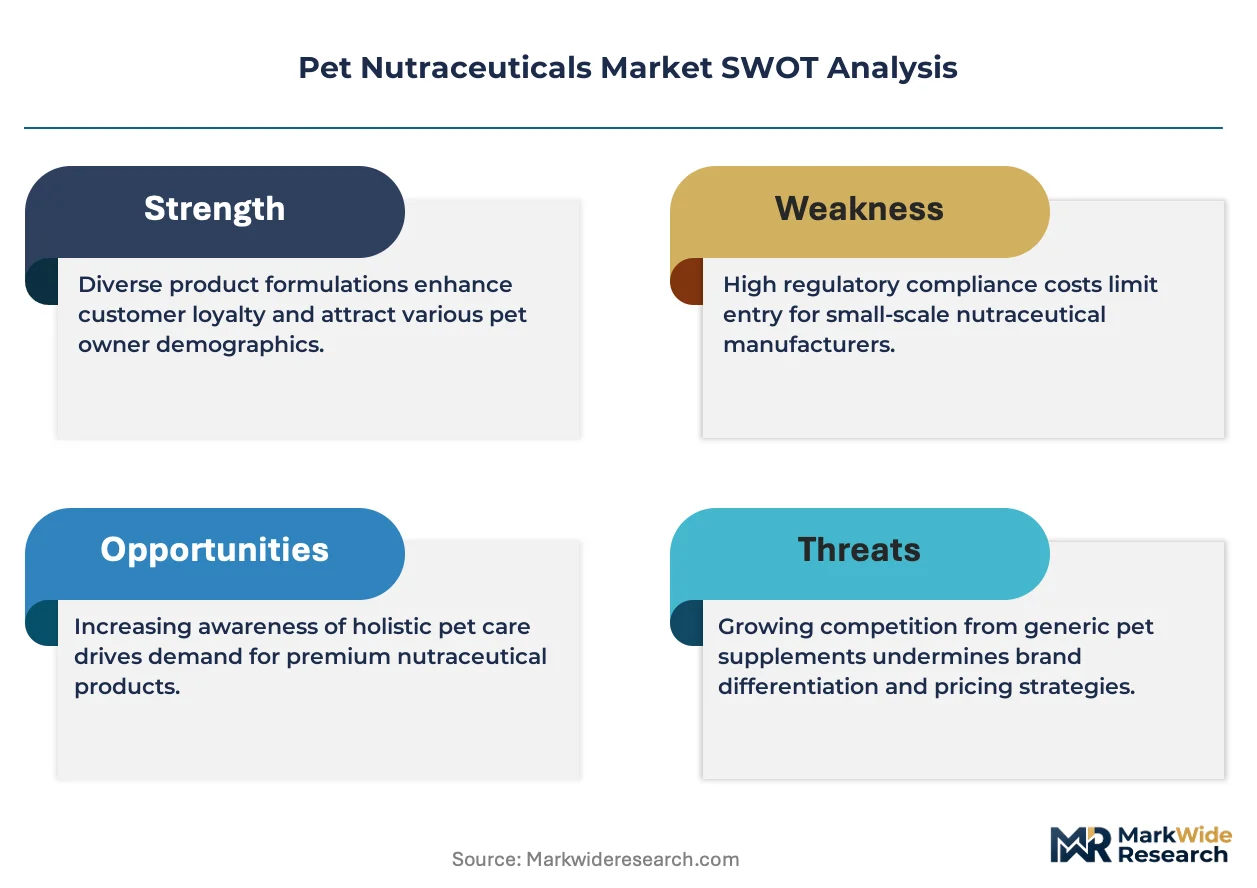
The competitive structure tilts toward diversified consumer goods conglomerates with captive veterinary health divisions. Mars Incorporated and Nestlé Purina PetCare Company anchor the upper tier through backward integration into ingredient refining and captive R&D infrastructure. Mid-scale fermentation specialists occupy a distinct position through precision platform economics. Strategic moves concentrate on portfolio diversification into condition-specific formulations and geographic expansion through import partnerships in underpenetrated markets.
Among diversified multinational anchors, Mars Incorporated, Nestlé Purina PetCare Company, and Alltech, Inc. exemplify three competitive archetypes. Mars represents the integrated consumer health conglomerate with German-based R&D captive facilities. Nestlé Purina occupies the position of North American market anchor through upstream control over omega-3 oil refining. Alltech sits within the fermentation-derived actives specialist tier, with Kentucky-based production supplying standardized metabolite profiles to pharmaceutical-grade manufacturers in Germany and Japan.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare Company |
| Vetoquinol SA |
| Alltech, Inc. |
| Archer Daniels Midland Company |
| Colgate-Palmolive Company |
| General Mills Inc. |
| Zoetis Inc. |
| Kemin Industries, Inc. |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation platforms for nutritional actives are compressing the cost gap between synthetic and natural-source compounds while concentrating production in Kentucky-based facilities. This biotechnology shift simultaneously elevates quality consistency and reduces dependency on wild-caught marine sourcing, redistributing pricing power toward manufacturers with captive fermentation capacity.
Pricing Analysis
Outcome-based pricing anchored to documented clinical efficacy in dermatological and gastrointestinal applications commands premium positioning for substantiated probiotic and omega fatty acid products. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and cold-chain integrity, with veterinary-exclusive lines capturing the widest margins. Cost compression in economy-tier powder formulations is intensifying because of procurement leverage exercised by North American clinic networks. Pet owners purchasing through direct-to-consumer subscription channels demonstrate the lowest price sensitivity, prioritizing palatability and dosing convenience over per-unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised probiotic shipments drive quality-control investments and insurance cost allocation across distribution networks. Production gravity centers on Kentucky for fermentation-derived actives, Germany for pharmaceutical-grade refining, and Peru for marine omega-3 concentrates. Raw material dependencies include Peruvian anchovy harvests, algal biomass feedstocks, and standardized bacterial culture banks. Single-source vulnerability in wild-caught fish oil transmits harvest fluctuations directly into concentrate pricing. Distribution runs through veterinary clinic networks, direct-to-consumer subscription platforms, and pet specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation is displacing legacy botanical extraction and wild-caught marine sourcing as the dominant production methodology for high-purity nutritional actives.
For Market Incumbents: Extend captive R&D infrastructure into novel probiotic strain development to defend against precision fermentation specialists eroding traditional extraction margins. Backward integration into omega-3 oil refining secures supply continuity against Peruvian anchovy harvest volatility. Certification investment for EU Green Deal packaging compliance preserves continental market access against eighteen-month reformulation timelines. For New Entrants and Emerging Players: Veterinary telemedicine platforms represent the most penetrable channel for bypassing established clinic network procurement leverage. Brazil's underdeveloped localized probiotic manufacturing creates import partnership potential for fermentation-derived actives. Direct-to-consumer subscription positioning leverages chewable palatability advantages for recurring revenue models that circumvent veterinary markup structures. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-derived actives specialists given the biotechnology shift validating premium positioning for standardized metabolite profiles. Long-term viability favors manufacturers with Kentucky-based precision platforms supplying pharmaceutical-grade customers across three continents. Practitioners should monitor FDA Center for Veterinary Medicine enforcement patterns on live culture stability claims as inflection indicators for probiotic segment consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Kentucky-based facilities now supply standardized actives to German and Japanese pharmaceutical-grade manufacturers. |
| EU Green Deal Packaging Compliance | Biodegradable chewable development preserves continental market access against regulatory reformulation mandates. |
| Veterinary Telemedicine Integration | Diagnostic testing bundling with personalized supplement protocols compresses traditional retail channel share. |
| Brazilian Import Partnership Formation | Localized manufacturing gaps in South America's largest companion animal market create distribution opportunities. |
| Cold-Chain Distribution Investment | Live culture stability requirements validate premium positioning through substantiated viability claims. |
Research Methodology
Trade databases, regulatory filings, and veterinary clinical trial registries formed the secondary backbone for supply chain and efficacy substantiation mapping. Primary interviews with fermentation facility operations directors, veterinary clinic procurement managers, pet specialty retail category buyers, and regulatory affairs specialists at animal health divisions were combined with secondary validation. Bottom-up and top-down triangulation reconciled production capacity data with end-user demand estimates.
Historical trendline analysis of omega fatty acid concentrate pricing and probiotic formulation adoption patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, formulation format, end-user channel, and target animal species. CAGRs were derived from capacity expansion timelines, regulatory approval pathways, and channel migration velocity. Industry-specific forecast inputs incorporated Peruvian anchovy harvest cycles and EU Green Deal implementation phases.
Caveats apply where regulatory enforcement intensity, marine ecosystem volatility, or microbiome research validation failures could materially shift the outlook. Forecasts reflect assumptions about cold-chain infrastructure investment and telemedicine platform penetration that remain sensitive to macroeconomic conditions. Practitioners should monitor FDA Center for Veterinary Medicine guidance document releases and EFSA novel feed additive authorization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Nootropics Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Europe Nutricosmetics Market