
 Levocarnitine Market | 2026-2036
Levocarnitine Market Size, Share, and Industry Trends Forecast 2026-2036
Levocarnitine Market Intelligence
Continuous-flow enzymatic synthesis is reconfiguring commercial production economics for active pharmaceutical ingredients, replacing batch fermentation with tighter purity control and higher space-time yields. Lonza Group AG leverages its bioprocess engineering heritage to anchor large-scale contract manufacturing for branded and generic levocarnitine formulations. Northeast Pharmaceutical Group Co., Ltd. dominates bulk API supply through backward integration into raw material fermentation, while Evonik Industries AG competes on specialized liposomal and sustained-release delivery platforms.
Levocarnitine, or L-carnitine, is a quaternary ammonium compound biosynthesized from lysine and methionine that facilitates long-chain fatty acid transport into mitochondria for beta-oxidation and ATP generation, with pharmaceutical grades requiring chiral purity above 99.5% and residual D-carnitine below 0.5% under USP-NF monographs. The therapy area segmentation shows metabolic disorders occupying the largest revenue share due to chronic dialysis patient populations requiring lifelong supplementation, while neurological disorders represent the fastest-expanding category as academic research links acetyllevocarnitine to cognitive protection in aging populations. Among distribution channels, third-party retail and online retail are displacing hospital-centric procurement as prescription-to-OTC switches and direct-to-consumer nutraceutical branding expand addressable touchpoints.
FDA enforces Current Good Manufacturing Practice for finished pharmaceuticals and dietary supplements under 21 CFR 111 and 211, while EMA's MDR and REACH frameworks govern excipient safety and environmental discharge from fermentation facilities; China's NMPA implements GB standards for chiral drug purity that align with ICH Q3D elemental impurity guidelines. These overlapping compliance layers raise capital barriers for new entrants and favor incumbents with established quality management systems and multi-territory dossier experience. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs, as divergence in impurity thresholds and analytical methods directly determines batch release feasibility and cross-border filing costs.
Market Dynamics
Continuous-flow enzymatic synthesis is compressing batch cycle times and tightening chiral purity specifications, forcing capital redeployment toward single-use bioreactor infrastructure and real-time analytical release testing.
Growth Catalysts
- Dialysis patient supplementation:Chronic kidney disease populations in the United States and Germany require lifelong levocarnitine therapy to prevent cardiomyopathy and muscle wasting, creating durable demand pull.
- EMA MDR harmonization:Streamlined excipient safety dossiers across EU member states reduce cross-border filing friction for generic manufacturers.
- Acetyllevocarnitine cognitive research:Academic institutions in Japan and Italy are expanding clinical investigation into neuroprotective applications for aging populations.
Market Restraints
- Fermentation input volatility:Lysine and methionine feedstock costs fluctuate with corn and soybean meal markets, squeezing API margin structures.
- Chinese API concentration:Northeast Pharmaceutical Group and regional fermentation specialists control bulk supply, creating single-source vulnerability for Western formulators.
- Chiral separation technical ceiling:Crystallization-based resolution methods face yield plateaus above 85 percent, limiting unit economics improvement.
Strategic Opportunities
- Indian outpatient expansion:CDSCO prescription-to-OTC switches for metabolic indications could unlock direct-to-consumer channels in tier-two cities.
- Liposomal delivery convergence:Combination of phospholipid encapsulation with sustained-release polymer matrices enables once-daily dosing for neurological applications.
- Sports nutrition regulatory tailwind:FSSAI clean-label mandates for dietary supplements position pharmaceutical-grade levocarnitine as a premium input for nutraceutical formulators.
Industry Challenges
- Bioprocess engineering talent scarcity:Continuous-flow enzymatic synthesis requires hybrid skill sets spanning biocatalysis and chemical engineering that outpace university pipeline output.
- Multi-territory dossier complexity:Divergent USP, EP, and ChP impurity thresholds force parallel validation studies, extending regulatory timelines.
- Legacy quality system integration:Paper-based batch records at mid-tier API facilities impede real-time release architecture deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Levocarnitine Market |
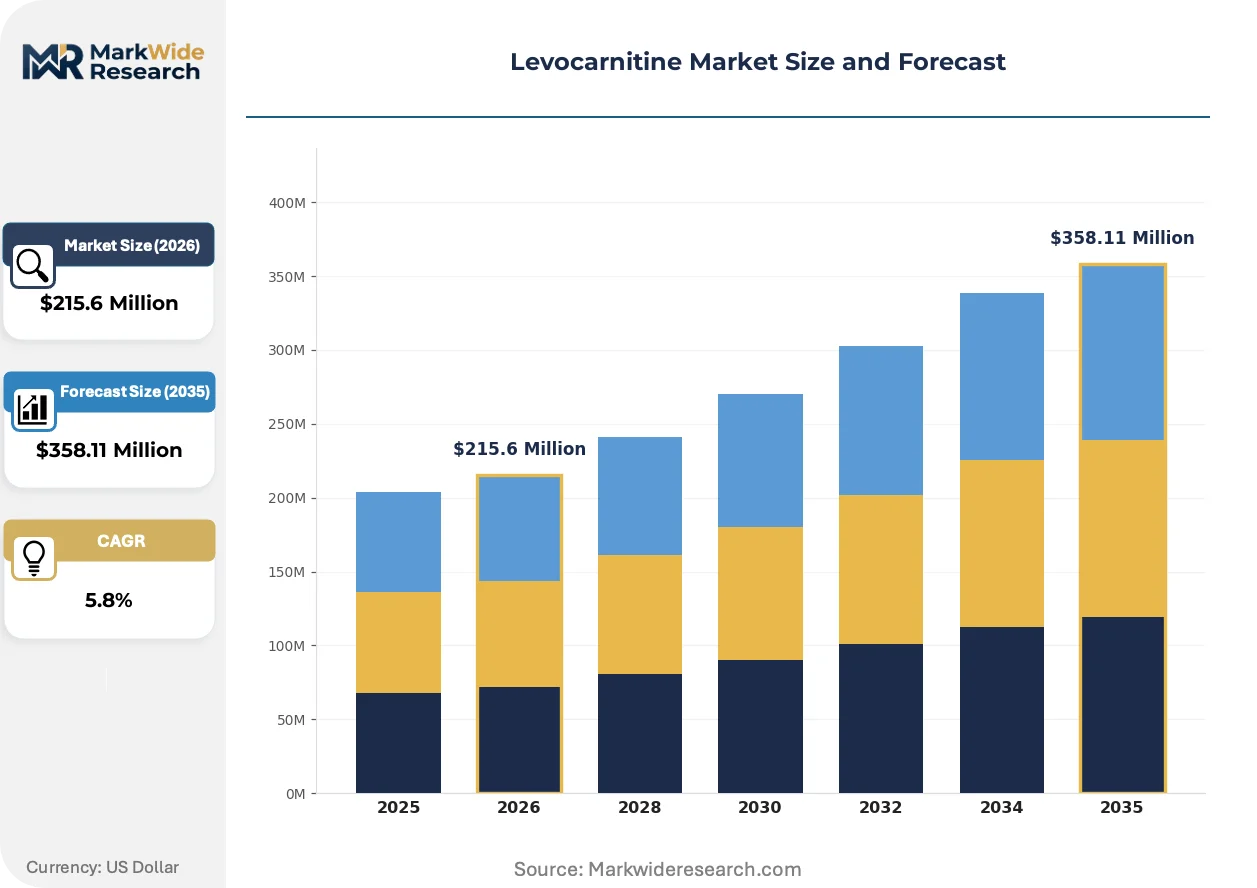
| Market Size in 2026 | $215.6 Million |
| Market Size in 2035 | $358.11 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid, Powder Therapy Area: Neurological Disorders, Cardiovascular Diseases, Metabolic Disorders, Muscle Disorders End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Online Retail, Direct Sales, Third-Party Retail, Wholesalers |
| Companies Covered | Evonik Industries AG, Aceto Corporation, Lonza Group AG, Tokyo Chemical Industry Co., Ltd., Sigma-Tau Pharmaceuticals, Merck KGaA, Northeast Pharmaceutical Group Co., Ltd., Jiangsu Wuzhong Pharmaceutical, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Levocarnitine Market Strategic Shifts & Innovations
Process analytical technology and digital twin modeling are compressing development timelines while regulatory convergence pressures are reshaping dossier strategies across major markets.
Process analytical technology (PAT) with inline Raman spectroscopy enables real-time chiral purity monitoring during enzymatic synthesis. Contract manufacturers in Switzerland and Singapore are adopting PAT at pilot scale to eliminate offline testing delays. This capability is digitizing batch release workflows and collapsing quality control cycle times from days to hours.
China's NMPA is tightening GB standards for elemental impurities under ICH Q3D alignment, requiring updated validation data for existing API filings. Domestic fermentation facilities must retrofit wastewater treatment systems to meet MEE discharge limits for ammonium byproducts. Generic levocarnitine producers with multi-territory experience are consolidating regulatory affairs functions to manage parallel compliance burdens.
Direct-to-consumer nutraceutical branding is displacing hospital-centric procurement for metabolic health applications. Third-party retail platforms and specialized online pharmacies in Germany and the United States now capture significant volume for maintenance therapy prescriptions. This channel rotation is most visible in sports nutrition, where athlete self-administration bypasses traditional endocrinology clinic gatekeepers.
Levocarnitine Market Segmentation
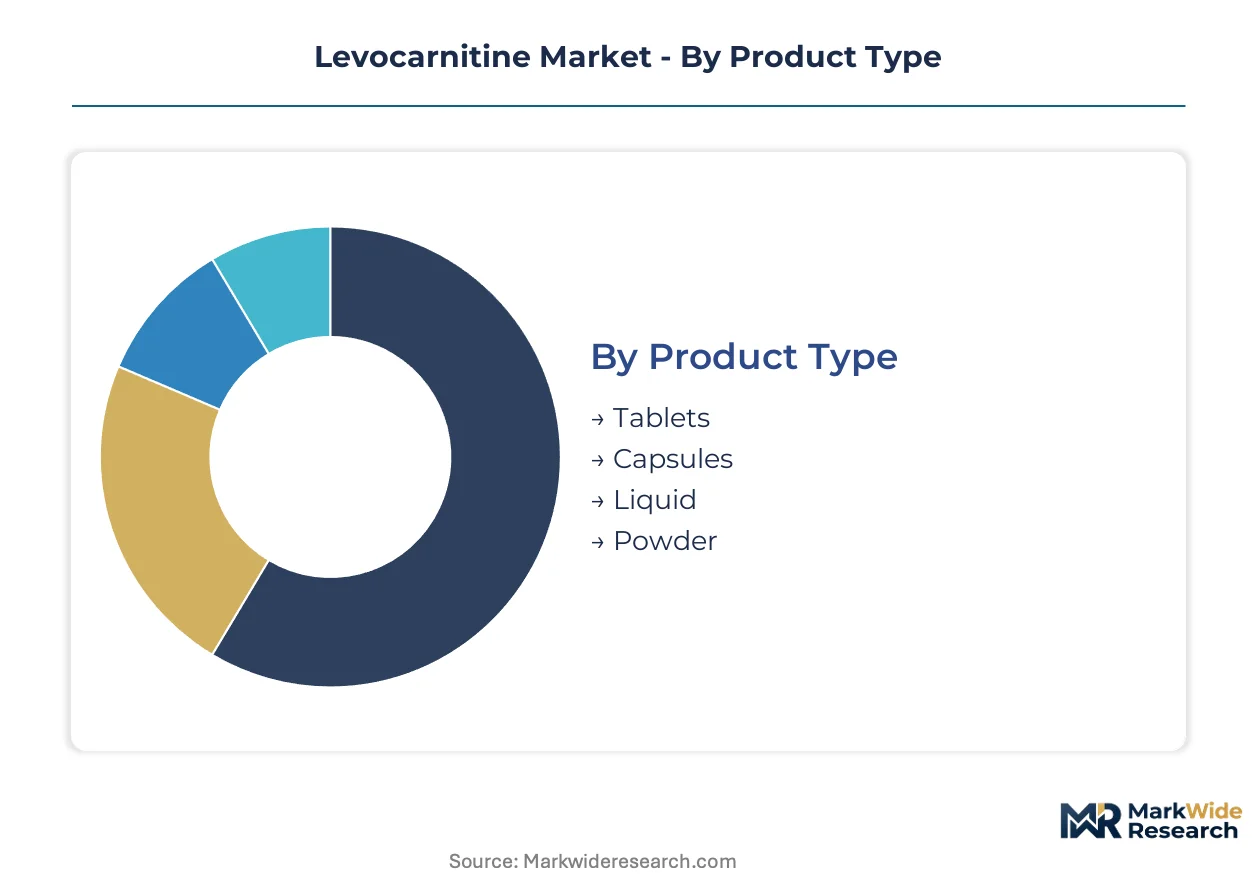
Levocarnitine formulation choices directly shape patient adherence patterns and reimbursement pathways across chronic therapy settings. Segmentation reveals how delivery format preferences diverge between institutional procurement and direct-to-consumer nutraceutical channels.
Product Type:
After-sales service intensity varies sharply across dosage forms, with liquid formulations requiring cold-chain logistics support and powder formats demanding compounding guidance that tablets rarely need.
- Tablets:Compressed dosage forms with standardized USP-NF dissolution profiles dominate hospital formularies and long-term care facilities. German and United States dialysis centers specify scored tablets for dose flexibility in end-stage renal disease protocols, though chiral stability testing adds quality control overhead.
- Liquid:Oral solutions and syrups with precise mg/mL concentrations serve pediatric metabolic disorder patients and geriatric populations with swallowing difficulties. Homecare demand concentrates in Japan and Italy where caregiver-administered dosing improves compliance in neurological applications.
- Capsules:Hard gelatin and HPMC shells protect hygroscopic API from moisture degradation during tropical storage.
- Powder:Bulk API or pre-weighed sachets enable personalized dosing in sports nutrition compounding.
By volume, Tablets lead. By growth pace, Liquid is ahead.
Therapy Area:
Cost tier stratification separates chronic replacement therapy from premium-priced neuroprotective indications, with reimbursement depth determining accessible patient pools.
- Metabolic Disorders:Primary carnitine deficiency and secondary depletion in chronic kidney disease require lifelong supplementation with documented cardiomyopathy prevention. United States Medicare and German statutory health insurance cover levocarnitine as essential therapy, anchoring volume concentration in these markets.
- Neurological Disorders:Acetyllevocarnitine formulations for cognitive decline and peripheral neuropathy command premium pricing in aging demographics. Japanese academic medical centers and Italian neurology clinics are expanding off-label protocols for mild cognitive impairment, driving fastest-expanding demand.
- Cardiovascular Diseases:Adjunctive therapy for statin-associated myopathy and congestive heart failure shows variable evidence strength across cardiology guidelines.
- Muscle Disorders:Sports nutrition and inherited myopathies represent emerging applications with limited formal reimbursement.
By volume, Metabolic Disorders lead. By growth pace, Neurological Disorders are expanding most quickly.
End User:
Customer type fragmentation reflects the prescription-to-OTC transition, with institutional gatekeepers losing share to self-directed patient procurement.
- Hospitals:Inpatient and outpatient departments manage acute deficiency correction and dialysis supplementation under pharmacy and therapeutics committee oversight. United States academic medical centers and German university hospitals maintain tight formulary control over parenteral formulations.
- Homecare:Self-administered oral therapy for maintenance dosing bypasses clinical visit requirements. Direct-to-consumer channels in Germany and United States capture maintenance prescriptions as patients seek convenience and cost savings.
- Clinics:Specialized endocrinology and nephrology practices coordinate chronic disease management.
- Pharmacies:Community and mail-order dispensaries handle prescription fulfillment and OTC transitions.
By volume, Hospitals lead. By growth pace, Homecare is climbing the fastest.
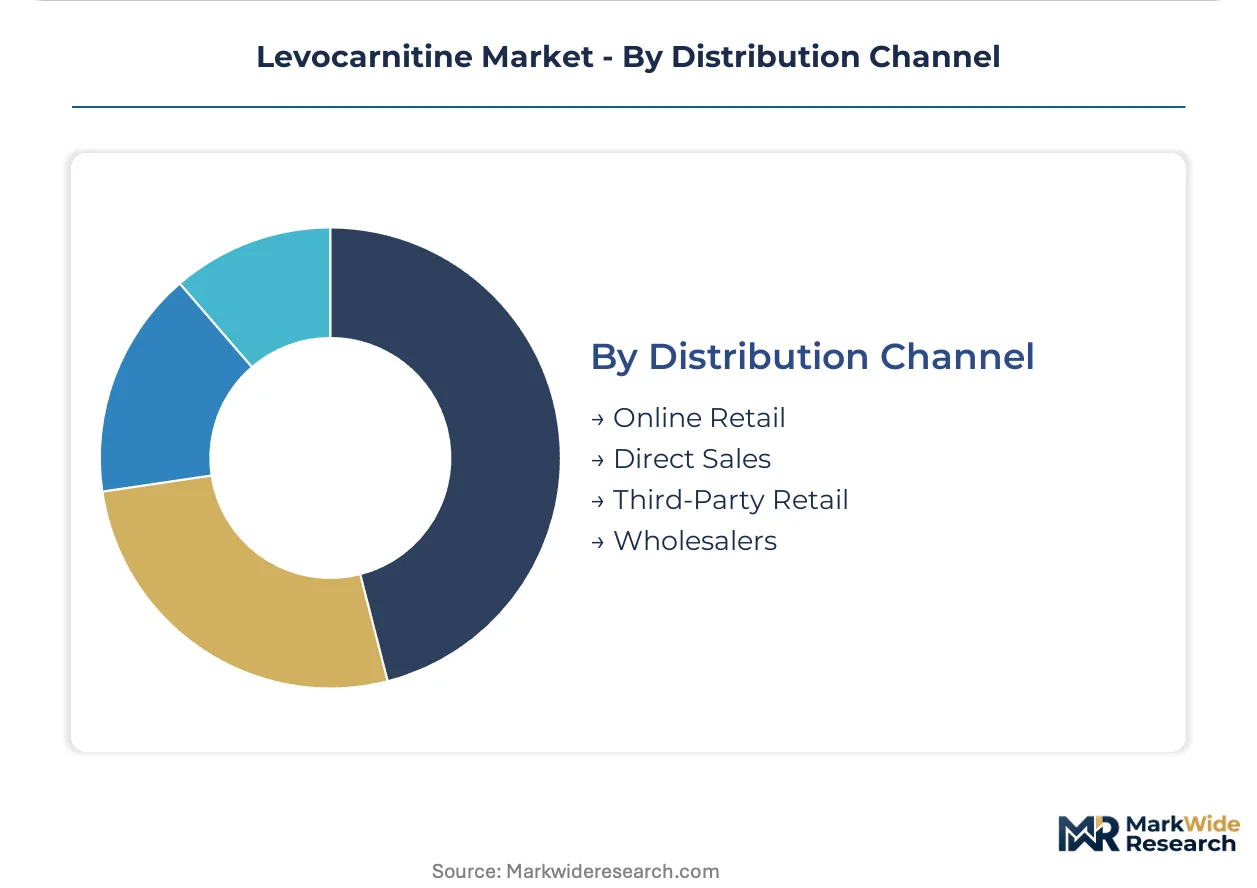
Distribution Channel:
Supply concentration in third-party retail is fragmenting as platform economics enable direct manufacturer-patient relationships.
- Third-Party Retail:Chain pharmacies and mass merchandisers in Germany and United States maintain dominant shelf presence for OTC levocarnitine. Retail buyer consolidation pressures margin structures while demanding promotional support that strains mid-tier manufacturers.
- Online Retail:Specialized nutraceutical platforms and marketplace sellers capture sports nutrition and wellness-oriented consumers. Direct-to-consumer branding in United States and China enables premium positioning outside pharmacy reimbursement constraints.
- Direct Sales:Manufacturer-owned channels serve institutional contracts and specialty pharmacy networks.
- Wholesalers:Regional distributors maintain inventory positions for hospital and clinic procurement.
By volume, Third-Party Retail leads. By growth pace, Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dialysis centers and metabolic disorder clinics concentrate levocarnitine procurement in aging healthcare systems. Germany, the United States, China, Japan, and Italy anchor volume demand through distinct reimbursement and regulatory pathways.
United States
Medicare coverage for end-stage renal disease patients sustains institutional procurement at dialysis chains. FDA enforces Current Good Manufacturing Practice under 21 CFR 211 for parenteral formulations. Boston and Minneapolis academic medical centers coordinate multi-site trials for acetyllevocarnitine neuroprotection protocols.
Germany
Statutory health insurance funds classify levocarnitine as essential therapy for primary carnitine deficiency. EMA's MDR harmonization streamlines excipient safety dossiers across EU member states. Frankfurt and Munich specialty pharmacies manage direct-to-consumer fulfillment for maintenance dosing.
China
NMPA implements GB standards for chiral drug purity aligned with ICH Q3D elemental impurity guidelines. Northeast Pharmaceutical Group anchors bulk API supply through backward integration into lysine fermentation. Shanghai and Shenyang fermentation facilities retrofit wastewater systems to meet MEE discharge limits for ammonium byproducts.
Japan
PMDA oversees pharmaceutical-grade manufacturing while METI coordinates industrial biotechnology policy. Tokyo academic medical centers expand clinical investigation into acetyllevocarnitine for mild cognitive impairment. Osaka contract manufacturers adopt process analytical technology for real-time chiral purity monitoring.
Italy
Neurology clinics in Milan and Rome pioneer off-label protocols for peripheral neuropathy and cognitive decline. EMA REACH frameworks govern excipient safety and environmental discharge from fermentation operations. Italian sports nutrition formulators source pharmaceutical-grade material for clean-label dietary supplements under EU food safety regulations.
Levocarnitine Market Key Industry Players
Channel-controlling players compete with product-specialist players across institutional and direct-to-consumer segments. The vendor base organizes into three tiers: multinational chemical conglomerates with fermentation infrastructure, mid-scale pharmaceutical API specialists, and regional nutraceutical formulators. Dominant competitive moves include capacity expansion in single-use bioreactor infrastructure and strategic partnerships for liposomal delivery platform licensing.
Within the multinational tier, Evonik Industries AG and BASF SE exemplify diversified chemical producers with pharmaceutical excipient portfolios. Lonza Group AG and Merck KGaA occupy positions as contract manufacturing organizations with bioprocess engineering heritage. Among Asia-Pacific specialists, Northeast Pharmaceutical Group Co., Ltd. and Tokyo Chemical Industry Co., Ltd. represent regional fermentation and chemical supply anchors respectively.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Aceto Corporation |
| Lonza Group AG |
| Tokyo Chemical Industry Co., Ltd. |
| Sigma-Tau Pharmaceuticals |
| Merck KGaA |
| Northeast Pharmaceutical Group Co., Ltd. |
| Jiangsu Wuzhong Pharmaceutical |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese fermentation capacity for bulk levocarnitine API determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic shape of procurement networks. Lysine and methionine feedstock volatility propagates through contract structures, compressing margins for Western formulators while concentrating pricing power with backward-integrated producers.
Pricing Analysis
Cost-plus contracts with corn and soybean meal indexation dominate long-term API procurement between Chinese fermentation houses and Western generic manufacturers. Price differentiation separates USP-NF pharmaceutical grades from food-grade material through chiral purity certification and elemental impurity testing under ICH Q3D. Cost compression in standard-grade tablets is intensifying because retail buyer consolidation demands promotional support that strains mid-tier formulators. Dialysis centers and hospital formularies show lowest price sensitivity due to Medicare and statutory insurance reimbursement, while sports nutrition direct-to-consumer channels exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for Western levocarnitine formulators. API production concentrates in China, with Northeast Pharmaceutical Group anchoring bulk supply, while formulation and packaging distribute across Germany, the United States, and Japan. Raw material dependencies rest on lysine and methionine fermentation feedstocks, phospholipid excipients for liposomal delivery, and gelatin or HPMC capsule shells. Distribution runs through third-party retail chains and specialized online pharmacies, with hospital procurement losing share to direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as prescription-to-OTC switches and direct-to-consumer nutraceutical branding splinter demand across multiple channels, creating niches for specialized players. The erosion of hospital-centric procurement opens white-space for agile formulators targeting self-directed patient segments.
For Market Incumbents: Build regulatory dossier depth as a moat against emerging Asian competitors. Invest in multi-territory quality management systems to manage divergent USP, EP, and ChP impurity thresholds, and expand single-use bioreactor capacity in Switzerland or Singapore to reduce tariff exposure. Patent cliff pressure on generic portfolios threatens pricing power; anchor position through continuous-flow enzymatic synthesis technology licensing. For New Entrants and Emerging Players: Establish a beachhead in Indian outpatient metabolic health through CDSCO prescription-to-OTC switch exploitation. Target tier-two cities with direct-to-consumer branding for maintenance therapy, bypassing hospital gatekeepers. Penetrable segments include sports nutrition compounding and acetyllevocarnitine neurological applications with limited incumbent presence. Go-to-market angle: pharmaceutical-grade positioning under FSSAI clean-label mandates. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors contract manufacturing organizations with bioprocess engineering heritage and multi-territory regulatory experience. Long-term viability centers on liposomal delivery platform control and real-time release testing capability. Acquisition target archetype: mid-scale API specialists with PAT-enabled facilities and established EMA/FDA dossier history. Signal to watch: NMPA GB standard tightening forcing domestic Chinese facility retrofits and export capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Enzymatic Synthesis Scale-Up | Lonza and Swiss CMOs compress batch cycle times while tightening chiral purity above USP-NF thresholds. |
| Liposomal Delivery Platform Licensing | Evonik's phospholipid encapsulation enables once-daily neurological dosing and premium positioning. |
| Multi-Territory Dossier Consolidation | Generic producers with parallel USP, EP, and ChP validation reduce regulatory timeline friction. |
| Direct-to-Consumer Channel Expansion | German and United States online pharmacies capture maintenance prescriptions outside reimbursement constraints. |
| Process Analytical Technology Deployment | Inline Raman spectroscopy at Osaka contract manufacturers collapses quality control from days to hours. |
Research Approach
A spread of perspectives from bioprocess engineering directors, regulatory affairs leads at generic manufacturers, dialysis center pharmacy managers, and nutraceutical formulators converged on the working assumptions. Primary interviews with fermentation facility operators and hospital procurement committees combined with secondary validation from FDA 21 CFR filings, EMA MDR submissions, NMPA GB standards, and USP-NF monograph databases. Bottom-up volume estimates from dosage-form consumption patterns triangulated against top-down API production capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user, and distribution channel, with regional regulatory cluster as an overlay. CAGRs derived from historical volume trajectory analysis adjusted for prescription-to-OTC switch timing and dialysis patient population growth. Industry-specific inputs encompassed lysine and methionine feedstock price indices and continuous-flow enzymatic synthesis adoption curves.
Macroeconomic conditions sit as an overlay; deviation in corn and soybean meal commodity prices, Chinese environmental enforcement intensity, or FDA/EMA harmonization pace would shift the trajectory. Forecasts reflect documented assumptions about patent expiration timing and reimbursement stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Europe Collagen Peptide Products Market