
 US Pet Nutraceuticals Market | 2026-2036
US Pet Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Nutraceuticals Market Insights
Single-source ingredient procurement is realigning toward multi-source supply networks among US pet nutraceutical manufacturers seeking resilience against raw material volatility. Nestle Purina Petcare leverages its captive R&D infrastructure to develop proprietary probiotic strains, while Mars Incorporated anchors its position through backward integration into omega fatty acid refining. Nutramax Laboratories differentiates via veterinary-exclusive distribution channels that bypass mass retail entirely.
Pet nutraceuticals comprise bioactive compounds including glucosamine, chondroitin, omega-3 fatty acids, and live microbial cultures formulated to physiological doses for non-human metabolism, manufactured through cold-press extrusion or microencapsulation to preserve thermolabile actives. These products serve the commercial purpose of bridging nutritional gaps in processed pet diets or addressing species-specific pathophysiologies beyond baseline feed adequacy. Joint health applications dominate current revenue pools due to aging dog demographics, while probiotic formulations for digestive health represent the fastest-expanding segment as microbiome science transfers from human to veterinary nutrition. Chewable formulations command premium positioning over powders and liquids because of dosing compliance advantages in companion animal households.
The FDA Center for Veterinary Medicine regulates product labels and health claims, while the Association of American Feed Control Officials establishes nutrient profiles that manufacturers must meet for interstate distribution. The National Animal Supplement Council provides voluntary compliance pathways that increasingly determine retail access decisions by major pet specialty chains. Stakeholders must monitor whether state-level veterinary pharmacy boards restrict the sale of condition-specific supplements through non-clinical channels.
Market Dynamics
Pet humanization is compressing the innovation cycle for condition-specific supplements as owners demand clinical-grade efficacy from over-the-counter products, forcing manufacturers to validate bioactive claims through veterinary pharmacokinetic studies rather than traditional feed-grade safety testing alone.
Growth Catalysts
- Aging Canine Demographics:Extended lifespans among large-breed dogs are expanding the addressable population for osteoarthritis management products, with veterinary clinics now screening joint health at younger ages to initiate preventive protocols.
- FDA Center for Veterinary Medicine Guidance:Draft guidelines on animal dietary supplement labeling are clarifying permissible structure-function claims, reducing regulatory uncertainty that previously deterred R&D investment in novel bioactive formulations.
- Microbiome Research Translation:Human gut health discoveries are accelerating probiotic strain development for species-specific gastrointestinal conditions, with veterinary nutritionists now prescribing live microbial cultures for antibiotic-associated dysbiosis recovery.
Market Restraints
- Marine-Derived Omega-3 Volatility:Wild-caught fish oil supply disruptions and aquaculture feed competition are compressing gross margins for EPA/DHA concentrates, forcing reformulation toward algal alternatives with inferior oxidative stability profiles.
- Ingredient Concentration in Pacific Northwest:Domestic glucosamine and chondroitin sulfate production clusters around Puget Sound processing facilities, creating geographic vulnerability to regional climate events and labor actions.
- Clinical Evidence Thresholds:Veterinary teaching hospitals now require randomized controlled trial data for formulary inclusion, raising the capital barrier for novel supplement market entry beyond what feed-grade safety substantiation previously demanded.
Strategic Opportunities
- Feline Underpenetration:Supplement compliance rates in cat households lag canine adoption by approximately half, creating whitespace for palatability-engineered formulations that mask bitter actives in lickable pastes rather than conventional tablets.
- Telehealth Veterinary Platforms:Remote consultation services are bypassing traditional clinic gatekeepers for supplement recommendations, enabling direct-to-consumer brands to capture prescription-adjacent sales through digital veterinary partnerships.
- State Veterinary Pharmacy Board Harmonization:Pending uniform standards for non-prescription therapeutic product sales across California, New York, and Texas would eliminate the current patchwork of channel restrictions that complicate national distribution strategies.
Industry Challenges
- Veterinary Nutrition Specialist Scarcity:Board-certified veterinary nutritionists number fewer than one hundred nationally, creating a bottleneck for clinical trial design and label claim substantiation that manufacturer-employed generalist veterinarians cannot legally substitute.
- Cold-Chain Microencapsulation Capacity:Thermolabile probiotic preservation requires pharmaceutical-grade lyophilization infrastructure that contract manufacturers in the animal health sector lack, forcing brands to compete with human nutraceutical producers for limited toll processing slots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Nutraceuticals Market |
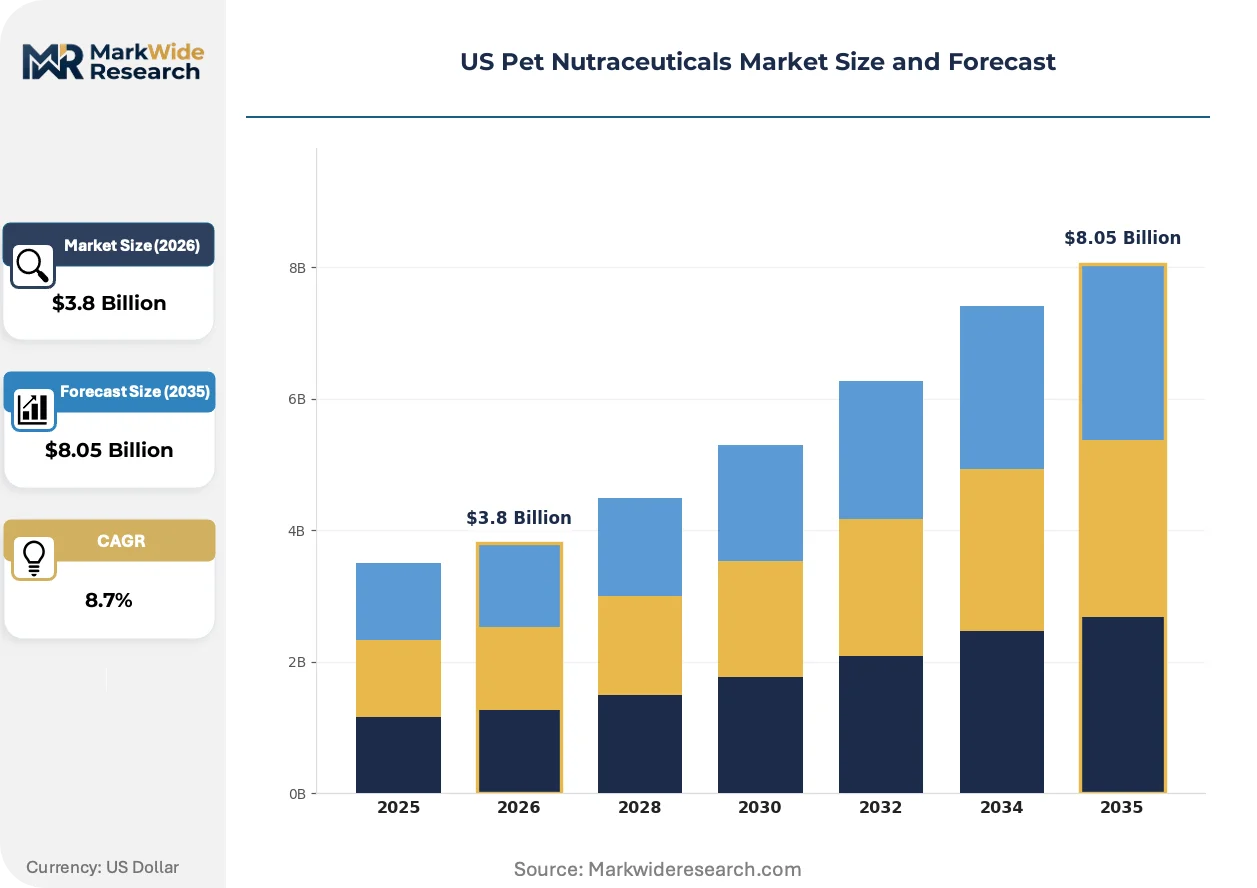
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Omega Fatty Acids, Probiotics Application: Joint Health, Skin & Coat, Digestive Health, Immune Support Animal Type: Dogs, Cats, Birds, Small Mammals Formulation Type: Chewables, Powders, Tablets, Liquids |
| Companies Covered | Nestle Purina Petcare, Mars Incorporated, ADM, Nutramax Laboratories, Virbac, Vetoquinol, Zoetis, Diamond Pet Foods, Spectrum Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Nutraceuticals Market Trends and Innovations
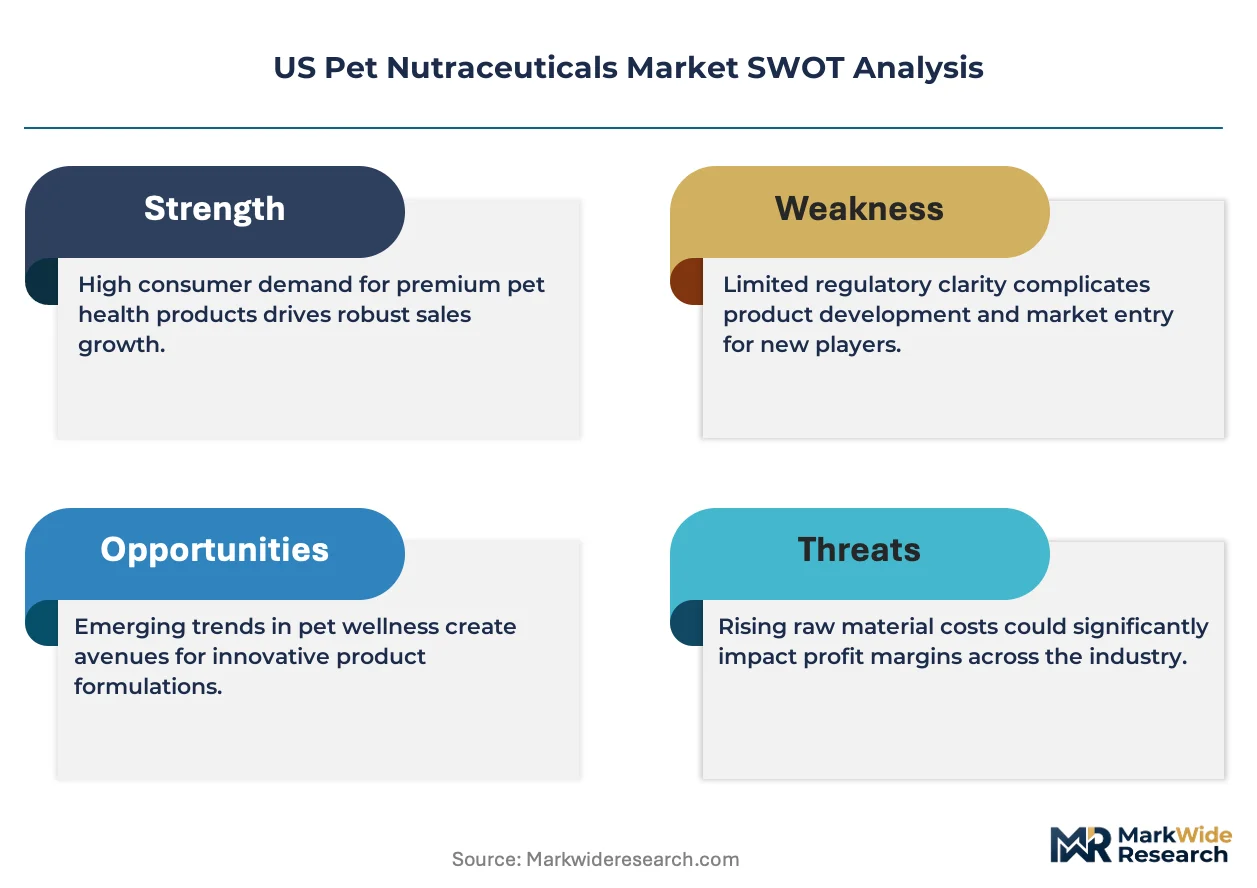
Formulation science is pivoting from shelf-stable powders toward bioavailable delivery systems that mimic treat consumption patterns, while regulatory clarity and microbiome research converge to elevate clinical credibility expectations.
Precision fermentation is decentralizing the supply of high-purity omega-3 fatty acids by enabling algal DHA production in controlled bioreactor environments independent of marine ecosystem volatility. Mid-tier pet food manufacturers are adopting these ingredients at accelerating rates to hedge against fish oil price spikes. This biotechnology is compressing the historical premium commanded by Nordic marine-derived concentrates and enabling inland production facilities.
The National Animal Supplement Council's Quality Seal program is tightening audit protocols for good manufacturing practice compliance, with third-party certification now mandatory for placement in Petco and PetSmart corporate-owned locations. Manufacturers without NASC membership face de facto exclusion from the specialty retail channel that drives margin-rich premium positioning. California and Northeast corridor retailers are enforcing these standards most aggressively, creating a bifurcation between certified and non-certified brand accessibility.
Subscription-based replenishment models are displacing episodic retail purchasing for chronic condition supplements, with Chewy and Amazon's auto-ship functionality capturing the joint health and digestive support categories. Veterinary clinics are responding by launching proprietary online pharmacies with competitive pricing to retain the recurring revenue stream. This channel shift is most pronounced in urban coastal markets where delivery infrastructure supports same-day fulfillment expectations.
US Pet Nutraceuticals Market Segmentation
Pet nutraceutical manufacturers configure production lines around physiological dosing requirements and species-specific palatability constraints. Segmentation decisions determine cold-chain investments, veterinary channel access, and regulatory substantiation pathways.
Product Type:
Standardized commodity ingredients compete with proprietary bioactive formulations across this spectrum, with margin capture depending heavily on strain exclusivity and extraction method control.
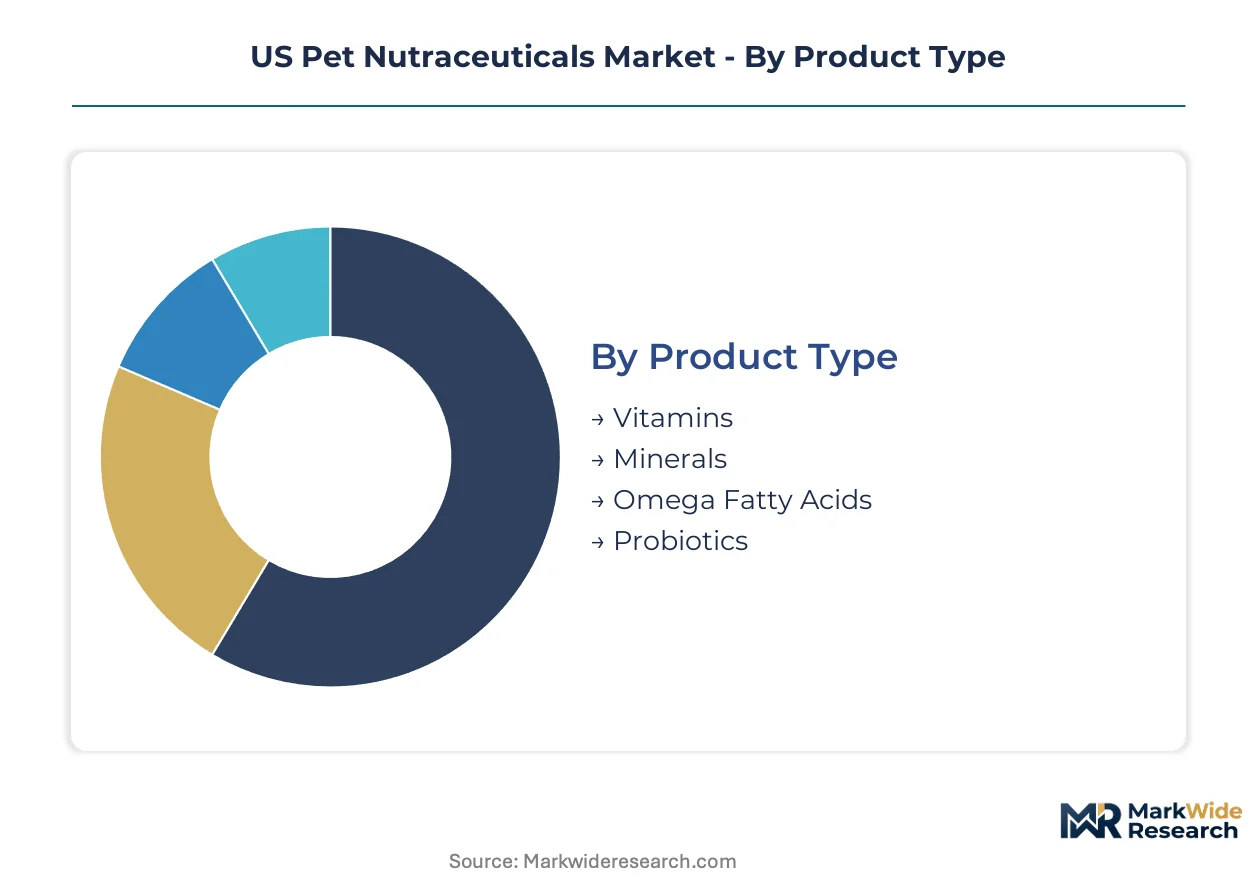
- Vitamins:Synthetic fat-soluble and water-soluble compounds formulated to AAFCO nutrient profiles for processed pet food fortification. Demand concentrates in Midwest contract manufacturing facilities serving mass-market kibble producers facing nutrient degradation during extrusion.
- Minerals:Chelated and inorganic trace element complexes optimized for bioavailability in carnivore digestive systems. Expansion is steepest in zinc and selenium formulations targeting dermatological conditions in California specialty retail channels.
- Omega Fatty Acids:EPA/DHA concentrates from marine and algal sources.
- Probiotics:Live microbial cultures with species-specific strain selection.
Most installed capacity flows through Vitamins. Expansion is steepest in Probiotics.
Application:
Condition-specific positioning requires distinct clinical evidence packages, with veterinary formulary inclusion driving premium pricing power in chronic disease management categories.
- Joint Health:Glucosamine-chondroitin matrices and green-lipped mussel extracts targeting osteoarthritis progression in aging large-breed dogs. Demand concentrates in Northeast corridor veterinary clinics screening hip dysplasia at two-year wellness exams.
- Digestive Health:Microbiome modulation formulations for antibiotic recovery and inflammatory bowel management. Expansion is climbing fastest as telehealth veterinarians prescribe probiotics for feline chronic enteropathies bypassing traditional clinic dispensing.
- Skin & Coat:Essential fatty acid and biotin complexes for allergic dermatitis.
- Immune Support:Beta-glucan and antioxidant formulations for senior animals.
Joint Health commands the largest revenue pool. Digestive Health is gaining share fastest.
Animal Type:
Formulation complexity escalates with metabolic diversity and dosing compliance challenges across species with divergent gastrointestinal physiology and taste receptor profiles.
- Dogs:Palatable chewable matrices dominate, with dosing protocols established for breed-specific weight ranges. Demand concentrates in suburban households purchasing premium supplements through veterinary clinic loyalty programs.
- Cats:Bitter-masking paste formulations and microencapsulated powders for obligate carnivore dietary preferences. Expansion is accelerating in urban coastal markets where feline ownership rates exceed national averages and owners seek stress-free administration methods.
- Birds:Water-soluble and pelleted formulations for avian metabolic requirements.
- Small Mammals:Species-specific dosing for rabbit, ferret, and guinea pig physiology.
Dogs absorb the majority of production volume. Cats show the steepest adoption trajectory.
Formulation Type:
Manufacturing capital allocation diverges between high-speed tablet presses, cold-extrusion chewable lines, and aseptic liquid filling equipment with incompatible throughput economics.
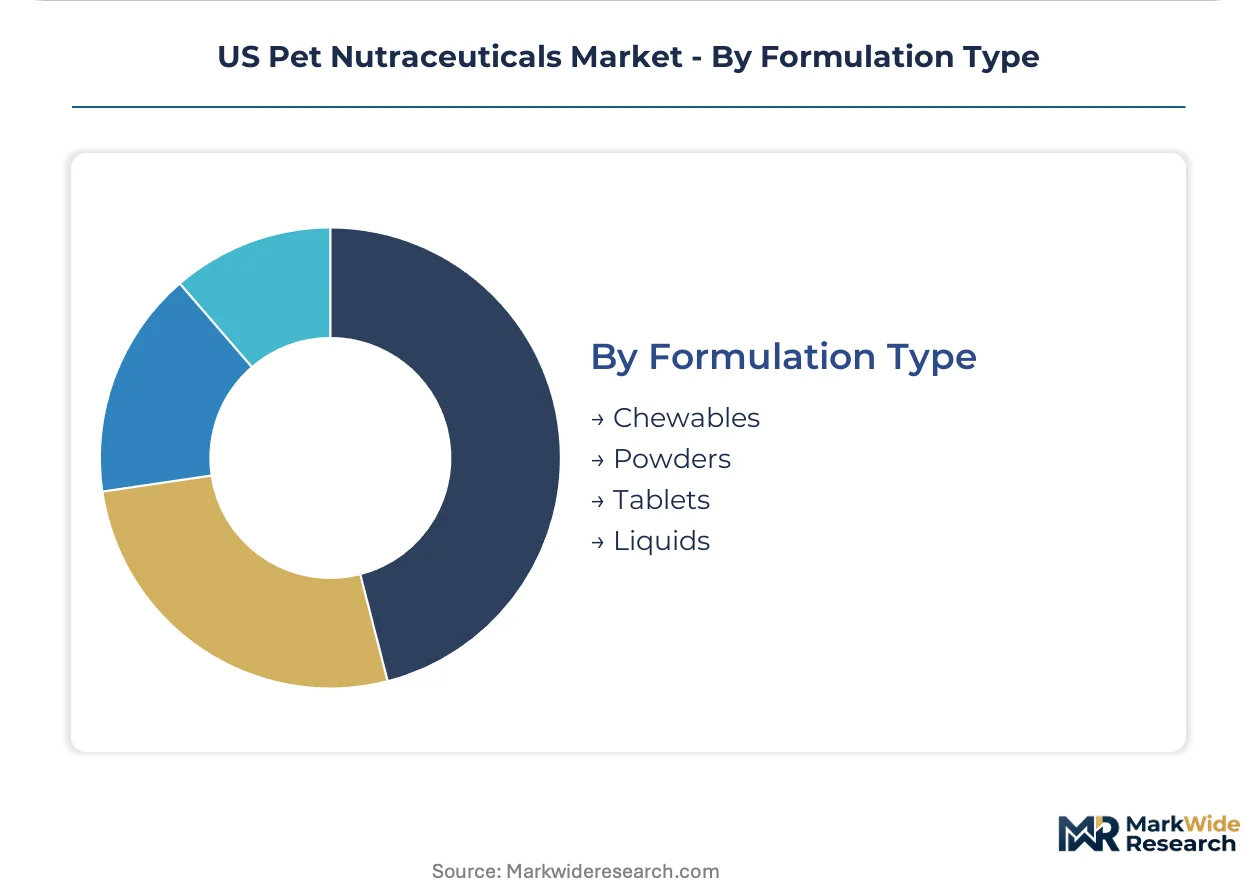
- Chewables:Cold-extruded matrices with thermolabile active protection and meat-flavored palatability engineering. Demand concentrates in direct-to-consumer subscription channels where dosing compliance drives retention metrics.
- Powders:Microencapsulated and free-flowing blends for food toppers and homemade diet supplementation. Expansion is climbing fastest in raw-feeding enthusiast communities in Pacific Northwest urban centers.
- Tablets:Compressed dosage forms with enteric coating for acid-sensitive actives.
- Liquids:Aqueous suspensions and oil-based solutions for precise titration.
Chewables dominate current manufacturing capacity. Powders are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Puget Sound processing corridor anchors domestic glucosamine and chondroitin sulfate production, with California and the Northeast corridor driving premium pet wellness expenditure above national benchmarks. Demand concentrates in coastal metropolitan zones where veterinary clinic density supports condition-specific supplement dispensing.
California
Los Angeles and San Francisco Bay Area households outspend national averages on premium pet wellness products, with specialty retail chains enforcing NASC certification requirements most aggressively. The California Veterinary Medical Board monitors veterinary pharmacy dispensing practices for supplement products. San Diego hosts contract manufacturing facilities serving direct-to-consumer brands with cold-chain probiotic preservation capabilities.
Northeast Corridor
New York Metro and Greater Boston veterinary clinics screen large-breed dogs for joint health at earlier ages, expanding preventive supplement protocols. State veterinary pharmacy boards in New York and Massachusetts maintain distinct channel restrictions for condition-specific products. Connecticut and New Jersey distribution hubs serve subscription-based replenishment models through Philadelphia and Newark logistics infrastructure.
Pacific Northwest
Seattle and Portland raw-feeding enthusiast communities drive powder formulation demand for homemade diet supplementation. Washington State Department of Agriculture oversees feed-grade manufacturing facility inspections. Tacoma and Everett processing plants concentrate marine-derived omega-3 refining capacity vulnerable to regional climate disruptions.
Texas
Dallas-Fort Worth and Houston suburban households purchasing through veterinary clinic loyalty programs absorb substantial canine supplement volume. The Texas State Board of Veterinary Medical Examiners influences non-prescription therapeutic product accessibility. Austin emerging as telehealth veterinary platform headquarters enabling direct-to-consumer brand partnerships.
Florida
Miami and Tampa metropolitan areas show accelerating feline supplement adoption as urban ownership rates exceed national averages. Florida Department of Agriculture and Consumer Services regulates pet food and supplement manufacturing permits. Orlando distribution infrastructure supports Southeast regional fulfillment for subscription auto-ship programs.
US Pet Nutraceuticals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue telehealth-enabled direct distribution bypassing traditional clinic gatekeepers. The market structure stratifies across three tiers: multinational consumer goods conglomerates with captive R&D infrastructure, veterinary-exclusive specialists leveraging prescription-adjacent positioning, and mass-market private label suppliers serving retail channel price competition. Dominant competitive moves include backward integration into omega fatty acid refining and strategic partnerships with telehealth veterinary platforms for recommendation-channel capture.
Within the conglomerate tier, Nestle Purina Petcare and Mars Incorporated exemplify scale-driven positioning through integrated supply chains and proprietary strain development. Nutramax Laboratories occupies the veterinary-exclusive specialist archetype, representing channel-bypass strategies that circumvent mass retail entirely. These three entities anchor the competitive spectrum from mass-market penetration to clinical-grade credibility positioning.
| Leading Market Players |
|---|
| Nestle Purina Petcare |
| Mars Incorporated |
| ADM |
| Nutramax Laboratories |
| Virbac |
| Vetoquinol |
| Zoetis |
| Diamond Pet Foods |
| Spectrum Brands |
| Others |
Pricing and Supply Chain Analysis
Backward integration into omega fatty acid refining anchors pricing power for multinational conglomerates while compressing margin capture for contract-dependent mid-tier manufacturers. Mars Incorporated's captive refining infrastructure insulates against marine-derived input volatility that erodes competitors' cost positions.
Pricing Analysis
Input-cost pass-through from wild-caught fish oil supply disruptions is compressing gross margins for EPA/DHA concentrates and forcing reformulation toward algal alternatives. Pricing stratifies across premium, standard, and economy tiers based on NASC certification status and veterinary-exclusive distribution access. Pricing pressure stems from aquaculture feed competition diverting marine biomass. Mass-market private label buyers exhibit highest price sensitivity; veterinary clinic channels demonstrate lowest.
Supply Chain Analysis
Freight costs for thermolabile probiotic preservation escalate as pharmaceutical-grade lyophilization capacity concentrates in human nutraceutical facilities with limited toll processing slots for animal health. Raw material sourcing draws from Puget Sound glucosamine-chondroitin clusters, Nordic marine oil refineries, and inland algal bioreactor facilities. Single-source vulnerability concentrates in Pacific Northwest processing infrastructure exposed to regional climate events. Distribution runs through veterinary clinic dispensing, specialty retail chains, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Center for Veterinary Medicine draft guidance on animal dietary supplement labeling is accelerating R&D investment and premium positioning.
For Market Incumbents: Anchor formulary inclusion through randomized controlled trial investment that satisfies veterinary teaching hospital evidence thresholds. Deepen NASC certification compliance to secure Petco and PetSmart placement. Counter telehealth-enabled direct-to-consumer entrants by launching proprietary online pharmacy platforms with competitive auto-ship pricing.
For New Entrants and Emerging Players: Enter via feline supplement whitespace where palatability-engineered paste formulations address approximately half the canine compliance rate. Target urban coastal markets with lickable bitter-masking products for obligate carnivore preferences. Pursue digital veterinary partnerships for prescription-adjacent recommendation capture.
For Investors and Strategic Acquirers: Roll-up economics work for veterinary-exclusive specialists with captive distribution channels because state veterinary pharmacy board fragmentation creates local moats. Five-to-ten year viability hinges on clinical credibility positioning. Target mid-tier manufacturers with cold-chain microencapsulation capabilities. Monitor harmonization of California, New York, and Texas non-prescription therapeutic standards as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Algal DHA production in controlled bioreactors reduces marine ecosystem dependency for omega-3 sourcing. |
| NASC Quality Seal Certification | Third-party audit compliance secures placement in Petco and PetSmart corporate-owned specialty retail locations. |
| Telehealth Platform Partnership | Digital veterinary recommendation channels bypass traditional clinic gatekeepers for direct-to-consumer capture. |
| Veterinary-Exclusive Distribution | Prescription-adjacent positioning through clinic dispensing commands premium pricing over mass retail. |
| Probiotic Strain Patent Development | Species-specific live microbial culture exclusivity differentiates from commodity supplement formulations. |
Research Methodology
Direct dialogue with veterinary nutrition specialists, FDA Center for Veterinary Medicine regulatory affairs leads, specialty retail category buyers, contract manufacturing facility managers, and telehealth veterinary platform executives grounded qualitative findings. Secondary validation drew from FDA guidance documents, AAFCO nutrient profile standards, National Animal Supplement Council audit protocols, and state veterinary pharmacy board filings. Bottom-up production capacity assessments and top-down expenditure pattern analysis were triangulated.
Bottom-up modeling tracked installed manufacturing capacity across cold-extrusion chewable lines, lyophilization preservation infrastructure, and microencapsulation equipment. Top-down validation assessed pet owner expenditure patterns by metropolitan zone. Segmentation dimensions included product type, application, animal species, and formulation format. CAGRs were derived from expenditure trend extrapolation moderated by regulatory timeline assumptions. Forecast inputs incorporated aging canine demographic projections and microbiome research translation velocity.
Inputs from regulatory filing databases and veterinary clinic dispensing records were available through the study window; gaps in telehealth platform transaction data introduce uncertainty bands around direct-to-consumer segment sizing. Forecasts reflect documented assumptions about FDA guidance finalization timelines and state-level harmonization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
US Collagen Market