
 US and China Glucose Market | 2026-2036
US and China Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
US and China Glucose Market Intelligence
A transition from single-source commodity procurement to multi-source contracts for specialized glucose grades is decoupling buyer relationships from single suppliers. Archer Daniels Midland Company leverages its extensive corn processing infrastructure in the US to supply high volumes. In contrast, Cargill, Incorporated competes by offering a diverse portfolio of sweeteners and starches to large food and beverage clients in both nations. Ingredion Incorporated specializes in value-added ingredients for specific functional applications.
Glucose is a monosaccharide, a simple sugar that serves as a fundamental energy source for biological organisms. Its commercial forms are often characterized by their Dextrose Equivalent (DE) value, which indicates the degree of starch hydrolysis. Within product types, dextrose remains a high-volume commodity, while high-fructose corn syrup faces scrutiny in the US market. The food & beverage end-user segment commands the largest share, but the pharmaceuticals segment offers higher margins for specific high-purity grades.
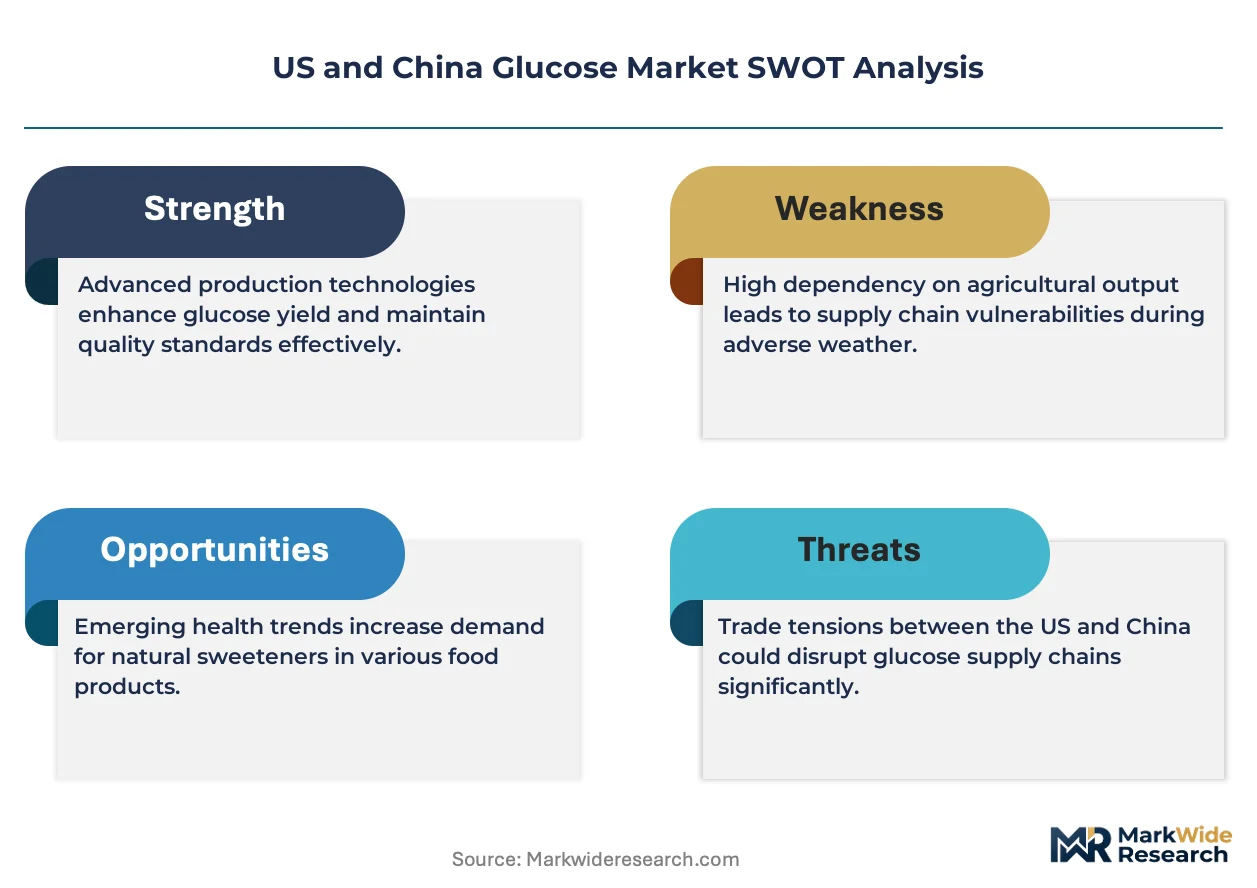
The US Food and Drug Administration (FDA) sets strict guidelines for ingredient labeling and Generally Recognized as Safe (GRAS) status. In China, national GB standards govern food additive specifications, creating distinct compliance pathways for market access in each country. Navigating the divergent consumer health trends and regulatory landscapes of the US and China will determine long-term profitability for glucose producers.
Market Dynamics
Divergent regulatory pathways and consumer health priorities in the United States and China represent the central force shaping the glucose market. Producers must navigate the FDA's labeling mandates in the US while aligning with China's state-driven health objectives.
Growth Catalysts
- Clean-Label Formulations:Demand from the US food and beverage industry for simple, recognizable ingredients is driving the substitution of complex additives with functional glucose syrups in products like baked goods, beverages, and dairy alternatives.
- China's Health Policy:The 'Healthy China 2030' plan encourages food manufacturers to reduce sugar content, creating a catalyst for lower-sweetness glucose variants and blends that help manage caloric density and glycemic response in processed foods.
- Pharmaceutical Grade Purity:The expanding biopharmaceutical sectors in both nations require high-purity liquid dextrose and other glucose forms as a critical carbohydrate source in cell culture media for producing biologics and vaccines.
Market Restraints
- Feedstock Price Volatility:The market is exposed to fluctuations in corn prices, a primary feedstock, which directly impacts production costs for major processors in the US Midwest and key agricultural provinces in China, compressing margins.
- Alternative Sweetener Substitution:The rise of natural, high-intensity sweeteners like stevia and monk fruit, along with polyols like erythritol, presents a significant substitution threat, particularly in beverages and health-focused food products.
- Regulatory Compliance Barriers:Navigating China's distinct GB standards for food additives and ingredients presents a compliance hurdle for US-based producers, requiring separate testing and documentation for market access compared to FDA requirements.
Strategic Opportunities
- Plant-Based Food Texturizers:Developing specialized glucose syrups that provide binding, browning, and texture in plant-based meat and dairy analogues offers a high-value application opportunity as consumer demand for these products grows in both countries.
- Bioprocessing Media Components:There is a significant opportunity to supply high-purity, low-endotoxin glucose to the burgeoning cell and gene therapy manufacturing hubs, which have stringent raw material specifications beyond standard food-grade products.
- Low-Glycemic Index Syrups:Formulating and marketing glucose products with a lower glycemic impact allows producers to appeal to health-conscious consumers and food manufacturers developing products for diabetic-friendly or weight management diets in the US.
Industry Challenges
- Dual Regulatory Navigation:Managing the separate and resource-intensive compliance pathways for the US FDA's GRAS notification system and China's State Administration for Market Regulation (SAMR) approval for food additives complicates product development and launch timelines.
- Capital-Intensive Infrastructure:The high capital expenditure needed to construct new corn wet-milling facilities or upgrade existing plants to produce specialized, value-added glucose grades presents a significant barrier to entry and expansion for smaller players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and China Glucose Market |
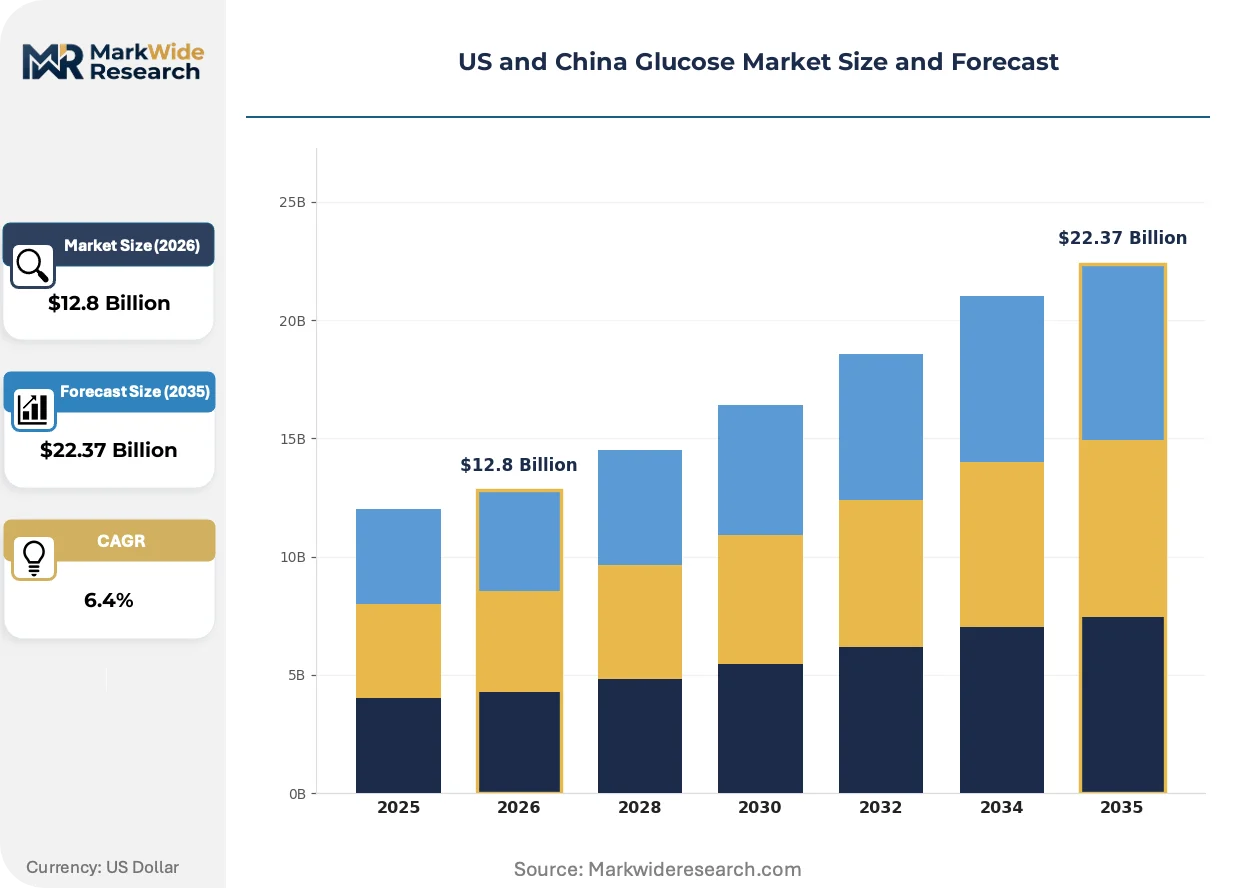
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dextrose, Fructose, Sucrose, Maltodextrin End User: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements Application: Baking, Confectionery, Beverages, Nutraceuticals Distribution Channel: Online, Wholesalers, Direct Sales, Retail |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Tereos S.A., AGRANA Beteiligungs-AG, Wilmar International Limited, Louis Dreyfus Holding B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and China Glucose Market Strategic Shifts & Innovations
A re-evaluation of carbohydrate functionality beyond simple sweetness is driving innovation across the US and China glucose markets. This shift prioritizes the textural, stability, and formulation benefits that specific glucose grades can provide in modern food and pharmaceutical systems.
Enzymatic modification technology enables the precise tailoring of glucose syrup characteristics, including viscosity, freezing point depression, and browning control. Food manufacturers in the confectionery and frozen dessert segments are increasingly adopting these custom syrups to improve product quality and stability. This targeted molecular control is converging with the demand for simplified ingredient lists, allowing glucose to replace other functional additives.
The US Food and Drug Administration's updated Nutrition Facts label, which mandates the declaration of 'Added Sugars,' is a significant regulatory driver. This rule pressures CPG companies to reformulate products to reduce their declared sugar content, directly impacting ingredient selection. High-fructose corn syrup faces the most scrutiny, prompting formulators to investigate lower-DE glucose syrups and alternative sweeteners to meet consumer and regulatory expectations.
Contractual arrangements are evolving from transactional, volume-based purchasing of commodity glucose to strategic, multi-supplier partnerships for specialized grades. Large food and beverage corporations are diversifying their supplier base to mitigate risk and access innovative ingredients, moving away from sole-source dependency on a single corn processor. This procurement trend is most visible among multinational firms managing complex supply chains across both the US and China.
US and China Glucose Market Segmentation
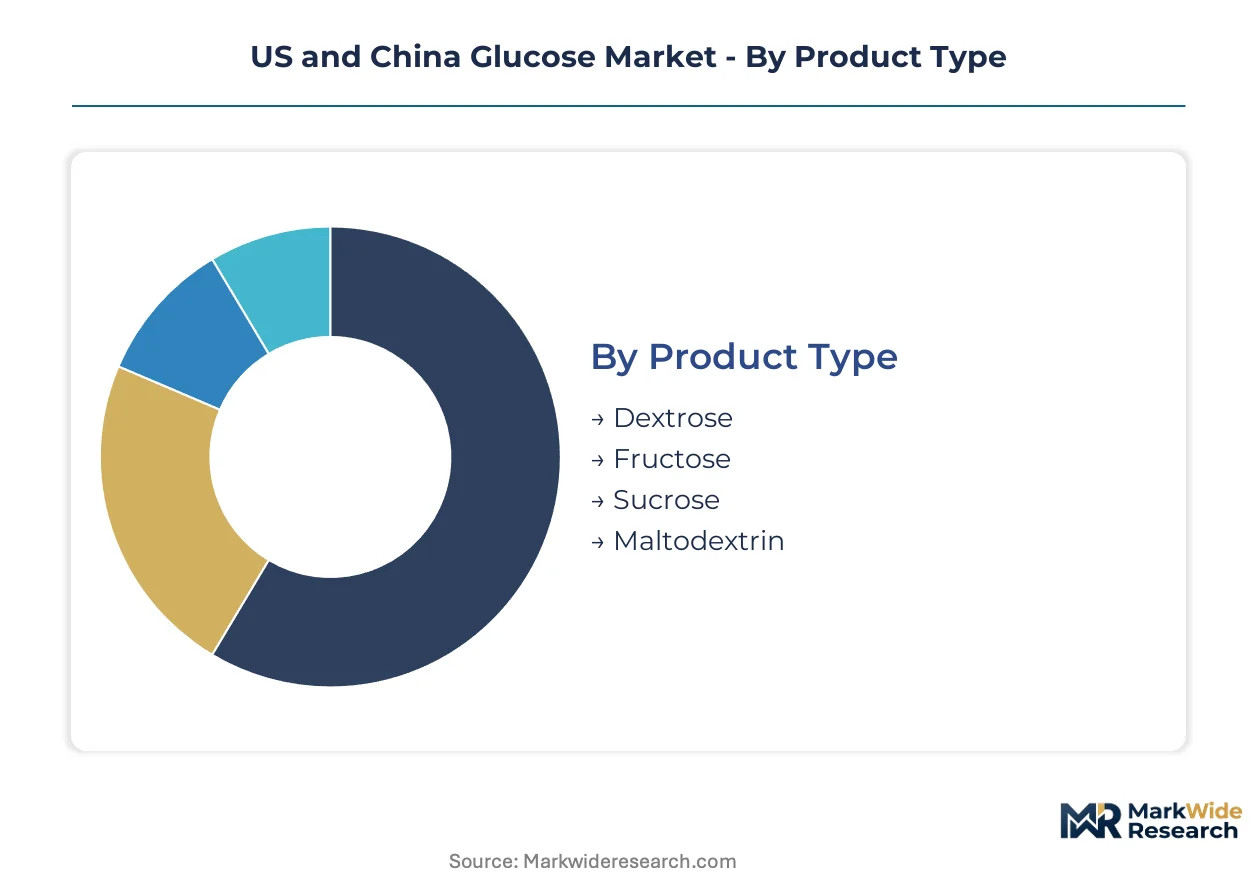
The US and China glucose market exhibits clear segmentation across product types, end-user industries, applications, and distribution channels. Understanding these distinct segments is crucial for producers to tailor product offerings and navigate the divergent regulatory and consumer landscapes in both countries. Each segment presents unique demand drivers and compliance requirements.
Product Type:
The production of various glucose types is highly concentrated among a few large corn processors in the US Midwest and China's agricultural regions.
- Dextrose:A monosaccharide, dextrose is the purest form of glucose, typically produced by enzymatic hydrolysis of starch. High-volume demand comes from the food and beverage sector in both the US and China for its direct sweetness and energy source properties.
- Maltodextrin:A polysaccharide derived from starch, maltodextrin has a low DE value, offering minimal sweetness but excellent bulking, thickening, and texturizing properties. Its demand is significant in clean-label formulations across both US and Chinese processed foods, particularly for dairy alternatives and snack products.
- Fructose:This monosaccharide, often as high-fructose corn syrup, faces regulatory and consumer scrutiny in the US market due to health concerns.
- Sucrose:A disaccharide composed of glucose and fructose, sucrose is a widely used table sugar, competing with glucose products in many sweetening applications.
Dextrose absorbs the bulk of installed capacity; maltodextrin is expanding most quickly.
End User:
The volume of glucose consumed varies significantly across different end-user industries in the US and China.
- Food & Beverage:This sector represents the largest consumer of glucose, utilizing it as a sweetener, texturizer, and bulking agent in a vast array of products. Demand is driven by consumer preferences for clean-label ingredients in the US and sugar reduction initiatives under China's 'Healthy China 2030' plan.
- Pharmaceuticals:The pharmaceutical industry requires high-purity glucose grades, particularly liquid dextrose, for applications in intravenous solutions, cell culture media, and excipients. Stringent purity requirements for biologics manufacturing in both US and Chinese biopharma hubs drive specific product development.
- Cosmetics:Glucose derivatives serve as humectants and emollients in cosmetic formulations, enhancing skin hydration and product texture.
- Dietary Supplements:Glucose and its derivatives function as binders, fillers, and energy sources in various tablet, powder, and liquid supplement formulations for US and Chinese consumers.
While the Food & Beverage sector drives overall volume, the Pharmaceuticals segment offers substantially higher margins due to specialized purity requirements.
Application:
The maturity of glucose applications varies, with some traditional uses well-established and others rapidly evolving.
- Baking:Glucose syrups provide moisture retention, browning, and fermentation benefits in various baked goods across US and Chinese markets.
- Confectionery:Glucose is essential in confectionery for controlling crystallization, adding body, and preventing sugar bloom in candies and chocolates.
- Beverages:Glucose is widely used in beverages as a sweetener, bodying agent, and fermentation substrate for alcoholic drinks. Reformulation efforts in the US to reduce 'Added Sugars' and China's focus on lower-sugar options are reshaping its use in this segment.
- Nutraceuticals:In nutraceuticals, specific glucose forms act as energy sources, excipients, or delivery vehicles for active compounds. The focus on health and wellness in both the US and China drives demand for specialized glucose in functional food and supplement products.
Baking and Confectionery represent foundational uses, while Beverages and Nutraceuticals are experiencing dynamic shifts driven by consumer health trends.
Distribution Channel:
The nature of the customer base dictates the preferred distribution channels for glucose products.
- Online:Online platforms facilitate procurement for smaller businesses and specialized ingredient buyers seeking niche glucose grades in both countries.
- Wholesalers:Wholesalers play a critical role in distributing bulk and specialty glucose products to a wide array of small to medium-sized food processors and industrial clients. These intermediaries manage logistics and inventory for regional markets in the US and provincial areas in China.
- Direct Sales:Large-volume glucose producers primarily utilize direct sales channels to serve major food and beverage corporations and pharmaceutical manufacturers. This approach allows for customized contracts and technical support, essential for complex supply chains in the US and China.
- Retail:Retail channels primarily cater to household consumers for small-pack glucose products, though this represents a minor portion of the overall industrial market.
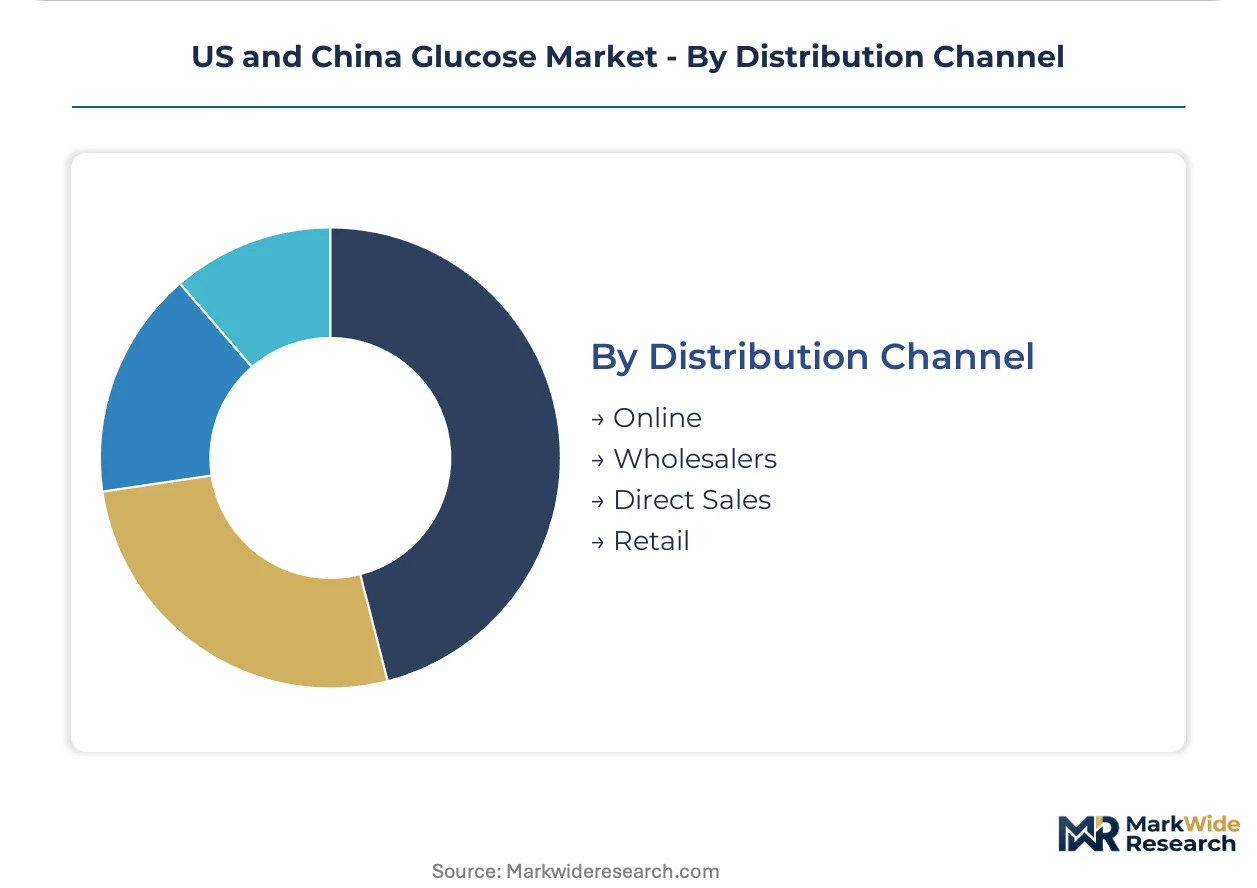
Direct Sales channels handle the largest industrial volumes, while Wholesalers provide essential market access for diverse regional customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn-producing regions in the US Midwest and China's agricultural heartlands anchor glucose market production. These areas supply diverse end-user segments, from food and beverage to high-purity pharmaceuticals. Regulatory frameworks in both nations shape product demand and market access.
US Midwest
Demand for clean-label ingredients drives glucose use in baked goods and dairy alternatives across the US Midwest. The US FDA's nutritional labeling mandates influence product reformulation efforts, favoring functional glucose syrups. Major food processing clusters across Illinois and Iowa concentrate significant glucose consumption and production capacity. This region remains a core hub for commodity glucose manufacturing.
US Northeast
The biopharmaceutical sector requires high-purity liquid dextrose for cell culture media and intravenous solutions. FDA's stringent purity requirements for biologics manufacturing shape specialized product development here. Pharmaceutical manufacturing hubs in Boston and New Jersey drive demand for these premium glucose grades. These specialized applications offer higher margins for producers.
China's Yangtze River Delta
Industrial food and beverage manufacturers require functional glucose syrups for diverse applications within this developed coastal region. China's 'Healthy China 2030' plan encourages sugar reduction in processed foods, impacting ingredient choices. Shanghai and Jiangsu provinces represent major food processing and biopharma hubs with high glucose consumption. This area also sees significant demand for specialized glucose in export-oriented products.
China's Shandong Peninsula
Food manufacturing and domestic consumer goods production create substantial glucose demand across the Shandong Peninsula. National GB standards govern food additive specifications, creating distinct compliance pathways for market access here. Shandong province's extensive corn processing facilities support a large glucose supply chain for both domestic and regional markets. This region is critical for high-volume commodity glucose supply.
US and China Glucose Market Key Industry Players
Global majors compete with regional champions across extensive corn processing infrastructure and diverse product portfolios, significantly influencing market dynamics. The US and China glucose market exhibits a tiered structure, with large, integrated players dominating commodity volumes and smaller firms focusing on niche, value-added applications. Three strategic archetypes include global agricultural processors, specialized ingredient manufacturers, and local distributors serving regional markets with tailored solutions. Capacity expansion, portfolio diversification into value-added grades, and strategic partnerships represent common competitive moves among these participants.
At the scale-driven end of the market, Archer Daniels Midland Company and Cargill, Incorporated exemplify global agricultural processors with extensive corn processing capabilities. These entities occupy a position of significant volume supply across both the US and China, anchoring commodity segments. Ingredion Incorporated, by contrast, represents a specialized ingredient manufacturer, focusing on value-added glucose derivatives for specific functional applications. This company sits within the tier catering to more specialized formulation needs. Such varied approaches highlight the diverse competitive strategies employed to serve distinct market segments.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Tereos S.A. |
| AGRANA Beteiligungs-AG |
| Wilmar International Limited |
| Louis Dreyfus Holding B.V. |
| Others |
Cost & Logistics Intelligence
Large food and beverage corporations in the US and China often negotiate long-term, contract-based pricing for commodity glucose grades, influencing overall market stability. This procurement strategy aims to mitigate feedstock price volatility while securing consistent supply for high-volume production needs.
Pricing Analysis
Service-level agreements for specialized glucose grades often unbundle technical support from the base product price, allowing for customized solutions. The dominant pricing model remains transactional for commodity volumes, shifting towards value-based contracts for high-purity pharmaceutical grades. Price differentiation stems from purity specifications and functional applications, alongside volume scale. Pricing pressure originates from volatile corn prices, compressing margins for processors. Pharmaceutical buyers exhibit the least price sensitivity due to stringent purity requirements, while bulk food and beverage manufacturers are highly sensitive to cost fluctuations.
Supply Chain Analysis
Logistics and freight costs significantly influence glucose pricing, particularly for bulk shipments from the US Midwest to coastal US food processing centers and from China's agricultural provinces to its coastal manufacturing hubs. Geographic supply concentration exists in the US Midwest and China's Shandong province, which are major corn-producing regions. The market draws from primary feedstock dependencies on corn. A structural risk involves the commodity price volatility of corn, directly impacting production costs. Distribution primarily runs through direct sales channels for large industrial volumes, supplemented by wholesalers serving regional and smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US and China glucose market presents a cost-of-compliance story, with the US FDA's stringent GRAS notification process creating a significant barrier-to-entry moat for established, compliant producers.
For Market Incumbents: Cement long-term supply agreements with major food and beverage clients to secure volume commitments amidst evolving procurement patterns. Diversify feedstock sourcing beyond corn or invest in advanced processing technologies to mitigate commodity price volatility. Invest in R&D for low-glycemic glucose variants to counter the threat of alternative sweeteners and align with health trends. Focus on expanding high-purity glucose capacity in regions with growing biopharmaceutical sectors.
For New Entrants and Emerging Players: China's 'Healthy China 2030' plan opens a window for specialized glucose producers to offer lower-sweetness variants and functional ingredients. Target niche applications such as plant-based food texturizers and bioprocessing media components, which demand high-value, specialized grades. The most penetrable segment lies within value-added ingredients for specific functional applications. A strong go-to-market angle involves providing extensive technical support and formulation expertise to food manufacturers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated corn processors in the US Midwest, seeking to acquire existing infrastructure at favorable valuations. The long-term viability of the glucose market is anchored by its fundamental role as an energy source and functional ingredient across diverse industries. Acquisition targets should be specialized ingredient manufacturers with proprietary enzymatic modification technologies. A key signal to watch is sustained feedstock price stability, which improves operational predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US Midwest | Increases supply of commodity glucose for food processing clusters in Illinois and Iowa. |
| R&D for Low-Glycemic Syrups | Addresses consumer health trends and regulatory pressure for reduced sugar content in US and China. |
| Investment in Bioprocessing Grade Glucose | Supports the expanding biopharmaceutical sectors in the US Northeast and China's Yangtze River Delta. |
| Multi-Source Procurement Strategy | Mitigates supply chain risks and reduces dependency on single suppliers for large food and beverage clients. |
| Compliance with China's GB Standards | Secures market access and ensures product acceptance for specialized glucose grades in China's domestic market. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. Primary research involved in-depth interviews with food technologists, pharmaceutical procurement managers, corn wet-milling plant operators, and ingredient distributors in both the US and China. This process combined bottom-up data collection with top-down market validation, ensuring comprehensive coverage.
Market sizing and forecasts were modeled at granular levels across product types, end-user segments, and key regional hubs in the US and China. Segmentation dimensions included dextrose, maltodextrin, food & beverage, pharmaceuticals, US Midwest, and Yangtze River Delta. Compound Annual Growth Rates were derived from historical data analysis and expert consensus over the projection horizon. Key industry-specific forecast inputs included corn price forecasts and biopharmaceutical R&D spending trends.
The model assumes a particular technology adoption path; alternative pathways for enzymatic modification of starch would alter the outlook for specialized glucose grades. Forecasts reflect assumptions regarding regulatory stability and consumer health trend persistence. Unforeseen trade policy shifts or rapid adoption of novel alternative sweeteners represent risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Piracetam Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Magtein Market
Nutraceuticals
North America Effervescent Tablet Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Ayurvedic Products Market