
 Ayurvedic Products Market | 2026-2036
Ayurvedic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Ayurvedic Products Market Analysis
Indian herb cultivation regions are pivoting toward certified organic farming to secure export-grade raw material pipelines. Dabur Ltd. leverages its integrated supply chain from Himalayan foothill gardens to metropolitan retail shelves. Patanjali Ayurved Limited anchors mass-market penetration through its sprawling franchise network across Indian tier-two cities. Himalaya Wellness Company differentiates via pharmaceutical-grade extraction protocols that satisfy stringent Western market entry requirements.
Ayurvedic products comprise botanical formulations derived from herbs, minerals, and metals processed through traditional decoction, fermentation, or oil-infusion methods standardized by pharmacopeial assays. These preparations serve therapeutic, prophylactic, and cosmetic functions rooted in tridosha constitutional theory. Herbal Supplements command the largest revenue pool due to chronic-disease self-management trends among aging populations. Skin Care represents the fastest-expanding category as clean-beauty consumers reject synthetic actives in favor of neem, turmeric, and sandalwood derivatives. Essential Oils concentrate margin capture through aromatherapy diffusion in spa and hospitality channels.
India's CDSCO mandates Ayurvedic drug licensing under the Drugs and Cosmetics Act while the country's BIS certifies product quality through IS standards for herbal raw materials. The EU Green Deal's deforestation-free supply chain requirements are reshaping import documentation for Indian botanical exporters. WHO's Traditional Medicine Strategy provides harmonization frameworks that reduce technical barriers to cross-border Ayurvedic commerce. Stakeholders must monitor evolving pharmacovigilance obligations in target jurisdictions before committing to capacity expansion.
Market Dynamics
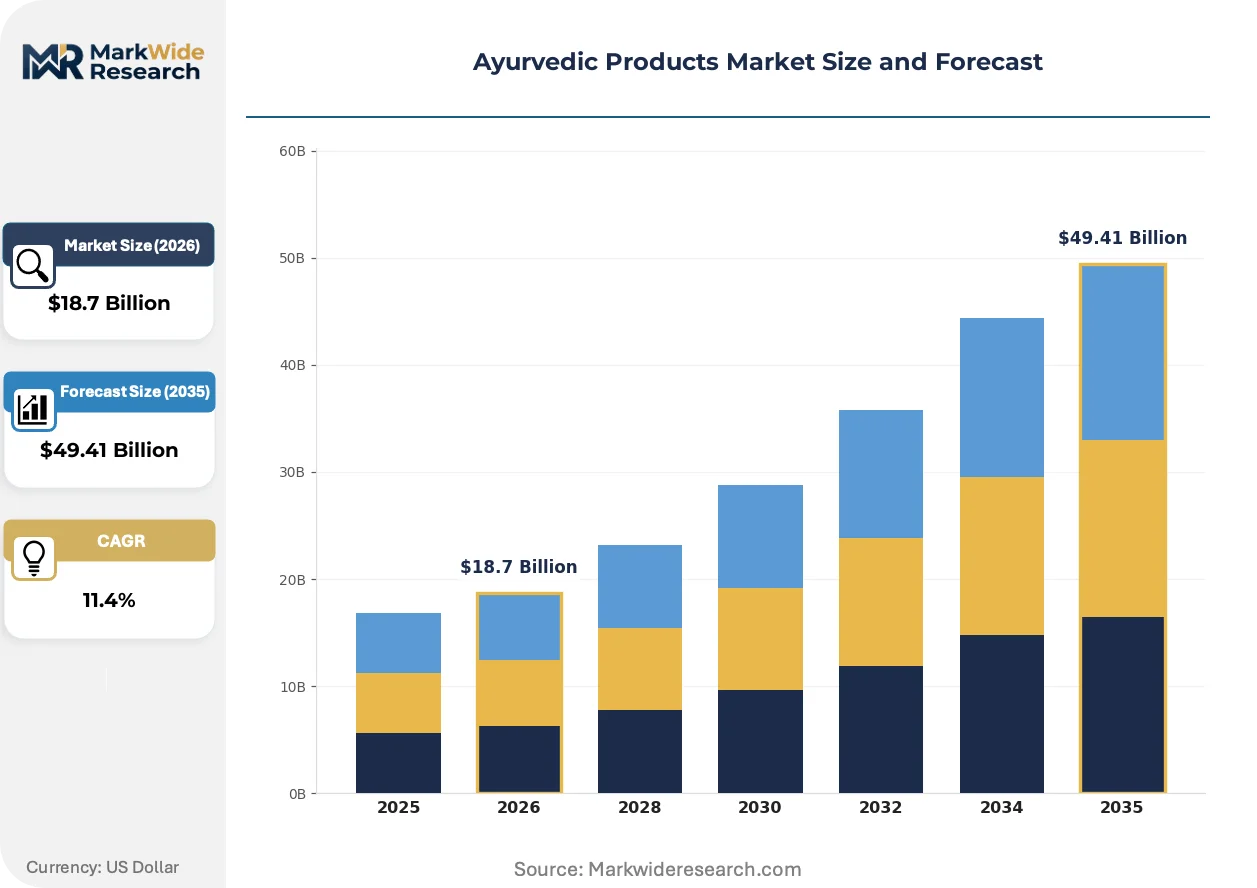
India's PLI scheme for herbal manufacturing is accelerating domestic production capacity while EU Green Deal deforestation-free requirements reshape import documentation for Indian botanical exporters. This regulatory friction between incentive-driven supply expansion and compliance-heavy market access defines current competitive positioning.
Growth Catalysts
- Ayurvedic service expansion:Wellness centers across Germany and the United States are adding panchakarma and herbal therapy menus to capture clean-beauty consumer spending.
- CDSCO licensing harmonization:India's Drugs and Cosmetics Act standardization enables faster export clearance for GMP-certified manufacturers targeting Western pharmacopeial markets.
- Kerala-Uttarakhand cluster concentration:Traditional medicine cultivation hubs supply certified organic raw botanicals to global formulators seeking traceable supply chains.
Market Restraints
- Raw material volatility:Wild-crafted herb availability fluctuates with monsoon patterns across the Western Ghats, forcing contract price renegotiations.
- Extraction technology gaps:Small-batch manufacturers lack pharmaceutical-grade extraction infrastructure required for EMA and FDA botanical drug submissions.
- EU documentation burden:Deforestation-free supply chain certification adds 12-18 month lead times for first-time Indian exporters.
Strategic Opportunities
- Spa-hospitality channel penetration:Aromatherapy diffusion in Dubai and Singapore luxury properties captures margin-rich essential oil volumes.
- BIS-ISO convergence:Dual certification protocols enable simultaneous domestic and export market qualification, reducing duplicate testing costs.
- Aging population self-management:Chronic disease prevention positioning for herbal supplements targets Medicare-adjacent demographics in North American direct-to-consumer channels.
Industry Challenges
- Pharmacovigilance capability gaps:Post-market adverse event reporting systems remain underdeveloped among mid-tier Ayurvedic manufacturers.
- Tridosha standardization delays:Constitutional diagnostic protocols resist ISO harmonization, complicating multinational clinical trial design.
- Legacy distribution reconfiguration:Franchise-dependent networks in Indian tier-two cities struggle to integrate e-commerce fulfillment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ayurvedic Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Essential Oils, Skin Care, Hair Care Application: Personal Care, Nutritional Supplements, Health Remedies, Wellness End User: Individuals, Healthcare Practitioners, Wellness Centers, Retailers Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Emami Ltd., Vicco Laboratories, Dabur Ltd., Amrutanjan Health Care Limited, Kerala Ayurveda Ltd., Patanjali Ayurved Limited, Baidyanath, Hamdard India, Himalaya Wellness Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ayurvedic Products Market Emerging Trajectories
Clean-label extraction technologies and pharmacopeial-grade standardization are compressing the gap between traditional preparation methods and Western regulatory acceptance. These shifts are rewriting how Ayurvedic products qualify for pharmacy and professional channel placement.
Supercritical CO2 extraction of ashwagandha and turmeric actives is rewriting purity benchmarks for botanical supplements. Pharmaceutical contract manufacturers in India are adopting this solvent-free technology to satisfy USP-NF monograph requirements. The shift is compressing traditional solvent-based extraction margins while enabling entry into professional healthcare channels previously closed to Ayurvedic suppliers.
EU Green Deal deforestation-free supply chain mandates are forcing documentation system overhauls across Indian botanical exporters. EUDR compliance requires geolocation tagging of every herb harvest back to specific farm plots in Kerala and Uttarakhand. Smallholder cooperatives are responding by deploying blockchain-traceable collection networks to satisfy European importer audit protocols.
Direct-to-practitioner sampling models are displacing traditional retail pharmacy stocking for professional-grade Ayurvedic lines. Integrative medicine clinics in California and New York now source standardized extracts through specialized B2B portals rather than conventional distributors. This channel pivot concentrates volume with manufacturers capable of lot-specific certificate-of-analysis documentation.
Ayurvedic Products Market Segmentation
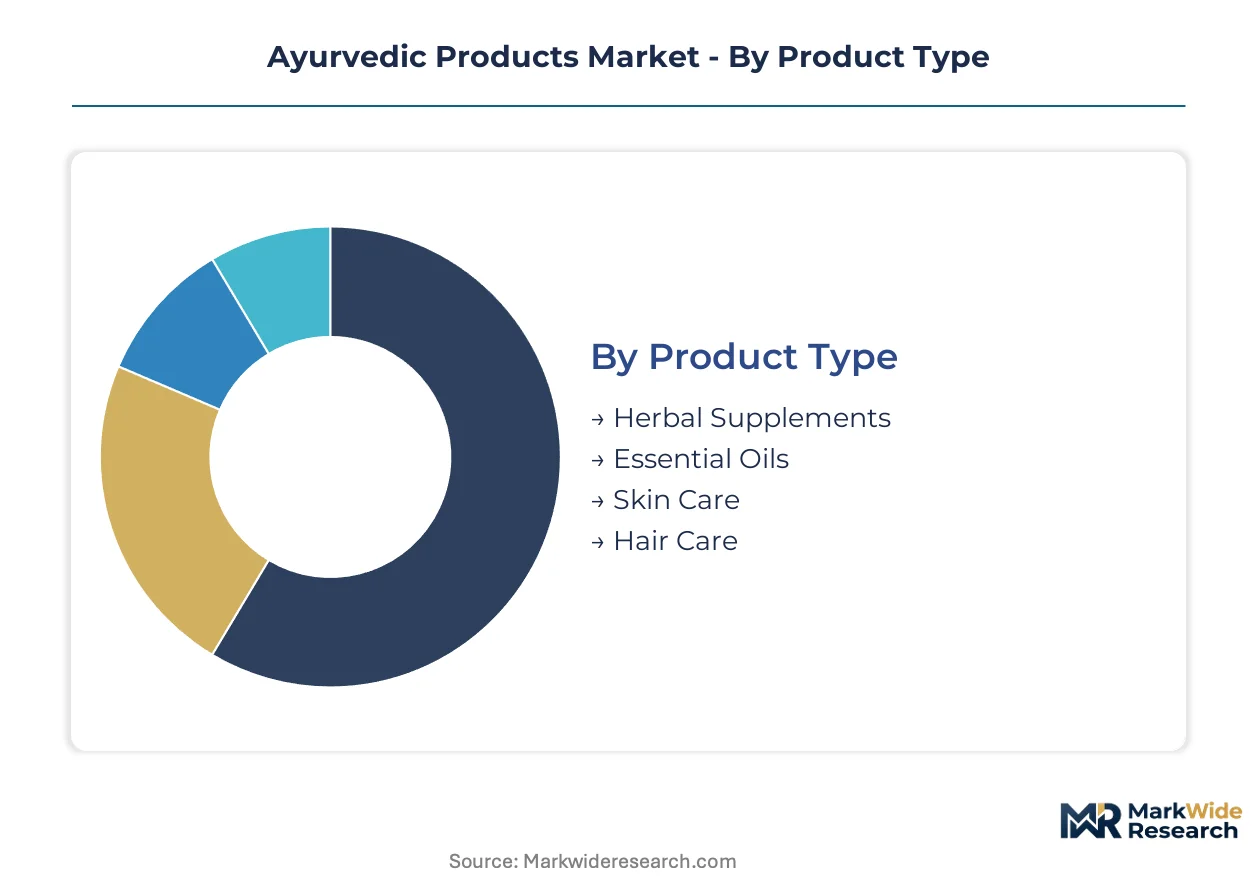
Regulatory pathways fragment the Ayurvedic Products Market across distinct compliance burdens. Product-type certification requirements determine export eligibility and channel access, while application-specific positioning shapes reimbursement and professional adoption trajectories.
Product Type:
CDSCO drug licensing applies to formulations with therapeutic claims, while FSSAI food safety certification governs nutritional positioning. EMA botanical drug pathways demand pharmaceutical-grade extraction documentation for European pharmacy placement.
- Herbal Supplements:Standardized extracts of ashwagandha, turmeric, and triphala delivered in capsule or tablet matrices. Demand concentrates in North American direct-to-consumer channels where aging populations self-manage metabolic and cognitive health, though USP-NF monograph compliance raises manufacturing barriers for mid-tier suppliers.
- Skin Care:Topical formulations leveraging neem, sandalwood, and saffron actives through oil-infusion or aqueous extraction methods. Kerala-based manufacturers supply clean-beauty formulators in Germany and France seeking EUDR-compliant botanical traceability, with EU Green Deal documentation requirements extending procurement cycles.
- Essential Oils:Steam-distilled or CO2-extracted volatile compounds for aromatherapy diffusion.
- Hair Care:Oil-based treatments and herbal cleansers rooted in traditional decoction protocols.
Leading the category by volume: Herbal Supplements. Growing fastest: Skin Care.
Application:
Cost tier stratification separates premium professional-grade lines from mass-market retail positioning, with certification depth determining price band placement.
- Personal Care:Daily-use cosmetic formulations including cleansers, moisturizers, and hair treatments. Mass-market penetration dominates Indian tier-two cities through franchise networks, while premium positioning targets Dubai and Singapore spa-hospitality channels.
- Nutritional Supplements:Preventive health formulations standardized for active constituent content. Medicare-adjacent demographics in the United States drive chronic-disease self-management positioning, requiring FDA dietary supplement notification compliance.
- Health Remedies:Condition-specific therapeutic preparations.
- Wellness:Panchakarma and constitutional balancing protocols delivered through service channels.
Personal Care commands the widest distribution footprint. Nutritional Supplements are gaining share fastest through practitioner-direct sampling models.
End User:
Customer sophistication determines documentation requirements, with professional channels demanding lot-specific certificate-of-analysis while individual consumers prioritize brand recognition.
- Individuals:Direct purchasers through e-commerce and retail channels.
- Healthcare Practitioners:Integrative medicine clinicians in California and New York sourcing standardized extracts through specialized B2B portals rather than conventional distributors, with lot-level traceability mandatory for inventory acceptance.
- Wellness Centers:German and United States facilities expanding panchakarma and herbal therapy menus to capture clean-beauty consumer spending, requiring bulk supply contracts with GMP-certified manufacturers.
- Retailers:Pharmacy chains and health stores curating shelf placement.
Individuals generate the highest transaction volume. Wellness Centers show the steepest expansion trajectory as service-based Ayurvedic penetration deepens in Western markets.
Distribution Channel:
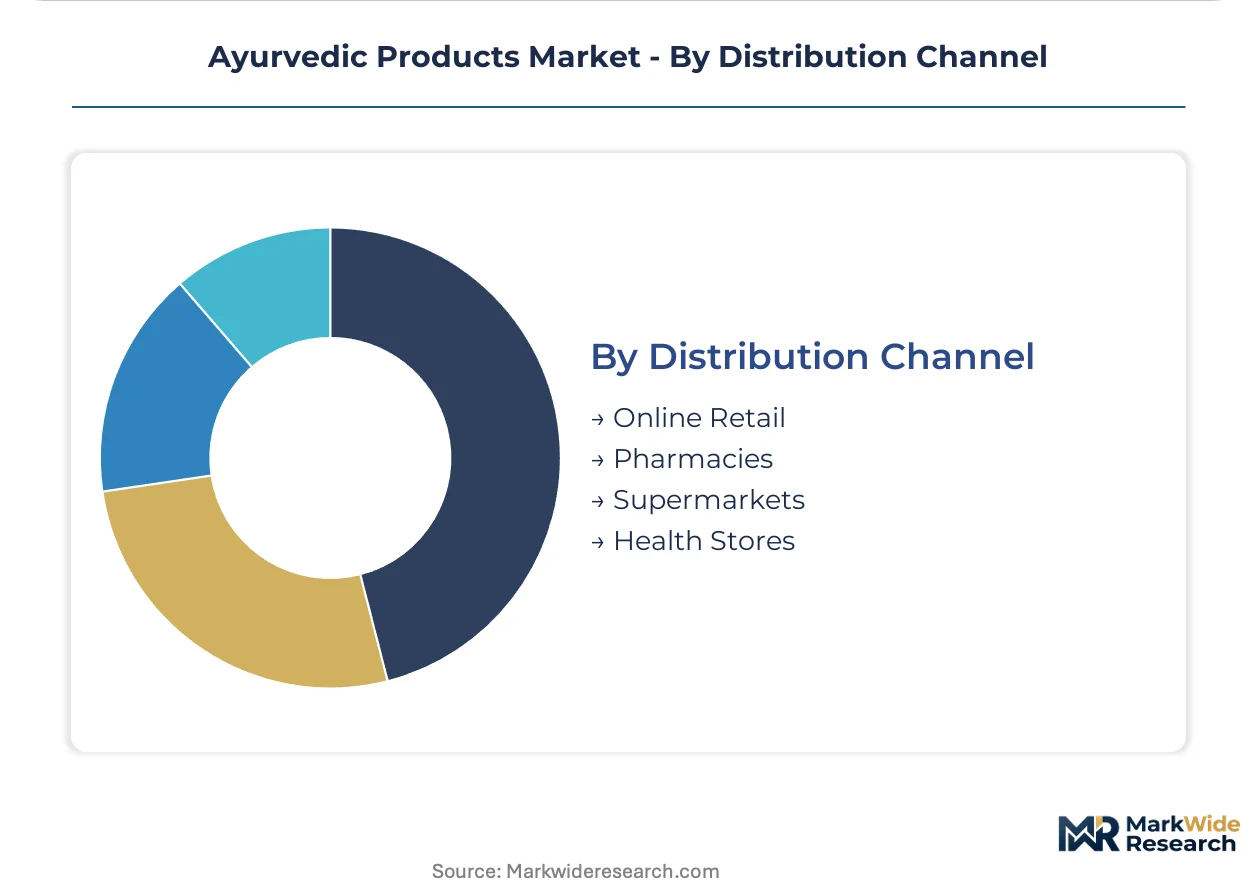
Channel selection dictates margin capture and regulatory exposure, with pharmacy placement requiring the most stringent pharmacovigilance infrastructure.
- Online Retail:Direct-to-consumer platforms and marketplace presence.
- Pharmacies:Professional healthcare channel placement requiring adverse event reporting systems and drug licensing compliance, with CDSCO harmonization enabling faster export clearance for qualified Indian manufacturers.
- Supermarkets:Mass-market food and drug retail positioning.
- Health Stores:Specialty natural products retail with educated consumer base.
Online Retail leads transaction volume through pandemic-accelerated habit formation. Pharmacies represent the highest-margin placement for certified manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala's spice gardens and Uttarakhand's alpine meadows anchor raw material pipelines for Ayurvedic manufacturing. These cultivation clusters supply certified organic botanicals to formulators across three continents. Regulatory divergence between India's PLI incentives and EU Green Deal compliance requirements is fragmenting export pathways.
India
Kerala and Uttarakhand cultivation belts supply ashwagandha, turmeric, and triphala to global extractors. CDSCO licensing under the Drugs and Cosmetics Act standardizes domestic manufacturing while BIS certifies raw material quality through IS standards. Mumbai and Delhi-NCR house GMP-certified contract manufacturers serving North American and European importers.
United States
Integrative medicine clinics in California and New York drive practitioner-direct demand for standardized herbal extracts. FDA dietary supplement notification requirements govern import clearance for Indian manufacturers. Wellness centers across Texas and Florida are expanding panchakarma service menus to capture clean-beauty consumer spending.
Germany
EMA botanical drug pathways demand pharmaceutical-grade extraction documentation for pharmacy placement. EU Green Deal deforestation-free supply chain mandates force 12-18 month lead times for first-time Indian exporters. Hamburg and Frankfurt serve as import gateways for Kerala-sourced essential oils targeting spa-hospitality channels.
United Arab Emirates
Dubai luxury properties capture margin-rich aromatherapy volumes through essential oil diffusion contracts. MOHAP registration requirements govern Ayurvedic therapeutic product importation. The city's free zone infrastructure enables Indian manufacturers to establish regional distribution hubs serving Saudi Arabia and Qatar markets.
Singapore
Specialized B2B portals connect Indian GMP-certified manufacturers with Southeast Asian integrative medicine practitioners. HSA regulatory frameworks require adverse event reporting systems for pharmacy-channel placement. The port city's logistics infrastructure compresses shipment times for Kerala-sourced botanical raw materials.
Ayurvedic Products Market Vendor Landscape
Global majors compete with regional champions across certification depth and supply chain control. The vendor base stratifies into three tiers: integrated Himalayan cultivator-manufacturers, mass-market franchise operators, and pharmaceutical-grade extraction specialists. Consolidation pressure concentrates among mid-tier players lacking EMA or FDA submission capabilities. Dominant competitive moves include backward integration into certified organic cultivation and strategic partnerships with Dubai and Singapore hospitality distributors.
Among India-based integrated operators, Dabur Ltd. and Patanjali Ayurved Limited exemplify contrasting scale strategies. Dabur occupies a position anchored in Himalayan foothill supply chains and metropolitan retail penetration. Patanjali represents mass-market franchise density across tier-two cities. Himalaya Wellness Company sits within the pharmaceutical-grade tier, satisfying USP-NF monograph requirements for Western professional channels.
| Leading Market Players |
|---|
| Emami Ltd. |
| Vicco Laboratories |
| Dabur Ltd. |
| Amrutanjan Health Care Limited |
| Kerala Ayurveda Ltd. |
| Patanjali Ayurved Limited |
| Baidyanath |
| Hamdard India |
| Himalaya Wellness Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal deforestation-free mandates gate qualified supply access and premium-tier pricing eligibility for Ayurvedic exporters, forcing documentation investments that stratify manufacturers into compliance tiers with corresponding margin bands. Buyers in Germany and the United States pay extraction-grade premiums only to suppliers with blockchain-traceable Kerala and Uttarakhand sourcing.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade extract pricing from commodity herb trading, with USP-NF monograph compliance commanding substantial premia over FSSAI-certified alternatives. Price differentiation rests on certification depth and volume scale, with small-batch wild-crafted botanicals facing cost compression from standardized greenhouse cultivation. Pricing pressure intensifies in mass-market personal care tiers as Patanjali's franchise density forces margin concessions. Direct-to-practitioner channels show lowest price sensitivity due to clinical efficacy requirements.
Supply Chain Analysis
BIS-ISO dual certification gates participation in Western professional channels, filtering out mid-tier Indian manufacturers lacking pharmaceutical-grade extraction infrastructure. Cultivation concentrates in India, with raw material dependencies on ashwagandha root, turmeric rhizome, and triphala fruit harvested across monsoon-dependent Western Ghats belts. Single-source vulnerability runs through wild-crafted herb availability disrupted by rainfall variability. Distribution runs through Mumbai and Delhi-NCR contract manufacturers serving North American and European importers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Green Deal documentation requirements erect barrier-to-entry moats favoring certified incumbents with capitalized traceability systems.
For Market Incumbents: Acquire blockchain-traceable collection networks in Kerala and Uttarakhand to secure deforestation-free supply chain credentials before EUDR enforcement tightens. CDSCO licensing harmonization enables faster export clearance for GMP-certified manufacturers targeting EMA botanical drug pathways. Patenting supercritical CO2 extraction protocols for ashwagandha and turmeric actives locks in pharmaceutical-grade positioning against solvent-based competitors. For New Entrants and Emerging Players: Enter via Dubai and Singapore spa-hospitality channels where essential oil diffusion contracts capture margin-rich volumes with lower certification burdens than pharmacy placement. North American integrative medicine clinics present the most penetrable white-space for practitioner-direct sampling models. Specialized B2B portals serving California and New York clinicians offer a go-to-market angle bypassing conventional distributor markups. For Investors and Strategic Acquirers: First-time Indian exporters securing EUDR compliance within 12-18 month lead times is the leading indicator that premium-tier market access is achievable and sustainable. Acquisition targets should profile as mid-tier manufacturers with GMP infrastructure but lacking EMA submission capabilities, where compliance investment unlocks professional channel expansion. Watch for CDSCO export clearance acceleration signals as inflection indicators of regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Cultivation | Himalayan foothill garden control secures export-grade raw material pipelines for USP-NF compliance. |
| Supercritical CO2 Extraction Technology Adoption | Solvent-free active recovery satisfies EMA botanical drug purity benchmarks for pharmacy placement. |
| Blockchain-Traceable Collection Network Deployment | Geolocation tagging of Kerala and Uttarakhand harvests satisfies EU Green Deal audit protocols. |
| Direct-to-Practitioner B2B Portal Launch | Lot-specific certificate-of-analysis documentation captures integrative medicine clinic volume in California. |
| Dubai Free Zone Distribution Hub Establishment | MOHAP-registered regional infrastructure serves Saudi Arabia and Qatar spa-hospitality channels. |
Methodological Framework
Multi-period observation of CDSCO licensing timelines, EUDR compliance completion rates, and Kerala-Uttarakhand cultivation yields anchored the trend analysis, supplemented by interviews with Ayurvedic drug development executives, regulatory affairs leads at Indian GMP-certified manufacturers, formulary directors at German pharmacy chains, and wellness center procurement managers in Dubai and Singapore. Secondary validation drew from FDA dietary supplement notification databases, EMA botanical drug submission records, EU Green Deal implementation guidance, and BIS certification registries. Bottom-up volume aggregation across product-type and application segments triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed value and volume across herbal supplements, skin care, essential oils, and hair care product types, further disaggregated by personal care, nutritional supplements, health remedies, and wellness applications. End-user stratification captured individual consumers, healthcare practitioners, wellness centers, and retailer channels with corresponding distribution channel overlays. CAGRs were derived from regression analysis of historical certification penetration rates and projected professional channel adoption curves, incorporating monsoon pattern volatility effects on wild-crafted herb pricing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Green Deal enforcement acceleration or CDSCO export clearance protocol changes. Model assumptions reflect documented regulatory pathway timelines, cultivation yield sensitivities, and professional channel reimbursement dynamics. A model refresh is warranted upon material change in EUDR documentation requirements or PLI scheme herbal manufacturing incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Magtein Market
Nutraceuticals
Cissus Quadrangularis Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Nootropics Market