
 Anti Aging Agent Market | 2026-2036
Anti Aging Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Aging Agent Market Insights
Prestige dermatology channels are reorganizing procurement priorities for anti-aging actives, shifting volume toward clinic-dispensed and physician-backed formulations. DSM-Firmenich leverages its integrated biotechnology platform to secure peptide supply chains for professional skincare lines. Croda anchors its position through lipid-active delivery systems that improve retinoid stability in high-potency serums. Givaudan competes via specialized botanical extraction capabilities that serve clean-label antioxidant demand in European and North American markets.
Anti-aging agents comprise biologically active compounds—retinol derivatives, signal peptides, polyphenolic antioxidants, and recombinant growth factors—engineered to modulate collagen synthesis, cellular turnover, or oxidative stress markers in human skin. These substances typically require encapsulation in liposomal or nanoemulsion matrices to maintain efficacy at concentrations between 0.1% and 2.0% by formulation weight. Antioxidant segments now command margin pools as consumers prioritize photodamage prevention alongside correction, while peptide applications in haircare represent the fastest-expanding use case beyond traditional facial skincare. Retinoid formulations sustain dominance in prescription-adjacent channels where clinical validation supports premium positioning.
FDA oversight of cosmeceutical claims in the United States restricts how anti-aging benefits appear on packaging, pushing brands toward substantiated clinical testing. REACH and the EU Cosmetics Regulation in Europe mandate exhaustive safety dossiers for novel peptide introductions, elevating compliance costs for smaller suppliers. Stakeholders must monitor evolving classification boundaries between cosmetics and drugs across major jurisdictions, as regulatory reclassification would reshape market access requirements and reformulation timelines.
Market Dynamics
Dermatology clinics and medical spas now command procurement priority over traditional cosmetic brands, forcing ingredient suppliers to restructure distribution toward physician-backed channels with validated clinical dossiers.
Growth Catalysts
- Clinic-dispensed channel expansion:Physician-backed formulations now outpace retail growth as dermatology practices vertically integrate skincare dispensing. Medical spas in the United States drive peptide uptake through supervised treatment protocols.
- Photodamage prevention priority:Consumer preference pivots from correction to prevention, elevating antioxidant actives in premium positioning. Polyphenolic formulations gain traction alongside retinoid maintenance regimens.
- REACH-compliant peptide sourcing:European formulators invest in verified supply chains to meet EU Cosmetics Regulation safety dossier requirements. Verified sourcing becomes a procurement discriminator for professional skincare lines.
Market Restraints
- Retinoid stability costs:Liposomal encapsulation and nanoemulsion matrices add 15-25% to formulation input costs. High-potency serums require cold-chain logistics that constrain geographic reach.
- Regulatory friction from FDA claims oversight:United States packaging restrictions on cosmeceutical benefits force expensive clinical substantiation. Smaller brands lack capital for trial design and statistical validation.
- Peptide supplier concentration:Biotechnology platforms capable of recombinant growth factor production cluster in Switzerland and the Netherlands. Single-source dependencies create vulnerability for mid-tier formulators.
Strategic Opportunities
- Haircare peptide applications:Signal peptides represent the fastest-expanding use case beyond facial skincare. Scalp treatment protocols in medical spas open new volume channels.
- Clean-label antioxidant demand:Specialized botanical extraction capabilities serve European and North American markets seeking polyphenolic alternatives to synthetic actives. Givaudan and comparable suppliers capture margin through verified origin claims.
- Professional channel disintermediation:Direct procurement relationships between dermatology clinics and ingredient suppliers bypass traditional cosmetic brand markups. DSM-Firmenich and Croda establish captive supply agreements with clinic networks.
Industry Challenges
- Clinical trial design expertise:Formulators lack in-house biostatisticians to design studies meeting FDA substantiation standards. Contract research organization costs compress margins for mid-market players.
- Encapsulation technology integration:Legacy manufacturing lines require retrofitting for liposomal and nanoemulsion production. Capex intensity favors suppliers with existing biotechnology infrastructure.
- Regulatory classification ambiguity:Evolving boundaries between cosmetics and drugs across the United States and Europe create reformulation risk. Stakeholders must monitor reclassification proceedings in multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Aging Agent Market |
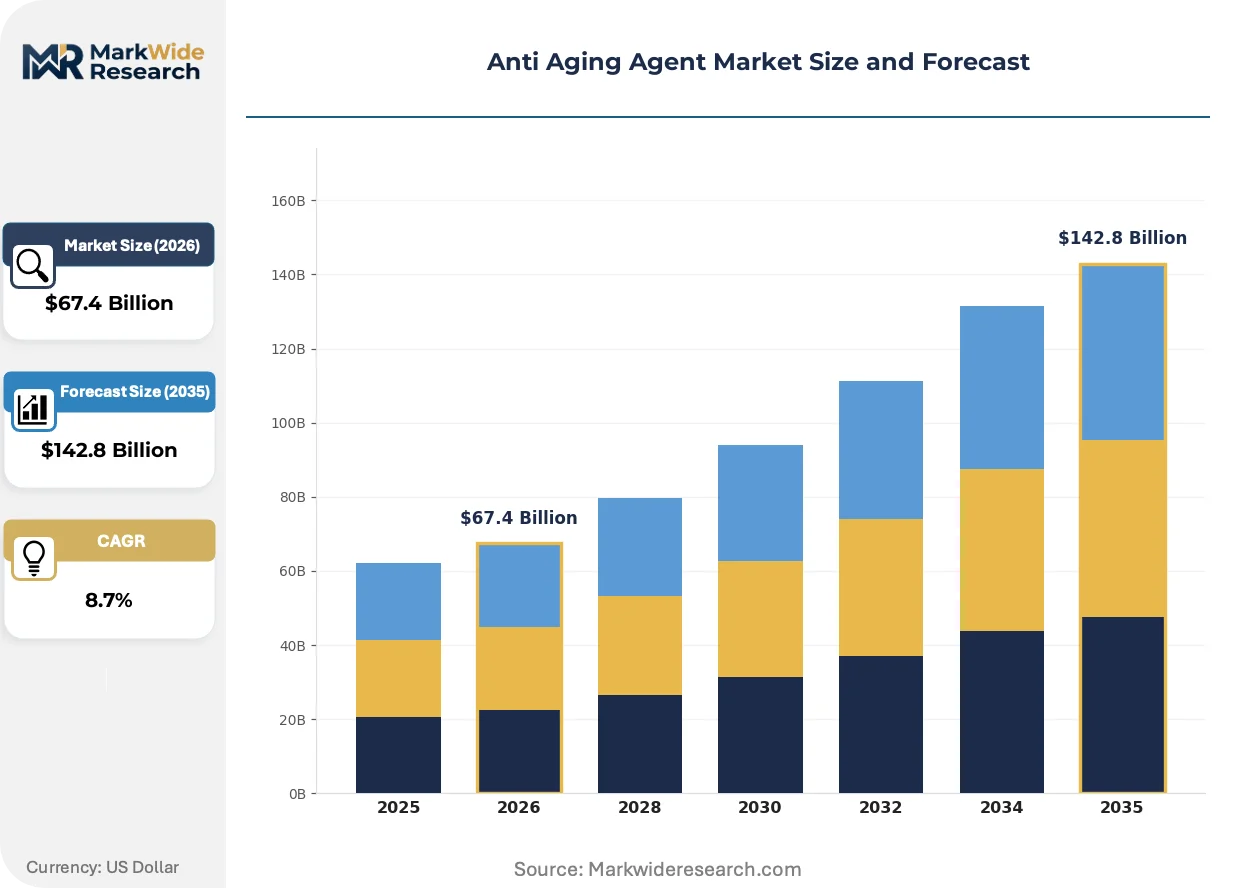
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $142.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinoids, Peptides, Antioxidants, Growth Factors Application: Skincare, Haircare, Dietary Supplements, Cosmetics Formulation: Serums, Creams, Gels, Lotions Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | DSM-Firmenich, Givaudan, Croda, BASF, Symrise, Ashland, Clariant, Evonik, Seppic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Aging Agent Market Trends and Innovations
Active ingredient delivery systems and regulatory compliance architectures now determine competitive position more than raw molecule efficacy. Formulators compete on stability engineering and clinical validation depth.
Encapsulation technology is bifurcating the market between premium clinic-dispensed serums and mass-market retinol products. Liposomal matrices maintain retinoid potency at 0.5-2.0% concentrations for physician-backed lines, while conventional emulsions dominate retail shelves with degraded actives. This technical divide compresses margin pools at the mid-market tier where stability claims lack substantiation.
REACH and the EU Cosmetics Regulation mandate exhaustive safety dossiers for novel peptide introductions. European formulators face 18-24 month compliance timelines before market entry, elevating barriers for smaller suppliers. Professional skincare brands respond by consolidating procurement around established peptide platforms with existing regulatory clearance.
Buyer concentration in dermatology channels reshapes distribution economics. Medical spas and clinic networks now negotiate direct supply agreements with ingredient manufacturers, displacing traditional cosmetic brand intermediaries. This channel disintermediation is most visible in the United States, where FDA oversight on claims has already professionalized the consumer decision process.
Anti Aging Agent Market Segmentation
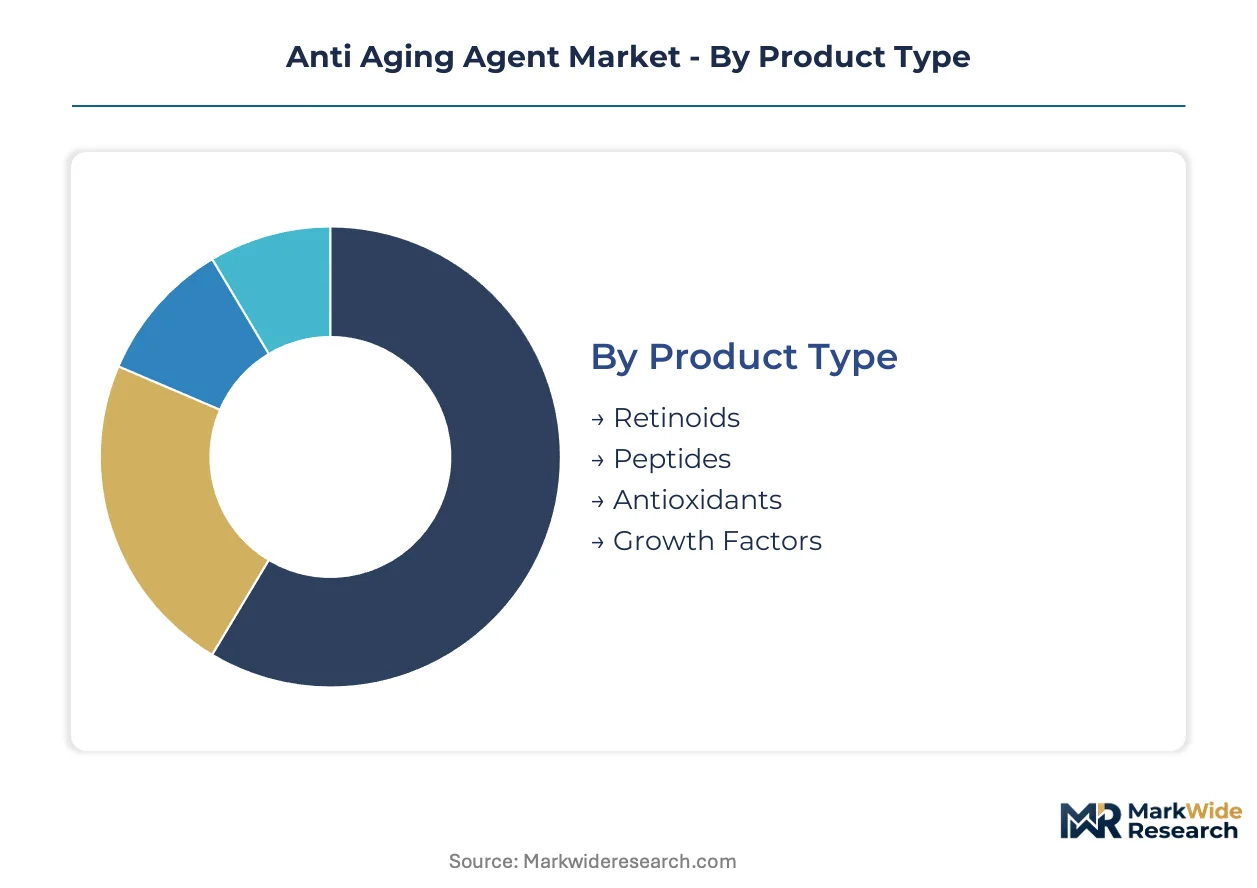
Ingredient suppliers structure pricing and distribution around how dermatology clinics versus retail channels source actives. Formulation complexity and regulatory substantiation requirements create divergent margin profiles across each segment category.
Product Type:
Peptides and retinoids capture premium margin pools due to encapsulation technology requirements and clinical validation costs.
- Retinoids:Vitamin A derivatives including retinol, retinaldehyde, and prescription-strength tretinoin require liposomal stabilization to prevent oxidation at therapeutic concentrations. United States dermatology practices drive demand for encapsulated formulations that justify higher dispensing fees through demonstrated efficacy stability.
- Peptides:Signal peptides and carrier peptides engineered for collagen synthesis modulation command procurement priority from medical spa networks. REACH compliance timelines in Europe favor established recombinant production platforms with existing safety dossiers.
- Antioxidants:Polyphenolic compounds including resveratrol, ferulic acid, and green tea catechins serve photodamage prevention protocols.
- Growth Factors:Recombinant epidermal and fibroblast growth factors remain restricted to physician-supervised applications.
Retinoids hold installed capacity. Peptides are rotating up the share rankings.
Application:
Volume concentration shifts toward professional treatment settings where supervision justifies higher active concentrations.
- Skincare:Facial serums and targeted treatments represent the core revenue base, with clinic-dispensed formulations outpacing retail growth. FDA claims oversight in the United States pushes brands toward physician-backed channels where clinical substantiation supports premium positioning.
- Haircare:Scalp treatment protocols using signal peptides for follicle stimulation are climbing the fastest within medical spa service menus. European procurement prioritizes REACH-verified sourcing for these emerging applications.
- Dietary Supplements:Oral collagen and antioxidant capsules compete with topical delivery for systemic anti-aging positioning.
- Cosmetics:Color cosmetics with incorporated actives serve mass-market prevention messaging.
Skincare dominates current procurement volumes. Haircare is gaining share fastest among professional channel buyers.
Formulation:
Stability engineering investments concentrate in serum formats where bioactive preservation justifies price premiums.
- Serums:Lightweight, high-concentration vehicles require nanoemulsion or liposomal encapsulation to maintain retinoid and peptide potency. Cold-chain logistics constraints limit geographic reach for premium clinic-dispensed lines.
- Creams:Emulsion-based delivery systems dominate retail shelves with lower actives concentrations and conventional preservation.
- Gels:Water-based matrices suit oil-sensitive skin segments and post-procedure applications.
- Lotions:Lower viscosity formats serve body care and mass-market prevention positioning.
Serums command formulation R&D investment. Creams maintain volume leadership in retail distribution.
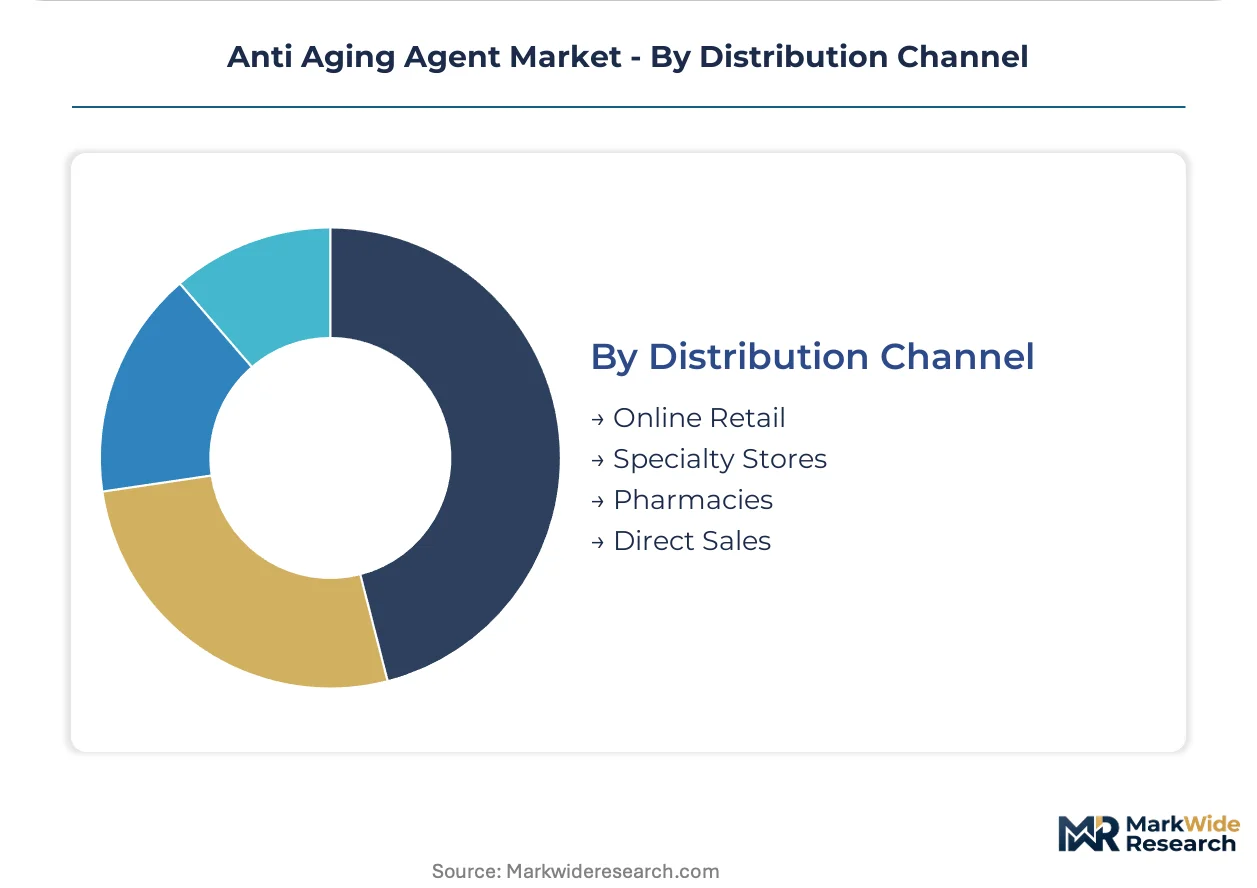
Distribution Channel:
Channel disintermediation restructures margin capture toward direct clinic-supplier relationships.
- Online Retail:E-commerce platforms serve educated consumers seeking ingredient transparency and verified reviews. United States brands navigate FDA packaging restrictions through detailed digital education content.
- Specialty Stores:Prestige beauty retailers face procurement priority displacement as dermatology clinics vertically integrate dispensing.
- Pharmacies:Retail pharmacy chains stock mid-tier antioxidant and retinol products with OTC positioning.
- Direct Sales:Physician office dispensing and medical spa protocols bypass traditional brand markups through captive supply agreements with biotechnology ingredient suppliers.
Direct sales channels are expanding capacity fastest. Online retail holds current transaction volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution of temperature-sensitive peptide formulations, while direct air freight corridors from Basel and Amsterdam serve clinic-dispensed channels across three continents.
United States
FDA claims oversight on cosmeceutical packaging forces brands toward physician-backed dispensing models. Medical spa networks in Florida and California negotiate direct supply agreements with biotechnology ingredient manufacturers. The Greater Boston corridor hosts recombinant growth factor production platforms serving dermatology practices nationwide.
Germany
REACH compliance timelines and exhaustive safety dossier requirements elevate barriers for novel peptide introductions. The Rhine-Main industrial cluster around Frankfurt anchors liposomal encapsulation technology for retinoid stabilization. Baden-Württemberg formulation houses supply professional skincare lines across the European Economic Area.
Switzerland
Recombinant growth factor production platforms cluster around Basel, creating single-source dependencies for mid-tier formulators. Swissmedic oversight shapes clinical validation standards for physician-supervised applications. The Lake Geneva biotech corridor supplies signal peptides to medical spa networks in France and Italy.
Netherlands
ECHA regulatory guidance from The Hague influences EU-wide safety assessment protocols for novel anti-aging actives. The Amsterdam-Rotterdam port complex handles bulk antioxidant imports for polyphenolic formulation houses. Eindhoven-region encapsulation technology providers serve nanoemulsion production for premium serum lines.
Japan
METI standards for functional cosmetic claims push brands toward substantiated clinical testing for peptide-based formulations. The Kansai industrial corridor around Osaka hosts botanical extraction capabilities for clean-label antioxidant demand. PMDA consultation procedures create extended lead times for growth factor product registrations.
Anti Aging Agent Market Competitive Landscape
Concentration sits with integrated biotechnology platforms and specialized delivery system providers. The supplier base organizes around three archetypes: fermentation-derived peptide specialists, lipid-active encapsulation engineers, and botanical extraction houses. Consolidation pressure favors players with captive regulatory dossiers and cold-chain distribution assets. M&A activity targets REACH-compliant manufacturing capacity, while strategic partnerships lock in dermatology clinic procurement relationships.
Within the integrated biotechnology tier, DSM-Firmenich and Givaudan exemplify divergent sourcing strategies—one leveraging recombinant production platforms, the other specialized botanical extraction for clean-label positioning. Croda occupies a position bridging encapsulation technology and lipid-active delivery systems. These three anchors represent the spectrum of competitive approaches: captive biotech infrastructure, verified origin supply chains, and formulation engineering capabilities.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Givaudan |
| Croda |
| BASF |
| Symrise |
| Ashland |
| Clariant |
| Evonik |
| Seppic |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Swiss recombinant peptide producers and United States dermatology clinic networks lock in supply access and price visibility for high-potency retinoid formulations, insulating procurement teams from spot-market volatility in antioxidant feedstocks.
Pricing Analysis
Volume-discount tiering separates physician-dispensed peptide serums from retail retinol creams and mass-market antioxidant lotions. Clinic networks with captive supply agreements capture 15-20% input cost advantages over independent medical spas purchasing through distributor intermediaries. Pricing pressure intensifies in mid-market retail channels where unencapsulated retinoid products compete on label claims without clinical substantiation. Hospital-affiliated dermatology practices exhibit lowest price sensitivity due to bundled procedure economics, while independent aesthetic clinics negotiate aggressively on peptide minimum order quantities.
Supply Chain Analysis
Cold-chain logistics chokepoints at the Port of Rotterdam and Basel-Mulhouse-Freiburg tripoint constrain temperature-sensitive growth factor distribution to medical spa networks. Recombinant peptide production clusters in Switzerland and the Netherlands, while liposomal encapsulation inputs draw from German specialty chemical manufacturers. Single-source dependencies for recombinant epidermal growth factors create vulnerability for mid-tier formulators lacking dual-qualified suppliers. Distribution runs through direct procurement relationships between biotechnology platforms and clinic networks, bypassing traditional cosmetic brand markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from at-home microcurrent and LED therapy devices that promise comparable collagen stimulation without clinical supervision, forcing active ingredient suppliers to demonstrate superior efficacy-to-cost ratios in physician protocols.
For Market Incumbents: Secure REACH-compliant peptide sourcing through captive agreements with Basel-region biotechnology platforms before European safety dossier backlogs extend lead times. Consolidate liposomal encapsulation capacity in the Rhine-Main corridor to defend margin position against emerging Asian suppliers with unproven cold-chain capabilities. Backward integration into recombinant growth factor production reduces single-source vulnerability as Swissmedic tightens clinical validation standards. For New Entrants and Emerging Players: Anchor in scalp treatment peptide applications for medical spa service menus, where signal peptide protocols for follicle stimulation remain underpenetrated relative to facial skincare saturation. Target independent dermatology clinics in Florida and California with direct supply agreements that bypass established distributor relationships. Emphasize clean-label botanical antioxidant extraction credentials to capture European procurement preference for verified origin claims. For Investors and Strategic Acquirers: Encapsulation technology specialists with existing nanoemulsion production lines and FDA-substantiated clinical dossiers represent the most defensible acquisition profile in a market consolidating around validated delivery systems. Monitor ECHA regulatory guidance timelines from The Hague as an inflection indicator for novel peptide market entry barriers and incumbent pricing power durability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Dossier Investment | FDA-substantiated efficacy claims unlock physician-dispensed channel premiums and defend against at-home device substitution. |
| Encapsulation Technology Acquisition | Liposomal matrix capabilities from German or Dutch specialists secure retinoid stability advantages in high-concentration serums. |
| Direct Clinic Supply Agreements | Captive procurement relationships with United States medical spa networks displace traditional cosmetic brand intermediaries. |
| REACH-Compliant Peptide Sourcing | Verified supply chains from Swiss biotechnology platforms preempt European safety dossier backlogs and compliance delays. |
| Haircare Application Development | Signal peptide protocols for scalp treatment open fastest-expanding volume channels beyond saturated facial skincare segments. |
Research Methodology
The analysis maps retinoid stabilization technologies, peptide synthesis platforms, antioxidant extraction methods, and growth factor production systems, each validated through formulation chemists at encapsulation technology providers, procurement directors at dermatology clinic networks, regulatory affairs specialists navigating FDA claims oversight, and supply chain managers at cold-chain logistics operators. Primary interview findings triangulate against ECHA safety dossier filings, FDA cosmeceutical guidance documents, Swissmedic clinical validation standards, United States customs import records for peptide feedstocks, and SEC disclosures from listed specialty chemical manufacturers. Bottom-up volume estimates from individual clinic dispensing protocols reconcile with top-down market sizing from ingredient supplier production capacities.
Consistency checks validate volume and value outputs against external benchmarks including European professional skincare procurement databases, United States medical spa service menu pricing audits, and Japanese METI functional cosmetic claim registrations. The analytical framework segments by active ingredient type, formulation complexity, distribution channel structure, and regional regulatory cluster across the projection horizon. CAGRs derive from modeled clinic-dispensed channel expansion rates, encapsulation technology adoption curves, and REACH compliance timeline impacts on novel peptide introductions. Industry-specific forecast inputs include liposomal matrix production capacity utilization and recombinant growth factor batch yield improvements.
Decision-makers should treat outputs as directional under assumptions of sustained FDA claims oversight stringency and stable ECHA safety assessment protocols; material deviation in regulatory classification boundaries between cosmetics and drugs would warrant model refresh. Practitioners should keep alternative scenarios live as at-home device efficacy claims and clean-label botanical sourcing preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Nootropics Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
Magtein Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market