
 Virtual Reality Headset Market | 2026-2036
Virtual Reality Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality Headset Market Intelligence
Enterprise direct-to-business procurement is reshaping how VR headset vendors allocate inventory and technical support resources. Meta leverages its social platform ecosystem to sustain hardware attach rates among content creators. Sony dominates console-integrated VR through exclusive gaming IP and controlled retail partnerships. HTC specializes in high-fidelity tethered systems for commercial simulation clients across Asia-Pacific and European markets.
A virtual reality headset is a wearable display device that combines dual high-resolution screens, typically OLED or LCD panels operating at 90–120 Hz refresh rates, with integrated motion tracking sensors to generate immersive three-dimensional environments for the user. Its primary commercial purpose spans interactive entertainment, skills training, and spatial design visualization across industries. Standalone headsets capture the broadest consumer base by eliminating external computing dependencies, while PC-powered systems anchor professional-grade simulation workflows where rendering fidelity determines utility. Military simulation applications are expanding fastest among verticals, driven by defense contractors seeking cost-effective tactical rehearsal environments.
FCC certification governs radio frequency emissions for US-bound headsets, while CE marking under the EU's MDR framework imposes biocompatibility and optical safety standards on devices with prolonged skin contact. China's MIIT enforces GB standards for wireless transmission and battery safety, creating segmented compliance pathways for manufacturers serving multiple markets. Stakeholders must track how emerging AI Act provisions in Europe classify headsets with embedded biometric monitoring, as reclassification could trigger additional conformity assessment obligations before market entry.
Market Dynamics
Enterprise procurement of tethered VR systems for healthcare simulation and defense training is compressing consumer-led demand cycles, forcing manufacturers to reallocate engineering talent toward thermal management and optical precision for all-day professional use.
Growth Catalysts
- EU AI Act biometric provisions:Reclassification of headsets with embedded eye-tracking and facial analysis as high-risk AI systems is accelerating conformity assessment investments among European vendors seeking first-mover certification advantage.
- Defense simulation vertical:Military contractors in the United States and United Kingdom are procuring cost-effective tactical rehearsal environments, displacing live-fire training budgets toward immersive hardware procurement.
- MIIT GB standard harmonization:China's consolidation of wireless transmission and battery safety standards is enabling domestic manufacturers to achieve faster multi-market clearance for export-bound standalone headsets.
Market Restraints
- OLED panel supply concentration:Korean and Japanese display manufacturers control high-refresh-rate micro-OLED output, creating input cost volatility for premium headset tiers dependent on sub-10-millisecond pixel response.
- CE marking MDR friction:The EU's Medical Device Regulation imposes biocompatibility and optical safety testing on prolonged skin-contact devices, extending time-to-market by 8-14 months for European-bound hardware.
- Smartphone AR substitution:Spatial computing features on premium handsets are capturing casual immersive content consumption, narrowing the addressable base for entry-level standalone VR headsets.
Strategic Opportunities
- Industrial maintenance augmentation:German and French automotive manufacturers are piloting mixed-reality headsets for real-time assembly guidance, creating white space beyond entertainment and training verticals.
- India PLI scheme leverage:Production-linked incentives for electronics manufacturing are attracting component suppliers to establish local assembly for cost-optimized headsets targeting price-sensitive education and healthcare buyers.
- 5G edge-cloud convergence:Low-latency streaming architectures are enabling thin-client headsets that offload rendering to distributed servers, reducing hardware BOM while preserving visual fidelity for enterprise simulation clients.
Industry Challenges
- Optomechanical engineering scarcity:The intersection of precision lens design, thermal dynamics, and human-factor ergonomics requires specialized talent pools concentrated in Taiwan and southern Germany, constraining R&D velocity for second-tier vendors.
- FCC certification timeline compression:Radio frequency emission testing for Wi-Fi 6E and 60 GHz unlicensed bands is creating bottlenecks at accredited labs, delaying US market entry for products with novel wireless architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality Headset Market |
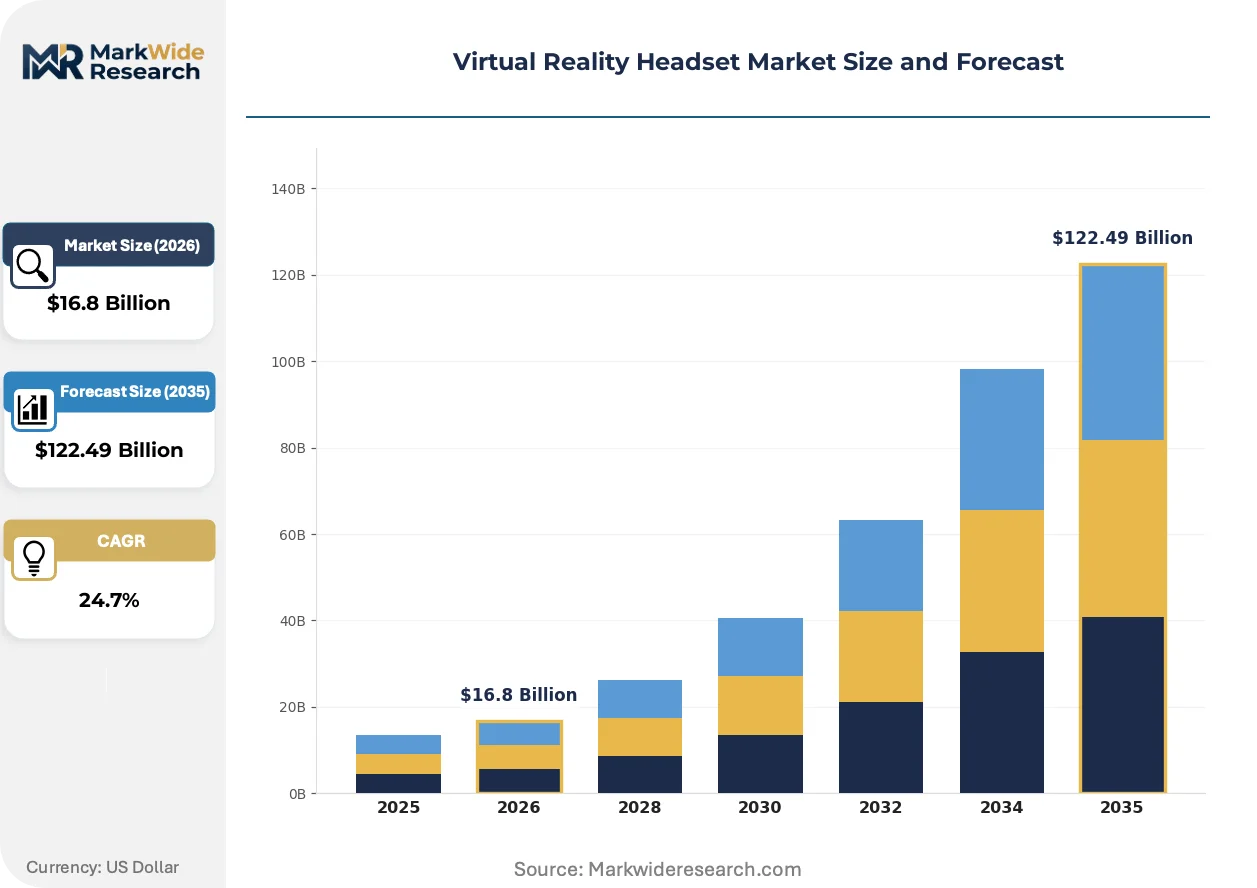
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $122.49 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Smartphone-Based, PC-Powered, Console-Integrated Technology: Oculus, Vive, PlayStation VR, Valve Index, Windows Mixed Reality Application: Gaming, Education, Military Simulation, Architectural Design, Virtual Tourism End User: Game Developers, Educational Institutions, Defense Contractors, Design Firms, Travel Agencies |
| Companies Covered | HTC, Google, Meta, Pimax, DPVR, Microsoft, Pico Interactive, Vuzix Corporation, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality Headset Market Strategic Shifts & Innovations
Display architectures and regulatory classification frameworks are simultaneously evolving, compressing product development cycles while expanding the addressable use cases for immersive hardware across professional and consumer segments.
Pancake lens optics are replacing Fresnel designs in premium headsets, folding the optical path through polarized reflectors to reduce headset thickness by 40 percent while expanding field-of-view. Medical training centers and architectural visualization studios are adopting these configurations for multi-hour continuous use. The technology is migrating from flagship enterprise SKUs toward mid-tier consumer offerings as manufacturing yields improve and unit costs decline.
The EU AI Act's risk-based classification system is imposing conformity assessment obligations on headsets with embedded biometric monitoring, requiring notified body involvement for devices capturing physiological or behavioral data. Hardware vendors are restructuring firmware architectures to isolate biometric processing modules, enabling modular certification pathways. Products targeting healthcare and workplace wellness applications face the steepest compliance burden, with several manufacturers delaying European launches pending legal clarity on eye-tracking data governance.
Defense contractors and hospital networks are consolidating procurement authority under dedicated immersive technology officers, displacing decentralized IT purchasing that previously fragmented vendor relationships. These concentrated buyers are demanding multi-year service agreements bundling hardware, content licensing, and technical support. The shift is most visible in the United States and United Kingdom, where military health services and national health systems are standardizing on single-vendor enterprise agreements for simulation infrastructure.
Virtual Reality Headset Market Segmentation
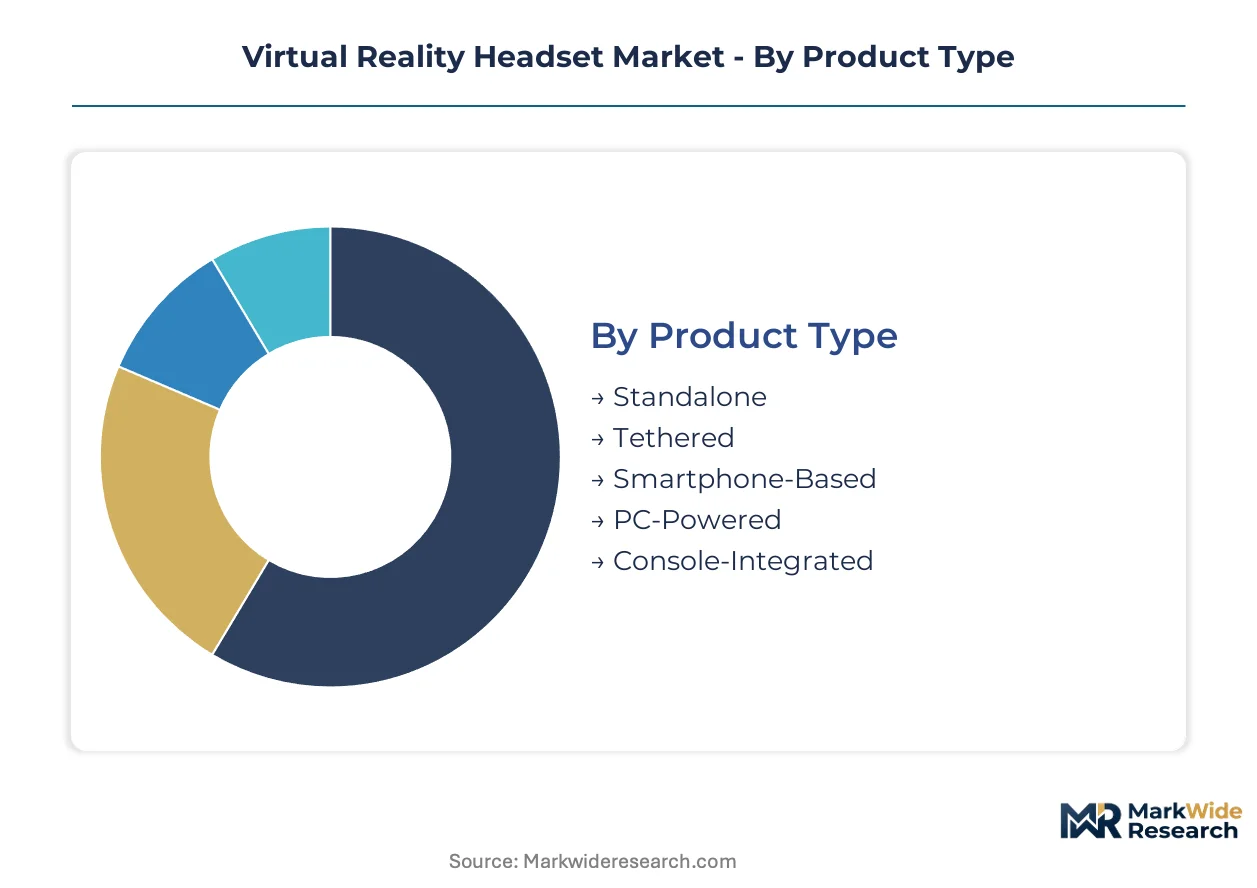
Segmentation in the VR headset market reveals divergent replacement cycles across hardware architectures. Product type determines procurement frequency, while application verticals dictate performance specifications and compliance requirements.
Product Type:
Replacement cycles vary dramatically from eighteen-month consumer refresh intervals to seven-year enterprise deployment horizons, compressing or extending vendor revenue recognition patterns.
- Standalone:Integrated SoC architectures eliminate external computing dependencies, enabling untethered operation. Demand concentrates in China's consumer retail channels and North American education districts seeking zero-setup deployment. Domestic manufacturers in Shenzhen and Chengdu scale production for export-bound units targeting price-sensitive institutional buyers.
- Tethered:High-bandwidth cable connections to workstation GPUs deliver sub-20-millisecond motion-to-photon latency for precision simulation. German automotive manufacturers and United Kingdom defense contractors standardize procurement on these systems for multi-hour continuous use, prioritizing thermal stability over portability.
- Smartphone-Based:Low-cost shell enclosures leverage existing handset displays and sensors for casual immersive content.
- PC-Powered:External rendering pipelines support variable refresh rates up to 144 Hz for competitive gaming applications.
- Console-Integrated:Proprietary hardware-software binding ensures optimized performance within closed entertainment ecosystems.
Standalone headsets anchor the volume base while tethered systems gain share at the steepest rate among enterprise simulation clients.
Technology:
Platform ecosystems determine content library depth and developer incentive structures, with proprietary SDKs locking in creative talent and fragmenting addressable audiences.
- Oculus:Social platform integration drives content creator retention through monetization tools and audience access. Meta's storefront policies and hardware subsidies concentrate consumer demand in North American and Western European markets where social VR adoption outpaces standalone gaming.
- Vive:SteamVR compatibility and enterprise licensing programs support commercial simulation deployments across Asia-Pacific healthcare networks. HTC's location-based entertainment partnerships in Tokyo and Seoul generate recurring hardware refresh demand.
- PlayStation VR:Exclusive gaming IP and controlled retail partnerships dominate console-integrated segments.
- Valve Index:Finger-tracking controllers and high-fidelity audio attract enthusiast PC gaming segments.
- Windows Mixed Reality:Open standards approach enables multi-vendor hardware compatibility for enterprise IT standardization.
Oculus technology anchors the volume base while Vive configurations expand most quickly among healthcare and defense simulation verticals.
Application:
Performance requirements scale with session duration and safety-criticality, from recreational entertainment tolerance for latency to military rehearsal demands for physiological fidelity.
- Gaming:Competitive multiplayer titles drive refresh rate specifications and controller haptics innovation. South Korean esports venues and North American streaming content creators sustain hardware upgrade cycles through audience-facing performance requirements.
- Military Simulation:Cost-effective tactical rehearsal environments displace live-fire training budgets across United States and United Kingdom defense procurement. Contractors demand multi-year service agreements bundling hardware, scenario licensing, and classified network integration.
- Education:Institutional procurement concentrates in STEM laboratory and vocational training contexts.
- Architectural Design:Real-time ray-traced visualization supports client presentation and spatial planning workflows.
- Virtual Tourism:Cultural heritage digitization and destination marketing applications serve hospitality sector experimentation.
Gaming applications anchor the volume base while military simulation climbs the fastest among verticals as defense contractors consolidate immersive technology procurement.
End User:
Procurement authority centralization varies from decentralized IT purchasing in education to dedicated immersive technology officers in defense and healthcare networks.
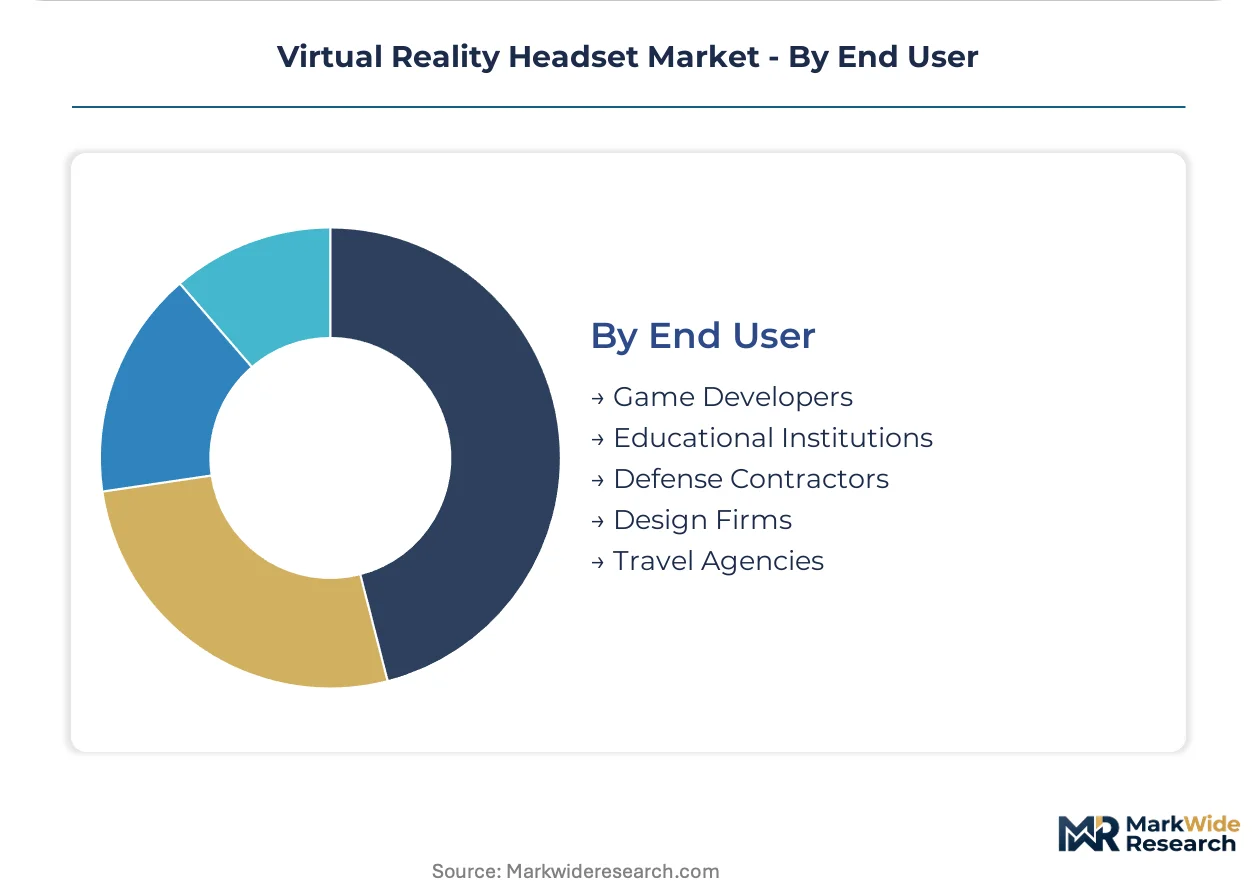
- Game Developers:Content creation pipelines demand high-fidelity reference hardware for optimization and debugging. Independent studios in Montreal and Stockholm prioritize standalone development kits for cross-platform deployment targeting Meta's storefront.
- Defense Contractors:Classified network integration requirements and security clearance protocols create vendor qualification barriers. United States and United Kingdom military health services standardize on single-vendor enterprise agreements for simulation infrastructure, displacing fragmented procurement.
- Educational Institutions:Zero-setup deployment requirements favor standalone configurations for K-12 adoption.
- Design Firms:Client-facing presentation needs drive premium tethered system selection.
- Travel Agencies:Experimental deployment for destination preview and booking conversion.
Game developers anchor the volume base while defense contractors drive the steepest procurement expansion as military health services consolidate simulation infrastructure authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial procurement channels while Chinese manufacturers compete on volume throughput. Defense contractors in the United Kingdom pay premiums for classified-network integration that consumer channels cannot match. Shenzhen production clusters achieve cost structures that European assemblers cannot replicate without tariff exposure.
United States
Defense contractors and military health services consolidate procurement under dedicated immersive technology officers. FCC certification timelines for Wi-Fi 6E and 60 GHz bands create bottlenecks at accredited testing labs. Austin and Seattle clusters host simulation software vendors partnering with hardware manufacturers on multi-year service agreements.
Germany
Automotive manufacturers pilot mixed-reality assembly guidance systems for real-time maintenance workflows. CE marking under the EU's MDR framework imposes biocompatibility and optical safety standards that extend time-to-market by 8-14 months. Bavarian precision optics suppliers in Munich and Nuremberg provide pancake lens components for premium headset tiers.
China
Domestic manufacturers scale production for both consumer retail and industrial export buyers. MIIT enforces GB standards for wireless transmission and battery safety that enable faster multi-market clearance for export-bound standalone units. Shenzhen and Chengdu production clusters supply price-sensitive education districts across Southeast Asia and Latin America.
United Kingdom
National Health Service trusts standardize on single-vendor enterprise agreements for surgical simulation infrastructure. The EU AI Act's biometric provisions drive conformity assessment investments among vendors seeking first-mover certification advantage. London defense procurement offices displace live-fire training budgets toward immersive tactical rehearsal environments.
India
Production-linked incentive schemes for electronics manufacturing attract component suppliers establishing local assembly operations. Price-sensitive education and healthcare buyers drive demand for cost-optimized standalone configurations. Karnataka and Tamil Nadu industrial corridors host contract manufacturers serving domestic institutional procurement and re-export channels.
Virtual Reality Headset Market Key Industry Players
Platform-integrated technology conglomerates and specialized immersive hardware fabricators split the market along ecosystem control vectors. Consolidation pressure concentrates around content library depth and developer SDK lock-in rather than unit manufacturing scale. Three archetypes dominate: social-platform hardware subsidizers, enterprise simulation specialists, and console-entertainment integrators. Competitive moves center on exclusive content licensing arrangements and multi-year service agreement bundling for defense and healthcare procurement officers.
Among platform-integrated conglomerates, Meta and Microsoft occupy positions anchoring distinct ecosystem strategies, while Sony exemplifies the console-entertainment integrator archetype through proprietary hardware-software binding. HTC and Pico Interactive sit within the specialized hardware tier, representing geographic diversification across Asia-Pacific manufacturing and European commercial simulation markets. Vuzix Corporation occupies a position exemplifying the enterprise-focused specialist archetype.
| Leading Market Players |
|---|
| HTC |
| Meta |
| Pimax |
| DPVR |
| Microsoft |
| Pico Interactive |
| Vuzix Corporation |
| Sony |
| Others |
Cost & Logistics Intelligence
Shenzhen production clusters anchor global headset manufacturing capacity, with their throughput dynamics directly compressing margins for European assemblers who cannot replicate comparable cost structures without tariff exposure. This geographic concentration grants Chinese domestic manufacturers pricing power in education and healthcare procurement channels where institutional buyers prioritize zero-setup deployment economics.
Pricing Analysis
Configured-to-order tethered systems for defense contractors command substantial premiums over standard standalone SKUs sold through retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by optical fidelity, thermal management specifications, and bundled multi-year service agreements. Cost compression in entry-level standalone tiers is intensifying because smartphone AR substitution narrows the addressable consumer base. Educational institutions in India and Southeast Asia represent the most price-sensitive demand segment, while United Kingdom defense contractors and German automotive manufacturers exhibit lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for headset vendors serving dual-market procurement officers. Component sourcing draws from Korean and Japanese micro-OLED fabricators, Taiwanese precision optics suppliers, and Chinese battery cell manufacturers. Single-source vulnerability concentrates in high-refresh-rate display panels where sub-10-millisecond pixel response specifications limit qualified supplier pools. Distribution runs through direct enterprise agreements for defense and healthcare verticals, while consumer channels rely on controlled retail partnerships and education district procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized optomechanical engineering talent pools in Taiwan and southern Germany constrain R&D velocity, creating acquisition premiums for teams capable of integrating precision lens design with thermal dynamics and human-factor ergonomics.
For Market Incumbents: Pre-empt smartphone AR substitution by accelerating pancake lens migration into mid-tier consumer SKUs before manufacturing yields fully mature. Secure captive supply of high-refresh-rate micro-OLED panels through backward integration partnerships with Korean and Japanese display fabricators. Invest in FCC pre-certification testing capacity to bypass Wi-Fi 6E and 60 GHz band bottlenecks at accredited labs. For New Entrants and Emerging Players: Pursue industrial maintenance augmentation white space in German and French automotive assembly guidance, where incumbent vendors remain anchored in entertainment and training verticals. Target cost-optimized standalone configurations for India's price-sensitive education and healthcare buyers under PLI scheme manufacturing incentives. Deploy 5G edge-cloud streaming architectures to reduce hardware BOM while preserving visual fidelity for thin-client enterprise deployments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates with underutilized immersive hardware divisions lacking dedicated immersive technology officer relationships. Long-term viability hinges on enterprise simulation contract durability rather than consumer hardware refresh cycles. Monitor EU AI Act biometric classification clarity as the critical inflection signal for European market entry timing and conformity assessment investment thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Pancake Lens Manufacturing Scale-Up | Reduces headset thickness 40% for multi-hour medical training and architectural visualization use. |
| EU AI Act Conformity Assessment | Enables first-mover certification advantage for biometric-enabled devices in European healthcare markets. |
| Defense Contractor Service Agreement Bundling | Captures multi-year revenue streams through classified network integration and scenario licensing. |
| India PLI Scheme Manufacturing Localization | Attracts component suppliers to Karnataka and Tamil Nadu corridors for cost-optimized institutional supply. |
| 5G Edge-Cloud Rendering Partnership | Offloads computational load to distributed servers while preserving sub-20-millisecond latency for simulation clients. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with hardware engineering directors, enterprise procurement officers at defense contractors, immersive technology officers in healthcare networks, and FCC certification consultants; alongside secondary validation through MIIT GB standard filings, CE marking MDR documentation, SEC hardware manufacturer disclosures, and customs trade data for headset component flows. Bottom-up unit shipment modeling triangulated against top-down market value reconstructions across product type, technology platform, application vertical, and end-user archetype dimensions.
Forecast inputs considered replacement cycle differentiation between eighteen-month consumer refresh intervals and seven-year enterprise deployment horizons across the projection horizon. Segmentation dimensions modeled include hardware architecture, platform ecosystem, application safety-criticality, and procurement authority centralization. CAGRs were derived from regression analysis of historical shipment trajectories overlaid with regulatory catalyst timing and defense budget reallocation patterns toward immersive training infrastructure.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, defense procurement authorization levels, or China-EU trade corridor stability would shift the trajectory. Forecasts reflect documented assumptions regarding OLED panel supply expansion, EU AI Act implementation timelines, and 5G network deployment cadence in target enterprise markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market