
 5G and Virtual Reality Market | 2026-2036
5G and Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
5G and Virtual Reality Market Outlook
The gap between premium enterprise-grade VR systems and mass-consumer headsets is broadening as 5G network slicing enables differentiated service tiers. Qualcomm Technologies leverages its Snapdragon XR platforms to anchor high-end standalone performance, while Meta Platforms competes aggressively on cost-optimized hardware volume. Samsung Electronics differentiates through integrated smartphone-to-headset ecosystems that sustain recurring content revenue.
5G and Virtual Reality denotes the convergence of fifth-generation cellular networks with immersive three-dimensional computing environments, where sub-10 millisecond latency and 1 Gbps throughput enable real-time rendered spatial experiences streamed from edge servers. This technology stack serves industrial training, remote collaboration, and consumer entertainment by eliminating local processing constraints. Cloud-based deployment architectures capture expanding margin pools as enterprises shift capital expenditure to subscription models, while tethered systems retain niche dominance in high-fidelity simulation environments where latency tolerance approaches zero. Gaming end users currently occupy the largest addressable base, though healthcare applications are accelerating fastest as telehealth reimbursement frameworks mature.
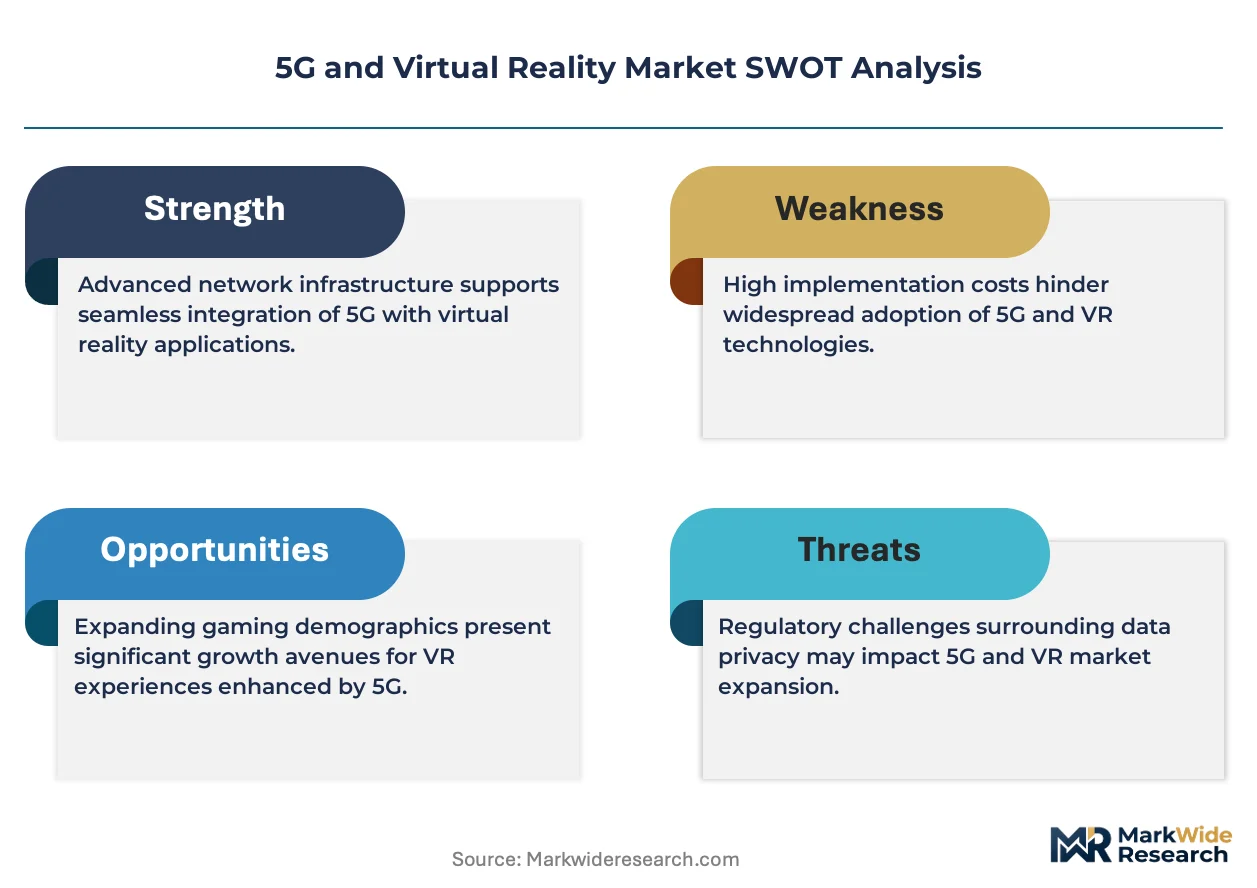
The FCC governs spectrum allocation for 5G-enabled VR services in the United States, while the EU AI Act imposes transparency obligations on automated content generation within immersive environments, and China's MIIT enforces GB standards for network equipment interoperability. These frameworks collectively shape product certification timelines, cross-border data routing requirements, and hardware compliance costs that filter market entry. Stakeholders must monitor evolving spectrum auction outcomes and content moderation liabilities as regulatory fragmentation between jurisdictions intensifies compliance complexity.
Market Dynamics
Network slicing is fragmenting service tiers in the 5G and Virtual Reality market, forcing hardware vendors to align product roadmaps with carrier-defined performance bands rather than consumer price points alone.
Growth Catalysts
- Industrial Digitalization Mandates:Germany's Industry 4.0 framework compels manufacturers to deploy VR-enabled remote maintenance over 5G private networks, creating anchored demand for low-latency edge infrastructure.
- Telehealth Reimbursement Expansion:Japan's Ministry of Health, Labour and Welfare has approved procedural codes for VR-assisted rehabilitation, accelerating clinical adoption of immersive therapeutic protocols.
- Edge Computing Proliferation:Multi-access edge computing nodes are compressing render-to-display latency below the 20-millisecond nausea threshold, expanding addressable use cases beyond gaming into professional simulation.
Market Restraints
- Semiconductor Supply Concentration:Advanced XR chip fabrication concentrates in Taiwan and South Korea, exposing headset manufacturers to geopolitical disruption in wafer supply chains.
- Spectrum Auction Cost Burden:FCC Part 96 licensing fees for 3.5 GHz CBRS bands inflate carrier capital requirements, delaying rural 5G VR service deployment.
- Motion-to-Photon Latency Floors:Physics-bound constraints in photon emission and neural processing impose hard limits on fully untethered high-fidelity experiences.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for telecom and networking equipment are attracting contract manufacturers to establish 5G VR hardware assembly capacity.
- Convergence with Haptic Feedback:Integration of force-feedback gloves with 5G-streamed VR is opening surgical training and industrial skill transfer applications previously reserved for physical mock-ups.
- Direct-to-Enterprise Channel Expansion:Bypassing consumer retail through carrier-managed service bundles is capturing recurring revenue streams in corporate training verticals.
Industry Challenges
- Spatial Computing Talent Scarcity:Shortages in 3D engine optimization and network orchestration expertise are extending development timelines for complex multi-user environments.
- Cross-Jurisdictional Content Compliance:China's GB standards for data localization conflict with EU GDPR portability requirements, forcing redundant content hosting architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G and Virtual Reality Market |
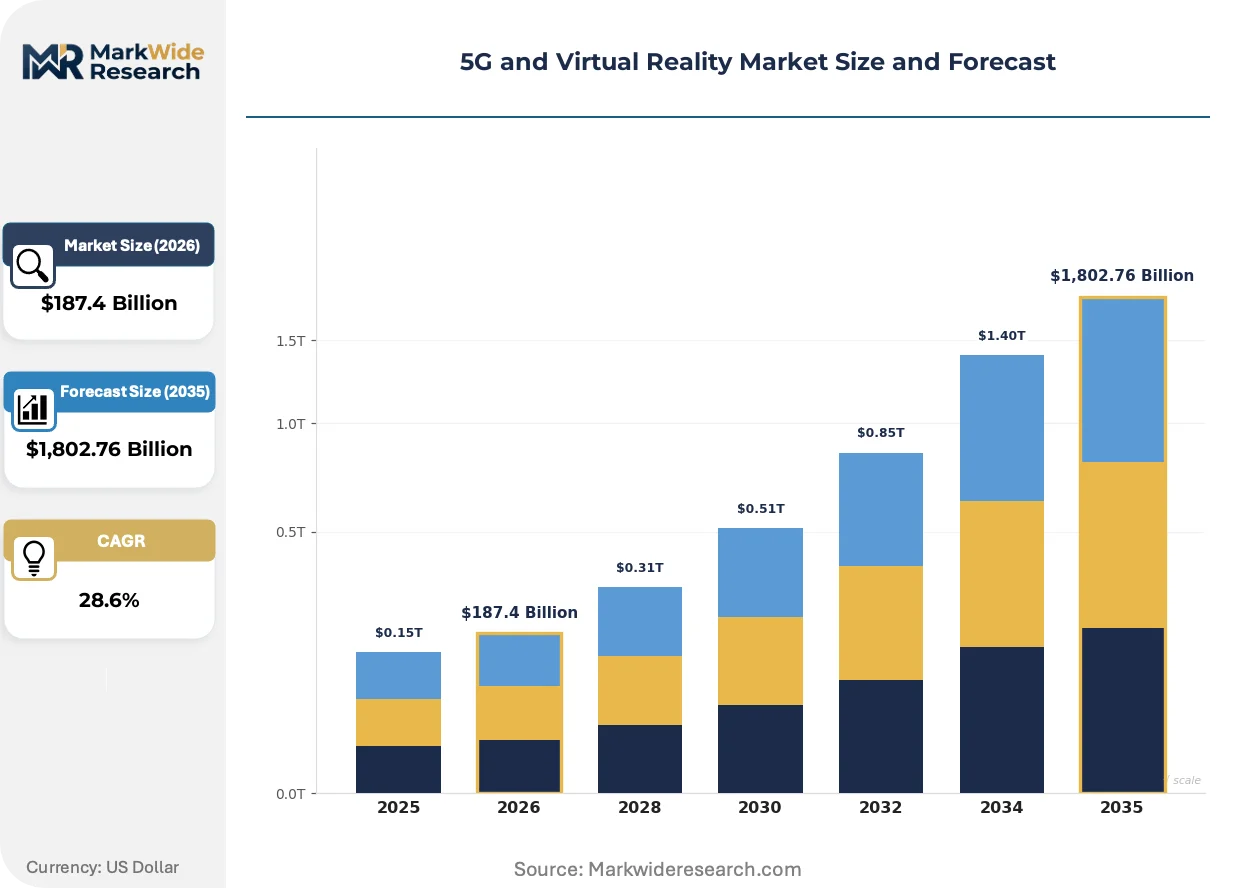
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $1,802.76 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Gaming, Healthcare, Education, Retail Application: Training Simulations, Telehealth, Virtual Tours, Social VR Technology: Standalone, Tethered, Cloud-based, Mobile Deployment: On-premises, Hybrid, Cloud, Edge Computing |
| Companies Covered | Qualcomm Technologies, Microsoft, Google, Samsung Electronics, Sony, Meta Platforms, NVIDIA, Huawei Technologies, HTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G and Virtual Reality Market Strategic Shifts
Foveated rendering is compressing bandwidth requirements while regulatory frameworks are hardening around biometric data collection in immersive environments.
Cloud-native XR streaming is rewriting how computational load distributes between edge servers and local headsets. Automotive design studios in Stuttgart and Detroit are adopting this architecture to eliminate workstation tethering during collaborative reviews. The shift is compressing hardware refresh cycles from three years to eighteen months as rendering migrates off-device.
The EU AI Act imposes transparency obligations on automated content generation within immersive environments, requiring disclosure when synthetic characters or environments are algorithmically produced. Training simulation providers must now embed provenance metadata into scenario files. German industrial certification bodies are revising safety standards to incorporate these disclosure requirements.
Subscription-based hardware access is displacing outright purchase in enterprise VR procurement. Healthcare systems in Japan and the United Kingdom are favoring per-seat monthly licensing that bundles headsets, software, and 5G connectivity. This model concentrates vendor selection authority with procurement departments rather than individual clinical units.
5G and Virtual Reality Market Segmentation
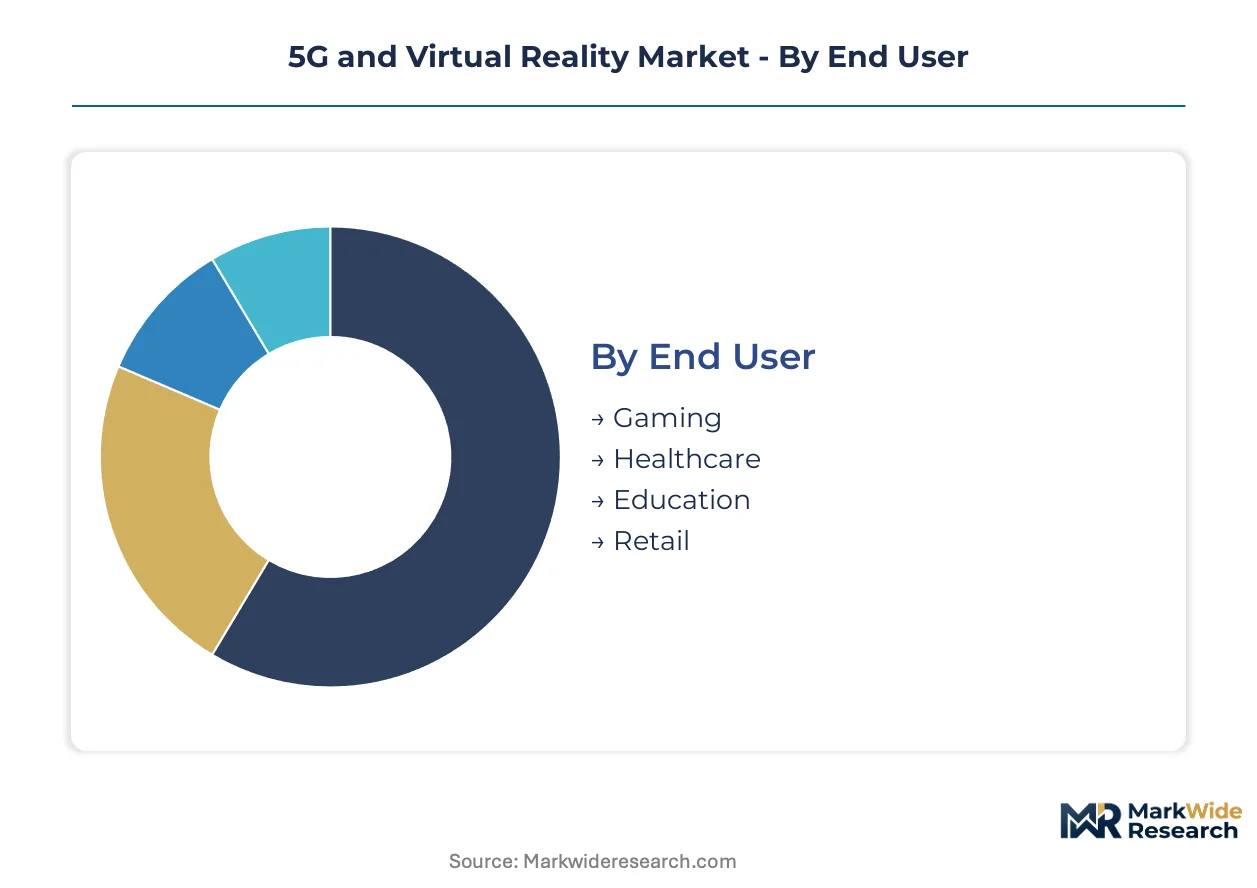
Segmentation in the 5G and Virtual Reality market reveals how latency tolerance, mobility requirements, and computational load distribution shape procurement decisions across enterprise and consumer verticals. Buyers prioritize deployment flexibility over hardware ownership as network slicing matures.
End User:
Procurement authority concentrates with departments controlling experiential budgets rather than IT infrastructure teams.
- Gaming:Mass-market headsets dominate unit volumes, with 5G edge streaming reducing local GPU requirements. Demand clusters in South Korea and Japan where esports venues deploy private network slices for tournament-grade latency. Subscription revenue models are displacing perpetual software licenses.
- Healthcare:Surgical training and therapeutic rehabilitation command premium pricing through reimbursed procedural codes. Japan's Ministry of Health, Labour and Welfare has accelerated clinical adoption with specific reimbursement frameworks for VR-assisted protocols.
- Education:K-12 and higher education institutions favor cost-optimized mobile-dependent headsets. Budget constraints favor cloud-rendered content over local processing investments.
- Retail:Virtual showrooms and spatial commerce pilots concentrate in luxury goods and automotive configurators. Proof-of-concept deployments precede scaled rollout due to uncertain conversion metrics.
Gaming leads on scale; Healthcare leads on momentum.
Application:
Latency sensitivity determines whether workloads migrate to edge infrastructure or tolerate cloud round-trip delays.
- Training Simulations:Industrial and military buyers demand sub-20 millisecond motion-to-photon latency for skill retention validity. Germany's Industry 4.0 framework mandates VR-enabled maintenance training over 5G private networks.
- Telehealth:Remote diagnostics and rehabilitation protocols require HIPAA-compliant data routing with biometric privacy safeguards. Clinical validation timelines extend procurement cycles beyond consumer markets.
- Virtual Tours:Real estate and hospitality deployments prioritize photorealism over interactivity, tolerating higher latency for reduced infrastructure cost.
- Social VR:Multi-user presence applications balance avatar fidelity against bandwidth constraints, with Meta Platforms and competing platforms optimizing compression algorithms for 5G throughput.
Training Simulations dominates enterprise expenditure; Telehealth climbs the fastest as reimbursement frameworks mature.
Technology:
Compute location—on-headset, tethered workstation, or remote edge—determines hardware refresh economics and content portability.
- Standalone:All-in-one headsets with integrated Snapdragon XR processors eliminate cable constraints. Qualcomm Technologies anchors premium performance tiers while cost-optimized alternatives capture education and retail pilots.
- Tethered:PC-dependent systems retain dominance in high-fidelity simulation where zero-latency tolerance justifies workstation investment. Automotive design studios in Stuttgart maintain tethered workflows for collaborative engineering reviews.
- Cloud-based:Render-to-stream architectures compress hardware cycles from three years to eighteen months as computational load shifts off-device.
- Mobile:Smartphone-dependent headsets leverage existing device penetration for lowest entry cost, limiting performance to handset thermal and display constraints.
Standalone leads on scale; Cloud-based leads on momentum.
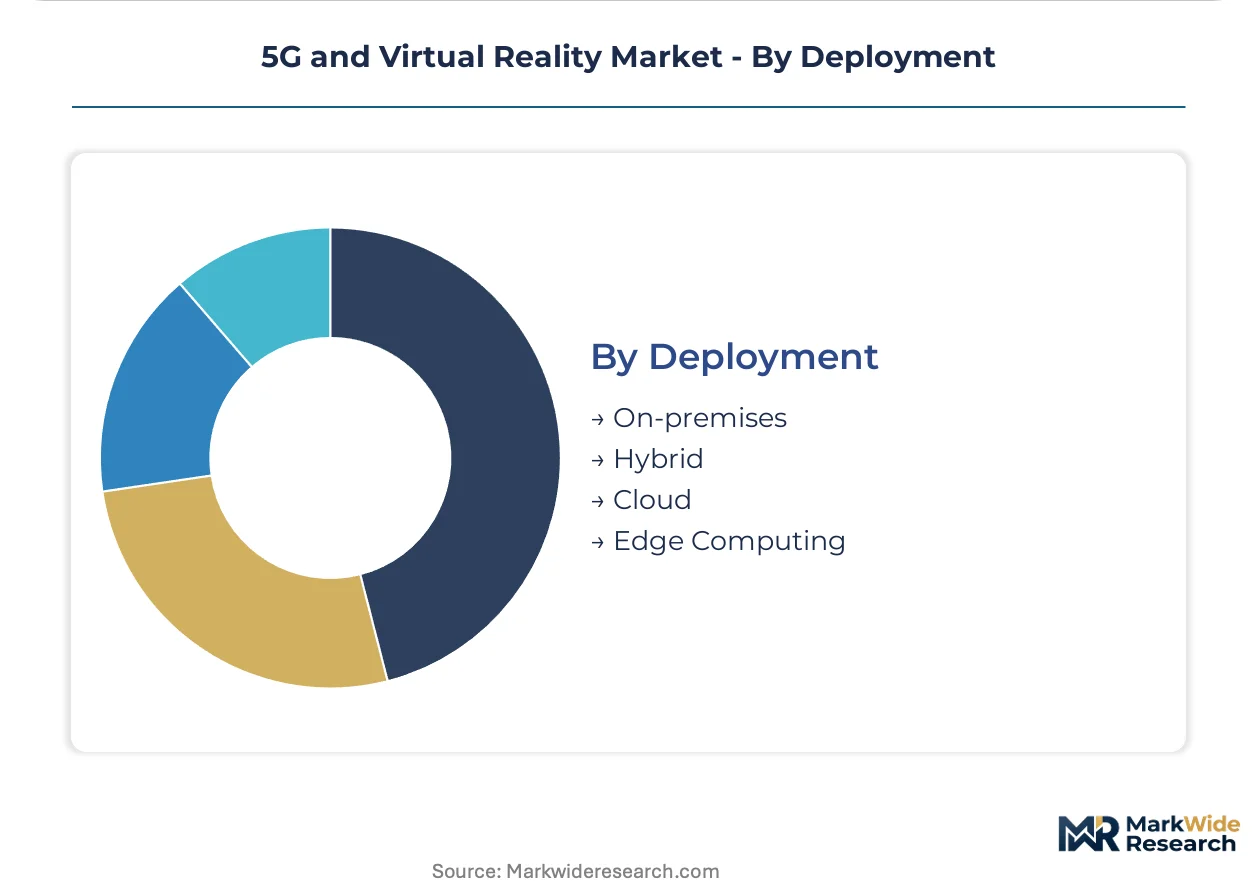
Deployment:
Data sovereignty requirements and latency floors determine whether enterprises self-host, hybridize, or fully outsource infrastructure.
- On-premises:Defense and critical infrastructure operators maintain air-gapped VR training environments with zero external data exposure. Capital intensity limits adoption to security-sensitive verticals.
- Hybrid:Sensitive rendering on local edge with non-critical content streaming from cloud balances performance against compliance. German manufacturers favor this architecture for IP protection.
- Cloud:Fully outsourced infrastructure minimizes IT overhead for pilot programs and seasonal demand spikes. GDPR and China's data localization rules fragment hosting architectures.
- Edge Computing:Multi-access edge nodes co-located with 5G base stations compress render-to-display latency below nausea thresholds. Carrier-managed service bundles are capturing recurring revenue in corporate training.
Cloud leads on scale; Edge Computing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spatial computing talent clusters in Shenzhen, Seoul, and San Jose anchor investment flows into 5G VR infrastructure. National broadband strategies and industrial digitalization mandates reshape procurement patterns across major economies.
United States
Enterprise training budgets and defense simulation contracts drive procurement volume. FCC Part 96 rules tighten latency standards for 3.5 GHz CBRS bands, accelerating carrier infrastructure investment. Seattle hosts Microsoft's mixed reality engineering operations alongside Qualcomm's XR chipset development in San Diego.
China
MIIT-enforced GB standards for network equipment interoperability compress vendor certification timelines. State-backed 5G rollout targets industrial parks in Guangdong and Jiangsu provinces. Shenzhen's electronics manufacturing ecosystem supplies component modules for standalone headsets.
Germany
Industry 4.0 frameworks compel manufacturers to deploy VR-enabled remote maintenance over 5G private networks. KBA and federal economic ministries coordinate safety certification for automotive simulation applications. Stuttgart's automotive design studios maintain tethered workflows for collaborative engineering reviews.
Japan
METI subsidies for industrial digitalization anchor demand for low-latency edge infrastructure. PMDA and the Ministry of Health, Labour and Welfare approved procedural codes for VR-assisted rehabilitation, accelerating clinical adoption. Tokyo's esports venues deploy private network slices for tournament-grade latency.
South Korea
MFDS standards for medical device software intersect with 5G VR telehealth deployments. National 5G spectrum allocation prioritized industrial zones in Gyeonggi Province. Seoul Capital Area carriers bundle edge computing nodes with enterprise training subscriptions.
5G and Virtual Reality Market Competitive Environment
Top-tier vendors anchor premium performance tiers through integrated chipset-headset ecosystems, while cost-optimized hardware specialists compete on volume penetration. The market structures around three strategic archetypes: semiconductor platform providers, consumer electronics conglomerates, and cloud-native software stacks. Dominant competitive moves include carrier-managed service bundling and backward integration into edge infrastructure.
Within the semiconductor platform tier, Qualcomm Technologies and NVIDIA occupy positions defining rendering performance standards for standalone and cloud-streamed architectures. Meta Platforms exemplifies the consumer-scale archetype, competing aggressively on hardware volume against Samsung Electronics, which anchors integrated smartphone-to-headset ecosystems. Microsoft represents the enterprise software stack archetype, leveraging cloud infrastructure for hybrid deployment models.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Microsoft |
| Samsung Electronics |
| Sony |
| Meta Platforms |
| NVIDIA |
| Huawei Technologies |
| HTC |
| Others |
Value Chain & Pricing Dynamics
Cloud-native XR streaming is compressing hardware refresh cycles from three years to eighteen months while simultaneously shifting margin pools toward edge infrastructure operators and away from discrete headset manufacturers. This transition concentrates pricing power with carriers managing 5G network slices and edge computing nodes, fragmenting procurement authority across IT infrastructure teams and departmental experiential budgets.
Pricing Analysis
Bundled carrier-managed service offerings diverge sharply from unbundled hardware-plus-software procurement across enterprise verticals. Subscription-based hardware access is displacing outright purchase in healthcare and corporate training, with three-tier pricing structure across premium, standard, and economy levels anchored to latency guarantees and edge node proximity. Price differentiation rests on certification grade for medical device software under MFDS and PMDA frameworks versus consumer-grade entertainment tiers. Cost compression in mass-consumer headsets is intensifying because Meta Platforms and cost-optimized specialists compete aggressively on volume penetration. Education and K-12 institutions exhibit highest price sensitivity, while reimbursed healthcare applications show lowest elasticity due to procedural code anchoring.
Supply Chain Analysis
India's PLI scheme for electronics and China's MIIT-enforced localization mandates are reshaping component sourcing strategies for 5G VR hardware assembly. Advanced XR chip fabrication concentrates in Taiwan and South Korea, exposing headset manufacturers to geopolitical disruption in wafer supply chains. Raw material dependencies span gallium nitride for RF front-ends, high-brightness micro-OLED displays, and rare-earth elements for precision actuators. Single-source vulnerability in Snapdragon XR platform supply creates bottleneck risk for premium standalone tiers. Distribution runs through carrier-managed enterprise service bundles and consumer electronics retail channels, with direct-to-enterprise channel expansion capturing recurring revenue in corporate training verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme offers 4-6 percentage point effective cost advantages against China's dual carbon compliance burdens and EU AI Act transparency obligations.
For Market Incumbents: Deploy backward integration into edge infrastructure to capture recurring revenue streams escaping hardware commoditization. Qualcomm Technologies and NVIDIA should deepen captive supply of rendering acceleration silicon to defend margin position against ARM-based alternatives. Carrier-managed service bundling offers defensive moat construction against cloud-native software stack entrants threatening hybrid deployment dominance. For New Entrants and Emerging Players: The premium-to-economy price-point gap in enterprise training hardware exceeds three hundred percent, creating white-space opportunity for mid-tier specialists. India's contract manufacturing ecosystem offers lowest-cost assembly capacity for cost-optimized education and retail pilots. Target K-12 institutional procurement with smartphone-dependent mobile headsets leveraging existing device penetration, bypassing premium standalone development costs entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among cloud-native XR streaming platforms with proven carrier distribution partnerships. Long-term viability over the five-to-ten year horizon hinges on successful migration from hardware transactional models to recurring infrastructure services. Acquisition target archetype: multi-access edge computing operators with co-located 5G base station relationships. The signal to watch is reimbursement framework expansion beyond Japan's Ministry of Health, Labour and Welfare approvals into additional procedural code jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier-Managed Service Bundling | Captures recurring revenue streams in corporate training verticals through 5G network slice provisioning. |
| Backward Integration into Edge Infrastructure | Qualcomm and NVIDIA anchor rendering performance standards by controlling multi-access edge node deployment. |
| Medical Device Software Certification | MFDS and PMDA approvals unlock reimbursed healthcare applications with premium pricing tiers. |
| Cloud-Native XR Streaming Architecture | Automotive design studios in Stuttgart eliminate workstation tethering through render-to-stream migration. |
| Production-Linked Incentive Localization | India's PLI scheme attracts contract manufacturers establishing 5G VR hardware assembly capacity. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carrier network planning officers, healthcare procurement committees, industrial training directors, and semiconductor platform engineers alongside secondary validation. Sources included FCC Part 96 licensing databases, MIIT GB standard filings, METI subsidy disbursement records, and hyperscaler edge computing capex disclosures. Bottom-up unit economics and top-down sectoral expenditure models were triangulated against carrier service bundle pricing and enterprise procurement database benchmarks.
Comparable-period anchoring linked projection horizons to historical 5G deployment cycles and VR hardware refresh trajectories across the modeling period. Segmentation dimensions spanned end-user vertical, compute location architecture, deployment topology, and regional regulatory cluster. CAGRs were derived from slope-intercept modeling of edge infrastructure investment curves and reimbursement framework adoption trajectories. Forecast inputs incorporated network slicing maturity indices and spatial computing talent availability by metropolitan cluster.
Caveats apply where spectrum auction outcomes, semiconductor supply disruptions, or cross-jurisdictional content compliance fragmentation could materially shift the outlook. Forecasts reflect documented assumptions around carrier capital commitment timelines and clinical validation completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market