
 China Post-Traumatic Stress Disorder Treatment Market | 2026-2036
China Post-Traumatic Stress Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
China Post-Traumatic Stress Disorder Treatment Market Insights
Multi-source API procurement is decoupling from sole reliance on imported active pharmaceutical ingredients for PTSD medications in China. Pfizer Inc. leverages its established psychiatry portfolio to sustain brand recognition among hospital formulary committees. Eli Lilly and Company differentiates through its neuroscience R&D footprint, while Sun Pharmaceutical Industries anchors cost-competitive generic manufacturing for domestic volume.
Post-traumatic stress disorder treatment encompasses psychotherapeutic interventions and pharmacological management targeting trauma-related dysregulation of the hypothalamic-pituitary-adrenal axis, with SSRIs constituting first-line pharmacotherapy due to their modulation of serotonin transporter activity. Cognitive Behavioral Therapy occupies the dominant position within therapy type segmentation owing to its established reimbursement codes and clinician training infrastructure. Teletherapy represents the fastest-expanding delivery mode as internet hospital licenses proliferate under NHC directives, while SSRIs command the largest medication type revenue pool despite generic erosion.
NMPA oversees novel drug approvals and bioequivalence standards for PTSD therapeutics, while the National Health Commission governs clinical practice guidelines and hospital-based mental health service expansion. NMPA's accelerated review pathways for innovative psychiatric compounds directly shape which manufacturers secure priority market access. Stakeholders must monitor evolving digital therapeutics classification rules as SAMR develops frameworks distinguishing medical software from wellness applications.
Market Dynamics
NMPA's accelerated review pathways for novel psychiatric compounds are compressing approval timelines from five years to eighteen months, forcing domestic manufacturers to upgrade bioequivalence capabilities or cede priority hospital access to multinational entrants.
Growth Catalysts
- Teletherapy infrastructure:Internet hospital licenses under NHC directives are extending PTSD care beyond tier-three hospital catchments into second-tier cities lacking specialized psychiatric departments.
- Military screening mandates:People's Liberation Army mental health protocols now require annual PTSD assessments for combat-exposed personnel, institutionalizing demand for both pharmaceutical and psychotherapeutic interventions.
- API localization:Domestic manufacturers are securing multi-source supply chains for SSRI active ingredients, reducing import dependency and stabilizing formulary pricing for hospital procurement committees.
Market Restraints
- Specialist workforce scarcity:China counts fewer than 50,000 licensed psychiatrists against a population exceeding 1.4 billion, creating bottlenecks at specialized PTSD clinics in Beijing and Shanghai.
- Reimbursement code limitations:Cognitive Behavioral Therapy sessions remain capped at twelve annually under basic medical insurance, forcing out-of-pocket payment for extended treatment protocols.
- Generic erosion pressure:Patent expiration for established SSRIs has triggered price competition that compresses margins for originator brands while NMPA bioequivalence standards tighten manufacturing compliance costs.
Strategic Opportunities
- Digital therapeutics classification:SAMR's developing framework distinguishing medical software from wellness applications will clarify reimbursement pathways for AI-guided exposure therapy platforms.
- Veteran community penetration:Retired PLA personnel concentrated in provincial capitals represent an underpenetrated cohort with established healthcare access through military hospital networks.
- Integration of pharmacogenomic testing:Convergence of SSRI prescribing with CYP2D6 metabolizer screening enables personalized dosing protocols that differentiate premium service tiers in private psychiatric clinics.
Industry Challenges
- Clinician training standardization:Trauma-focused CBT certification programs remain fragmented across provincial medical universities, producing uneven treatment fidelity in community health centers.
- Data interoperability:Electronic health record systems deployed by internet hospitals lack standardized trauma-history documentation fields, complicating longitudinal outcome tracking across care settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Post-Traumatic Stress Disorder Treatment Market |
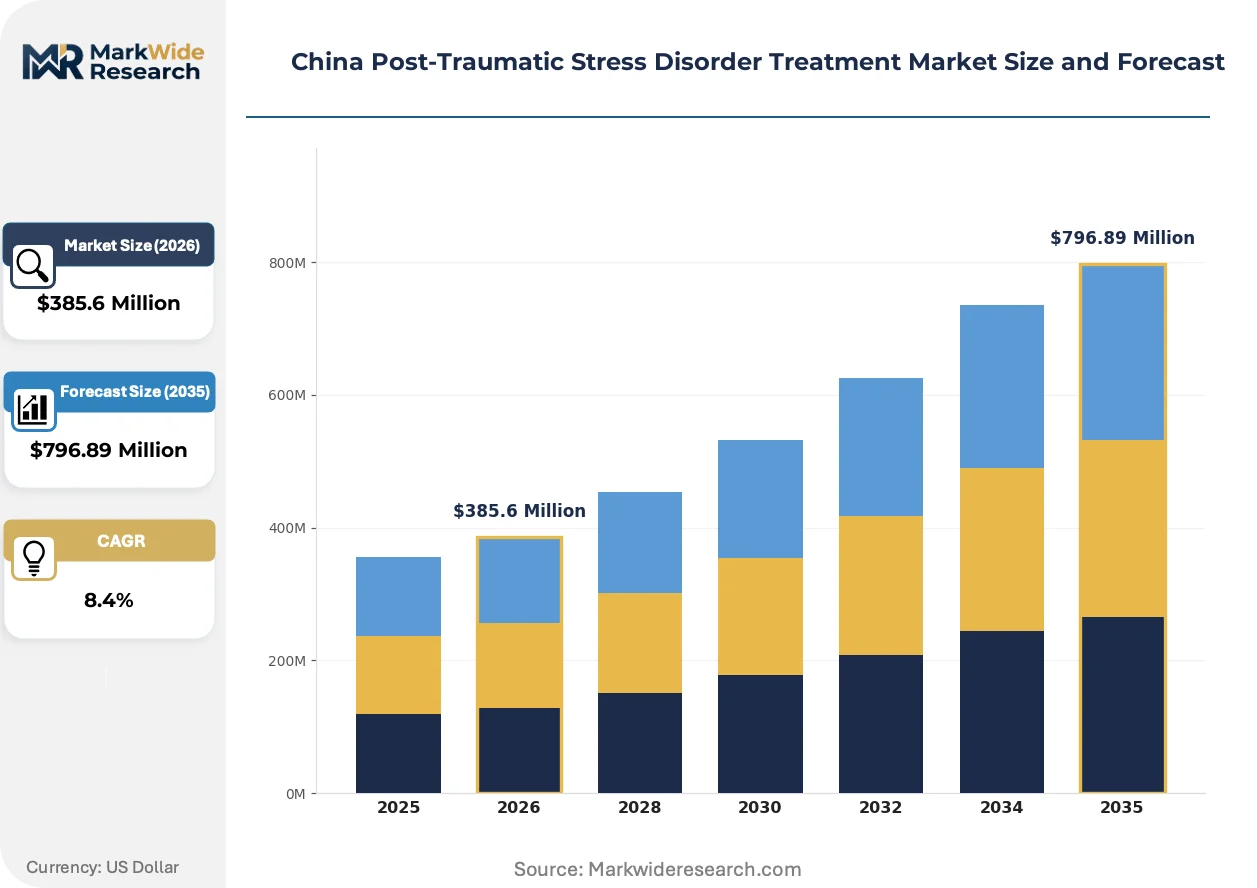
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cognitive Behavioral Therapy, Eye Movement Desensitization and Reprocessing, Exposure Therapy, Psychodynamic Therapy Patient Type: Military Veterans, First Responders, Survivors of Abuse, General Population Delivery Mode: In-Person, Online Counseling, Group Therapy, Teletherapy Medication Type: SSRIs, SNRIs, Antipsychotics, Benzodiazepines |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Otsuka Pharmaceutical, Aurobindo Pharma, Lupin, Sun Pharmaceutical Industries, Novartis International AG, Jazz Pharmaceuticals, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Post-Traumatic Stress Disorder Treatment Market Trends and Innovations
Biomarker-guided patient stratification is displacing trial-and-error prescribing in PTSD pharmacotherapy, with cortisol awakening response testing and functional MRI patterns enabling targeted SSRI selection before treatment initiation.
Virtual reality exposure therapy is consolidating its position as the dominant technology for controlled trauma reprocessing in military and first-responder populations. PLA rehabilitation hospitals are deploying combat scenario simulations at scale, compressing the traditional twelve-week CBT protocol into intensive four-week modules that reduce inpatient bed days and accelerate return-to-duty clearances.
NMPA's 2023 guidelines on conditional approval for innovative psychiatric drugs are accelerating market entry for novel mechanisms targeting the hypothalamic-pituitary-adrenal axis. Domestic biotechnology firms are responding by prioritizing glucocorticoid receptor modulators in their pipelines, while multinational sponsors are relocating Phase II PTSD trials to Chinese sites to leverage the streamlined pathway.
Hospital formulary committees are consolidating procurement authority for PTSD medications at the provincial level, displacing individual hospital purchasing autonomy. This concentration enables volume-based pricing negotiations with manufacturers but requires domestic suppliers to establish dedicated key account management teams in Chengdu, Xi'an, and Wuhan where provincial health commissions coordinate tier-three hospital networks.
China Post-Traumatic Stress Disorder Treatment Market Segmentation
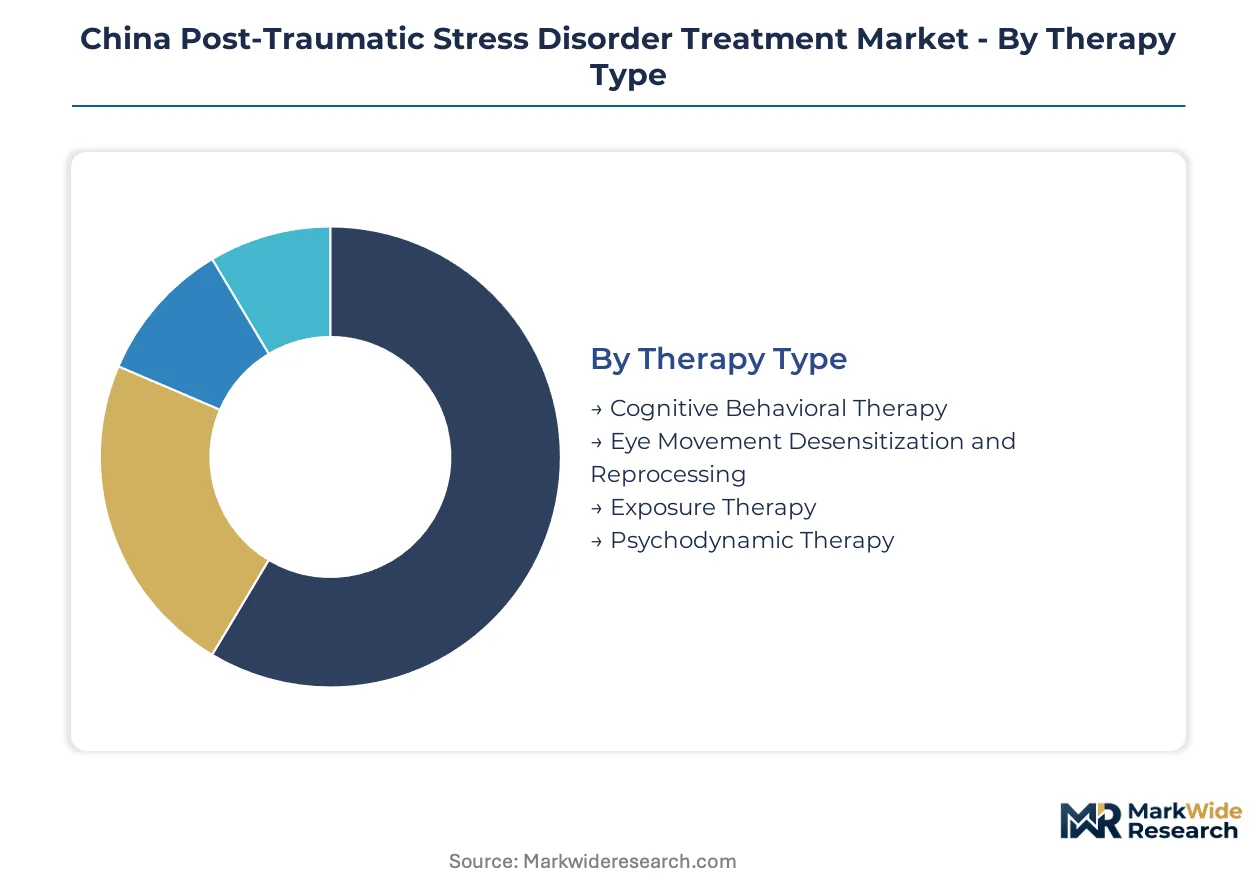
PTSD treatment in China fragments across therapeutic modality, patient cohort, delivery infrastructure, and pharmacological mechanism. Each segmentation axis carries distinct regulatory, reimbursement, and competitive implications that shape manufacturer and provider strategies.
Therapy Type:
Cognitive Behavioral Therapy anchors the therapeutic infrastructure through its established efficacy protocols and NHC reimbursement coding, while Eye Movement Desensitization and Reprocessing gains traction in military rehabilitation hospitals where trauma reprocessing speed drives operational outcomes.
- Cognitive Behavioral Therapy:Structured protocols targeting maladaptive trauma cognitions through cognitive restructuring and behavioral activation. Beijing and Shanghai tier-three hospitals concentrate demand as provincial medical universities standardize CBT certification curricula under NHC directives.
- Eye Movement Desensitization and Reprocessing:Bilateral stimulation techniques accelerating memory reconsolidation. PLA rehabilitation centers in Chengdu and Xi'an drive adoption where compressed treatment timelines support return-to-duty metrics for combat-exposed personnel.
- Exposure Therapy:Graduated confrontation with trauma cues through imaginal and in-vivo techniques. Virtual reality variants are expanding in first-responder programs.
- Psychodynamic Therapy:Long-term exploration of unconscious conflict patterns. Limited penetration outside private psychiatric clinics in Guangzhou and Shenzhen due to reimbursement gaps.
Cognitive Behavioral Therapy leads on scale; Eye Movement Desensitization and Reprocessing leads on momentum.
Patient Type:
Cost tier stratification separates institutionalized demand from out-of-pocket markets, with military and first-responder channels commanding dedicated procurement budgets while abuse survivors and general population segments navigate fragmented insurance coverage.
- Military Veterans:Retired PLA personnel accessing care through military hospital networks and provincial veteran affairs bureaus. Annual screening mandates under PLA mental health protocols institutionalize pharmaceutical and psychotherapeutic demand across 31 provincial capitals.
- First Responders:Fire, police, and emergency medical personnel exposed to occupational trauma. Municipal public security bureaus in Beijing, Shanghai, and Guangzhou pilot employer-funded EAP programs.
- Survivors of Abuse:Domestic violence and childhood trauma survivors. Women's federations and civil society organizations bridge referral gaps where basic medical insurance coverage remains incomplete.
- General Population:Civilian trauma exposure including accidents and natural disasters. Demand concentrates in urban centers with established psychiatric departments.
Military Veterans lead on scale; First Responders lead on momentum.
Delivery Mode:
Volume concentration tracks internet hospital licensing density, with telehealth infrastructure extending reach beyond tier-three hospital catchments while in-person modalities retain dominance for complex trauma presentations.
- In-Person:Face-to-face therapeutic encounters in hospital and clinic settings. Tier-three psychiatric departments in Beijing, Shanghai, and Chengdu concentrate capacity where specialist workforce scarcity creates appointment bottlenecks.
- Teletherapy:Synchronous video-based clinical delivery. Internet hospital licenses under NHC directives enable expansion into second-tier cities lacking specialized psychiatric infrastructure.
- Online Counseling:Asynchronous text and messaging platforms. SAMR's evolving medical software classification creates regulatory uncertainty for AI-guided interventions.
- Group Therapy:Cohort-based trauma processing in structured settings. PLA rehabilitation hospitals deploy intensive four-week modules compressing traditional twelve-week protocols.
In-Person leads on scale; Teletherapy leads on momentum.
Medication Type:
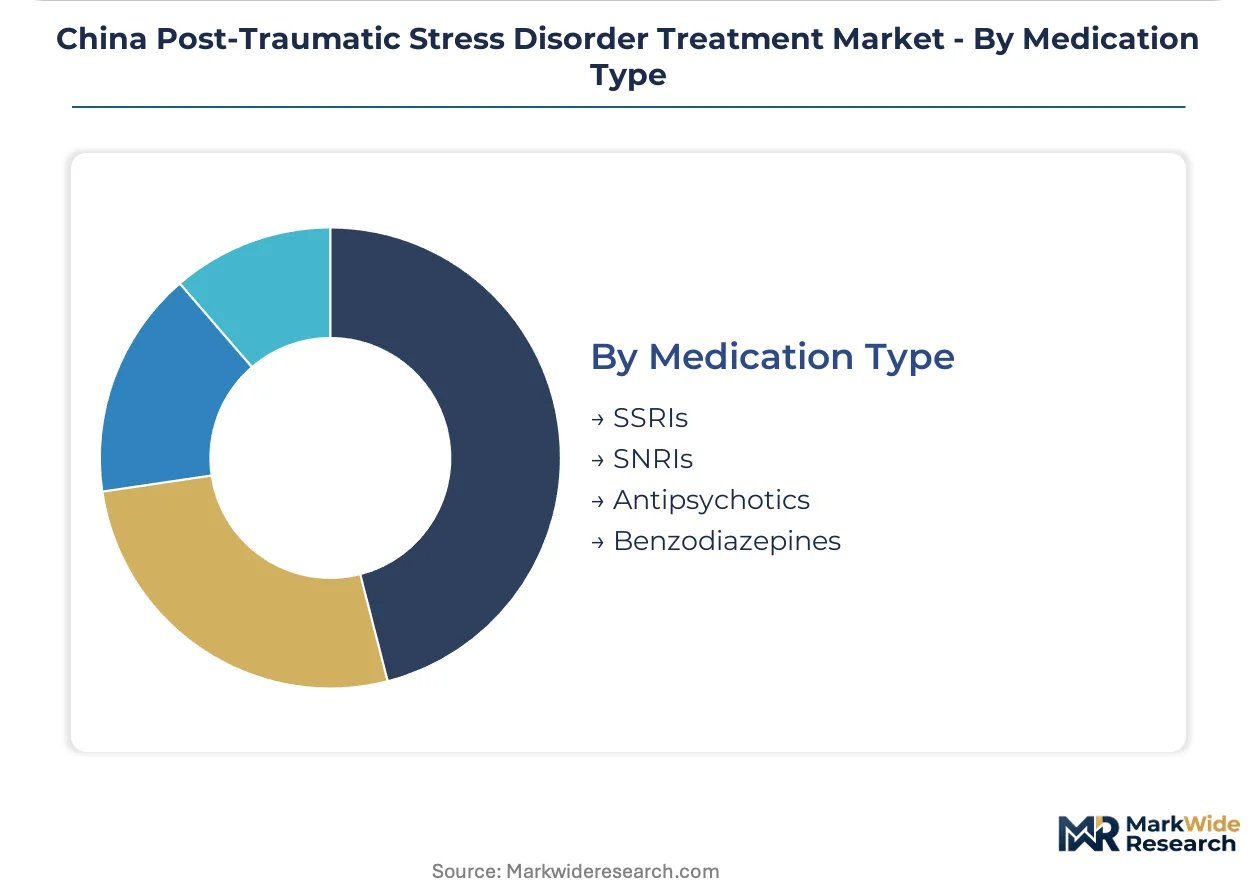
Margin structure differentiates between mature generic categories and novel mechanisms, with SSRI commoditization pressuring originator brands while SNRIs and atypical antipsychotics defend premium positioning through bioequivalence complexity.
- SSRIs:Selective serotonin reuptake inhibitors modulating synaptic serotonin availability. Domestic API localization for fluoxetine and sertraline active ingredients reduces import dependency and stabilizes hospital procurement pricing.
- SNRIs:Serotonin-norepinephrine reuptake inhibitors targeting dual monoamine pathways. Venlafaxine and duloxetine formulations retain formulary preference where SSRI non-response drives second-line prescribing.
- Antipsychotics:Atypical agents addressing hyperarousal and intrusive symptoms. Quetiapine and risperidone adjunctive use expands in severe PTSD presentations.
- Benzodiazepines:Short-term anxiolytic management of acute hyperarousal. NMPA prescribing restrictions limit chronic utilization due to dependence liability.
SSRIs lead on scale; SNRIs lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in PTSD treatment are concentrating pharmaceutical manufacturing in jurisdictions where NMPA compliance costs remain below FDA or EMA thresholds, while provincial health commissions in China leverage this cost gap to expand specialized psychiatric infrastructure.
Beijing-Tianjin-Hebei
Military hospital networks and veteran affairs bureaus anchor demand from retired PLA personnel. NHC directives mandate annual PTSD screening protocols that institutionalize pharmaceutical procurement. Tier-three hospitals in Beijing concentrate specialized psychiatric capacity where fewer than 50,000 licensed psychiatrists serve the national population.
Yangtze River Delta
Shanghai's municipal public security bureaus pilot employer-funded EAP programs for first responders exposed to occupational trauma. SAMR's evolving digital therapeutics classification creates regulatory clarity for internet hospital licenses. Hangzhou and Nanjing internet hospitals extend teletherapy reach into second-tier cities lacking psychiatric departments.
Pearl River Delta
Private psychiatric clinics in Guangzhou and Shenzhen absorb out-of-pocket demand where basic medical insurance caps CBT sessions at twelve annually. NMPA accelerated review pathways compress novel drug approval timelines from five years to eighteen months. Domestic biotechnology firms prioritize glucocorticoid receptor modulators in development pipelines.
Sichuan-Chongqing
PLA rehabilitation centers in Chengdu deploy virtual reality exposure therapy for combat scenario simulations. Provincial health commissions consolidate procurement authority for PTSD medications at the provincial level. Xi'an military hospitals drive adoption of Eye Movement Desensitization and Reprocessing where compressed treatment timelines support return-to-duty metrics.
China Post-Traumatic Stress Disorder Treatment Market Competitive Landscape
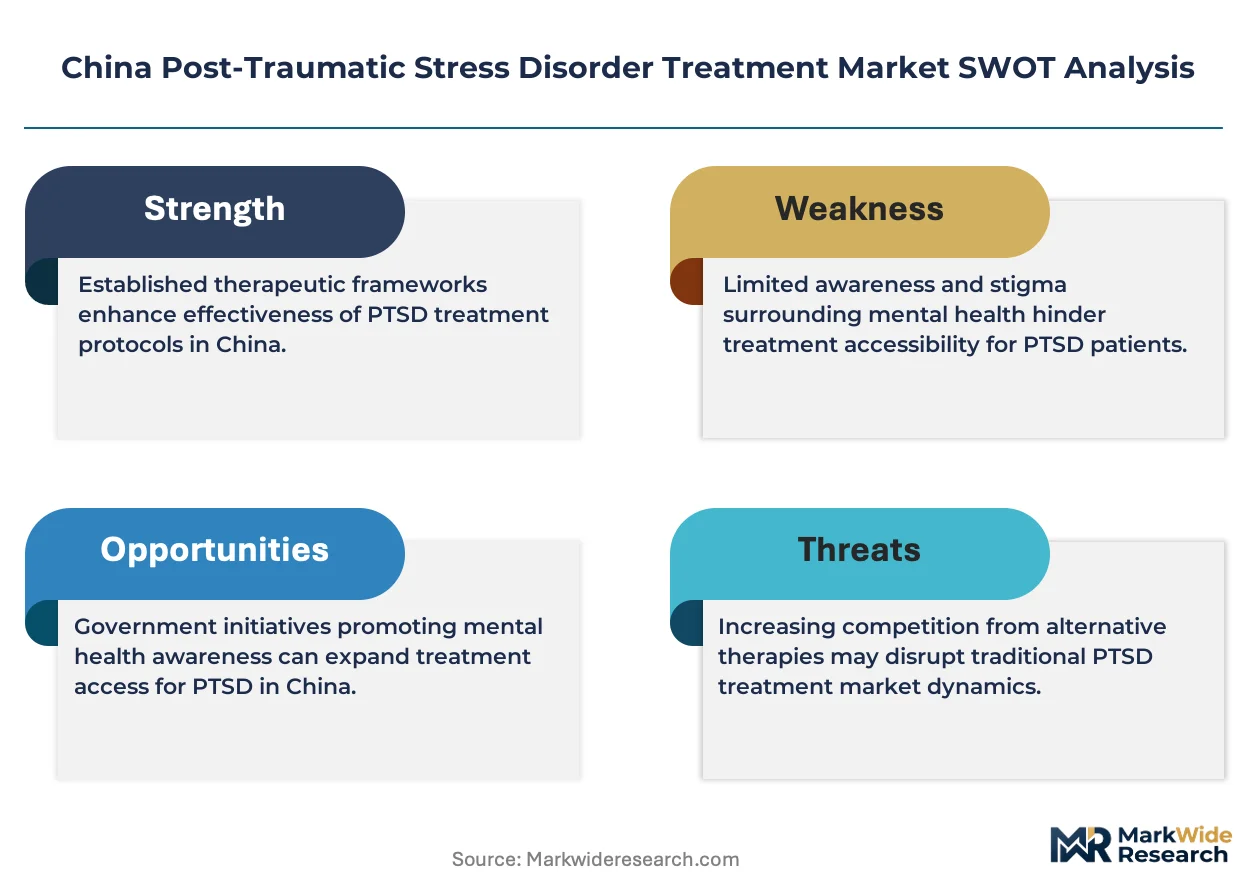
Established producers occupy the standard tier; emerging entrants pursue novel mechanism development under NMPA conditional approval frameworks. The market structures around three tiers: multinational originators defending brand recognition through psychiatry portfolio breadth, domestic manufacturers anchoring cost-competitive generic volumes, and biotechnology specialists targeting glucocorticoid receptor modulation. Strategic moves concentrate on provincial procurement consolidation and bioequivalence capability upgrades.
Among multinational pharmaceutical sponsors, Pfizer Inc. and Eli Lilly and Company occupy positions where established hospital formulary relationships sustain access priority. Sun Pharmaceutical Industries exemplifies the domestic generic archetype through cost-competitive manufacturing scale. These three anchors represent distinct competitive vectors: originator brand defense, neuroscience R&D specialization, and API localization for hospital procurement stability.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Otsuka Pharmaceutical |
| Aurobindo Pharma |
| Lupin |
| Sun Pharmaceutical Industries |
| Novartis International AG |
| Jazz Pharmaceuticals |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient spot indices for fluoxetine and sertraline cascade through three distinct pricing tiers, with domestic manufacturers leveraging multi-source procurement to compress formulary bids while originator brands defend hospital access through bioequivalence certification premiums.
Pricing Analysis
Input-cost pass-through from API localization is reshaping procurement negotiations. Contract-based long-term offtake agreements anchor volume procurement for tier-three hospital networks, with price differentiation resting on NMPA bioequivalence certification status and vertical integration depth. Generic erosion intensifies cost compression in the SSRI category as patent expirations trigger price competition. Domestic manufacturers exhibit highest price sensitivity, while multinational originators retain leverage in SNRI and novel mechanism segments where bioequivalence complexity defends premium positioning.
Supply Chain Analysis
Reverse-logistics flows for expired psychiatric medications remain underdeveloped, constraining API recovery rates from hospital formulary returns. Manufacturing concentration centers on India and China for SSRI active ingredients, with secondary sourcing from Italy for specialized excipients. Supply chains draw from cortisol assay reagents, serotonin precursor compounds, and virtual reality hardware components. Single-source vulnerability characterizes the CYP2D6 metabolizer testing kit segment. Distribution runs through provincial health commission consolidation points before hospital pharmacy allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on API localization cost-down trajectories and the shift toward pharmacogenomic-guided premium service tiers in private psychiatric clinics.
For Market Incumbents: Anticipate NMPA bioequivalence standard tightening by upgrading manufacturing capabilities or securing priority review status for novel mechanisms. Defend hospital formulary positioning through dedicated key account management teams in provincial capitals where procurement authority concentrates. Vertical integration into domestic API production anchors cost-competitive bidding for volume contracts. For New Entrants and Emerging Players: Capture the veteran community penetration opportunity in provincial capitals outside Beijing and Shanghai, where retired PLA personnel access care through military hospital networks with established procurement budgets. Target teletherapy infrastructure gaps in second-tier cities lacking specialized psychiatric departments. A go-to-market angle centered on AI-guided exposure therapy platforms awaits SAMR digital therapeutics classification clarity. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic biotechnology firms prioritizing glucocorticoid receptor modulators under NMPA conditional approval frameworks. Long-term viability favors developers with integrated pipelines spanning biomarker-guided patient stratification and novel mechanism compounds. Monitor NMPA accelerated review pathway admission rates as the inflection indicator for pipeline value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Relocation of Phase II PTSD trials to Chinese sites leverages NMPA streamlined pathways. |
| Regulatory Approval Pathway | NMPA conditional approval for glucocorticoid receptor modulators compresses market entry timelines. |
| Manufacturing Scale-Up | Domestic API localization for SSRI ingredients reduces import dependency and stabilizes procurement pricing. |
| Strategic Partnership | Internet hospital licenses under NHC directives extend teletherapy reach into underserved second-tier cities. |
| Pipeline Diversification | Integration of pharmacogenomic testing with SSRI prescribing enables personalized dosing premium tiers. |
Research Methodology
Bottom-up patient volume modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core of this study. Primary interviews with hospital formulary directors, NMPA regulatory affairs specialists, PLA mental health protocol officers, and provincial health commission procurement managers combined with secondary validation from NMPA drug approval databases, ClinicalTrials.gov PTSD trial registrations, and hospital procurement disclosure records. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of antidepressant prescribing patterns and psychotherapy reimbursement code utilization established baseline trajectories. The analytical framework projects across therapy type, patient cohort, delivery mode, and medication mechanism dimensions throughout the forecast period. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate NMPA review pathway admission rates and internet hospital license proliferation under NHC directives.
Underlying measurement precision varies by segment; military veteran and teletherapy categories carry tighter precision than general population and psychodynamic therapy segments due to data availability from institutional procurement systems. Forecasts reflect assumptions regarding NMPA regulatory continuity and PLA screening mandate persistence. Practitioners should monitor SAMR digital therapeutics classification developments and provincial procurement consolidation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Mental Health Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
US Behavioral Health Market