
 Brazzein Market | 2026-2036
Brazzein Market Size, Share, and Industry Trends Forecast 2026-2036
Brazzein Market Analysis
Specialty ingredient distribution is reconfiguring around biotechnology-derived sweeteners as traditional sugar substitutes face scrutiny. Ingredion Incorporated leverages its global ingredient network to secure early commercial partnerships for brazzein. Sweegen anchors its position through precision fermentation scale-up, while Cargill competes via integrated supply chains spanning stevia to emerging proteins. Tate & Lyle PLC differentiates through formulation expertise that blends brazzein with modulators for taste optimization.
Brazzein is a high-intensity sweet protein derived from the West African fruit Pentadiplandra brazzeana, exhibiting approximately 2,000 times the sweetness of sucrose with remarkable heat stability above 80°C and a clean, sugar-like temporal profile. Powder formulations currently dominate commercial supply due to superior shelf stability and ease of integration into dry mixes, while liquid concentrates represent the fastest-growing segment as beverage producers seek pumpable, batch-consistent inputs. Natural extracts command premium positioning among organic-certified end users, though synthetic variants produced via microbial fermentation are capturing volume in cost-sensitive applications across mainstream food manufacturing.
The FDA's GRAS self-affirmation process shapes US market entry timelines for novel sweet proteins, while the EPA monitors fermentation facility emissions compliance for biomanufacturing scale-up. The European Food Safety Authority's novel food authorization under Regulation 2015/2283 creates a parallel compliance pathway that European suppliers must navigate for brazzein commercialization. Stakeholders should monitor fermentation yield breakthroughs and evolving clean-label certification standards as the primary variables determining competitive positioning in this emerging category.
Market Dynamics
Precision fermentation scale-up is compressing production timelines for high-intensity sweet proteins, collapsing the traditional agricultural dependency that constrained supply elasticity for natural sweeteners.
Growth Catalysts
- GRAS Self-Affirmation Pathway:The FDA's streamlined notification process accelerates novel protein approvals, reducing commercialization lag for fermentation-derived brazzein versus full food additive petitions.
- Beverage Clean-Label Mandates:Major soft drink and functional drink manufacturers are reformulating around biotechnology-derived sweeteners to replace artificial alternatives facing consumer scrutiny.
- Heat-Stable Protein Engineering:Advanced strain optimization is unlocking brazzein variants that maintain sweetness integrity above 80°C, opening baked goods and retort applications previously closed to protein sweeteners.
Market Restraints
- Feedstock Cost Volatility:Precision fermentation depends on glucose and nitrogen sources tied to agricultural commodity swings, compressing margin predictability at commercial scale.
- Biomanufacturing Concentration Risk:Contract fermentation capacity clusters in the United States and select European biotech hubs, creating geographic supply vulnerability for new market entrants.
- Novel Food Authorization Friction:EFSA's Regulation 2015/2283 pathway demands extensive toxicology dossiers, extending European market entry timelines 18-36 months beyond US availability.
Strategic Opportunities
- India Functional Beverage White Space:FSSAI's evolving novel food framework and surging middle-class sugar reduction demand create first-mover potential for brazzein-sweetened regional formulations.
- Pharmaceutical Excipient Convergence:Combination with taste-masking applications for pediatric and geriatric drug delivery represents an adjacent revenue stream untapped by incumbent sweetener suppliers.
- Direct-to-Manufacturer Digital Channels:Specialty ingredient platforms are bypassing traditional distributor markups, enabling price transparency and sample-to-contract velocity for mid-scale food producers.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Commercial-scale fermentation expertise specific to heterologous protein expression remains concentrated among a limited pool of specialists, inflating compensation and retention costs.
- Downstream Purification Bottlenecks:Chromatography and membrane filtration capacity for food-grade protein isolation is lagging fermentation scale-up, creating yield loss and quality variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazzein Market |
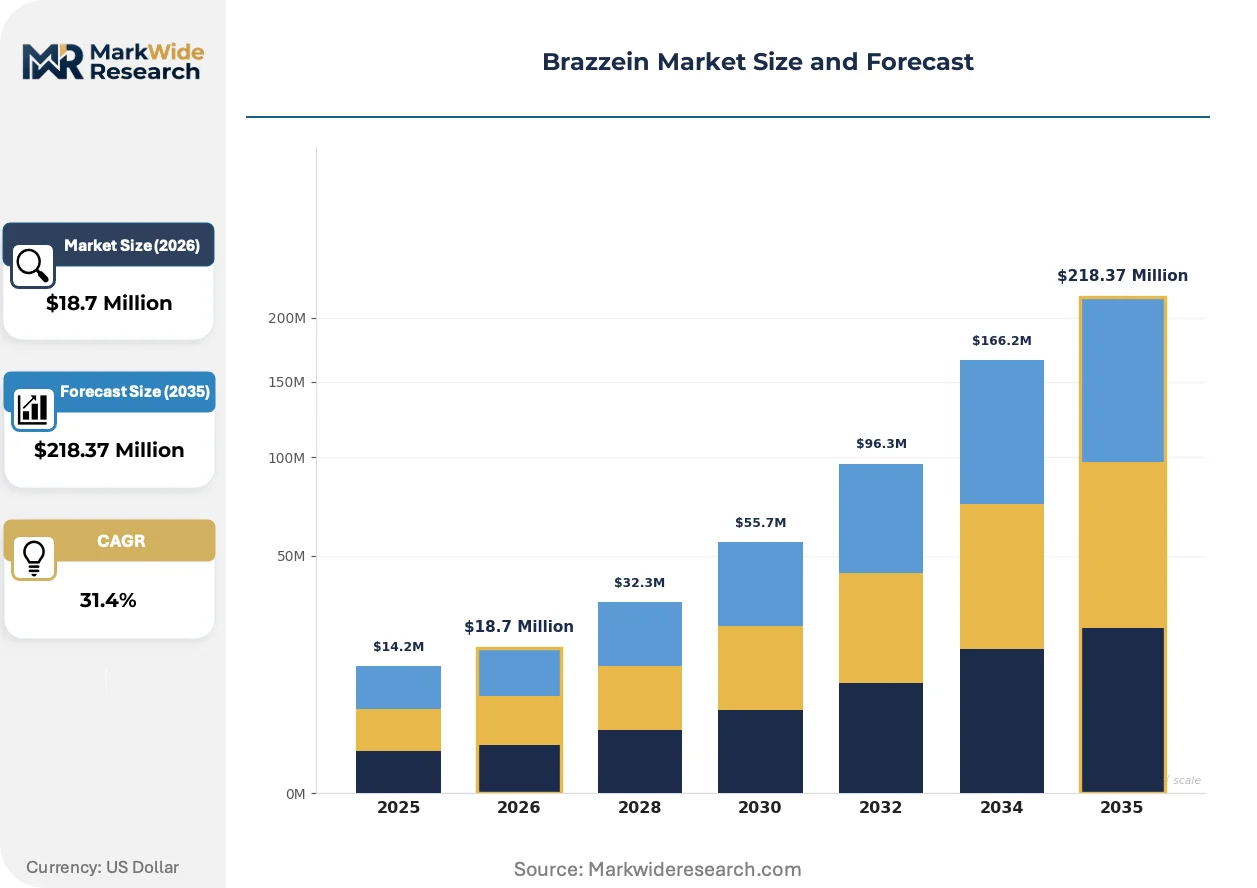
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Tablets Application: Food Industry, Beverage Production, Pharmaceuticals, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Food Service Formulation: Natural Extracts, Synthetic Variants, Blended Compounds, Concentrates |
| Companies Covered | Ingredion Incorporated, Sweegen, Archer Daniels Midland Company, Magellan Life Sciences, Senomyx, Cargill, Roquette Frères, Natur Research Ingredients, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazzein Market Emerging Trajectories
Computational protein design and continuous bioprocessing are converging to reshape how high-intensity sweeteners enter commercial supply chains, collapsing the traditional trade-off between natural positioning and manufacturing scalability.
Precision fermentation platforms are virtualizing the agricultural cultivation step entirely, replacing West African fruit harvesting with microbial cell factories in controlled bioreactor environments. Beverage and confectionery formulators are adopting these inputs at pilot scale, with several multinational manufacturers running parallel validation batches. This virtualization is compressing the geographic and seasonal constraints that historically limited natural sweetener supply security.
EFSA's tightening novel food dossier requirements under evolving implementation guidance is extending authorization timelines for fermentation-derived proteins entering European commerce. The industrial consequence is a sequential market entry pattern favoring US and Asian commercialization before European retail presence. Powder formulations targeting dry-mix applications are absorbing the longest delays, while liquid concentrates for beverage processing secure faster safety opinions.
Ingredient purchasing is consolidating around direct technical partnerships rather than spot-market transactions, with food manufacturers embedding supplier R&D teams into formulation development. Distributor intermediaries are losing share in high-value specialty sweeteners as buyers seek batch-to-batch consistency guarantees and regulatory documentation packages. This pattern is most pronounced in the United States, where precision fermentation suppliers are building captive customer success functions to displace traditional ingredient broker relationships.
Brazzein Market Segmentation
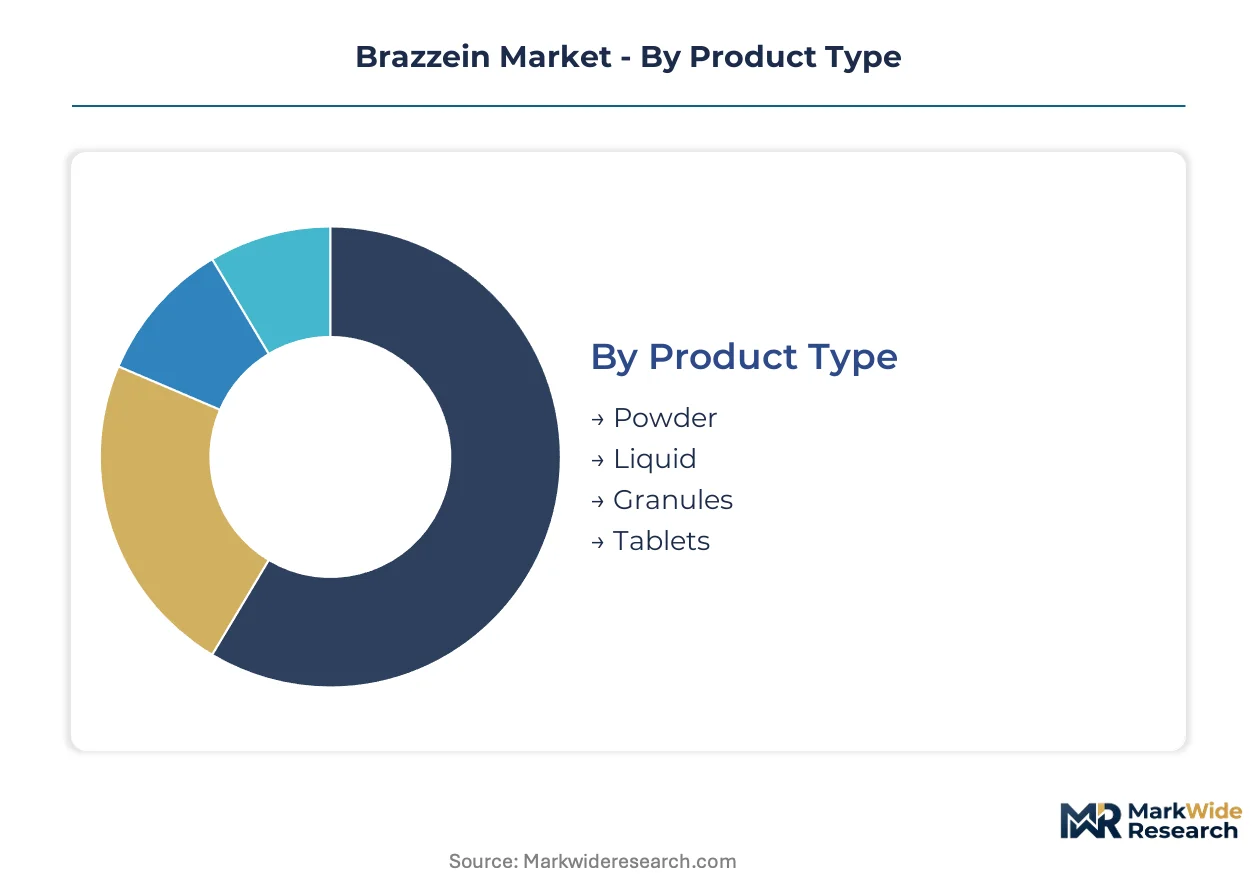
Brazzein segmentation reveals how technical specifications and supply chain requirements fragment across end-use scenarios. Formulation choices and delivery formats determine regulatory pathways, manufacturing partnerships, and margin structures for suppliers navigating this emerging category.
Product Type:
After-sales service intensity varies sharply across physical formats, with powder and liquid variants demanding distinct technical support for handling, storage, and integration protocols.
- Powder:Dry crystalline or spray-dried formulations offer superior shelf stability and compatibility with dry-mix manufacturing lines. Beverage and bakery manufacturers in the United States favor this format for batch consistency and reduced cold-chain dependency, though dispersion challenges in high-moisture applications constrain uptake.
- Liquid:Pumpable concentrates enable precise dosing and rapid dissolution in continuous processing environments. Functional drink producers seeking clean-label reformulation are driving fastest adoption here, particularly where heat-stable brazzein variants integrate into pasteurization protocols.
- Granules:Agglomerated particles bridge powder flowability with liquid dispersibility, serving tabletop sweetener and single-serve packet applications where consumer convenience dictates format selection.
- Tablets:Compressed dosage forms target direct-to-consumer channels and institutional food service, with dissolution rate engineering determining palatability outcomes.
Powder holds the largest share; momentum sits with liquid concentrates.
Application:
Cost tier stratification separates commodity-scale food manufacturing from premium pharmaceutical applications, with regulatory burden and technical specification intensity rising across the value ladder.
- Food Industry:Confectionery, dairy, and baked goods manufacturers deploy brazzein for sugar reduction while maintaining bulk and mouthfeel. Heat-stable variants above 80°C unlock retort and baking applications previously closed to protein sweeteners, with formulation support from suppliers like Tate & Lyle PLC smoothing integration.
- Beverage Production:Soft drink and functional drink reformulation represents the primary volume opportunity, as major manufacturers replace artificial sweeteners facing consumer scrutiny. Precision fermentation scale-up by Sweegen and others is compressing cost structures for this segment.
- Pharmaceuticals:Taste-masking for pediatric and geriatric drug delivery creates adjacent revenue streams, with excipient-grade purity requirements and FDA drug master file obligations extending commercialization timelines.
- Nutraceuticals:Sports nutrition and dietary supplement applications leverage brazzein's natural positioning and zero-calorie profile, though smaller batch sizes and certification demands fragment procurement patterns.
Beverage production commands current volume leadership; nutraceuticals are climbing the fastest.
End User:
Customer type determines procurement sophistication, with manufacturers embedding supplier R&D teams while distributors and food service operators rely on spot-market flexibility.
- Manufacturers:Multinational food and beverage producers negotiate direct technical partnerships, securing batch-to-batch consistency guarantees and regulatory documentation packages that displace traditional ingredient broker relationships.
- Retailers:Private-label and branded product developers source brazzein for consumer-facing sugar-reduced offerings, with clean-label certification requirements shaping supplier selection criteria.
- Distributors:Specialty ingredient intermediaries serve mid-scale producers lacking direct supplier relationships, though digital platforms are compressing markups and accelerating sample-to-contract velocity.
- Food Service:Institutional and commercial kitchen operators represent emerging demand, with tabletop and bulk liquid formats gaining traction in healthcare and corporate dining channels.
Manufacturers absorb the dominant procurement volume; food service is gaining share fastest.
Formulation:
Supply concentration clusters around synthetic variants produced via precision fermentation, while natural extracts command premium positioning among organic-certified end users.
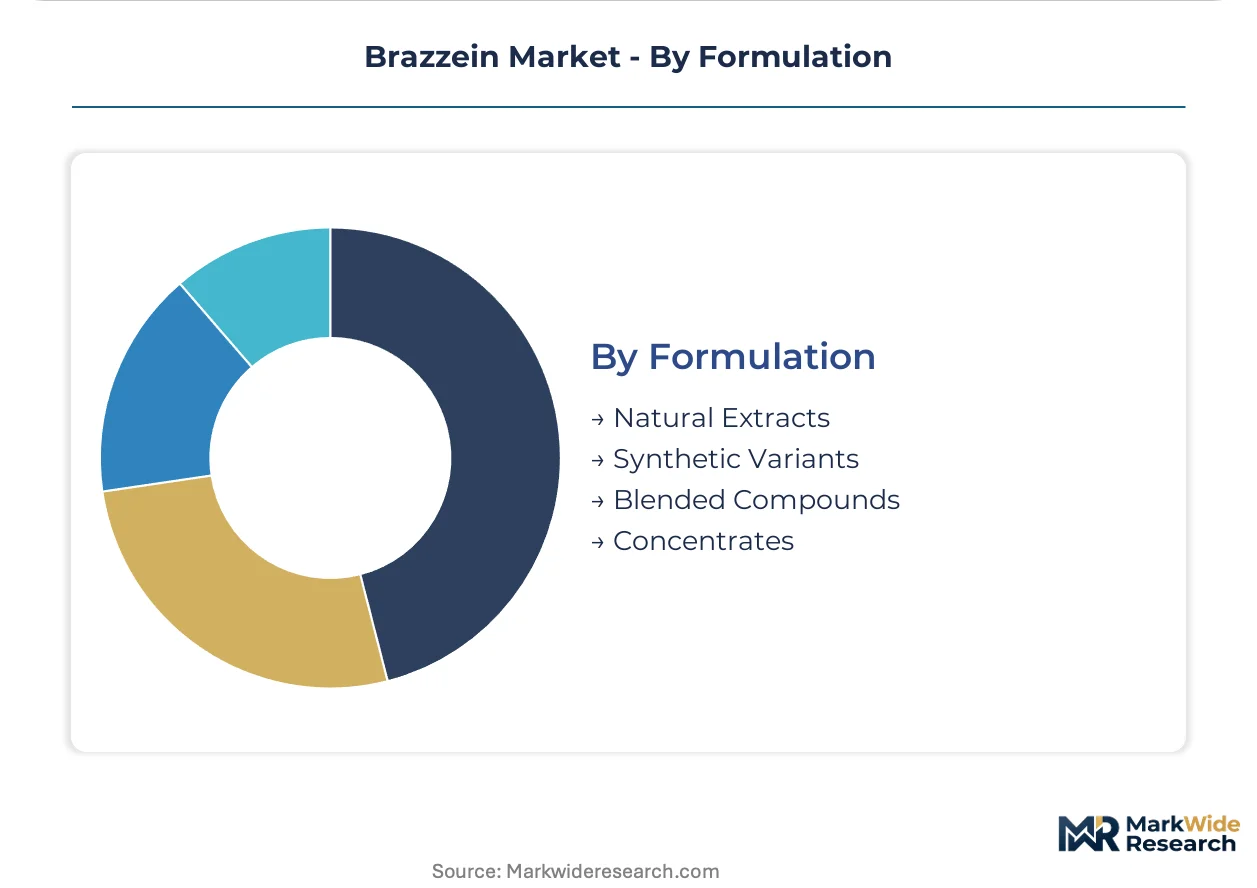
- Natural Extracts:Direct extraction from Pentadiplandra brazzeana fruit faces geographic and seasonal constraints, limiting scale and elevating cost structures for organic-certified applications in Europe and North America.
- Synthetic Variants:Microbial cell factories in controlled bioreactor environments virtualize agricultural dependency entirely. Ingredion Incorporated and Sweegen anchor commercial supply through precision fermentation infrastructure expanding fastest in the United States.
- Blended Compounds:Combinations with modulators, bulking agents, or complementary sweeteners optimize temporal profiles and cost-performance ratios for specific applications.
- Concentrates:High-potency liquid forms reduce shipping volumes and enable flexible dilution protocols for beverage processing lines.
Synthetic variants dominate volume; natural extracts retain premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European suppliers absorb authorization delays. Precision fermentation infrastructure clusters in American biotech corridors, compressing cost structures relative to regions dependent on extractive sourcing.
United States
FDA's GRAS self-affirmation pathway accelerates novel protein approvals for beverage manufacturers reformulating around clean-label mandates. Precision fermentation capacity expands fastest in Boston and San Diego biotech clusters, where Sweegen and Ingredion Incorporated anchor commercial-scale production.
Germany
EFSA's Regulation 2015/2283 novel food authorization extends market entry timelines, though pharmaceutical excipient applications create parallel revenue channels. Industrial biotechnology infrastructure in North Rhine-Westphalia supports contract fermentation partnerships for European market pre-positioning.
India
FSSAI's evolving novel food framework and surging functional beverage demand create first-mover potential for sugar-reduced regional formulations. Maharashtra and Karnataka host expanding food processing corridors where mid-scale manufacturers seek direct technical partnerships with fermentation suppliers.
China
SAMR's food additive approval pathways and domestic precision fermentation scale-up reshape import dependency for high-intensity sweeteners. Yangtze River Delta biomanufacturing clusters advance strain optimization capabilities for heat-stable protein variants targeting baked goods applications.
Brazil
ANVISA's regulatory harmonization with Codex standards and sugar reduction campaigns in processed foods drive ingredient substitution demand. São Paulo's food technology corridor attracts pilot-scale partnerships between multinational beverage formulators and biotechnology suppliers.
Brazzein Market Vendor Landscape
Ingredient conglomerates and precision fermentation specialists split the market into complementary supply tiers. Consolidation pressures intensify as beverage manufacturers demand batch-to-batch consistency guarantees that favor integrated suppliers over fragmented extractive sources. Three archetypes dominate: global ingredient distributors leveraging procurement networks, biotechnology platforms scaling microbial production, and formulation specialists blending sweeteners with taste modulators. Capacity expansion and strategic technical partnerships represent the dominant competitive vectors.
Among global ingredient distributors, Ingredion Incorporated and Cargill occupy positions spanning traditional sweetener portfolios into emerging protein categories. Tate & Lyle PLC exemplifies the formulation-specialist archetype, while Sweegen anchors the precision fermentation tier. These companies represent the strategic poles around which mid-scale suppliers and regional distributors organize competitive positioning.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Sweegen |
| Archer Daniels Midland Company |
| Magellan Life Sciences |
| Senomyx |
| Cargill |
| Roquette Frères |
| Natur Research Ingredients |
| Tate & Lyle PLC |
| Others |
Supply Flow & Price Mechanics
EFSA's novel food authorization friction compresses European supply availability while accelerating US pricing tier spreads, determining both premium capture for early movers and supply chain shape favoring precision fermentation clusters over extractive sourcing.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade brazzein extracts commands spreads of 40-60% above standard fermentation-derived powder, with certification tier and volume scale as the primary differentiation drivers. Pricing pressure stems from glucose feedstock volatility tied to agricultural commodity swings, compressing margins for synthetic variant producers. Large beverage manufacturers exhibit lowest price sensitivity due to reformulation urgency, while mid-scale nutraceutical blenders face acute cost compression.
Supply Chain Analysis
Upstream glucose and nitrogen sourcing draws from corn belt agricultural networks in the United States, Brazilian sugarcane processing corridors, and European beet sugar refineries. Precision fermentation capacity clusters in Boston and San Diego biotech corridors, with downstream distribution running through direct technical partnerships displacing traditional ingredient brokers. Single-source vulnerability concentrates in contract fermentation capacity, where bioprocess engineering talent scarcity limits rapid supplier switching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brazzein market sits at a fermentation-capacity expansion cycle that favors integrated biotechnology platforms over fragmented extractive suppliers, with GRAS pathway acceleration and beverage reformulation mandates driving recovery momentum.
For Market Incumbents: Build regulatory documentation moats through captive FDA GRAS dossier development and EFSA pre-submission engagement, locking in 18-36 month lead times over European challengers. Sweegen and Ingredion Incorporated should deepen backward integration into glucose supply through offtake agreements with Midwest agricultural processors, insulating margin pressure from feedstock volatility. Capacity addition in India and Brazil pre-positions for FSSAI and ANVISA framework maturation.
For New Entrants and Emerging Players: India's functional beverage white space in Maharashtra and Karnataka corridors represents the most penetrable entry point, with mid-scale manufacturers seeking direct technical partnerships bypassing distributor markups. Pharmaceutical excipient applications for pediatric taste-masking offer adjacent revenue with lower competitive density than beverage volumes. Go-to-market execution should anchor on digital specialty ingredient platforms enabling sample-to-contract velocity.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors precision fermentation specialists with demonstrated strain optimization and heat-stable variant pipelines. Long-term viability over the next decade hinges on continuous bioprocessing yield breakthroughs and clean-label certification standard capture. Acquisition targets should display captive downstream purification capacity and regulatory affairs infrastructure. The signal to watch is EFSA novel food opinion acceleration as inflection indicator for European demand normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Sweegen's bioreactor expansion in San Diego compresses unit economics for beverage-grade brazzein supply. |
| Regulatory Pre-Positioning | Early EFSA dossier submission under Regulation 2015/2283 secures sequential market entry timing advantage. |
| Backward Integration | Captive glucose supply agreements with US agricultural processors insulate margin pressure from commodity volatility. |
| Direct Technical Partnership | Embedding R&D teams into multinational beverage formulators displaces traditional ingredient broker relationships. |
| Heat-Stable Variant Development | Strain optimization above 80°C unlocks retort and baked goods applications previously closed to protein sweeteners. |
Methodological Framework
A spread of perspectives from precision fermentation platform executives, beverage formulation scientists, regulatory affairs specialists at FDA and EFSA, and specialty ingredient procurement managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA GRAS notification databases, EFSA novel food register entries, and fermentation facility EPA emissions filings. Bottom-up volume modeling from individual production facility outputs triangulated against top-down demand estimates from beverage industry reformulation announcements.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation across formulation type, application vertical, and geographic regulatory cluster. CAGRs were derived from facility capacity expansion announcements, strain yield improvement trajectories, and clean-label adoption curve assumptions. Industry-specific forecast inputs incorporated precision fermentation titer rate improvements and EFSA authorization timeline probability distributions.
Practitioners should monitor EFSA novel food opinion velocity, glucose commodity price movements, and contract fermentation capacity utilization for early signals requiring forecast revision. Cross-checking against FDA GRAS notification clearance rates and beverage manufacturer pilot-scale adoption disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
North America Water Enhancer Market