
 Africa Water Enhancer Market | 2026-2036
Africa Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Water Enhancer Market Outlook
Fitness enthusiasts are unwinding the historical dominance of family-oriented bulk purchasing in Africa's water enhancer landscape. The Kraft Heinz Company leverages its packaged foods infrastructure to anchor distribution across North African retail networks. Biogen SA specializes in sports nutrition extensions that compete directly with NUTRITECH's gym-channel dominance in South African metropolitan areas.
Africa water enhancers comprise concentrated liquid or powder formulations containing electrolytes, vitamins, flavor compounds, and trace minerals designed for dilution into potable water. These products typically achieve osmolarity between 150-300 mOsm/L when mixed at recommended ratios, functioning primarily to improve palatability of treated municipal supplies while delivering targeted nutritional supplementation. Flavoring agents command the broadest consumer reach across urban supermarkets, whereas mineral drops capture premium margins through health shop channels serving diagnosed deficiency populations. Sachet packaging dominates volume throughput in informal retail settings, while bottles sustain higher per-unit economics in supermarket placements across Kenyan and Nigerian cities.
South Africa's National Regulator for Compulsory Specifications enforces NRCS food-grade certification that limits import flexibility for uncertified enhancer concentrates. Kenya's Kenya Bureau of Standards mandates label disclosure of all artificial sweeteners under KS EAS 38 standards, shaping formulation choices for brands entering East African markets. Nigeria's National Agency for Food and Drug Administration and Control requires product registration with full ingredient transparency before commercial distribution. Stakeholders must monitor evolving harmonization between regional standards bodies and national regulators to preempt compliance fragmentation that could disrupt cross-border supply planning.
Market Dynamics
Fitness culture in Lagos and Nairobi is fragmenting traditional family-oriented bulk purchasing patterns, while South Africa's NRCS certification requirements create compliance bottlenecks that reshape import strategies for concentrate suppliers.
Growth Catalysts
- Electrolyte fortification demand:Urban gym chains in Nigeria and Kenya are stocking mineral drops alongside protein supplements, creating dedicated retail space for hydration enhancers targeting post-workout recovery protocols.
- KS EAS 38 label transparency:Kenya's artificial sweetener disclosure mandate is accelerating clean-label reformulation among entrants seeking differentiation in East African supermarket channels.
- Sachet packaging innovation:Single-serve powder formats are penetrating informal retail nodes across Nigerian commercial hubs where cash-flow constraints favor low-unit-price purchasing.
Market Restraints
- Import certification friction:South Africa's NRCS food-grade approval process extends lead times for uncertified concentrate suppliers, compressing margins on time-sensitive product launches.
- Municipal water quality variability:Inconsistent chlorination and turbidity levels in Lagos and Kinshasa municipal supplies degrade enhancer dissolution performance, limiting repeat purchase rates.
- Sugar-sweetened beverage substitution:Affordable carbonated soft drinks from dominant local bottlers capture price-sensitive household hydration occasions in Nigerian and Kenyan informal retail.
Strategic Opportunities
- Diagnostic-driven mineral drops:Health shop channels in Johannesburg and Cape Town are developing certified nutritionist consultation services that pair deficiency testing with personalized electrolyte formulations.
- Pharmacy distribution expansion:Nigeria's NAFDAC registration pathway enables shelf placement alongside rehydration salts in formal pharmacy chains serving middle-income suburban households.
- Natural flavor extract convergence:Cold-pressed fruit oil extraction technologies from South African agricultural processors are enabling clean-label flavoring agents that bypass artificial additive disclosure requirements.
Industry Challenges
- Refrigerated supply chain gaps:Temperature-sensitive probiotic-enhanced formulations face spoilage risk in Nigerian and Kenyan last-mile distribution lacking cold-chain infrastructure.
- Ingredient traceability documentation:NAFDAC's full transparency requirements demand supply chain auditing capabilities that many regional importers lack, delaying product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Water Enhancer Market |
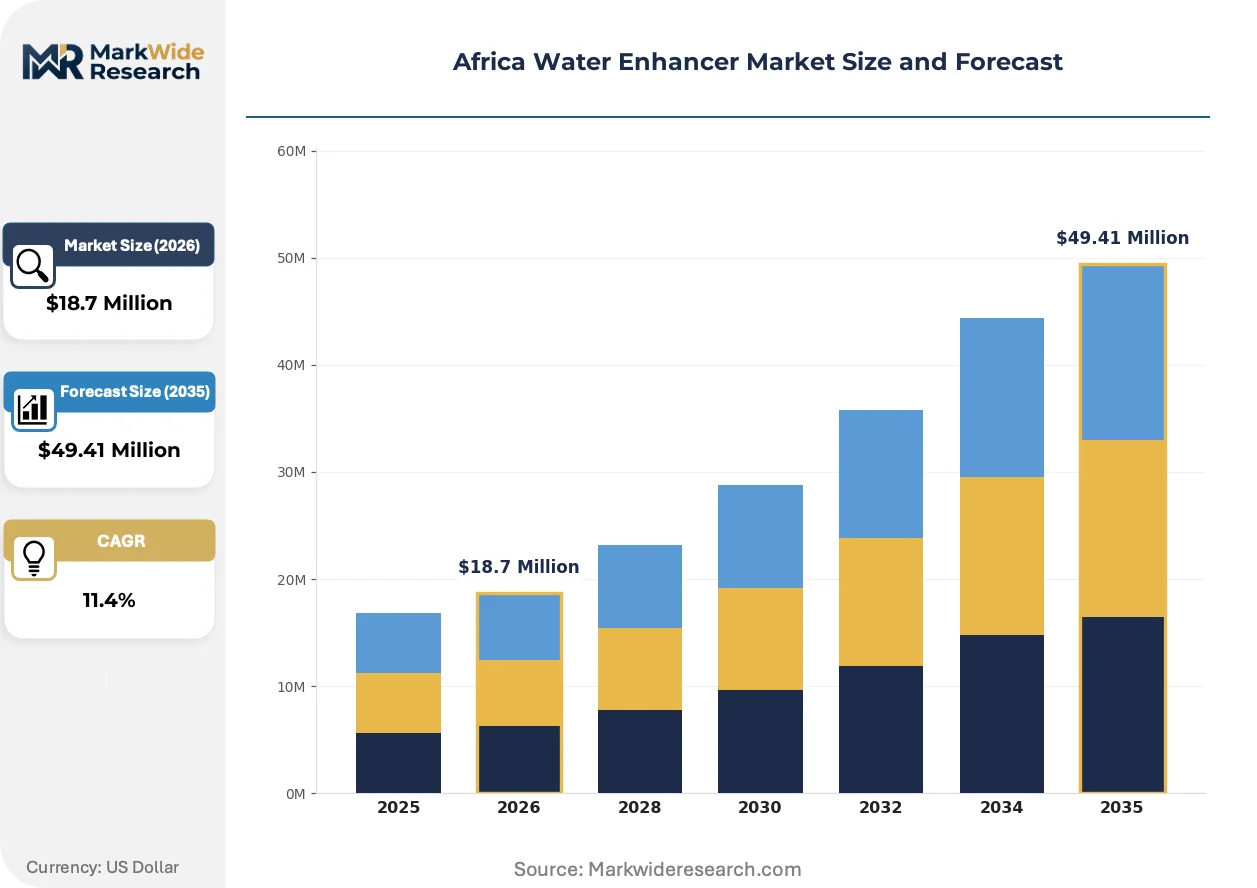
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Drops, Flavoring Agents, Enzyme Enhancers, Nutrient Infusions Distribution Channel: Online Stores, Supermarkets, Health Shops, Direct Sales Packaging Type: Bottles, Sachets, Jars, Tetra Packs Consumer Type: Fitness Enthusiasts, Health-Conscious Consumers, Families, Athletes |
| Companies Covered | The Kraft Heinz Company, Dyla LLC, NUTRITECH, Biogen SA, Elvin Group, ds international, 4C Foods, BPI Sports LLC, Nestle, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Water Enhancer Market Strategic Shifts
Natural extraction methods and regulatory transparency mandates are compressing formulation timelines while redirecting competitive advantage toward supply chain verification capabilities.
Stevia-glycoside and monk-fruit extract blends are supplanting aspartame and sucralose in premium-positioned enhancers targeting Nairobi and Lagos health-conscious consumers. South African formulators are accelerating adoption to preempt KS EAS 38 disclosure friction. This shift is compressing R&D cycles as brands race to match clean-label positioning without sacrificing sweetness intensity.
Harmonization pressures between the East African Community standards bodies and Kenya's Bureau of Standards are creating dual-compliance burdens for enhancer manufacturers. Cross-border distributors must now maintain parallel documentation systems. Sachet-format exporters serving informal retail channels face the steepest administrative cost escalation.
Subscription-based replenishment models are displacing supermarket pantry stocking among Johannesburg fitness enthusiasts and Lagos corporate wellness programs. Direct-to-consumer platforms bypass traditional retail markups while capturing consumption data for personalized formulation recommendations. Kenyan gym chains are piloting white-label partnerships with local blenders to capture recurring revenue streams.
Africa Water Enhancer Market Segmentation
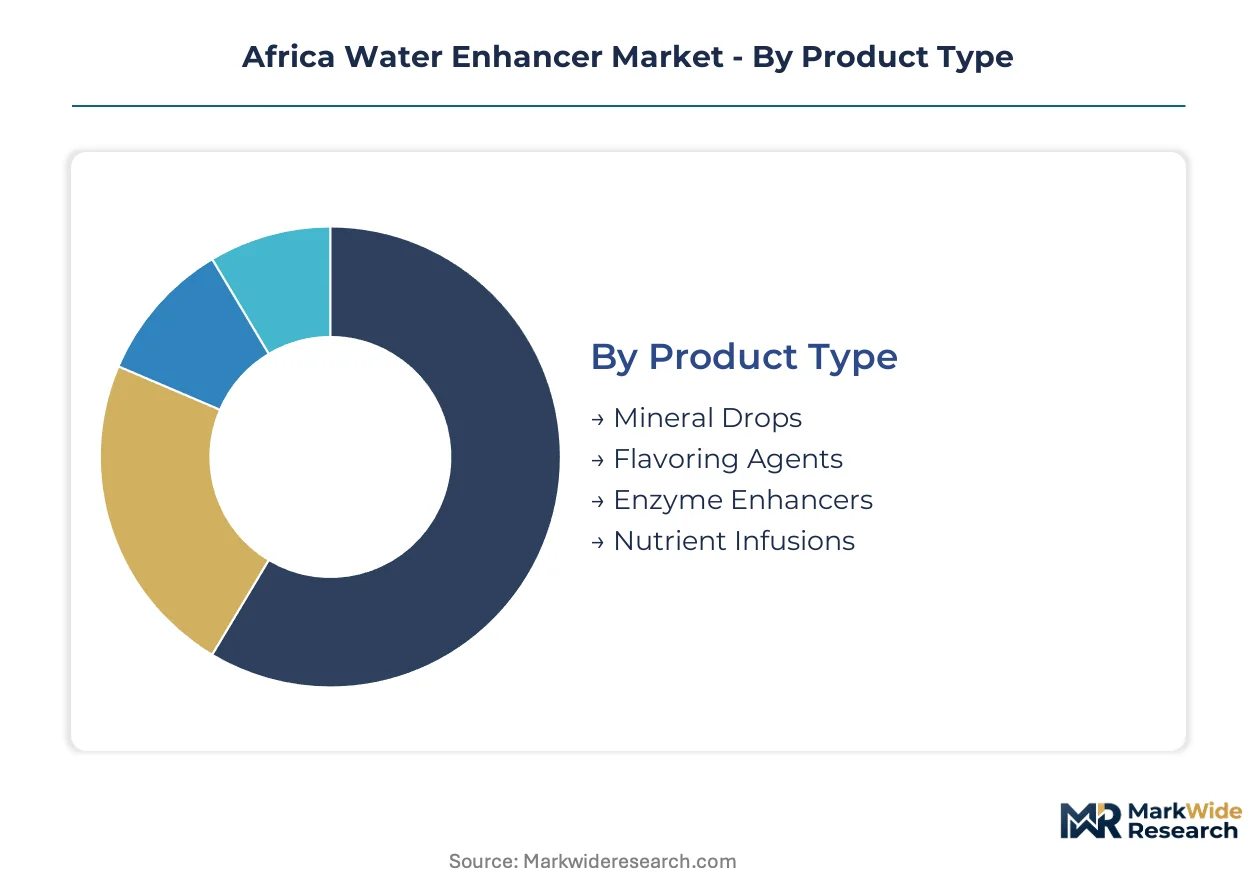
Water enhancer segmentation in Africa reveals stark divergences between domestic formulation capabilities and import-dependent supply chains. Product categories cluster around distinct price-performance thresholds that map directly to urban income stratification across Lagos, Nairobi, and Johannesburg metropolitan corridors.
Product Type:
Domestic production concentrates in flavoring agents and basic mineral formulations, while enzyme enhancers and specialized nutrient infusions remain overwhelmingly import-led from European and Asian suppliers.
- Flavoring Agents:Liquid concentrates containing natural and artificial flavor compounds, sweeteners, and acidulants designed for palatability enhancement of treated municipal water. Demand concentrates in Nigerian supermarket chains serving middle-income households in Lagos and Abuja where taste masking of chlorinated supplies drives repeat purchase.
- Mineral Drops:Concentrated electrolyte solutions with magnesium, potassium, zinc, and trace elements calibrated for deficiency correction. Fitness enthusiasts in Nairobi's Kilimani and Westlands districts are driving premium uptake through gym-channel distribution partnerships with local sports nutrition retailers.
- Enzyme Enhancers:Probiotic and digestive enzyme formulations requiring refrigerated handling throughout distribution.
- Nutrient Infusions:Vitamin-complex concentrates targeting specific demographic deficiencies with enhanced bioavailability claims.
Flavoring agents command the established base. The steepest expansion runs through mineral drops.
Distribution Channel:
Channel economics stratify sharply between formal retail requiring NAFDAC registration and informal nodes where sachet formats bypass regulatory documentation burdens.
- Supermarkets:Formal retail placements in Shoprite, Spar, and Nakumatt chains across South African and Nigerian urban centers. These outlets demand full NRCS or NAFDAC certification, filtering out uncertified imports while capturing recurring pantry-stocking behavior from suburban families in Cape Town's Atlantic Seaboard and Lagos's Lekki Peninsula.
- Health Shops:Specialized nutrition retailers serving diagnosed deficiency populations and performance-oriented consumers. Johannesburg's Rosebank and Cape Town's CBD clusters pair certified nutritionist consultations with personalized electrolyte recommendations, generating premium margins unavailable in mass retail.
- Online Stores:Direct-to-consumer platforms bypassing traditional markups through subscription replenishment models.
- Direct Sales:Gym-based vending and corporate wellness program partnerships.
Supermarkets anchor volume throughput. Health shops deliver margin expansion.
Packaging Type:
Format selection tracks purchasing power fragmentation between cash-constrained informal retail and premium supermarket placements.
- Sachets:Single-serve powder pouches dominating Nigerian open-air markets and Kenyan kiosk networks where daily wage earners favor low-unit-price hydration solutions. Sachet economics align with cash-flow constraints in Lagos's Oshodi and Nairobi's Gikomba trading hubs.
- Bottles:Multi-dose liquid containers sustaining higher per-unit economics in South African supermarket chains. Cape Town and Johannesburg consumers accept bottle premiums for concentrated formulations with extended shelf stability.
- Jars:Bulk powder containers targeting family-oriented purchasing in suburban retail.
- Tetra Packs:Aseptic liquid formats for ambient-stable distribution in cold-chain-deficient corridors.
Sachets penetrate the deepest. Bottles extract the highest margin per liter equivalent.
Consumer Type:
Demand fragmentation reflects divergent hydration occasions from athletic performance to pediatric nutrition across Africa's urban income spectrum.
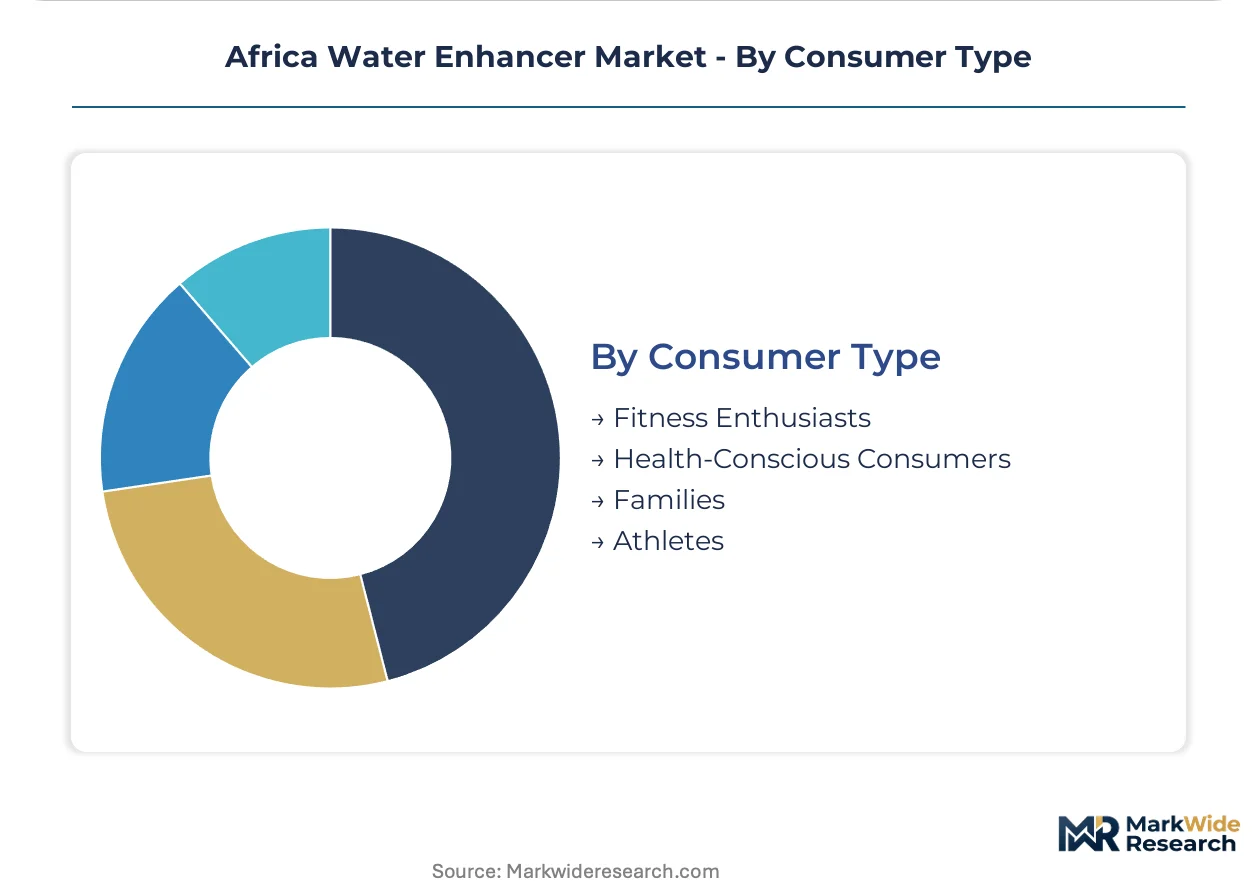
- Fitness Enthusiasts:Gym-affiliated consumers pursuing electrolyte replenishment protocols in Nigeria's burgeoning fitness culture. Lagos gym chains in Victoria Island and Ikeja are dedicating retail space to post-workout mineral drops, displacing traditional family-oriented bulk purchasing patterns among young professionals.
- Health-Conscious Consumers:Urban middle-income households seeking clean-label alternatives to sugar-sweetened beverages. Nairobi's Karen and Lavington residents are driving stevia-sweetened flavoring agent adoption through supermarket premium tiers.
- Families:Household purchasers prioritizing volume economics and child-friendly formulations.
- Athletes:Competitive and recreational sports participants requiring precise electrolyte replacement ratios.
Fitness enthusiasts are gaining share fastest. Health-conscious consumers sustain premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African formulators export mineral drop concentrates to Nigerian distributors navigating NAFDAC registration protocols, while Kenyan blenders supply sachet formats to informal retail nodes across East African Community corridors.
South Africa
Johannesburg's Rosebank health shop clusters pair certified nutritionist consultations with personalized electrolyte recommendations, driving premium mineral drop adoption. The National Regulator for Compulsory Specifications enforces NRCS food-grade certification that limits import flexibility for uncertified enhancer concentrates. Cape Town's Atlantic Seaboard supermarkets sustain bottle-format volume through suburban family pantry-stocking behavior.
Nigeria
Lagos gym chains in Victoria Island and Ikeja dedicate retail space to post-workout mineral drops, displacing traditional family-oriented bulk purchasing among young professionals. The National Agency for Food and Drug Administration and Control requires full ingredient transparency and product registration before commercial distribution. Abuja's middle-income households drive flavoring agent demand through formal supermarket channels serving chlorinated municipal supply masking needs.
Kenya
Nairobi's Kilimani and Westlands districts host gym-channel distribution partnerships between sports nutrition retailers and mineral drop suppliers. The Kenya Bureau of Standards mandates artificial sweetener disclosure under KS EAS 38 standards, accelerating clean-label reformulation among market entrants. Gikomba trading hubs favor sachet packaging economics that align with daily wage earner cash-flow constraints.
Egypt
Cairo's nascent fitness culture generates emerging demand for electrolyte fortification products through commercial gym partnerships. The country's national food safety regulator maintains import documentation requirements that shape concentrate supplier entry strategies. Alexandria's supermarket chains experiment with tetra pack formats for ambient-stable distribution in cold-chain-deficient corridors.
Africa Water Enhancer Market Competitive Environment
Listed leaders compete with private specialists across certification and distribution infrastructure dimensions. The market exhibits moderate concentration with multinational packaged food conglomerates anchoring formal retail placements while domestic sports nutrition specialists capture gym-channel premium positioning. Three archetypes dominate: multinational food conglomerates leveraging existing retail infrastructure, regional sports nutrition specialists with gym-channel integration, and private-label blenders serving subscription-based direct-to-consumer models. Competitive moves concentrate on NAFDAC registration acceleration and sachet packaging innovation for informal retail penetration.
Among multinational food conglomerates, The Kraft Heinz Company exemplifies the packaged foods infrastructure archetype anchoring North African retail networks. Within the regional sports nutrition tier, NUTRITECH and Biogen SA occupy positions reflecting gym-channel dominance strategies in South African metropolitan areas. These named entities represent the competitive tension between import-dependent certification-heavy operations and locally blended subscription models.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Dyla LLC |
| NUTRITECH |
| Biogen SA |
| Elvin Group |
| ds international |
| 4C Foods |
| BPI Sports LLC |
| Nestle |
| Others |
Value Chain & Pricing Dynamics
South Africa's NRCS food-grade certification gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified imports while enabling certified domestic blenders to command supermarket placement premiums. Lagos gym chains and Nairobi health shops absorb higher per-unit costs for verified electrolyte formulations, whereas informal sachet channels in Nigerian open-air markets trade certification bypass for rock-bottom unit economics.
Pricing Analysis
Clean-label versus artificial-sweetener formulation technologies generate the steepest pricing gaps in this market. Three-tier pricing structure across premium, standard, and economy levels separates NRCS-certified mineral drops from KS EAS 38-compliant flavoring agents from unregistered sachet powders. Price differentiation centers on certification grade and volume scale, with single-serve sachets extracting minimal margin per liter equivalent. Cost compression in the standard tier is intensifying because Kenyan blenders are racing to match stevia-sweetened positioning without sacrificing sweetness intensity. Informal retail nodes serving daily wage earners exhibit highest price sensitivity, while Johannesburg health shop consultations sustain lowest sensitivity through personalized deficiency testing bundles.
Supply Chain Analysis
Inventory lead times for NRCS-certified concentrate imports extend substantially beyond domestic South African blending cycles, compressing working capital efficiency for Nigerian distributors navigating NAFDAC registration protocols. Supply concentrates in South Africa, Kenya, and Nigeria, with Egyptian tetra pack experimentation emerging as a cold-chain bypass for ambient-stable distribution. Raw material dependencies center on stevia glycoside extracts, magnesium chloride feedstocks, and cold-pressed fruit oil flavor bases. Single-source vulnerability runs through European enzyme enhancer suppliers lacking African refrigeration infrastructure. Distribution runs through supermarket chains anchoring formal retail, health shops capturing premium positioning, and sachet networks penetrating informal nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where subscription-based replenishment models and white-label gym partnerships are displacing traditional pantry-stocking behavior, with interoperability between direct-to-consumer data capture and personalized formulation recommendation engines reshaping competitive advantage.
For Market Incumbents: Fortify NAFDAC registration acceleration capabilities to preempt compliance bottlenecks that delay Nigerian product launches, while deepening backward integration into South African agricultural processor networks for captive supply of cold-pressed fruit oil extracts. The Kraft Heinz Company's packaged foods infrastructure faces erosion from domestic sports nutrition specialists with gym-channel integration, making certification investment and channel control the priority defensive levers. For New Entrants and Emerging Players: Anchor in diagnostic-driven mineral drops paired with certified nutritionist consultation services, the most penetrable white-space target in Johannesburg and Cape Town health shop clusters. Kenya's KS EAS 38 clean-label momentum creates a secondary entry vector through stevia-sweetened flavoring agents bypassing artificial additive disclosure friction. Direct-to-consumer subscription platforms offer the cleanest go-to-market angle, bypassing traditional retail markups while capturing consumption data for personalized formulation recommendations. For Investors and Strategic Acquirers: NAFDAC's full ingredient transparency mandate reshapes the acquisition landscape toward targets with pre-existing supply chain auditing capabilities and accelerated registration track records. Long-term viability over the projection horizon hinges on dual-compliance infrastructure spanning NRCS certification and KS EAS 38 disclosure readiness. Vertically integrated mid-cap specialists with in-house South African blending and Kenyan sachet packaging assets represent the priority acquisition archetype. The signal to watch is harmonization pressure between East African Community standards bodies and national regulators, which would compress administrative cost escalation for cross-border distributors.| Strategic Initiative | Industry Significance |
|---|---|
| NAFDAC Registration Acceleration | Preempts compliance bottlenecks that compress margins on Nigerian product launches. |
| Backward Integration into Agricultural Processing | Captures South African cold-pressed fruit oil extraction for clean-label flavoring agent supply security. |
| Subscription-Based Replenishment Platform | Displaces supermarket pantry-stocking among Johannesburg fitness enthusiasts through direct-to-consumer data capture. |
| White-Label Gym Partnership | Enables Kenyan gym chains to capture recurring revenue streams through localized mineral drop blending. |
| Diagnostic-Driven Consultation Service | Pairs Johannesburg health shop certified nutritionists with personalized electrolyte recommendations for premium margin extraction. |
Study Parameters
A spread of perspectives from brand managers at multinational food conglomerates, category buyers at Nigerian supermarket chains, sports nutrition retail heads in Johannesburg and Nairobi, and regulatory affairs leads navigating NAFDAC and NRCS protocols converged on the working assumptions. Secondary validation drew from Kenya Bureau of Standards filings, South African customs and trade data, East African Community harmonization documentation, and SEC 10-K disclosures from listed packaged food entities. Bottom-up channel volume estimates and top-down macroeconomic consumption projections were triangulated to anchor the analytical framework.
Segmentation dimensions modeled span product type, distribution channel, packaging format, and consumer archetype across the analysis window, with flavoring agents, mineral drops, enzyme enhancers, and nutrient infusions treated as distinct demand pools. CAGRs were derived from fitted growth curves incorporating urbanization rates, fitness culture penetration indices, and municipal water quality variability. Industry-specific forecast inputs included gym-chain expansion pipelines in Lagos and Nairobi, and cold-chain infrastructure development trajectories for probiotic-enhanced formulations.
Material uncertainties — regulatory harmonization delays, municipal supply chlorination volatility, and refrigerated last-mile distribution gaps — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline acceleration and clean-label reformulation cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Fortifying Agent Market