
 Asia-Pacific Flavor Enhancer Market | 2026-2036
Asia-Pacific Flavor Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flavor Enhancer Market Outlook
The EU Green Deal's extraterritorial influence on supply chain sustainability is broadening buyer mandates across Asia-Pacific processed food sectors. Ajinomoto Group leverages its fermentation technology leadership to sustain dominance in amino acid-based enhancers across East Asian markets. Kerry Group anchors its position through backward integration into natural extract sourcing, while Symrise competes on botanical extraction capabilities for clean-label applications. Takasago navigates regional formulation preferences through specialized savory taste modulation platforms.
Flavor enhancers comprise substances that amplify or modify perceived taste intensity without contributing significant independent flavor character, typically manufactured through fermentation, enzymatic hydrolysis, or solvent extraction processes with purity thresholds measured by glutamate equivalence or nucleotide ratios. Their primary commercial purpose centers on reducing sodium, sugar, or fat content in processed foods while maintaining consumer sensory acceptance. Amino Acids occupy the largest value pool due to monosodium glutamate's entrenched cost-position in mass-market seasoning, though Natural Extracts represent the fastest structural expansion as Japanese and Australian manufacturers reformulate around FSSAI and Food Standards Australia New Zealand label-friendly positioning. The Beverages application segment shows concentrated innovation activity around umami modulation for low-sugar formulations, while Seasonings retains the deepest margin pool through direct-to-manufacturer bulk contracts.
Food Standards Australia New Zealand, Japan's Ministry of Health Labour and Welfare, and China's SAMR collectively enforce additive positive lists and labeling disclosure thresholds that dictate reformulation cycles and import clearance timelines across the region. India's FSSAI is tightening contaminant limits for nucleotide-based enhancers, forcing suppliers to recertify manufacturing sites or exit contract opportunities. Stakeholders must monitor divergence between Codex-aligned and national-specific maximum permitted levels when allocating R&D budgets across country portfolios.
Market Dynamics
Japan's positive list system for food additives is compressing formulation cycles across East Asian processed food corridors, forcing manufacturers to recertify entire product lines or abandon legacy enhancer portfolios.
Growth Catalysts
- Clean-label procurement mandates:Instant noodle and savory snack manufacturers across Southeast Asia are expanding orders for naturally-derived enhancers to meet retailer sustainability scorecards.
- Fermentation technology maturation:Amino acid production yields have improved through continuous bioprocessing, lowering unit economics for glutamate equivalence in mass-market seasoning applications.
- Umami modulation for low-sugar beverages:Beverage formulators in China's processed food corridor are deploying savory taste platforms to mask off-notes in reduced-sugar formulations.
Market Restraints
- Input cost volatility:Molasses and starch feedstock prices fluctuate with agricultural commodity cycles, squeezing margins for fermentation-based amino acid producers.
- Supply concentration risk:Natural extract sourcing clusters in specific botanical cultivation zones, creating geographic vulnerability for clean-label supply security.
- Regulatory friction from India's FSSAI:Tightening contaminant limits for nucleotide-based enhancers is forcing suppliers to recertify manufacturing sites or forfeit contract opportunities.
Strategic Opportunities
- Australian clean-label positioning:Food Standards Australia New Zealand's label-friendly framework creates export-ready positioning for botanical extraction capabilities serving reformulation demand.
- Direct-to-manufacturer bulk contracting:Seasonings producers are bypassing traditional distribution layers to capture margin pools through captive supply relationships with processed food manufacturers.
- Dual carbon alignment in China:SAMR enforcement of carbon intensity metrics is creating preferential procurement status for fermentation processes with verified emissions reductions.
Industry Challenges
- Reformulation timeline compression:Japan's Ministry of Health Labour and Welfare positive list revisions demand 18-month recertification windows that outpace standard R&D cycles.
- Cross-border label harmonization:Divergence between Codex-aligned and national-specific maximum permitted levels forces redundant testing protocols for multi-country portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flavor Enhancer Market |
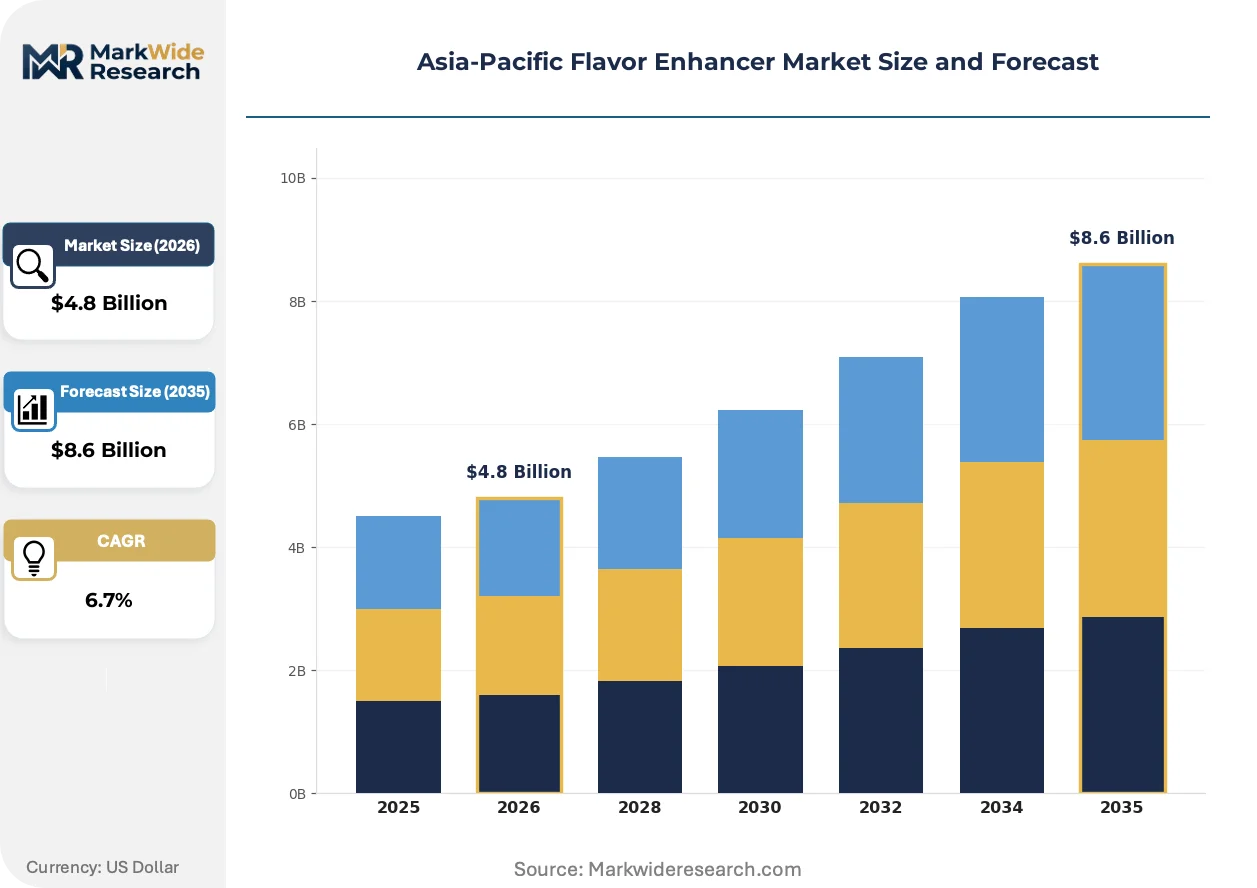
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Natural Extracts, Synthetic Flavorings, Spices Application: Food Processing, Beverages, Dairy Products, Seasonings End User: Manufacturers, Restaurants, Retailers, Caterers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Kerry Group, Symrise, Givaudan, Archer Daniels Midland, Takasago, Firmenich, Cargill, Sensient Technologies, Ajinomoto Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flavor Enhancer Market Strategic Shifts
Biotechnology-enabled taste modulation is displacing conventional extraction methods, while regulatory divergence between Codex standards and national positive lists is fragmenting formulation strategies across the region.
Precision fermentation for amino acid production is converging with enzymatic hydrolysis platforms to create hybrid manufacturing systems. Mid-cap seasoning manufacturers in South Korea and Thailand are piloting these integrated bioprocessing lines at commercial scale. This convergence is compressing capital requirements for entry-level clean-label production while raising purity thresholds for commodity-grade suppliers.
Japan's positive list system continues tightening disclosure thresholds for nucleotide-based additives, forcing reformulation of legacy savory seasoning portfolios. Industrial consequence includes accelerated R&D allocation toward amino acid alternatives that circumvent positive list scrutiny. China's SAMR is responding with parallel draft standards, creating harmonization pressure across Northeast Asian import clearance protocols.
Buyer concentration among Southeast Asian instant noodle manufacturers is consolidating procurement decisions into fewer technical sourcing teams. These consolidated buying centers now demand integrated flavor systems rather than commodity enhancer inputs, displacing spot-market transactions. This pattern is most visible in Thailand and Indonesia, where top-three manufacturers account for dominant volume share in regional savory snack production.
Asia-Pacific Flavor Enhancer Market Segmentation
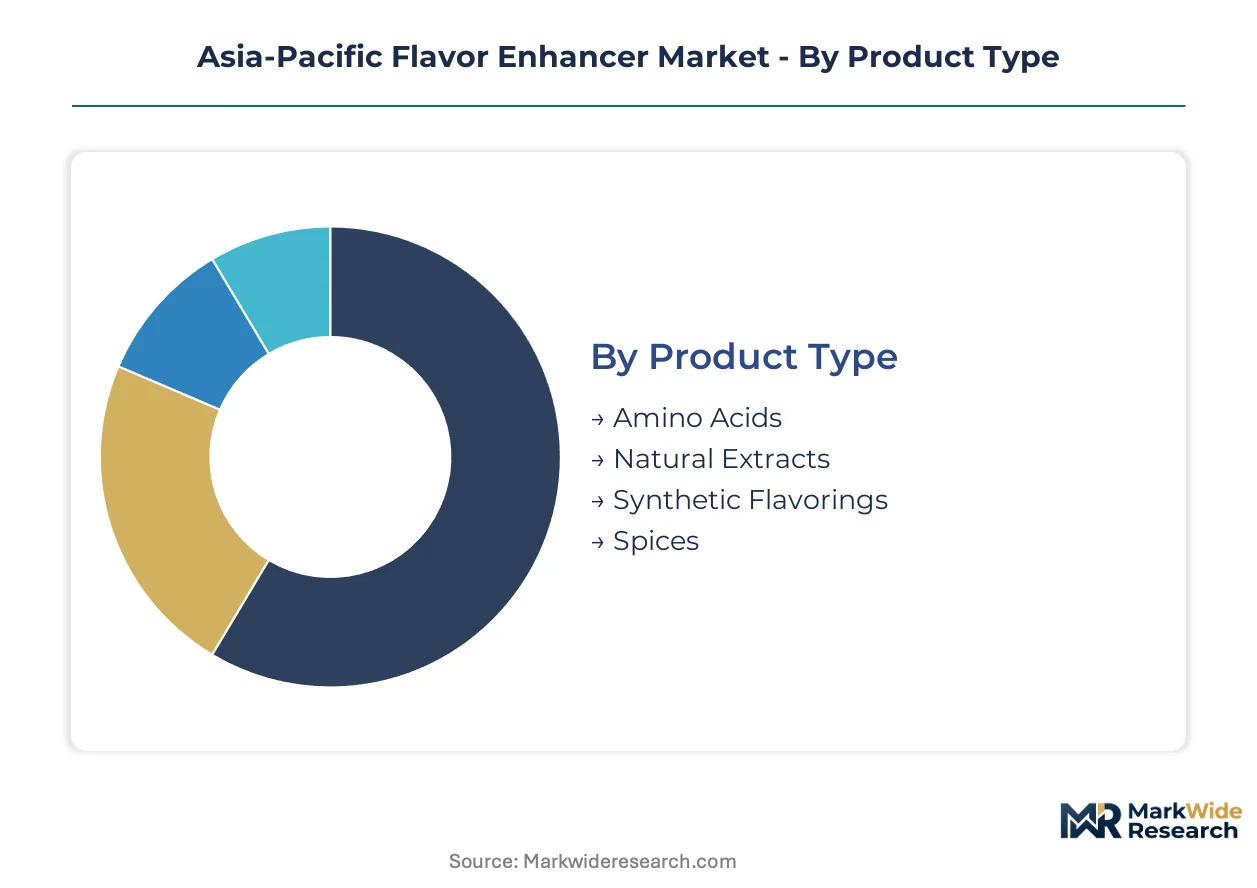
Asia-Pacific flavor enhancer procurement patterns diverge sharply across product categories and end-use channels, with reformulation cycles and regulatory recertification timelines dictating supplier prioritization. Manufacturers navigating Japan's positive list system and China's SAMR disclosure thresholds must align portfolio investments with segment-specific margin pools and volume concentration points.
Product Type:
Upgrade cycles in East Asian processed food corridors are accelerating displacement of legacy synthetic portfolios toward fermentation-derived and botanical alternatives that satisfy clean-label procurement mandates.
- Amino Acids:Monosodium glutamate and nucleotide compounds manufactured through continuous bioprocessing dominate mass-market seasoning applications. Procurement concentrates among instant noodle manufacturers in China's processed food corridor spanning Shanghai, Guangzhou, and Chengdu, where cost-position and glutamate equivalence specifications remain non-negotiable. Japan's Ministry of Health Labour and Welfare positive list revisions are compressing reformulation timelines for nucleotide variants.
- Natural Extracts:Botanical and fermentation-derived enhancers extracted through enzymatic hydrolysis or solvent methods serve clean-label positioning requirements. Demand clusters in Australian and Japanese markets aligned with Food Standards Australia New Zealand and Japan's disclosure-friendly frameworks, driven by retailer sustainability scorecards and export-ready certification needs.
- Synthetic Flavorings:Chemically synthesized taste modulators face declining procurement preference across Southeast Asian savory snack sectors.
- Spices:Whole and processed botanical inputs provide regional taste differentiation for seasoning blenders targeting localized palate preferences.
Amino Acids sits at the top of the volume ranking, with Natural Extracts climbing the fastest.
Application:
Cost tier differentiation separates commodity bulk contracts from premium integrated flavor systems, with direct-to-manufacturer relationships capturing deeper margin pools than spot-market transactions.
- Food Processing:Processed meat, savory snack, and ready-meal manufacturers deploy enhancers to reduce sodium, sugar, or fat content while maintaining sensory acceptance. Procurement concentrates among Southeast Asian instant noodle producers consolidating technical sourcing decisions into fewer buying centers.
- Beverages:Low-sugar formulation developers in China's beverage corridor leverage umami modulation platforms to mask off-notes in reduced-sugar products. This application commands premium positioning due to technical complexity and patent-protected taste modulation technologies.
- Dairy Products:Fermented dairy and plant-based milk alternatives utilize subtle savory enhancement for flavor depth.
- Seasonings:Direct-to-manufacturer bulk contracts dominate this deepest margin pool, with seasoning blenders bypassing distribution layers to secure captive supply relationships.
Food Processing commands the largest contract volume, while Beverages is gaining share fastest through innovation premiums.
End User:
Customer type fragmentation creates distinct service requirements, with manufacturers demanding technical co-development while foodservice operators prioritize logistics reliability and packaging flexibility.
- Manufacturers:Processed food and beverage producers with in-house R&D capabilities specify purity thresholds and glutamate equivalence ratios for integrated flavor systems. These buyers drive formulation partnership models requiring supplier technical staff embedded at manufacturing sites.
- Restaurants:Chain and independent foodservice operators procure standardized enhancer blends through distributor networks, with procurement decisions influenced by kitchen labor constraints and menu consistency requirements.
- Retailers:Private-label seasoning and sauce developers source enhancers for captive brand portfolios.
- Caterers:Institutional and event catering operations purchase volume-packaged enhancers through wholesale channels.
Manufacturers anchor the value pool, with Restaurants expanding most quickly through chain standardization mandates.
Distribution Channel:
Supply concentration in specific channel archetypes reflects buyer scale and technical service requirements, with bulk procurement gravitating toward direct manufacturer relationships while fragmented buyers rely on intermediaries.
- Wholesale:Bulk commodity amino acids and standard seasoning blends move through distributor networks serving mid-cap manufacturers and foodservice operators across Southeast Asia. This channel handles volume concentration for glutamate equivalence products with established specification standards.
- Online Retail:Specialty and small-batch enhancers reach artisanal producers and independent restaurants through digital procurement platforms. Growth concentrates in South Korea and Japan where technical documentation and certification transparency are digitized.
- Supermarkets:Consumer-packaged seasonings with enhancer components reach household buyers through retail shelf placement.
- Specialty Stores:Premium botanical extracts and clean-label positioning products serve niche formulation needs.
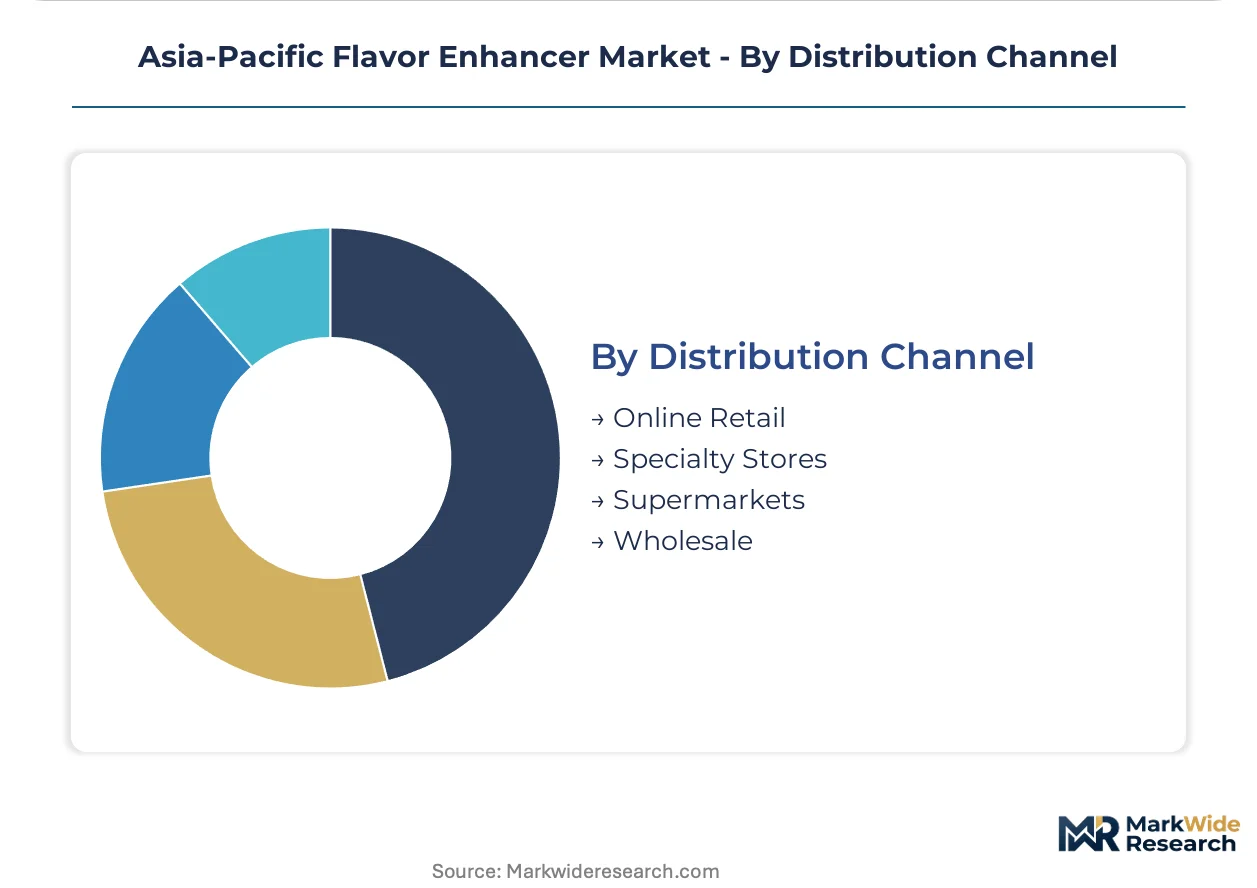
Wholesale retains the deepest volume concentration, with Online Retail expanding most quickly through procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's fermentation industry pioneered commercial amino acid production in the early twentieth century, establishing the technical foundation that now spans East Asian processed food corridors. Contemporary procurement patterns reflect this heritage while adapting to divergent national regulatory frameworks.
China
Processed food manufacturers across Shanghai, Guangzhou, and Chengdu drive concentrated demand for glutamate equivalence specifications in bulk seasoning contracts. SAMR's draft disclosure standards are tightening additive labeling requirements, forcing reformulation cycles among domestic instant noodle producers. The Yangtze River Delta cluster anchors fermentation capacity expansion serving both domestic consumption and export markets.
Japan
Positive list revisions from the Ministry of Health Labour and Welfare are compressing recertification timelines to eighteen-month windows. Food and beverage formulators in the Kanto region are accelerating displacement of nucleotide-based portfolios toward amino acid alternatives. Osaka-based seasoning blenders now demand integrated flavor systems with embedded technical documentation for import clearance protocols.
India
FSSAI contaminant limit tightening for nucleotide enhancers is forcing suppliers to recertify manufacturing sites or exit contract opportunities entirely. Savory snack producers in Maharashtra and Gujarat are expanding clean-label procurement to meet retailer sustainability mandates. The Mumbai-Pune corridor concentrates technical sourcing decisions for mid-cap seasoning manufacturers.
Australia
Food Standards Australia New Zealand's label-friendly framework creates export-ready positioning for botanical extraction capabilities. Natural extract demand clusters in Sydney and Melbourne serve reformulation requirements across premium processed food segments. Queensland cultivation zones supply concentrated botanical feedstocks for enzymatic hydrolysis platforms.
South Korea
Mid-cap seasoning manufacturers in Seoul and Busan are piloting hybrid bioprocessing lines combining precision fermentation with enzymatic hydrolysis. MFDS alignment with Codex standards reduces redundant testing for multi-country portfolios. The Daegu-Gyeongbuk region concentrates pilot-scale capacity for clean-label production scale-up.
Asia-Pacific Flavor Enhancer Market Competitive Environment
Premium-margin players sit above commodity-margin players across technical service intensity and certification depth, with integrated flavor system suppliers capturing deeper value pools than bulk amino acid merchants. The vendor base organizes into three tiers: fermentation technology leaders, botanical extraction specialists, and commodity-scale seasoning merchants. Consolidation pressure concentrates among mid-cap regional blenders seeking captive supply security. Dominant competitive moves include backward integration into natural extract sourcing and direct-to-manufacturer bulk contracting bypassing traditional distribution layers.
Within the fermentation technology tier, Ajinomoto Group exemplifies continuous bioprocessing leadership across East Asian markets. Among botanical extraction specialists, Symrise and Kerry Group occupy positions aligned with clean-label procurement mandates from Australian and Japanese regulators. Takasago represents specialized savory taste modulation capabilities serving regional formulation preferences. These three anchors illustrate divergent strategic postures: amino acid cost-position defense, natural extract portfolio expansion, and application-specific technical service depth.
| Leading Market Players |
|---|
| Kerry Group |
| Symrise |
| Givaudan |
| Archer Daniels Midland |
| Takasago |
| Firmenich |
| Cargill |
| Sensient Technologies |
| Ajinomoto Group |
| Others |
Value Chain & Pricing Dynamics
Molasses and starch feedstock costs cascade through fermentation-based amino acid production, compressing margins at commodity-grade tiers while premium natural extract positioning absorbs agricultural commodity volatility through long-term botanical cultivation contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated flavor systems with embedded technical documentation from bulk glutamate equivalence commodities and spot-market nucleotide compounds. Price differentiation hinges on certification grade against Japan's Ministry of Health Labour and Welfare positive list and volume scale in direct-to-manufacturer bulk contracts. Cost compression in economy-grade MSG runs through molasses price volatility and energy input spikes. Mid-cap seasoning manufacturers exhibit highest price sensitivity; beverage formulators deploying umami modulation platforms show lowest sensitivity due to patent-protected technical barriers.
Supply Chain Analysis
Certification gating through Food Standards Australia New Zealand label-friendly frameworks and India's FSSAI contaminant limits fragments supplier qualification timelines across the region. Raw material sourcing concentrates in China's Yangtze River Delta fermentation corridor, Queensland botanical cultivation zones, and Thai molasses processing clusters. Manufacturing draws from enzymatic hydrolysis platforms, continuous bioprocessing lines, and solvent extraction capabilities. Single-source vulnerability persists in natural extract botanical feedstocks clustered in specific cultivation geographies. Distribution runs through direct-to-manufacturer bulk contracting for integrated flavor systems alongside traditional wholesale channels for commodity amino acids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific flavor enhancer procurement functions as a geographic-arbitrage play between Japan's compressed eighteen-month recertification windows and Australia's export-ready label-friendly positioning, with cost differentials favoring fermentation capacity expansion in lower-regulatory-friction corridors.
For Market Incumbents: Cement dominance in amino acid cost-position through backward integration into molasses and starch feedstock sourcing, insulating against agricultural commodity cycles. Lock in captive supply relationships with Southeast Asian instant noodle manufacturers before buyer consolidation completes. Priority lever: embedded technical staff at manufacturing sites to accelerate reformulation partnership models and displace spot-market competitors. For New Entrants and Emerging Players: Enter via Australia's Food Standards Australia New Zealand-aligned botanical extraction capabilities serving Japanese export demand, bypassing nucleotide-based positive list scrutiny entirely. Target South Korean mid-cap seasoning manufacturers piloting hybrid bioprocessing lines as the most penetrable customer archetype. Go-to-market angle: precision fermentation yield improvements that compress capital requirements for clean-label entry. For Investors and Strategic Acquirers: Roll-up economics work for regional seasoning blenders seeking captive supply security because buyer consolidation among Southeast Asian instant noodle producers is compressing procurement decisions into fewer technical sourcing teams. Five-to-ten year viability hinges on fermentation technology maturation displacing conventional extraction. Signal to watch: SAMR finalization of carbon intensity metrics creating preferential procurement status for verified emissions reductions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sourcing | Molasses and starch procurement control insulates Ajinomoto Group and Kerry Group from agricultural commodity volatility squeezing mid-cap competitors. |
| Precision Fermentation Scale-Up | Continuous bioprocessing yield improvements lower unit economics for glutamate equivalence in mass-market seasoning applications across China's processed food corridor. |
| Direct-to-Manufacturer Bulk Contracting | Seasonings producers bypass distribution layers to capture margin pools through captive supply relationships with Thailand and Indonesia's top-three manufacturers. |
| Positive List Recertification Acceleration | Eighteen-month windows from Japan's Ministry of Health Labour and Welfare compress R&D cycles and favor incumbents with embedded technical documentation capabilities. |
| Botanical Extraction Certification Investment | Food Standards Australia New Zealand alignment creates export-ready positioning for Symrise and Kerry Group serving Japanese reformulation demand. |
Study Parameters
Direct dialogue with fermentation technology directors, seasoning manufacturer procurement leads, regulatory affairs specialists at flavor houses, and beverage formulator R&D heads grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, SEC filings of listed ingredient suppliers, Food Standards Australia New Zealand disclosure databases, and Japan's Ministry of Health Labour and Welfare positive list revisions. Bottom-up volume modeling across product type, application, and country portfolios triangulated against top-down macroeconomic indicators.
Segment-level outputs across amino acids, natural extracts, synthetic flavorings, and spices by food processing, beverages, dairy products, and seasonings applications were generated over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory recertification timelines and buyer consolidation patterns. Forecast inputs included molasses price indices, fermentation yield improvement trajectories, and positive list revision schedules.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time procurement contract terms and undisclosed reformulation partnership scopes introduce uncertainty bands around segment-level share estimates. Forecasts reflect assumptions about SAMR disclosure standard finalization and FSSAI contaminant limit enforcement intensity. A model refresh is warranted upon material change in Japan's Ministry of Health Labour and Welfare positive list revision frequency or China's dual carbon metrics implementation timeline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Anti-Sagging Agents Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market