
 Liquid Water Enhancers Market | 2026-2036
Liquid Water Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Water Enhancers Market Foresight
Buyer concentration among fitness centers and corporate wellness programs is shifting toward fragmented demand from home-based consumers and boutique gyms. Nestle S A leverages its beverage science infrastructure to sustain formulation leadership across electrolyte and vitamin-enhanced lines. The Coca-Cola Company anchors volume through mass retail channel control, while Stur Drinks LLC specializes in stevia-sweetened natural positioning that competes on clean-label differentiation.
Liquid water enhancers comprise concentrated, shelf-stable formulations—typically two to four milliliters per serving—designed to dilute into plain water and deliver flavor, electrolytes, vitamins, or caffeine without caloric load. These products employ hot-fill or aseptic processing to achieve ambient stability, serving commercial and residential users seeking portable hydration customization. Natural flavors segments command premium shelf placement as households reject artificial colorants, while single-serve packets dominate impulse channels and travel occasions. Bulk containers occupy foodservice and fitness center procurement, where cost-per-serving economics override portability preferences.
FDA governs GRAS status for non-nutritive sweeteners and flavor compounds, while EFSA thresholds on artificial additives shape export viability for North American manufacturers. State-level bottle deposit laws and extended producer responsibility frameworks in California and Oregon add compliance layers to packaging format decisions. Stakeholders must monitor evolving sweetener safety assessments and substrate sourcing requirements to preempt reformulation cycles and secure retail listing continuity.
Market Dynamics
The liquid water enhancers market is experiencing structural compression as clean-label mandates from FDA and EFSA force simultaneous reformulation across multiple sweetener categories, creating synchronized R&D cycles that favor scale players with captive beverage science infrastructure.
Growth Catalysts
- Functional Hydration Culture:Fitness centers and boutique gyms in the United States, Brazil, and Germany are normalizing concentrated electrolyte drops as standard equipment, embedding enhancers into workout rituals.
- Extended Producer Responsibility Frameworks:California and Oregon bottle deposit laws are accelerating packaging format innovation toward concentrated formats that reduce plastic intensity per serving.
- Aseptic Processing Advances:Hot-fill and ambient stability technologies are eliminating cold-chain requirements, unlocking convenience store and travel retail channels previously inaccessible to perishable alternatives.
Market Restraints
- GRAS Reassessment Cycles:FDA non-nutritive sweetener safety reviews create regulatory lag that freezes formulation decisions and extends new product development timelines.
- Stevia Supply Concentration:Stevia leaf extraction capacity concentrates in specific agricultural regions, exposing natural-positioned brands to raw material volatility and quality inconsistency.
- Tap Water Substitution:Municipal water quality improvements and filtered pitcher adoption in developed markets reduce the perceived necessity of flavor masking for hydration.
Strategic Opportunities
- Pediatric Formulation White Space:Vitamin-enhanced drops with controlled caffeine-free positioning for school-age children remain underdeveloped relative to adult sports segments.
- Corporate Wellness Procurement:Employer-subsidized hydration stations represent a B2B channel with contracted volume potential and lower customer acquisition costs than retail.
- Biodegradable Single-Serve Films:Water-soluble packaging technologies converging with concentrated formulations could eliminate plastic entirely for impulse and travel occasions.
Industry Challenges
- Flavor Chemist Scarcity:Formulation expertise spanning natural extract stability, electrolyte compatibility, and clean-label masking is concentrated among a limited pool of beverage scientists.
- Retailer Listing Timelines:Mass retail shelf resets occur on 12-18 month cycles, compressing window for new entrants to secure placement before formulation standards shift again.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Water Enhancers Market |
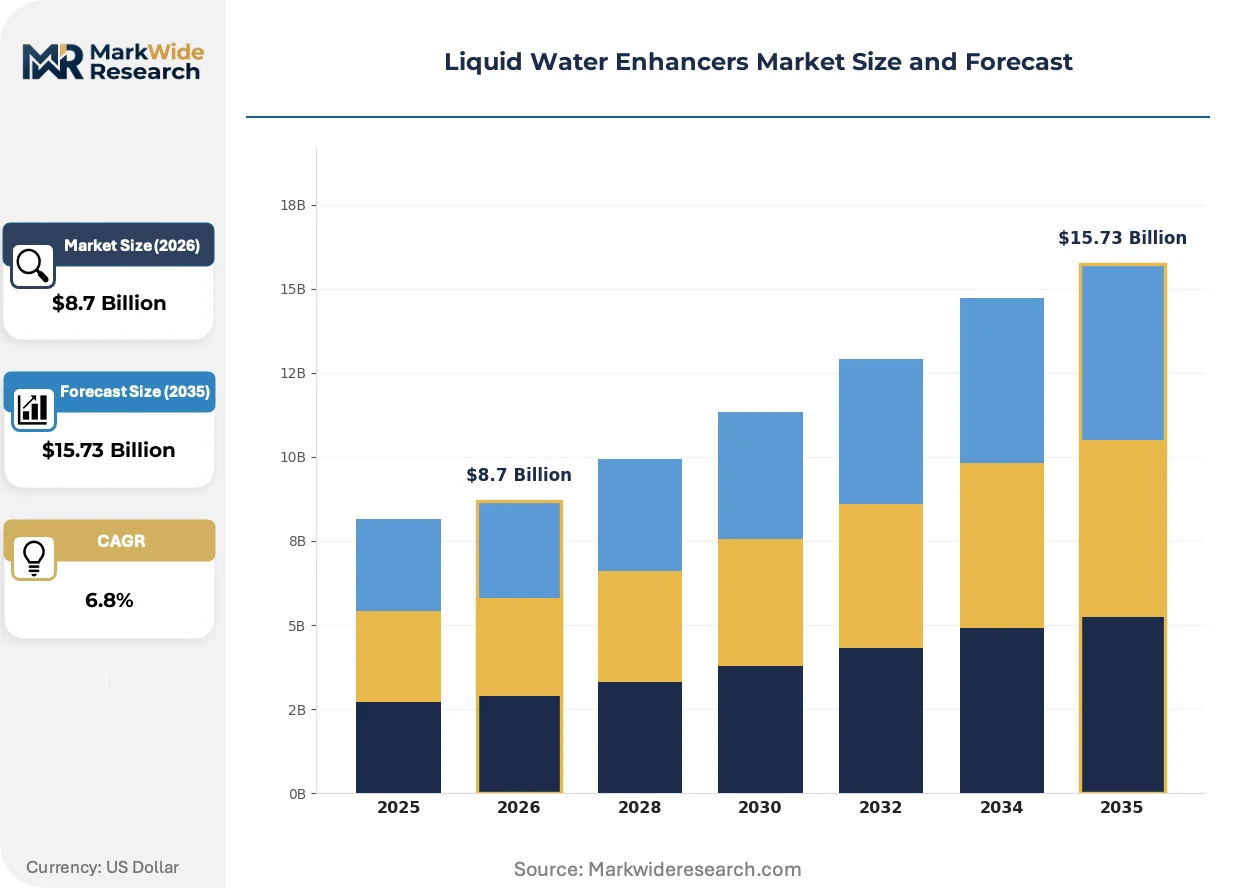
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Carbonated Enhancers, Sweeteners Packaging Type: Single-Serve Packets, Bottles, Bulk Containers, Pouches End User: Households, Fitness Centers, Cafés, Restaurants Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Vending Machines |
| Companies Covered | Nestle S A, Jel Sert, The Kraft Heinz Company, Arizona Beverages USA, 4C Foods, The Coca-Cola Company, Dyla LLC, Stur Drinks LLC, PepsiCo Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Water Enhancers Market Shifts & Advancements
Formulation transparency and processing efficiency are converging to redefine competitive advantage, with technology investments concentrating on stability science and regulatory pre-positioning rather than flavor novelty alone.
Micro-encapsulation of natural flavors is overtaking traditional heat-extraction methods as the dominant stability technology, protecting volatile compounds through aseptic processing temperatures. Mid-size manufacturers lacking captive encapsulation capacity are outsourcing to specialized ingredient houses, compressing margin structures and consolidating supplier relationships around technology licensors.
EFSA additive threshold tightening is reshaping export viability calculations for North American producers, forcing dual-formulation strategies or geographic product line segregation. Manufacturers serving EU markets are accelerating natural colorant substitution ahead of mandatory disclosure requirements, while domestic-only players risk stranded inventory if standards converge.
Home-based consumption patterns are fragmenting demand previously captured by fitness center bulk procurement, with households seeking portable single-serve formats for hybrid work schedules. E-commerce subscription models are displacing traditional grocery impulse purchases in the United States and Germany, requiring reformulation of marketing investment toward retention metrics rather than shelf visibility.
Liquid Water Enhancers Market Segmentation
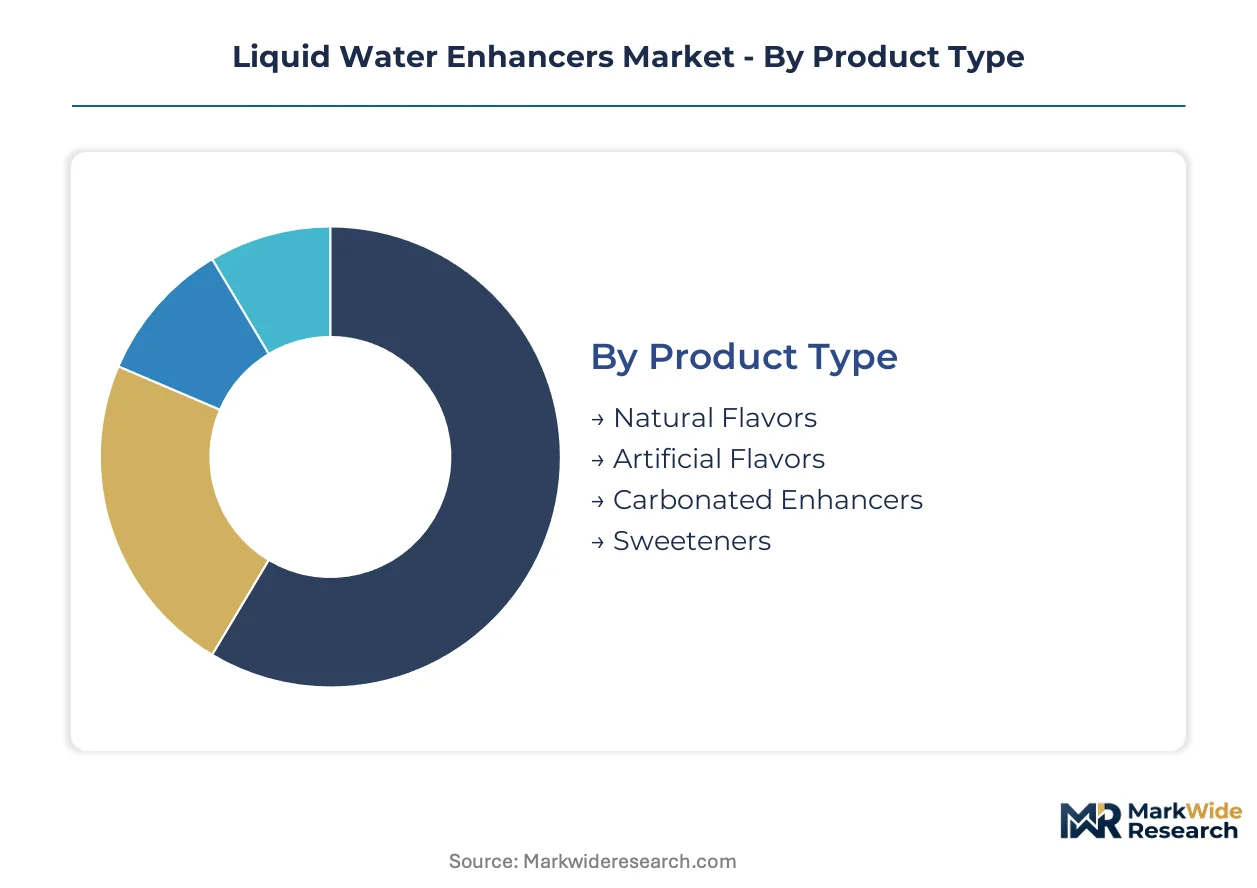
Liquid water enhancers fragment across formulation chemistry, portability requirements, and procurement context. Each dimension carries distinct regulatory burdens and margin structures that reshape competitive positioning across the value chain.
Product Type:
FDA GRAS determinations govern non-nutritive sweeteners and flavor compounds, while EFSA additive thresholds force dual-formulation strategies for export-oriented manufacturers. Natural extract stability requirements concentrate R&D investment among scale players with captive encapsulation infrastructure.
- Natural Flavors:Micro-encapsulation protects volatile compounds through hot-fill processing, replacing traditional heat-extraction methods. Demand concentrates in United States households rejecting artificial colorants, with premium shelf placement rewarding clean-label disclosure. Stevia leaf extraction capacity constraints expose this segment to agricultural volatility.
- Artificial Flavors:Synthetic compounds achieve cost-per-serving economics that undercut natural alternatives by significant margins. Procurement concentrates in foodservice and fitness center bulk purchasing where price sensitivity overrides label preferences. FDA safety review cycles create formulation freeze risks.
- Carbonated Enhancers:Pressurized formulations requiring specialized packaging compatibility with sparkling water systems.
- Sweeteners:Non-nutritive and nutritive variants spanning sucralose, stevia, and sugar alcohols with divergent stability profiles.
Leading the category by volume: Artificial Flavors. Expanding most quickly: Natural Flavors.
Packaging Type:
California and Oregon extended producer responsibility frameworks accelerate format innovation toward plastic intensity reduction. Cost-per-serving economics diverge sharply between impulse-channel portability and foodservice bulk efficiency.
- Single-Serve Packets:Two-to-four milliliter sachets dominate travel retail and convenience store channels where impulse purchasing drives trial. Demand concentrates in Germany and United States hybrid work households seeking desk-drawer portability. E-commerce subscription models are displacing traditional grocery placement for this format.
- Bottles:Multi-dose containers with calibrated droppers serve residential customization needs across flavor intensity preferences. Procurement concentrates in Brazilian supermarkets where household penetration of enhancers trails developed markets. Aseptic processing advances eliminate cold-chain barriers.
- Bulk Containers:Foodservice-scale packaging for fitness center hydration stations and corporate wellness programs.
- Pouches:Flexible format bridging single-serve convenience with reduced material intensity versus rigid bottles.
Volume leadership: Bottles. Steepest expansion trajectory: Single-Serve Packets.
End User:
Procurement authority and consumption occasion fragmentation reshape channel strategy, with B2B contracting offering volume certainty against retail acquisition costs.
- Households:Residential users drive flavor variety demand across age-segmented positioning including pediatric formulation white space. United States home-based consumption fragments demand previously captured by fitness center procurement. Filtered pitcher adoption in developed markets constrains perceived necessity.
- Fitness Centers:Boutique gyms in Brazil and Germany normalize electrolyte drops as standard equipment, embedding enhancers into workout rituals. Corporate wellness procurement offers contracted volume with lower customer acquisition costs.
- Cafés:Beverage customization for on-premise consumption with menu integration requirements.
- Restaurants:Table-service flavor personalization for water service programs.
Dominant by volume: Households. Gaining share fastest: Fitness Centers.
Distribution Channel:
Retailer shelf reset cycles compress new entrant windows, while digital retention metrics displace shelf-visibility investment.
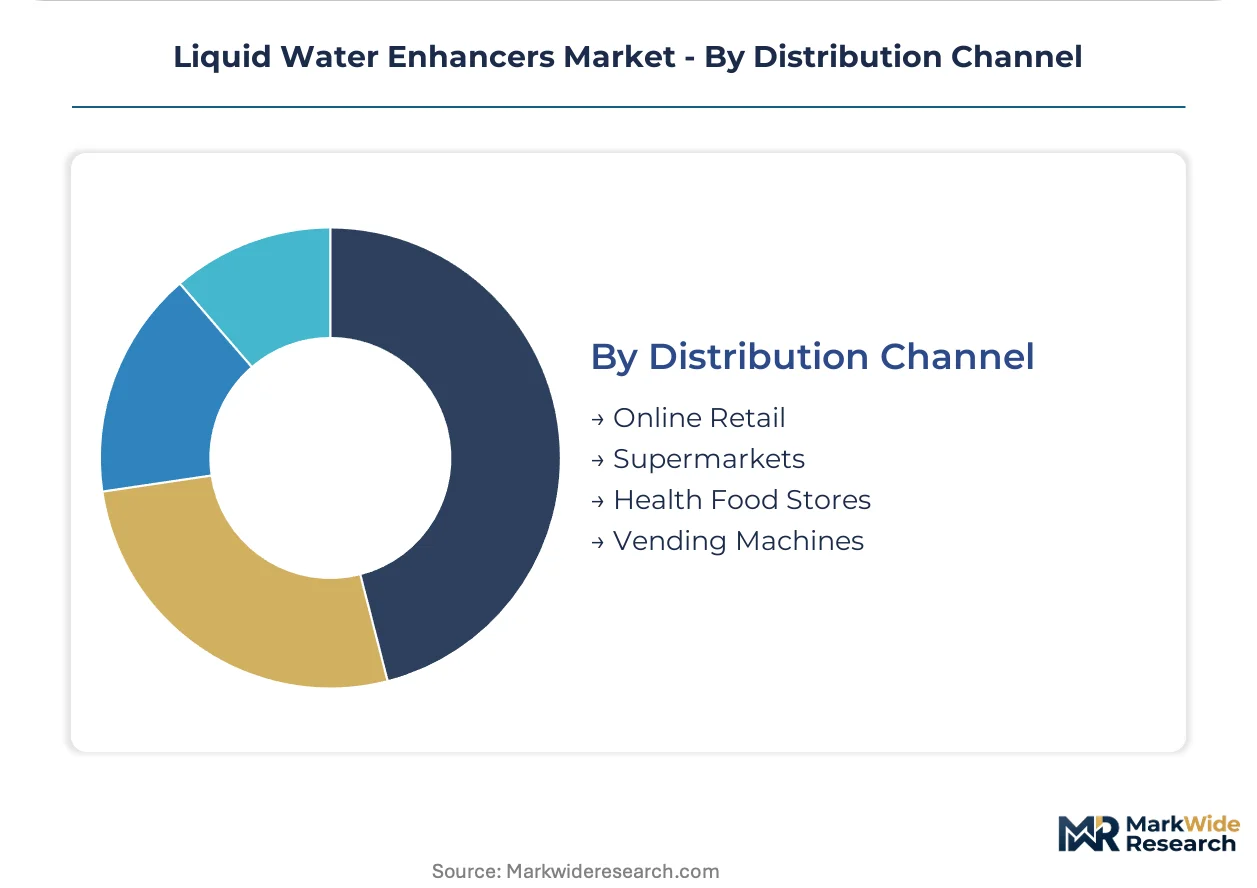
- Online Retail:Subscription models capture United States and Germany household replenishment with predictable recurring revenue. Data-driven flavor recommendation engines personalize assortment beyond physical shelf constraints.
- Supermarkets:Mass retail channel control anchors volume for established players with 12-18 month listing cycle relationships. Impulse placement at checkout drives trial for novel formats.
- Health Food Stores:Clean-label curation targets premium positioning with educated consumer self-selection.
- Vending Machines:Ambient-stable formats unlock travel and workplace occasions without cold-chain infrastructure.
Channel volume leader: Supermarkets. Climbing the fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for liquid water enhancers concentrates in the United States, Brazil, and Germany, where functional hydration culture has penetrated fitness centers and home consumption routines. These three markets anchor volume and innovation cycles, while regulatory divergence between FDA and EFSA jurisdictions creates formulation complexity for cross-border suppliers.
United States
Hybrid work households drive single-serve packet demand for desk-drawer portability, fragmenting procurement previously captured by corporate wellness programs. FDA GRAS reassessments of non-nutritive sweeteners create regulatory lag that freezes formulation decisions for mid-size players. California and Oregon extended producer responsibility frameworks accelerate packaging innovation toward concentrated formats with reduced plastic intensity per serving.
Brazil
Boutique gyms in São Paulo and Rio de Janeiro normalize electrolyte drops as standard workout equipment, embedding enhancers into fitness rituals ahead of household penetration. ANVISA governs additive safety thresholds for flavor compounds and sweeteners, requiring disclosure standards that lag FDA but converge with Mercosur harmonization efforts. Supermarket chains in the Southeast region dominate multi-dose bottle procurement where cost-per-serving economics override portability preferences.
Germany
EFSA additive threshold tightening forces natural flavor substitution ahead of mandatory disclosure requirements, compressing margins for artificial-positioned imports. E-commerce subscription models displace traditional grocery impulse purchases in Berlin and Munich, shifting marketing investment toward retention metrics. Bavarian and North Rhine-Westphalia fitness center chains drive bulk container procurement for hydration stations with contracted volume certainty.
United Kingdom
Health food store curation in London and Manchester targets premium clean-label positioning with educated consumer self-selection. FSA guidance on natural flavor claims creates compliance layers distinct from EFSA, complicating pan-European formulation strategies. Midlands-based beverage distributors consolidate supplier relationships around technology licensors with captive micro-encapsulation capacity.
Japan
Convenience store channels in Tokyo and Osaka unlock ambient-stable format penetration without cold-chain infrastructure, serving travel and workplace occasions. PMDA and METI standards on functional food claims restrict vitamin-enhanced positioning, limiting pediatric formulation development relative to Western markets. Kansai region specialty retailers curate stevia-sweetened imports for health-conscious aging demographics.
Liquid Water Enhancers Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation differentiation through clean-label infrastructure. The vendor base splits between consolidated beverage conglomerates with captive science infrastructure and fragmented natural-positioned specialists outsourcing encapsulation capacity. Three archetypes dominate: scale players controlling mass retail channel access, stevia-sweetened natural specialists competing on label transparency, and mid-size regional formulators serving foodservice bulk procurement. Competitive moves concentrate on portfolio diversification across sweetener categories and strategic partnerships with ingredient technology licensors.
Within the scale-driven tier, Nestle S A and The Coca-Cola Company occupy positions defined by beverage science infrastructure and retail channel control. Among natural-positioned specialists, Stur Drinks LLC exemplifies stevia-sweetened differentiation competing on clean-label disclosure standards. These three anchors represent the structural split between formulation leadership through R&D scale and market access versus positioning through ingredient sourcing and label transparency.
| Leading Market Players |
|---|
| Nestle S A |
| Jel Sert |
| The Kraft Heinz Company |
| Arizona Beverages USA |
| 4C Foods |
| The Coca-Cola Company |
| Dyla LLC |
| Stur Drinks LLC |
| PepsiCo Inc |
| Others |
Supply & Pricing Matrix
Captive micro-encapsulation infrastructure anchors both supply security and pricing power for scale manufacturers, while outsourced natural extract sourcing exposes mid-tier players to agricultural volatility and margin compression across stevia-dependent product lines.
Pricing Analysis
Volume leadership in artificial flavors trades margin for mass retail channel control, while natural flavors command premium positioning through clean-label certification tiers. Price differentiation separates stevia-sweetened premium lines from sucralose-based economy offerings, with FDA GRAS reassessment cycles intensifying cost compression in synthetic sweetener categories. Fitness center bulk procurement exhibits highest price sensitivity, whereas health food store channels absorb premium markups for transparent ingredient disclosure.
Supply Chain Analysis
California and Oregon extended producer responsibility frameworks are reshaping sourcing decisions toward concentrated formats with reduced plastic intensity per serving. Stevia leaf extraction capacity concentrates in Paraguay and China, while natural flavor compound production centers on United States and European specialty chemical houses. Single-source vulnerability runs through stevia agricultural regions exposed to climate volatility. Distribution runs through mass retail chains in the United States and Brazil, with e-commerce subscription models displacing traditional grocery replenishment in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-encapsulation technology is displacing legacy heat-extraction methods, creating formulation capability gaps that reshape competitive viability across natural flavor segments.
For Market Incumbents: Lock in captive encapsulation capacity through strategic partnerships with specialized ingredient houses or backward integration into natural extract processing. Defend shelf position against emerging stevia-sweetened specialists by accelerating dual-formulation portfolios that span regulatory jurisdictions. Channel control in mass retail remains the critical lever against subscription-model displacement. For New Entrants and Emerging Players: Pediatric formulation white space offers the most penetrable entry point, with vitamin-enhanced caffeine-free positioning for school-age children remaining underdeveloped relative to adult sports segments. Corporate wellness procurement channels provide contracted volume with lower customer acquisition costs than retail. A direct-to-employer go-to-market angle bypasses 12-18 month retailer listing timelines entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by scale beverage conglomerates seeking clean-label capability augmentation. Long-term viability hinges on formulation technology ownership rather than brand equity alone. The inflection signal to monitor is FDA GRAS reassessment timing for non-nutritive sweeteners, which would trigger synchronized reformulation cycles favoring acquirers with captive R&D infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Capacity Investment | Captive stability technology protects volatile natural compounds through aseptic processing temperatures. |
| Dual-Formulation Portfolio Development | Parallel FDA and EFSA-compliant lines secure export viability without geographic product segregation. |
| Corporate Wellness Channel Expansion | Employer-subsidized hydration stations offer contracted volume with lower customer acquisition costs. |
| Biodegradable Single-Serve Packaging | Water-soluble films eliminate plastic entirely for impulse and travel occasions under extended producer responsibility frameworks. |
| Pediatric Formulation Line Extension | Caffeine-free vitamin-enhanced drops address underdeveloped school-age positioning relative to adult segments. |
Research Methodology
Trade publications, beverage industry association reports, and regulatory filing databases formed the secondary backbone, supplemented by customs records and retail audit data. Primary interviews with beverage formulation scientists, mass retail category buyers, fitness center procurement managers, and regulatory affairs specialists provided ground-truth validation. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Historical trendline analysis established baseline growth patterns across natural and artificial flavor segments, with projection modeling incorporating packaging format shifts and channel migration dynamics. Segmentation dimensions spanned formulation chemistry, portability requirements, procurement context, and distribution channel structure. CAGRs were derived from fitted growth curves calibrated to regulatory milestone timing and technology adoption S-cycles.
Revisions become necessary when FDA GRAS reassessments materially alter sweetener viability, EFSA additive thresholds accelerate beyond modeled timelines, or stevia supply disruptions exceed historical volatility bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Australia Water Enhancer Market