
 Water Enhancer Market | 2026-2036
Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Water Enhancer Market Analysis
Clean-label formulation technology is narrowing the gap between natural taste profiles and shelf-stable concentrates. Nestlé S.A. leverages its botanical extraction infrastructure to sustain premium positioning in herbal sub-segments. Keurig Dr. Pepper anchors its portfolio through single-serve compatibility systems that dominate convenience channels. The Coca-Cola Company differentiates via stevia-leaf innovation pipelines and sports-partnership distribution.
Water enhancers are concentrated liquid, powder, or tablet additives that dissolve in plain water to impart flavor, electrolytes, vitamins, or functional compounds, typically formulated at dilution ratios between 1:12 and 1:24 with pH stabilizers and natural or nature-identical flavor systems. Their primary commercial purpose is converting commodity bottled or tap water into differentiated, higher-margin beverage occasions without refrigerated supply chain requirements. Syrups and drops capture the dominant volume share due to format flexibility across on-the-go and at-home consumption, while tablets register the fastest structural expansion among athletes and travel-oriented users. Online retail and health stores concentrate margin pools through subscription models and practitioner endorsements that command price premiums over mass supermarket placements.
FDA GRAS self-affirmation pathways and EFSA novel food assessments govern ingredient approvals on opposite sides of the Atlantic, while the EU Green Deal packaging directives pressure single-serve plastic formats toward biodegradable or concentrated refill alternatives. The FSSAI in India and China's SAMR impose divergent additive labeling thresholds that fragment export formulation strategies. Stakeholders must monitor evolving clean-label enforcement intensity and decide whether to regionalize production or absorb compliance-driven SKU proliferation.
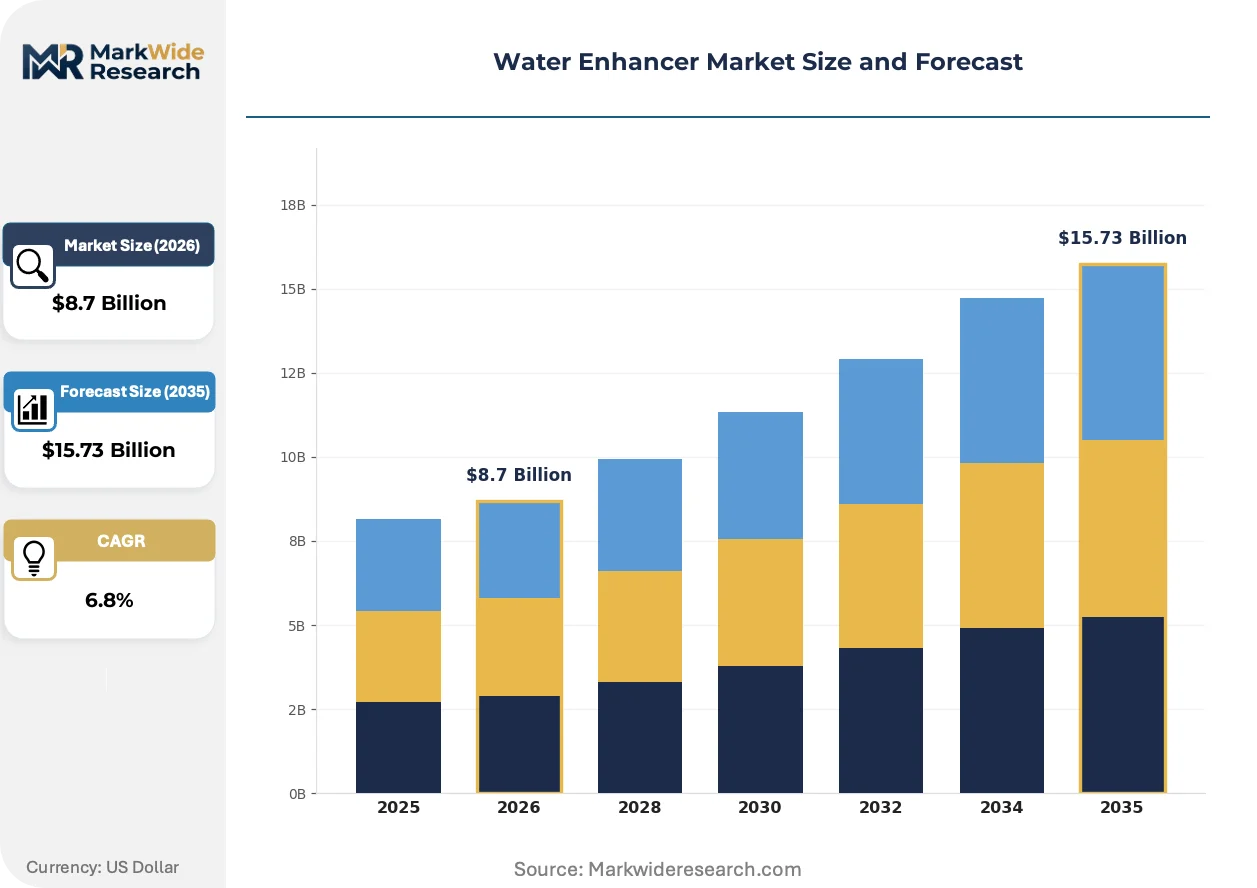
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are compressing synthetic additive pipelines while botanical extraction infrastructure becomes the decisive competitive moat. This regulatory compression is forcing simultaneous reformulation across multiple preservative categories.
Growth Catalysts
- EFSA Novel Food Pathways:Accelerated approval timelines for stevia-leaf derivatives and fermented botanicals are expanding permissible ingredient palettes for European formulators.
- Functional Hydration Culture:Electrolyte-enhanced concentrates are penetrating cycling, running, and CrossFit communities in the United States and Germany through practitioner endorsement networks.
- Biodegradable Single-Serve Formats:EU Green Deal packaging directives are pulling investment into concentrated refill systems and dissolvable film technologies that eliminate plastic waste streams.
Market Restraints
- Stevia Leaf Volatility:Agricultural supply concentration in Paraguay and China creates input cost instability for natural sweetener-dependent formulations.
- Flavor Stability Limitations:Citrus and berry extracts degrade faster than synthetic alternatives, constraining shelf-life claims and distribution radius.
- FSSAI Additive Thresholds:India's divergent labeling requirements for nature-identical versus natural flavors force SKU fragmentation for exporters targeting South Asian markets.
Strategic Opportunities
- SAMR Clean-Label Tailwinds:China's State Administration for Market Regulation is tightening artificial additive disclosure rules, creating first-mover advantage for botanical-forward entrants.
- Subscription Direct-to-Consumer Channels:Practitioner-curated monthly replenishment models bypass supermarket slotting fees and capture recurring revenue pools.
- Tablet Convergence with Wearables:Athletes are pairing effervescent electrolyte tablets with biometric hydration trackers, opening data-integrated product ecosystems.
Industry Challenges
- Flavor Chemist Scarcity:Natural taste profiling expertise sits concentrated with legacy fragrance houses, inflating R&D compensation costs.
- Multi-Jurisdiction Certification Timelines:Parallel FDA GRAS self-affirmation and EFSA novel food assessments extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Enhancer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syrups, Powders, Drops, Tablets Flavor Profile: Fruit, Herbal, Citrus, Mint End User: Health Conscious Consumers, Athletes, Families, Seniors Distribution Channel: Online Retail, Supermarkets, Health Stores, Clubs |
| Companies Covered | Nestlé S.A., Keurig Dr. Pepper, The Coca-Cola Company, Jel Sert, Dyla LLC, The Kraft Heinz Company, Unilever PLC, Nuun, PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Enhancer Market Emerging Trajectories
Formulation science is converging with digital traceability systems to create ingredient provenance as a purchasable attribute. This shift is elevating supply chain transparency from compliance checkbox to premium pricing mechanism.
Encapsulation technology using modified starch and gum arabic matrices is digitizing flavor release profiles in water enhancers. Sports nutrition brands in Germany are adopting micro-encapsulated caffeine and B-vitamin systems that activate at specific consumption temperatures. This precision delivery architecture is compressing the functional beverage category boundary by enabling tap-water transformation without refrigeration infrastructure.
REACH regulation amendments targeting microplastic-free claims are reshaping European formulation strategies. ECHA restrictions on synthetic polymer-based colorants are accelerating migration toward anthocyanin and chlorophyll-derived alternatives. German retailers are responding with mandatory clean-label scorecards that penalize undisclosed processing aids.
Practitioner endorsement networks are displacing traditional retail discovery for functional water enhancers. Registered dietitians and sports medicine physicians in the United States are curating private-label concentrate portfolios for patient cohorts. This channel shift concentrates margin capture with credentialed intermediaries rather than mass-market distributors.
Water Enhancer Market Segmentation
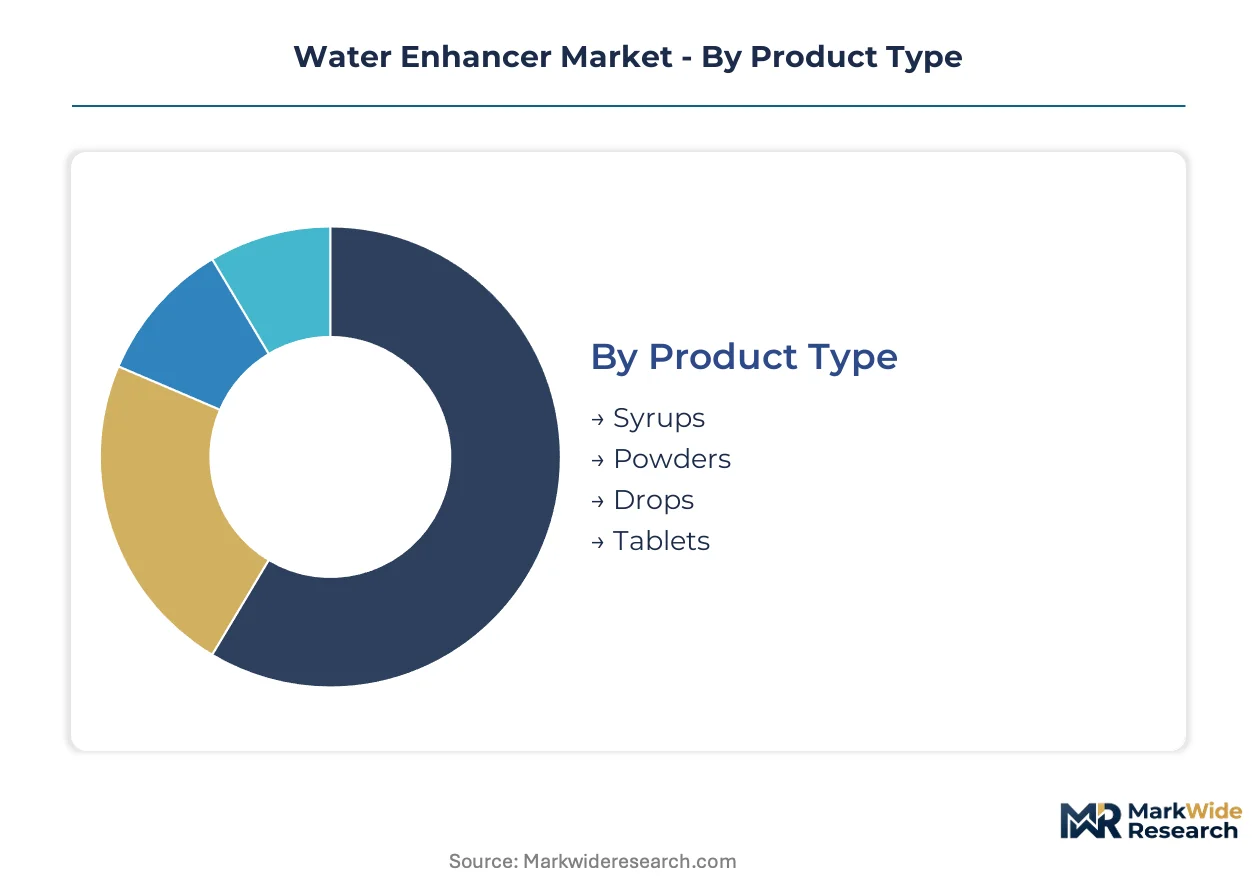
Water enhancer manufacturers segment demand across four intersecting dimensions that determine formulation priorities and channel economics. Product format dictates supply chain requirements, while flavor profile governs raw material sourcing strategies. End-user targeting shapes marketing spend allocation, and distribution channel selection determines margin capture potential.
Product Type:
Syrups and drops turn inventory fastest through impulse-driven convenience channel velocity, whereas tablets and powders cycle slower through practitioner-curated subscription replenishment.
- Syrups:Concentrated liquid formulations dilute at ratios between 1:12 and 1:24, incorporating pH stabilizers and preservative systems for ambient shelf stability. Demand concentrates in the United States through single-serve compatibility systems that dominate gas station and pharmacy checkout placement, though clean-label reformulation pressures are compressing synthetic additive pipelines.
- Tablets:Effervescent and non-effervescent compressed formats dissolve in water to release electrolytes, vitamins, or botanical actives with precise dosing control. Athletes in Germany and the United States drive adoption through pairing with biometric hydration trackers, creating data-integrated product ecosystems that command subscription premiums.
- Powders:Granular or crystalline concentrates packaged in stick packs or bulk canisters offer portability and customizable dosing flexibility.
- Drops:Ultra-concentrated liquid micro-dosage formats deliver intense flavor impact through minimal volume addition.
Syrups dominate installed base. Tablets are where expansion concentrates.
Flavor Profile:
Flavor selection maps directly to agricultural input exposure and extraction technology requirements, with citrus and berry profiles demanding more sophisticated stabilization investments than herbal alternatives.
- Fruit:Berry, tropical, and orchard fruit formulations rely on nature-identical and natural flavor systems with varying degradation kinetics. Families in the United States drive volume through mass-market supermarket placement, though citrus and berry extract stability limitations constrain shelf-life claims and distribution radius for premium-positioned variants.
- Herbal:Botanical extracts including chamomile, lavender, hibiscus, and adaptogenic roots leverage Nestlé's extraction infrastructure and similar legacy capabilities. Health-conscious millennials in Germany sustain premium positioning through practitioner endorsement networks that bypass traditional retail discovery channels.
- Citrus:Lemon, lime, and orange profiles face accelerated oxidative degradation requiring encapsulated or stabilized extract systems.
- Mint:Peppermint and spearmint variants offer masking properties for functional ingredients with strong inherent tastes.
Fruit flavors anchor mass-market volume. Herbal profiles are climbing the fastest through credentialed distribution.
End User:
Customer archetypes diverge sharply in purchase frequency, price elasticity, and information sourcing behavior, requiring distinct go-to-market architectures.
- Health Conscious Consumers:Millennials and Gen Z cohorts prioritize clean-label ingredient transparency and functional benefit verification through third-party certifications. This segment concentrates in Western Europe and North America where EFSA and FDA disclosure mandates have normalized ingredient provenance as a purchasable attribute.
- Athletes:Cyclists, runners, and CrossFit practitioners demand electrolyte-enhanced concentrates with precise mineral ratios for hydration optimization. Practitioner endorsement networks in the United States and Germany curate private-label portfolios, concentrating margin capture with credentialed intermediaries.
- Families:Multi-user households prioritize value formats, familiar flavor profiles, and child-friendly packaging designs.
- Seniors:Age-related hydration awareness and medication interaction concerns drive demand for low-sodium, vitamin-fortified options.
Health conscious consumers represent the largest addressable base. Athletes are gaining share fastest through subscription channel development.
Distribution Channel:
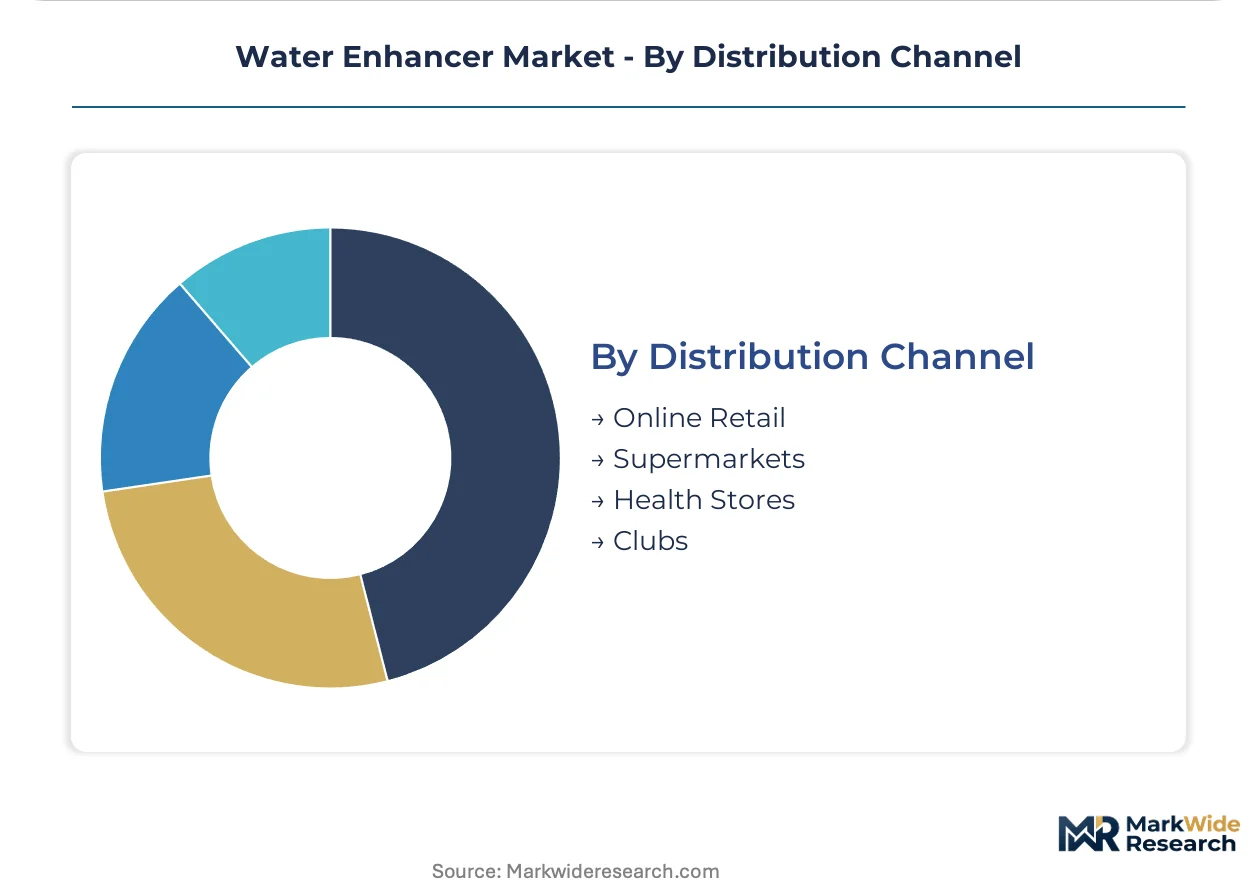
Channel selection determines working capital intensity and customer data access, with direct models offering superior lifetime value capture at higher acquisition cost.
- Online Retail:E-commerce platforms and direct-to-consumer storefronts enable subscription replenishment models with recurring revenue predictability. The United States concentrates margin pools through practitioner-curated monthly programs that bypass supermarket slotting fees.
- Health Stores:Specialty retailers and practitioner offices command price premiums through endorsement credibility and educated staff consultation. Germany's retailer-mandated clean-label scorecards penalize undisclosed processing aids, accelerating migration toward anthocyanin and chlorophyll-derived alternatives.
- Supermarkets:Mass-market grocery and hypermarket placement drives volume visibility through end-cap and checkout positioning.
- Clubs:Warehouse and membership-based retailers move bulk formats with compressed per-unit economics.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious millennials and Gen Z consumers concentrate in the United States and Germany, where functional hydration culture penetrates deepest and clean-label standards reshape ingredient sourcing strategies.
United States
Cyclists, runners, and CrossFit practitioners drive electrolyte-enhanced concentrate adoption through practitioner endorsement networks. FDA GRAS self-affirmation pathways govern ingredient approvals, compressing synthetic additive pipelines. Greater Boston and Austin host subscription-model startups pairing effervescent tablets with biometric hydration trackers.
Germany
Health-conscious millennials sustain premium herbal positioning through credentialed distribution channels. EFSA novel food assessments and EU Green Deal packaging directives pull investment into concentrated refill systems. Bavaria's retailer-mandated clean-label scorecards penalize undisclosed processing aids, accelerating botanical extraction infrastructure deployment.
China
SAMR clean-label tailwinds create first-mover advantage for botanical-forward entrants targeting artificial additive disclosure tightening. The State Administration for Market Regulation's evolving standards fragment export formulation strategies. Yangtze River Delta manufacturing clusters regionalize production to absorb compliance-driven SKU proliferation.
India
FSSAI divergent labeling requirements for nature-identical versus natural flavors force SKU fragmentation for exporters. The Food Safety and Standards Authority of India imposes additive thresholds that complicate multi-jurisdiction certification timelines. Maharashtra and Karnataka concentrate demand among urban health-conscious cohorts seeking functional hydration alternatives.
United Kingdom
Practitioner-curated subscription models bypass supermarket slotting fees and capture recurring revenue pools among wellness-focused consumers. REACH regulation amendments targeting microplastic-free claims reshape formulation strategies. London and Southeast England anchor direct-to-consumer channel development for tablet and powder formats.
Water Enhancer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Nestlé S.A., Keurig Dr. Pepper, and The Coca-Cola Company anchor the consolidated upper tier through distribution infrastructure and botanical extraction capabilities. Mid-cap specialists occupy practitioner-curated subscription channels. Competitive moves concentrate on clean-label reformulation acceleration and biodegradable single-serve format development.
Within the diversified-multinational tier, Nestlé S.A. and The Coca-Cola Company exemplify archetypes leveraging legacy extraction infrastructure and stevia-leaf innovation pipelines respectively. Keurig Dr. Pepper occupies a position anchored through single-serve compatibility systems. These Swiss and American entities represent contrasting strategic postures: one emphasizing botanical-forward premium positioning, the other emphasizing sports-partnership distribution networks.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Keurig Dr. Pepper |
| The Coca-Cola Company |
| Jel Sert |
| Dyla LLC |
| The Kraft Heinz Company |
| Unilever PLC |
| Nuun |
| PepsiCo, Inc. |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Los Angeles container freight corridors transmit cost volatility from Paraguayan stevia leaf harvests into German retail price differentiation, compressing margins for synthetic-dependent formulators while amplifying premium capture for botanical-extraction leaders.
Pricing Analysis
Cost-plus contracts with stevia leaf indexation dominate raw material procurement, though finished goods pricing stratifies across premium, standard, and economy tiers based on certification grade and channel positioning. FDA GRAS self-affirmation tiers command 15-25% premiums over unverified alternatives, while supermarket slotting fees in the United States force price compression on mass-market syrups. Subscription-direct models exhibit lowest price sensitivity among athlete segments pairing tablets with biometric trackers.
Supply Chain Analysis
Contract manufacturing concentrates with Nestlé's botanical extraction infrastructure in Switzerland, The Coca-Cola Company's stevia processing in Georgia, and Keurig Dr. Pepper's single-serve packaging in Vermont. Stevia leaf supply draws from Paraguayan agricultural cooperatives and Chinese processing facilities, while pH stabilizers and encapsulation matrices source from German chemical specialists. Single-source vulnerability in Paraguayan leaf concentration creates tariff-exposure risk. Distribution runs through practitioner-curated subscription channels capturing recurring revenue pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward credentialed practitioner networks consolidating demand curation in the United States and Germany, fragmenting traditional supermarket channel control.
For Market Incumbents: Entrench botanical extraction capabilities through backward integration into Paraguayan stevia cooperatives, defending against emerging clean-label specialists. Accelerate EFSA novel food certification pipelines to maintain premium positioning as SAMR disclosure rules tighten in China.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka urban corridors present underpenetrated demand among health-conscious cohorts seeking functional hydration alternatives, bypassing FSSAI SKU fragmentation through localized formulation partnerships. Target practitioner endorsement networks with tablet-wearable integration propositions.
For Investors and Strategic Acquirers: Mid-cap subscription-model specialists with captive practitioner networks offer acquisition exposure to recurring revenue pools displacing supermarket slotting-fee dependence. Watch EFSA novel food approval velocity as inflection signal for European formulation premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Extraction Infrastructure Expansion | Captures Paraguayan stevia supply security ahead of agricultural volatility. |
| EFSA Novel Food Certification Acceleration | Unlocks European premium positioning for fermented botanical formulations. |
| Practitioner Network Partnership Development | Bypasses supermarket slotting fees through credentialed demand curation. |
| Biodegradable Single-Serve Format Migration | Aligns with EU Green Deal packaging directives eliminating plastic waste. |
| Tablet-Wearable Ecosystem Integration | Commands subscription premiums through biometric hydration data pairing. |
Methodological Framework
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork encompassed brand managers at multinational beverage companies, category buyers at German health retailers, sports medicine physicians curating patient portfolios, and supply planners managing stevia leaf procurement. Secondary sources included FDA GRAS self-affirmation notices, EFSA novel food assessment records, EU Green Deal packaging directive amendments, and customs data tracking Paraguayan agricultural exports. Bottom-up volume modeling triangulated against top-down category spend estimates.
Calibration against historical adoption curves in functional beverage categories shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product format, flavor profile, end-user archetype, and distribution channel, with regional regulatory clusters modeled separately. CAGRs derived from trend extrapolation adjusted for enforcement intensity of clean-label mandates. Industry-specific inputs included stevia leaf harvest volatility indices and practitioner endorsement network expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by emerging botanical specialists would shift outcomes. Quarterly review of EFSA novel food approval timelines and SAMR disclosure rule amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Yellow Fats Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market