
 Canada Food Flavor and Enhancer Market | 2026-2036
Canada Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
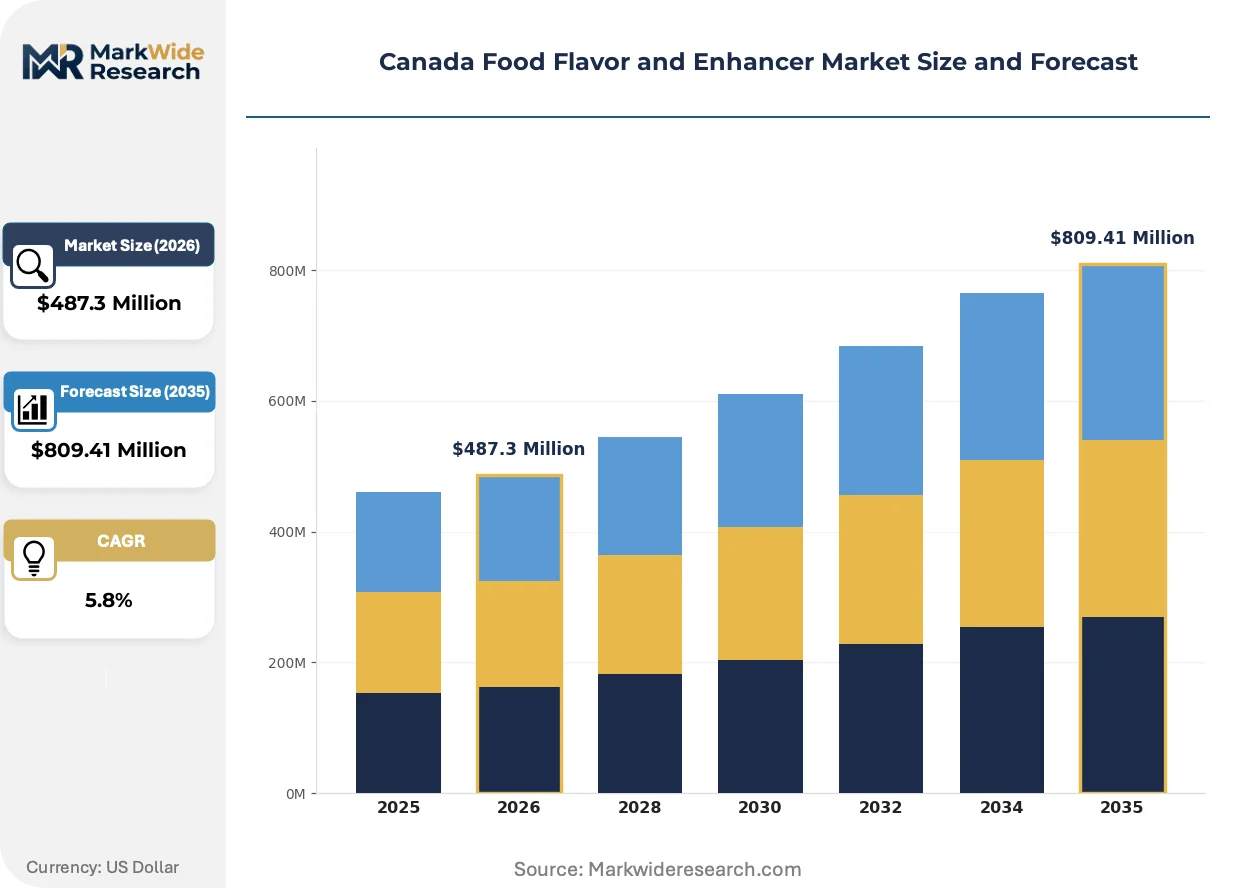
Canada Food Flavor and Enhancer Market Outlook
Premium clean-label specification tiers is rotating demand away from conventional synthetic portfolios. Kerry Group leverages its North American ingredient network to anchor supply security for Canadian processors. Givaudan differentiates through biotechnology-derived natural flavor platforms tailored to regional palates. Aromatics+Flavors Inc. competes as a domestic specialist with concentrated R&D operations near Toronto.
Food flavors and enhancers comprise aromatic compounds, taste-active molecules, and umami-intensifying additives formulated to modify or intensify sensory perception in processed and prepared foods; these substances typically undergo extraction, fermentation, or chemical synthesis to achieve target flavor profiles at parts-per-million dosing precision. Their primary commercial purpose centers on standardizing taste consistency across batch production while enabling sodium and sugar reduction in reformulated products. Natural flavoring commands structural priority as consumer skepticism toward synthetic additives hardens, though enhancers deliver the steepest growth trajectory given clean-label umami solutions for snack and savory applications. Liquid form retains dominance in beverage and dairy processing lines, while powder formulations gain share in bakery dry mixes where shelf stability governs procurement decisions.
Health Canada, the Canadian Food Inspection Agency, and Safe Food for Canadians Regulations collectively shape permissible additive lists, labeling thresholds, and import verification protocols that determine market access for both domestic blenders and foreign suppliers. CFIA enforcement of preventive control plans forces smaller flavor houses toward third-party certification investments that larger competitors already amortize. Stakeholders must monitor pending amendments to Health Canada's Food and Drug Regulations for novel flavor substances, as approval timelines will determine which portfolios capture reformulation cycles in ready-meal and plant-protein segments.
Market Dynamics
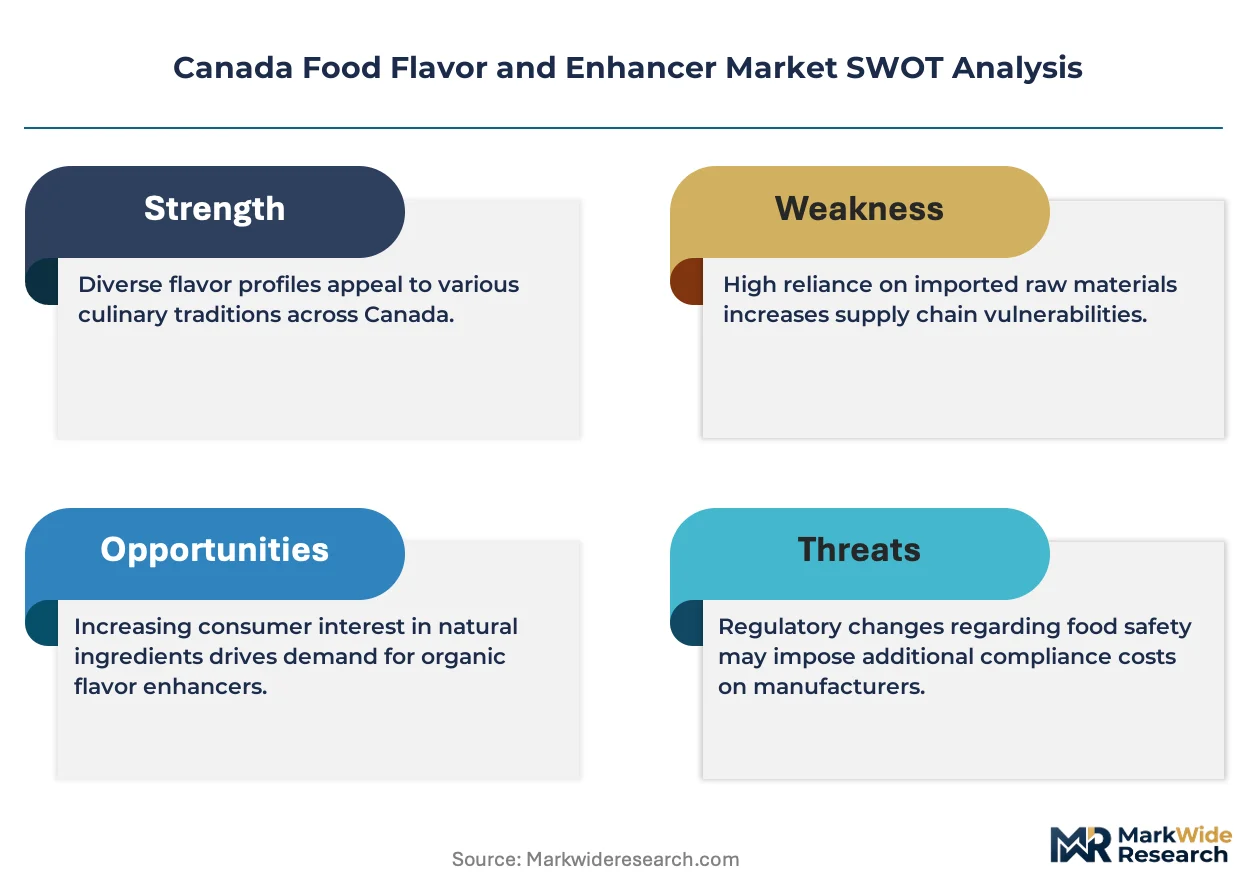
Health Canada's tightening thresholds for synthetic additives are forcing reformulation cycles across Ontario and Quebec processing corridors, compressing timelines for clean-label transitions while elevating biotechnology-derived alternatives.
Growth Catalysts
- Clean-label mandates:Safe Food for Canadians Regulations enforcement accelerates natural flavor adoption in ready-meal manufacturing. Processors retrofit lines to eliminate artificial enhancers before compliance deadlines.
- Biotechnology maturation:Precision fermentation yields cost-competitive natural umami molecules. Savory snack producers scale these inputs to achieve sodium reduction targets without sensory compromise.
- Industrial corridor density:The Toronto-Montreal food service axis concentrates demand for standardized flavor systems. Large-scale bakery and dairy operations drive volume procurement of liquid flavor concentrates.
Market Restraints
- Input cost volatility:Vanilla and citrus extract prices fluctuate with climate-driven harvest variability. Natural flavor portfolios carry margin exposure that synthetic alternatives avoid.
- Regulatory friction:Health Canada's novel food substance approval timelines extend 18-24 months for biotechnology-derived ingredients. Portfolio expansion delays favor incumbents with existing approved substance lists.
- Supply concentration:Domestic extraction capacity for maple and botanical derivatives clusters in southern Ontario. Geographic concentration creates vulnerability to regional processing disruptions.
Strategic Opportunities
- Plant-protein formulation:Meat alternative manufacturers in Alberta and British Columbia require masking and enhancing systems for legume and mycoprotein bases. Flavor houses can anchor regional supply partnerships.
- CFIA certification services:Preventive control plan verification creates adjacent revenue streams. Third-party certification expertise addresses capability gaps among mid-tier flavor blenders.
- Direct-to-manufacturer channels:E-commerce platforms for sample distribution and technical consultation reduce reliance on distributor networks. Smaller Ontario processors prefer digital procurement for formulation development.
Industry Challenges
- Flavor chemist scarcity:Specialized expertise in natural extraction and fermentation scale-up concentrates among senior practitioners. Knowledge transfer bottlenecks constrain R&D throughput for domestic specialists.
- Legacy system integration:Powder-to-liquid conversion equipment requires capital deployment that smaller Quebec bakeries defer. Dry mix manufacturers face productivity gaps against integrated liquid processing competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Flavor and Enhancer Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavoring, Synthetic Flavoring, Enhancers, Seasoning Form: Liquid, Powder, Granular, Paste Application: Bakery, Dairy, Beverage, Snacks Consumer Type: Households, Food Service, Catering, Industrial |
| Companies Covered | Kerry Group, Archer Daniels Midland Company, Givaudan, Flavorcan International Inc., Takasago International Corporation, Firmenich, Koninklijke DSM N.V., Aromatics+Flavors Inc., International Flavors and Fragrances Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Flavor and Enhancer Market Strategic Shifts
Biotechnology-derived flavor platforms are compressing cost structures for natural alternatives while regulatory modernization rewrites permissible substance lists. These forces are rotating procurement priorities across Canadian food manufacturing.
Precision fermentation for natural flavor molecules is fragmenting the traditional extraction supply base. Dairy processors in Ontario adopt these inputs at accelerating pace to meet clean-label dairy modifier demand. The technology is fragmenting established botanical supply relationships and compressing lead times from raw material to finished flavor compound.
Health Canada's Food and Drug Regulations amendment process for novel substances tightens approval documentation requirements. Flavor houses must expand toxicology and stability data packages before commercialization. Biotechnology-derived umami enhancers face the steepest compliance burden, delaying portfolio launches in savory applications.
Quebec and Ontario processors increasingly specify certified organic flavor tiers in procurement contracts. Conventional synthetic portfolios lose shelf space as retail private-label standards harden. This specification escalation concentrates purchasing power among large-scale manufacturers capable of certifying entire supply chains.
Canada Food Flavor and Enhancer Market Segmentation
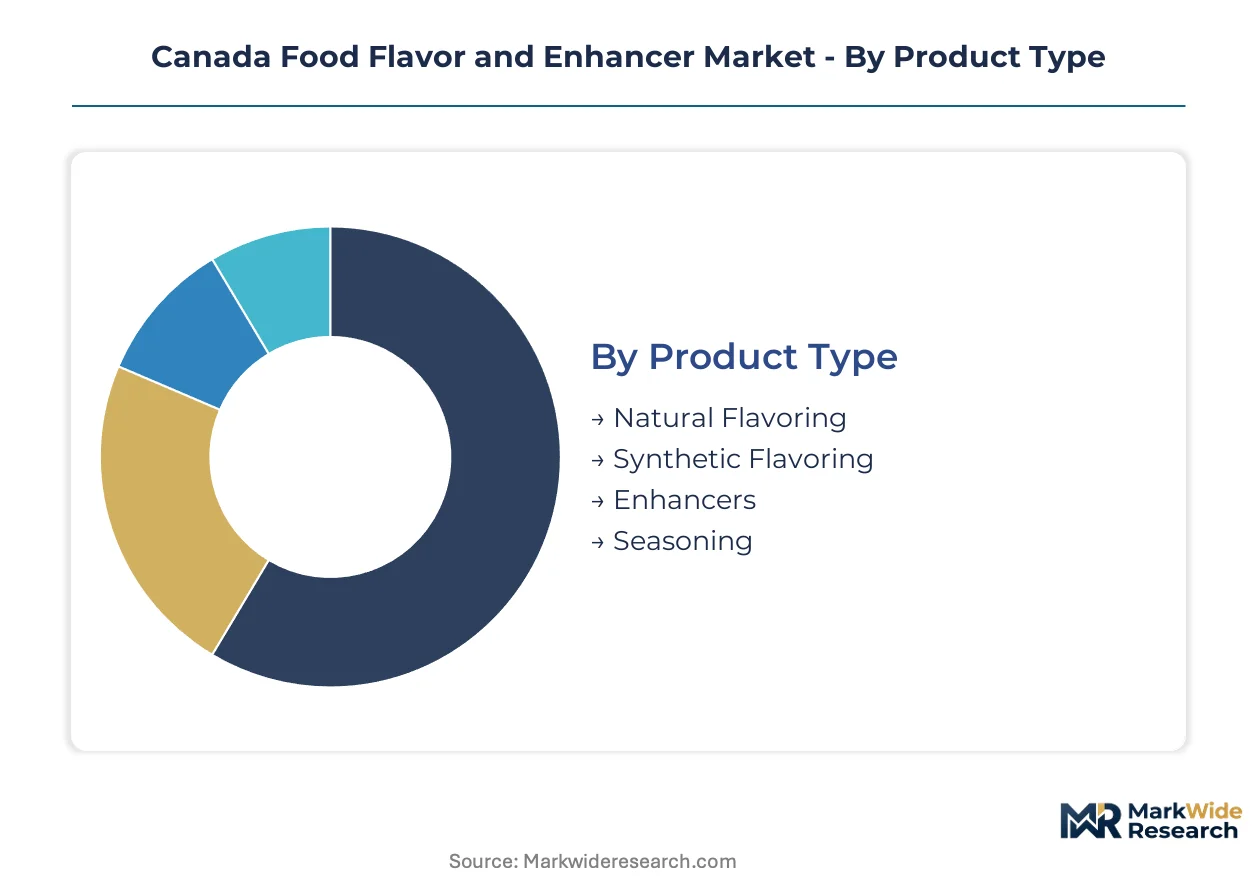
Segmentation in the Canada food flavor and enhancer market reveals distinct procurement patterns across product tiers and application channels. Clean-label mandates concentrate margin capture in specific natural flavoring and enhancer categories while form specifications govern equipment compatibility across Ontario and Quebec processing lines.
Product Type:
Margin pools concentrate in enhancers and natural flavoring as Health Canada tightens synthetic additive thresholds and processors absorb reformulation premiums.
- Natural Flavoring:Extracts and essential oils derived from botanical, spice, and fermentation sources deliver clean-label compliance for bakery and dairy reformulations. Ontario processors pay specification premiums to secure maple, vanilla, and citrus extracts amid volatile harvest cycles.
- Enhancers:Umami-intensifying molecules including yeast extracts, nucleotides, and biotechnology-derived alternatives enable sodium reduction without sensory loss. Demand concentrates in savory snack manufacturing across the Toronto-Montreal corridor as processors retrofit lines for clean-label positioning.
- Synthetic Flavoring:Chemically synthesized aromatic compounds face contracting procurement volumes under Safe Food for Canadians Regulations enforcement.
- Seasoning:Pre-blended spice and herb combinations serve food service and catering channels requiring batch consistency.
Enhancers hold installed capacity. Natural Flavoring is rotating up the share rankings.
Form:
Equipment integration costs across Quebec and Ontario processing facilities determine form selection premiums and retrofit timelines.
- Liquid:Concentrated solutions and emulsions dominate beverage and dairy processing lines where pump-fed dosing systems govern production economics. Toronto-area dairies specify liquid modifiers for clean-label milk and plant-protein beverage reformulations.
- Powder:Spray-dried and encapsulated formats gain procurement share in bakery dry mixes where shelf stability extends distribution reach. Southern Ontario manufacturers prefer powder concentrates for cross-country logistics efficiency.
- Granular:Free-flowing crystals suit seasoning applications in industrial snack production requiring uniform dispersion.
- Paste:High-viscosity formulations anchor ethnic sauce and prepared meal segments in British Columbia and Alberta.
Liquid maintains volume leadership. Powder is climbing the fastest as dry mix manufacturers expand clean-label portfolios.
Application:
Regulatory pressure intensity varies by application, concentrating margin capture in segments facing the steepest reformulation mandates.
- Bakery:Clean-label transitions in bread, pastry, and cracker formulations drive natural vanilla and butter flavor procurement. Quebec artisan and industrial bakeries specify certified organic tiers to meet retail private-label standards.
- Snacks:Sodium reduction targets in savory extruded and fried products position umami enhancers as critical formulation inputs. Ontario and Alberta snack processors scale biotechnology-derived alternatives to maintain taste intensity.
- Dairy:Flavored milk, yogurt, and plant-protein alternatives require masking systems for off-notes in legume and mycoprotein bases.
- Beverage:Natural fruit and botanical extracts face procurement competition from precision fermentation alternatives.
Bakery commands reformulation investment. Snacks is gaining share fastest on clean-label savory demand.
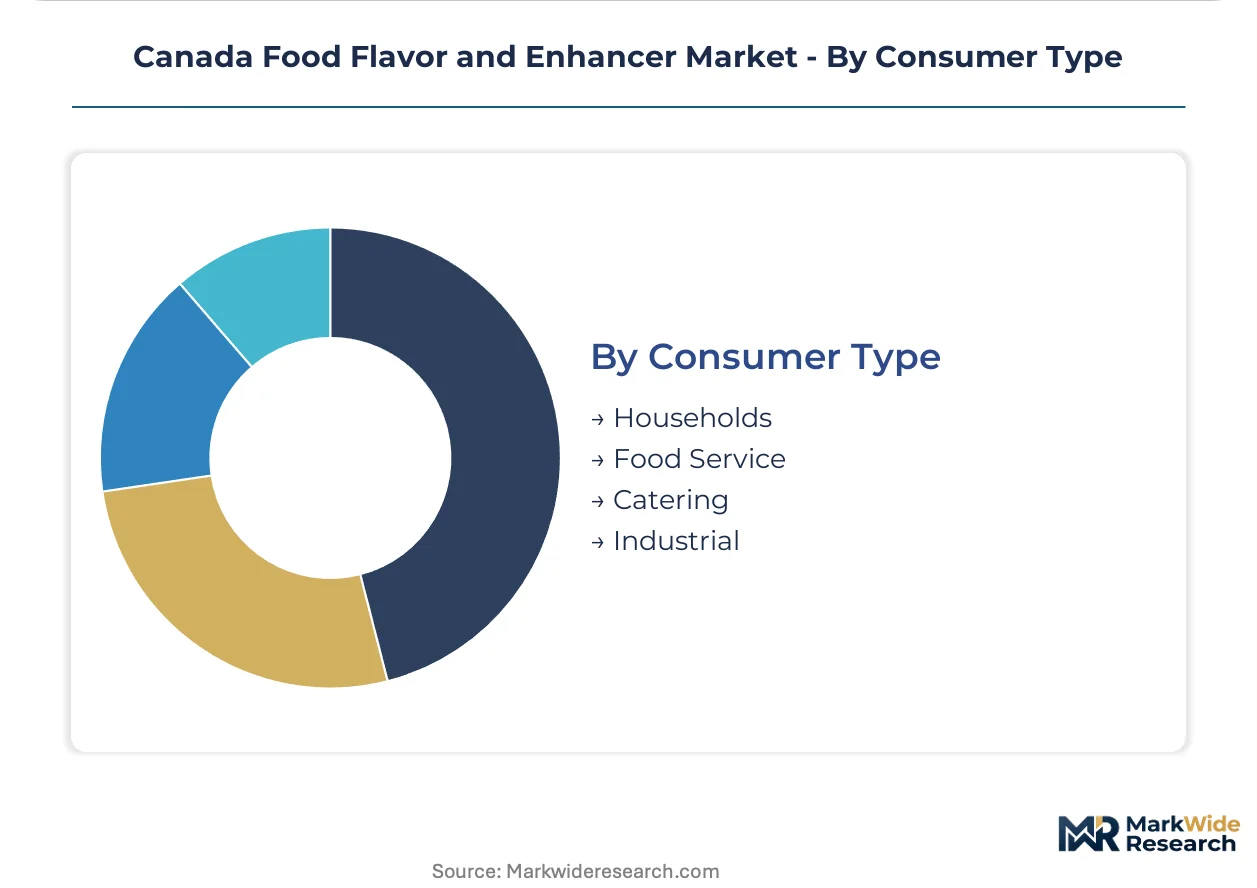
Consumer Type:
Procurement scale and technical service requirements separate industrial volumes from household and food service fragmentation.
- Industrial:Large-scale manufacturers across the Toronto-Montreal axis negotiate multi-year supply agreements for standardized flavor systems. These buyers demand batch certification, technical formulation support, and preventive control plan documentation under CFIA enforcement.
- Food Service:Chain restaurants and institutional kitchens specify concentrated bases and finished seasonings for menu consistency. British Columbia and Alberta operators prioritize direct-to-manufacturer digital procurement channels.
- Catering:Event and contract food service procures mid-volume blends with shorter lead time requirements.
- Households:Retail spice and seasoning purchases face private-label substitution and e-commerce platform competition.
Industrial locks in volume contracts. Food Service is expanding most quickly on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in southern Ontario extraction facilities for maple and botanical derivatives, with Quebec and Alberta processing corridors absorbing reformulation mandates. Health Canada regulations bind all provincial operations, though enforcement intensity varies by industrial density.
Ontario
Toronto-area dairies and snack manufacturers drive liquid flavor concentrate procurement for clean-label reformulations. Health Canada's Safe Food for Canadians Regulations enforcement accelerates preventive control plan adoption across the Golden Horseshoe. The Toronto-Montreal food service corridor anchors standardized flavor system demand for large-scale bakery operations.
Quebec
Artisan and industrial bakeries specify certified organic vanilla and butter flavor tiers for retail private-label compliance. CFIA verification protocols force mid-tier blenders toward third-party certification investments. Montreal processing facilities retrofit lines to eliminate artificial enhancers before regulatory deadlines.
Alberta
Meat alternative manufacturers require masking and enhancing systems for legume and mycoprotein bases in plant-protein formulations. Health Canada's novel food substance approval timelines determine which biotechnology-derived portfolios capture regional reformulation cycles. Edmonton and Calgary anchor emerging savory processing clusters for clean-label snack production.
British Columbia
Ethnic sauce and prepared meal segments in Vancouver specify paste-form flavor formulations for regional palate preferences. The province's food service operators prioritize direct-to-manufacturer digital procurement channels for formulation development. CFIA import verification protocols govern access for foreign suppliers serving Pacific distribution networks.
Canada Food Flavor and Enhancer Market Competitive Environment
Concentration sits with multinational ingredient networks and domestic specialists competing across certification tiers. The vendor base stratifies between global blenders with amortized compliance infrastructure and regional houses facing certification cost pressures. Two archetypes dominate: biotechnology platform operators and extraction-based natural specialists. Competitive moves center on fermentation capacity expansion and preventive control plan certification services.
Within the multinational tier, Kerry Group and Givaudan exemplify network-scale operators with North American supply security positioning. Aromatics+Flavors Inc. represents the domestic specialist archetype with concentrated R&D proximity to Toronto demand clusters. These three anchors illustrate the competitive tension between global platform breadth and regional formulation responsiveness.
| Leading Market Players |
|---|
| Kerry Group |
| Archer Daniels Midland Company |
| Givaudan |
| Flavorcan International Inc. |
| Takasago International Corporation |
| Firmenich |
| Koninklijke DSM N.V. |
| Aromatics+Flavors Inc. |
| International Flavors and Fragrances Inc. |
| Others |
Value Chain & Pricing Dynamics
Health Canada's Safe Food for Canadians Regulations gates both supplier qualification and price differentiation simultaneously, forcing processors to pay certification premiums for compliant flavor portfolios while squeezing non-certified competitors toward commodity pricing tiers.
Pricing Analysis
Safe Food for Canadians Regulations dictates the pricing tier structure across the Canada food flavor and enhancer market. Three-tier pricing structure across premium, standard, and economy levels separates CFIA-certified organic portfolios from conventional natural grades and synthetic alternatives. Pricing pressure stems from volatile vanilla and citrus extract harvests that compress margins in natural flavor tiers. Large-scale Toronto-Montreal corridor manufacturers exhibit lowest price sensitivity due to multi-year contract security, while mid-tier Quebec bakeries face acute cost compression.
Supply Chain Analysis
Southern Ontario extraction facilities for maple and botanical derivatives anchor supply concentration for domestic natural flavor inputs. The Canada food flavor and enhancer market draws from Madagascar and Indonesia for vanilla, India for spice oleoresins, and southern Ontario for maple derivatives. Single-source vulnerability concentrates in biotechnology-derived umami molecules awaiting Health Canada novel food approvals. Distribution runs through CFIA-verified blending facilities to industrial processors across the Toronto-Montreal corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large-scale manufacturers capable of certifying entire supply chains, fragmenting pricing leverage for smaller Ontario and Quebec processors.
For Market Incumbents: Fortify preventive control plan certification infrastructure to amortize compliance costs across volume tiers. Biotechnology platform operators should expand fermentation capacity in southern Ontario to capture clean-label reformulation cycles. Kerry Group and Givaudan network advantages threaten domestic specialists lacking amortized certification investments. For New Entrants and Emerging Players: Lead with plant-protein masking systems for Alberta and British Columbia meat alternative manufacturers, where Health Canada approval timelines create white space for approved-substance portfolios. Direct-to-manufacturer digital procurement channels offer lowest-friction entry for technical consultation services. CFIA certification expertise addresses capability gaps among mid-tier blenders seeking third-party verification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biotechnology-derived flavor platforms as precision fermentation scale-up demands specialized infrastructure. Long-term viability favors acquisition targets with existing Health Canada approved-substance lists and southern Ontario extraction proximity. The signal to monitor is Health Canada novel food substance approval velocity, which determines portfolio expansion timelines for savory enhancer categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extraction Facilities | Ontario-based maple and botanical captive supply secures clean-label input security against harvest volatility. |
| Precision Fermentation Capacity Expansion | Biotechnology-derived natural umami molecules compress cost structures for sodium reduction formulations. |
| CFIA Preventive Control Plan Certification | Third-party verification services generate adjacent revenue from mid-tier blenders facing compliance gaps. |
| Direct-to-Manufacturer Digital Platform Launch | E-commerce sample distribution reduces distributor reliance for Ontario processor formulation development. |
| Plant-Protein Regional Supply Partnership | Alberta and British Columbia masking system anchors anchor emerging meat alternative manufacturing clusters. |
Study Parameters
The analysis maps natural flavoring, synthetic flavoring, enhancers, and seasoning segments, each validated through flavor chemists, procurement leads at Toronto-Montreal corridor processors, CFIA compliance officers, and biotechnology platform R&D directors. Primary interview data triangulates against Health Canada Food and Drug Regulations filings, CFIA import verification records, Safe Food for Canadians Regulations enforcement bulletins, and southern Ontario extraction facility trade data. Bottom-up volume modeling and top-down value reconciliation cross-validate segment outputs.
Consistency checks against external benchmarks validated projections across the analysis window. The forecast framework models product type, form specification, application channel, and consumer procurement scale dimensions. CAGRs derive from segment-level volume trajectories adjusted for regulatory approval timelines and reformulation cycle frequencies. Biotechnology maturation curves and clean-label procurement elasticity inform savory enhancer and natural flavoring projections.
The analysis sits within stated boundaries; outcomes outside Health Canada regulatory modernization pace or biotechnology cost compression trajectories would require recalibration. Forecasts reflect assumptions regarding CFIA enforcement intensity and novel food substance approval velocity. Practitioners should keep alternative scenarios live as Health Canada Food and Drug Regulations amendments and climate-driven harvest variability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Lignans Market