
 South Korea Fat Replacers Market | 2026-2036
South Korea Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Fat Replacers Market Insights
Asset-light contract manufacturing and toll-processing arrangements are narrowing the capital barrier for mid-tier firms seeking fat replacer formulation capabilities. Cargill leverages its integrated starch and protein supply chains to sustain cost-competitive positions across emulsifier and protein-based replacer categories. Tate & Lyle anchors its presence through specialty carbohydrate expertise, while Kerry Group differentiates via flavor-fat interaction technologies that address sensory gaps in reduced-fat meat and dairy applications.
Fat replacers are functional food ingredients engineered to mimic the mouthfeel, texture, and satiety properties of conventional fats while delivering substantially lower caloric density, typically through carbohydrate-based microparticulate structures, protein-stabilized water-in-oil emulsions, or hydrocolloid gel networks. These formulations serve industrial food processors seeking to meet reduced-fat label claims without sacrificing product acceptability. The protein segment occupies premium positioning due to superior organoleptic performance in dairy analogs, whereas starch-based replacers dominate volume flows into bakery applications where cost thresholds remain tight. Emulsifier blends represent the fastest-advancing structural category, reflecting processor demand for multi-functional systems that simultaneously reduce fat and extend shelf stability in confectionery and meat products.
MFDS maintains stringent safety evaluations for novel fat replacer substances under its food additive approval framework, while KFDA-established nutrition labeling rules mandate verifiable fat reduction percentages for front-of-pack claims. The Ministry of Trade, Industry and Energy coordinates with MFDS on clean-label ingredient promotion through national food technology initiatives, channeling R&D subsidies toward domestically sourced protein and hydrocolloid alternatives. Stakeholders must monitor evolving enforcement patterns around reduced-fat claim substantiation and anticipate how MFDS alignment with Codex Alimentarius standards will reshape import qualification pathways for foreign-sourced replacer ingredients.
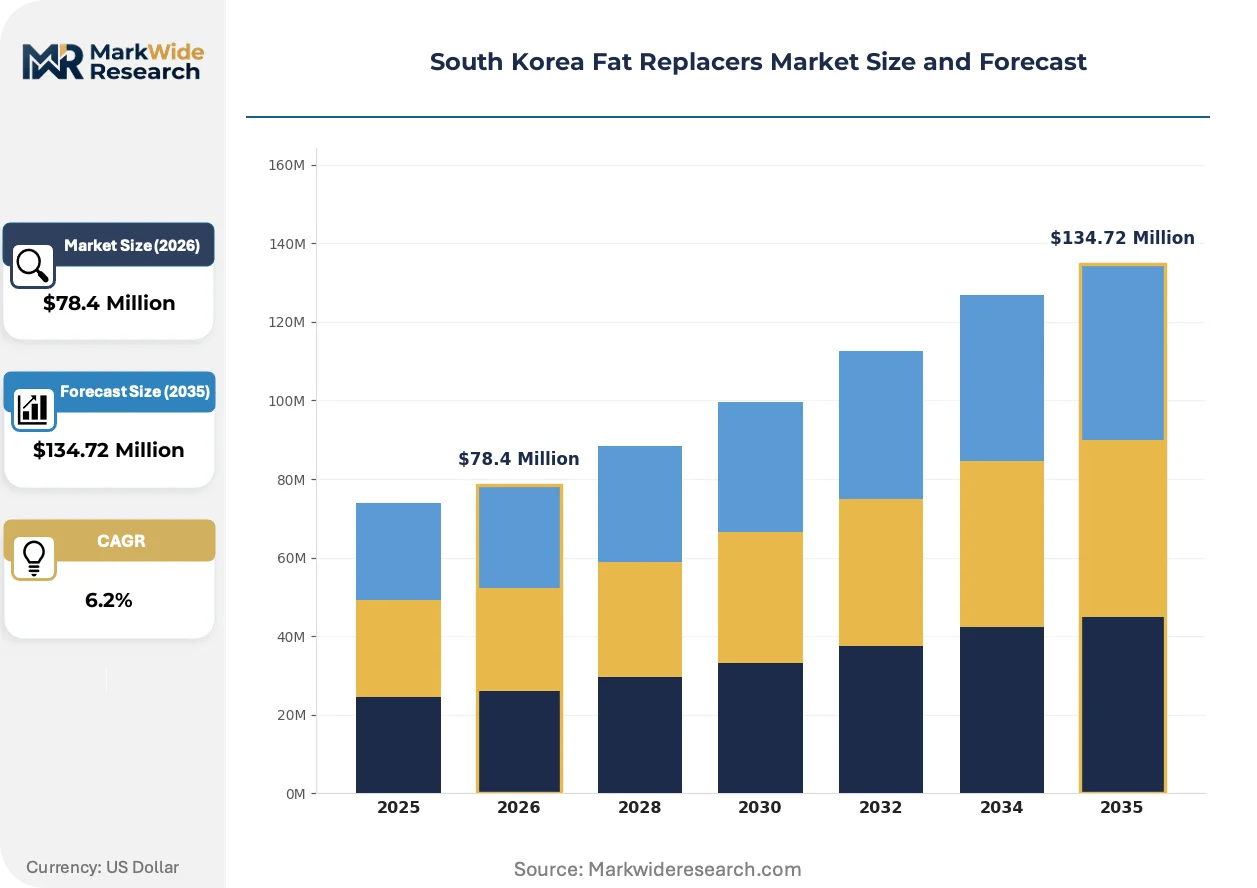
Market Dynamics
MFDS labeling standards for reduced-fat claims are compressing formulation timelines, forcing food processors to validate replacer performance against sensory benchmarks before front-of-pack authorization.
Growth Catalysts
- Clean-label ingredient approvals:MFDS accelerated pathways for domestically sourced protein and hydrocolloid alternatives channel R&D subsidies toward commercialization-ready formulations.
- Bakery sector reformulation:Starch-based replacers penetrate volume applications where cost thresholds remain tight and reduced-fat positioning drives retail placement.
- Seoul metropolitan cluster concentration:Food processing density in the capital region creates localized demand pull for technical service support and rapid sample turnaround.
Market Restraints
- Protein input cost volatility:Dairy and plant protein feedstock prices fluctuate with agricultural commodity cycles, compressing margin on premium-positioned replacer categories.
- Import qualification friction:MFDS alignment with Codex Alimentarius standards creates documentation burdens for foreign-sourced novel replacer substances seeking additive approval.
- Sensory-performance gap:Carbohydrate-based microparticulates fail to replicate fat-soluble flavor release in confectionery applications, limiting penetration.
Strategic Opportunities
- Gyeonggi-do manufacturing corridor expansion:Toll-processing capacity in this satellite region offers asset-light entry points for mid-tier firms seeking formulation capabilities.
- Emulsifier blend multi-functionality:Convergence of fat reduction and shelf-stability extension in meat products opens premium positioning for integrated structural systems.
- Flavor-fat interaction technologies:Sensory engineering that addresses mouthfeel deficits in reduced-fat dairy creates differentiation against commodity starch alternatives.
Industry Challenges
- Reduced-fat claim substantiation timelines:MFDS verification protocols for front-of-pack percentages extend product development cycles and delay market entry.
- Equipment retrofit requirements:Hydrocolloid gel network processing demands shear and temperature controls that legacy bakery lines lack, forcing capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Fat Replacers Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Starches, Gums, Proteins Application: Bakery, Dairy Products, Confectionery, Meat Products End User: Food Manufacturers, Restaurants, Retailers, Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ingredion Incorporated, CP Kelco, Cargill, Ashland Global Holdings, DKS Co. Ltd., Archer Daniels Midland Company, Tate & Lyle, FMC Corporation, Kerry Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Fat Replacers Market Trends and Innovations
Formulation science is pivoting toward integrated structural systems that combine multiple fat-mimicking mechanisms in single-ingredient platforms, collapsing the trade-off between cost and sensory fidelity.
Protein-stabilized water-in-oil emulsion technology is migrating from dairy analog specialists into meat and confectionery applications. Mid-tier processors in Gyeonggi-do are piloting these systems at commercial scale. The shift is compressing demand for standalone emulsifier additives that lack integrated protein scaffolding.
MFDS nutrition labeling rules now mandate verifiable fat reduction percentages for reduced-fat claims, creating compliance documentation requirements that favor suppliers with established analytical capabilities. Industrial buyers are consolidating vendor relationships to reduce qualification overhead. Bakery and dairy processors with existing MFDS dossiers capture disproportionate placement in reformulation programs.
Buyer concentration among Seoul-based food manufacturers is compressing switching cycles for replacer suppliers. Technical service responsiveness and rapid prototype turnaround now outweigh price in vendor selection. This pattern concentrates contract volumes with suppliers maintaining localized application laboratories in the metropolitan cluster.
South Korea Fat Replacers Market Segmentation
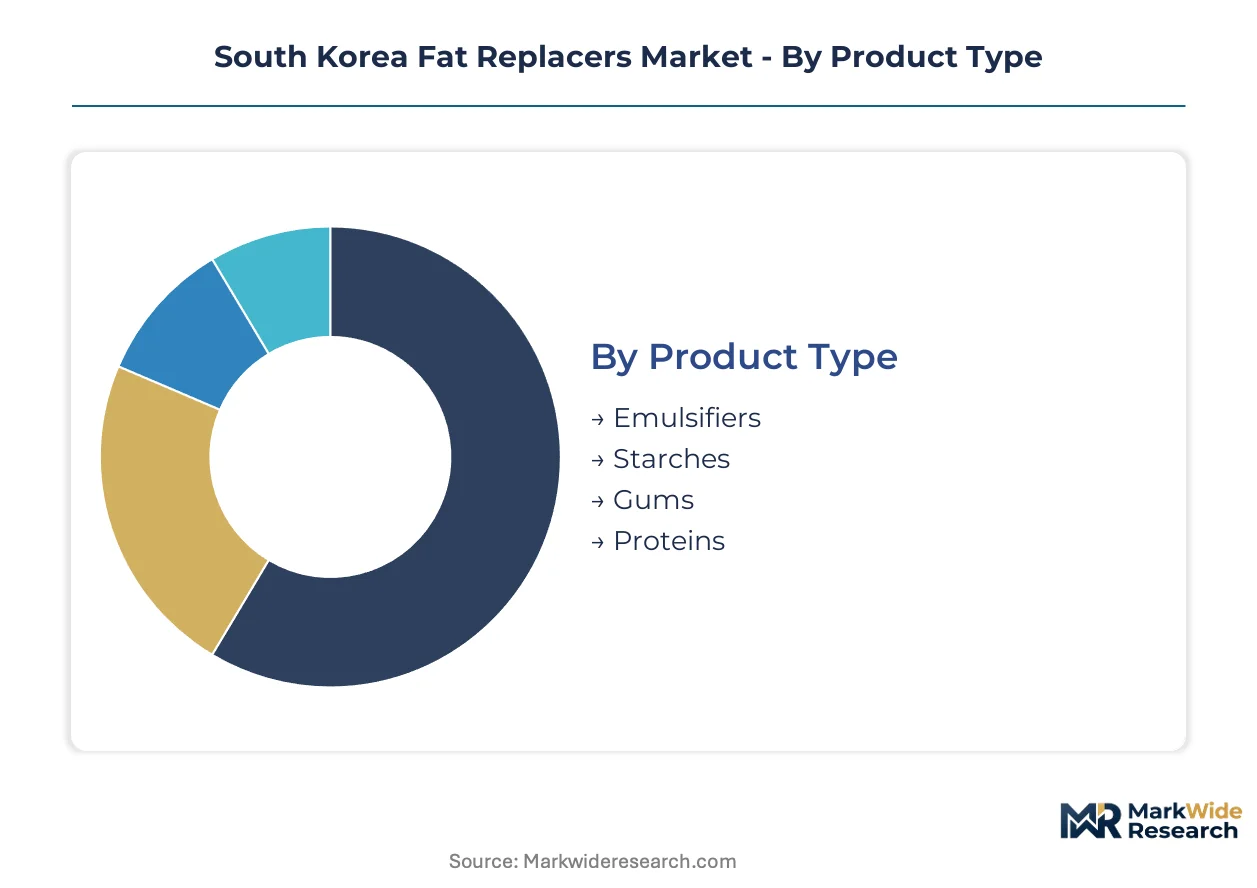
Segmentation in the South Korea fat replacers market reflects divergent technical service requirements across ingredient categories. After-sales support intensity varies sharply between protein-based systems demanding sensory troubleshooting and commodity starch replacers with minimal ongoing engagement.
Product Type:
After-sales-service intensity peaks with protein-based replacers requiring flavor-fat interaction optimization, while starch and gum categories operate on transactional supply models with limited technical overlay.
- Proteins:These formulations leverage dairy and plant-derived proteins to stabilize water-in-oil emulsions that replicate fat mouthfeel. Demand concentrates in Seoul's dairy processing cluster where MFDS clean-label approvals for domestically sourced alternatives accelerate reformulation timelines. Premium positioning reflects superior organoleptic performance in reduced-fat cheese and yogurt applications.
- Starches:Carbohydrate-based microparticulate structures dominate volume flows into cost-sensitive bakery applications. Gyeonggi-do manufacturing corridors absorb the majority of shipments, driven by tight cost thresholds in bread and pastry reformulation programs where reduced-fat claims drive retail placement.
- Emulsifiers:Multi-functional blends integrate fat reduction with shelf-stability extension in meat and confectionery processing.
- Gums:Hydrocolloid gel networks provide texture modulation in sauces and dressings with specialized shear-processing requirements.
Starches hold the largest share; momentum sits with proteins.
Application:
Application segmentation tracks divergent cost-performance trade-offs across food processing verticals, with dairy and meat commanding premium ingredient specifications versus commodity positioning in bakery.
- Bakery:Volume leadership in bread, cakes, and pastries reformulation where starch-based replacers meet aggressive cost targets. Seoul metropolitan processors drive demand for rapid sample turnaround on reduced-fat line extensions.
- Dairy Products:Cheese, yogurt, and ice cream applications require protein-stabilized emulsions that address sensory gaps in flavor release and mouthfeel continuity. MFDS labeling verification for reduced-fat claims extends development cycles in this premium tier.
- Meat Products:Sausage and processed meat reformulation leverages emulsifier blends for simultaneous fat reduction and shelf-life extension.
- Confectionery:Chocolate and candy applications face persistent technical barriers as carbohydrate microparticulates fail to replicate fat-soluble flavor delivery.
Bakery captures the greatest volume; dairy commands the steepest expansion trajectory.
End User:
End user segmentation reveals procurement concentration among industrial food manufacturers versus fragmented demand from foodservice and retail channels with limited formulation capabilities.
- Food Manufacturers:Industrial processors in Seoul and Gyeonggi-do drive consolidated demand for technical service-intensive replacer systems. These buyers validate performance against MFDS sensory benchmarks before front-of-pack authorization.
- Restaurants:Foodservice operators show nascent interest in reduced-fat menu items but lack in-house reformulation expertise.
- Retailers:Private-label development teams at major chains represent emerging demand for turnkey reduced-fat product lines.
- Consumers:Direct purchases remain minimal, confined to specialty health-food channels with limited market penetration.
Food manufacturers dominate current procurement; retailer private-label activity is expanding most quickly.
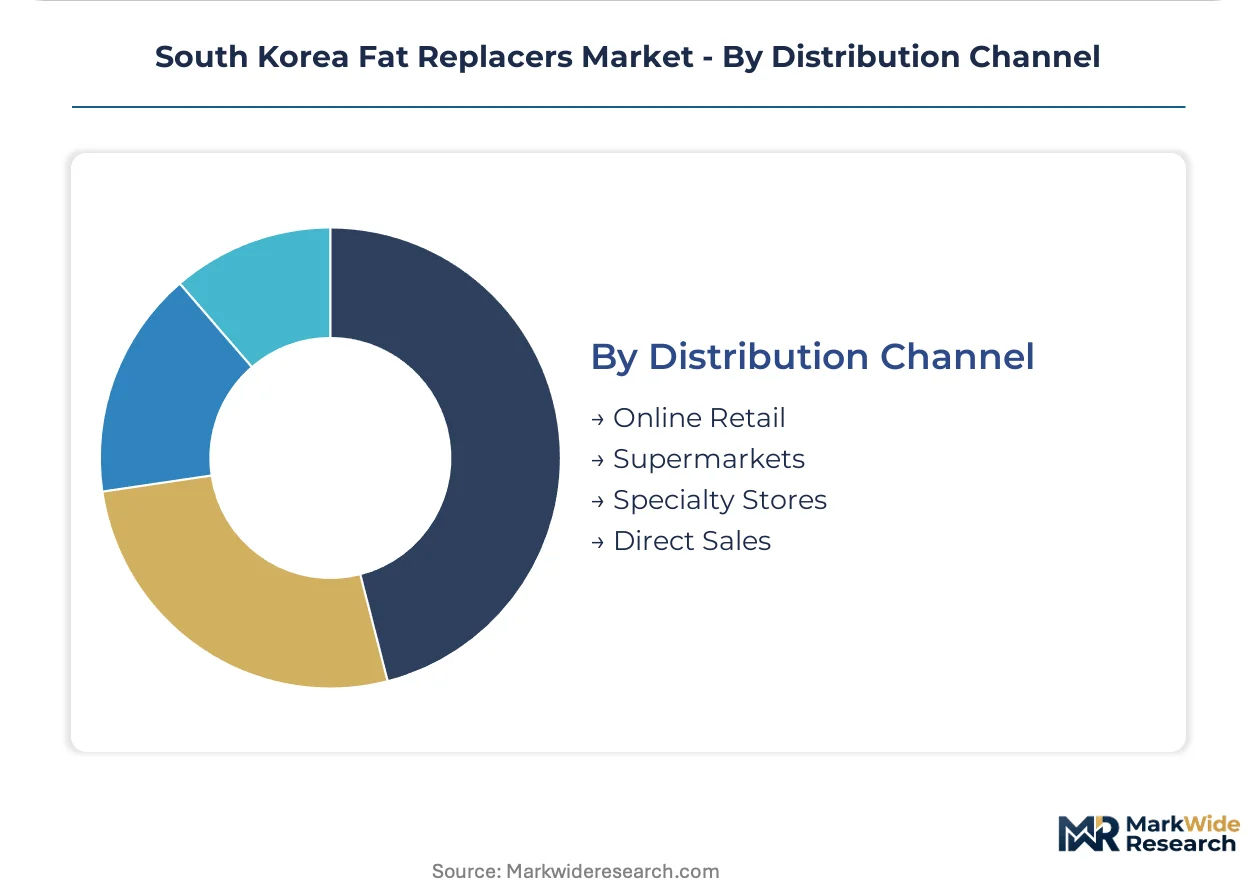
Distribution Channel:
Channel segmentation reflects the technical complexity of fat replacer procurement, with direct sales and specialty stores handling specification-intensive transactions versus commodity flows through mass retail.
- Direct Sales:Technical sales teams manage long-cycle relationships with Seoul-based food manufacturers requiring application laboratory support and MFDS dossier preparation. This channel captures premium protein and emulsifier volumes.
- Specialty Stores:Ingredient distributors serving mid-tier Gyeonggi-do processors offer localized inventory and rapid sample fulfillment for starch and gum categories.
- Supermarkets:Mass retail channels handle limited consumer-facing reduced-fat ingredient SKUs with minimal technical overlay.
- Online Retail:Digital procurement remains marginal, constrained by the need for sensory validation before commercial scale-up.
Direct sales anchors the channel mix; specialty stores are gaining share fastest among mid-tier processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial food manufacturers in Seoul and Gyeonggi-do drive procurement concentration for fat replacer systems, with MFDS labeling compliance shaping vendor selection across South Korea's processing corridors.
Seoul Capital Area
Dairy and bakery processors in Seoul's metropolitan cluster demand rapid technical service turnaround for reduced-fat reformulation programs. MFDS clean-label approval pathways accelerate domestic protein and hydrocolloid sourcing decisions. Application laboratories in Gangnam and Yeongdeungpo districts anchor supplier relationships for sensory validation before front-of-pack authorization.
Gyeonggi-do Manufacturing Corridor
Mid-tier food manufacturers in Suwon and Ansan leverage toll-processing arrangements to access fat replacer formulation capabilities without capital deployment. The Ministry of Trade, Industry and Energy channels R&D subsidies toward domestically sourced alternatives in this satellite region. Starch-based replacer volumes concentrate in bread and pastry lines where cost thresholds remain tight.
Busan-Ulsan Industrial Zone
Processed meat and seafood reformulation drives emulsifier blend demand in Korea's southeastern manufacturing hub. Ulsan's petrochemical infrastructure supports hydrocolloid derivative production for regional food processors. Local sausage and surimi manufacturers pilot multi-functional systems that simultaneously reduce fat and extend shelf stability.
Daegu-Gyeongbuk Region
Traditional confectionery producers in Daegu face persistent technical barriers as carbohydrate microparticulates fail to replicate fat-soluble flavor delivery. MFDS additive approval documentation burdens constrain import qualification for novel replacer substances. Regional processors rely on established starch and gum suppliers with existing regulatory dossiers.
Daejeon-Sejong Administrative Belt
Government research institutes in Daejeon coordinate national food technology initiatives under Ministry of Trade, Industry and Energy programs. Sejong-based policy formulation shapes clean-label ingredient promotion and import qualification pathways. Pilot facilities in this corridor validate domestically sourced protein alternatives before commercial scale-up.
South Korea Fat Replacers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Korea's fat replacer procurement landscape. Integrated ingredient conglomerates leverage starch and protein supply chain control to capture volume flows into bakery and dairy applications. Three archetypes dominate: multinational nutrition ingredient suppliers with localized technical service infrastructure, domestic distributors serving mid-tier processors with rapid sample fulfillment, and specialty hydrocolloid formulators addressing niche texture-modulation requirements. Competitive moves center on portfolio diversification into multi-functional emulsifier blends and backward integration into domestic protein sourcing.
Within the multinational supplier tier, Cargill, Tate & Lyle, and Kerry Group exemplify divergent positioning strategies. Cargill occupies a position anchored by integrated carbohydrate and protein supply chains. Tate & Lyle represents specialty carbohydrate expertise concentrated in technical formulation support. Kerry Group sits within the sensory-engineering archetype, addressing flavor-fat interaction gaps that commodity alternatives fail to resolve.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| CP Kelco |
| Cargill |
| Ashland Global Holdings |
| DKS Co. Ltd. |
| Archer Daniels Midland Company |
| Tate & Lyle |
| FMC Corporation |
| Kerry Group |
| Others |
Pricing and Supply Chain Analysis
Incheon Port container freight corridors transmit agricultural commodity volatility directly into protein-based replacer cost structures, amplifying margin compression for Seoul dairy processors while starch-based alternatives in Gyeonggi-do maintain tighter cost bands through domestic sourcing.
Pricing Analysis
Cost-plus contracts indexed to dairy and plant protein commodity benchmarks dominate protein-based replacer procurement, with MFDS clean-label certification tiers creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on sensory validation documentation and domestic sourcing quotas. Pricing pressure intensifies in bakery starch categories as toll-processing capacity expansion in Gyeonggi-do compresses formulation service margins. Food manufacturers in Seoul's metropolitan cluster show lowest price sensitivity for protein systems requiring technical service overlay, while mid-tier processors prioritize cost-per-kilogram metrics.
Supply Chain Analysis
Export-control documentation burdens under MFDS alignment with Codex Alimentarius standards constrain novel hydrocolloid flows from European and North American specialty suppliers, forcing Korean processors toward established Asian sources. Raw material dependencies center on tapioca starch from Southeast Asia, whey protein concentrates from Oceania, and seaweed-derived hydrocolloids from domestic Jeonnam cultivation. Single-source vulnerability concentrates in protein feedstocks tethered to agricultural commodity cycles. Distribution runs through direct technical sales for premium protein and emulsifier categories, with specialty distributors handling starch and gum volumes for mid-tier Gyeonggi-do manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as MFDS labeling verification requirements splinter procurement relationships and favor suppliers with localized analytical capabilities.
For Market Incumbents: Pre-empt margin erosion in commodity starch categories by securing captive supply of domestic Jeonnam hydrocolloid sources and embedding application laboratories within Seoul's Yeongdeungpo processing cluster. Accelerate certification investment for multi-functional emulsifier blends before MFDS tightens additive approval pathways for foreign-sourced alternatives. For New Entrants and Emerging Players: Establish a beachhead in Gyeonggi-do toll-processing partnerships where asset-light arrangements bypass capital barriers for mid-tier bakery reformulation programs. Target private-label development teams at major retail chains seeking turnkey reduced-fat dairy lines, leveraging rapid sample turnaround as the primary go-to-market wedge against established technical service infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from domestic ingredient distributors with existing MFDS dossiers and established relationships across Seoul's metropolitan food processing cluster. Long-term viability favors suppliers with backward integration into protein sourcing and sensory engineering capabilities. Watch for inflection signals in MFDS enforcement patterns around reduced-fat claim substantiation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Protein Sourcing | Captive supply of Jeonnam plant proteins reduces exposure to Oceania dairy commodity cycles and accelerates MFDS clean-label approval timelines. |
| Application Laboratory Expansion in Seoul Cluster | Localized sensory validation capabilities compress prototype turnaround cycles and anchor vendor relationships with dairy processors. |
| Multi-Functional Emulsifier Blend Development | Integrated fat reduction and shelf-stability systems command premium positioning in meat processing applications. |
| Toll-Processing Partnership Arrangements | Asset-light capacity access in Gyeonggi-do enables mid-tier bakery processors to enter reduced-fat reformulation without capital deployment. |
| MFDS Dossier Preparation Investment | Established additive approval documentation reduces qualification friction for foreign-sourced novel replacer substances. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MFDS food additive approval registers, Ministry of Trade industry subsidy disclosures, and customs trade data for hydrocolloid and protein feedstock imports. Interviews with food formulation technologists at Seoul-based dairy processors, procurement leads at Gyeonggi-do bakery manufacturers, and regulatory affairs specialists navigating MFDS labeling verification informed demand-side dynamics. Secondary validation drew from KFDA nutrition labeling guidelines, Codex Alimentarius standards documentation, and national food technology initiative reports. Bottom-up segmentation modeling triangulated against top-down market sizing from industrial production statistics.
Forecast inputs span protein type, application vertical, and end-user procurement concentration across the projection horizon. CAGRs were derived from elasticity modeling against agricultural commodity price indices and regulatory approval velocity assumptions. Segmentation dimensions include product category, processing application, buyer archetype, and geographic cluster density. Industry-specific inputs incorporate MFDS clean-label approval pipeline timelines and toll-processing capacity expansion rates in Gyeonggi-do satellite regions.
Stress conditions across protein feedstock price volatility, MFDS enforcement stringency, and import qualification documentation burdens were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory alignment trajectories and domestic sourcing subsidy continuity. Material shifts in MFDS adoption of Codex Alimentarius standards or Jeonnam hydrocolloid harvest yields would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Flour Conditioner Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Europe Water Enhancer Market