
 Fortified Salts Market | 2026-2036
Fortified Salts Market Size, Share, and Industry Trends Forecast 2026-2036
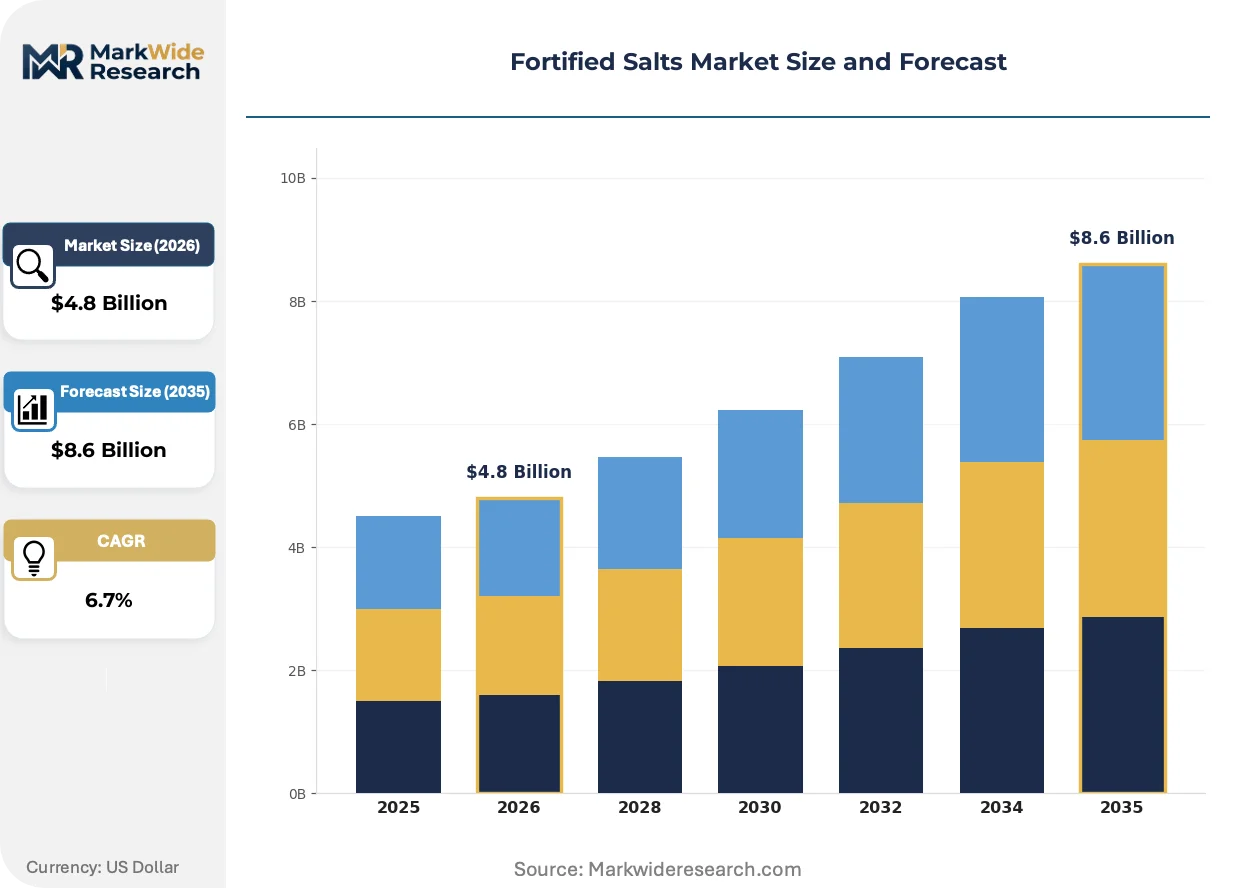
Fortified Salts Market Analysis
Microencapsulation of iodine and iron precursors is fragmenting traditional production methods across the fortified salts value chain. Tata Chemicals Limited leverages its integrated soda ash and salt operations to control input costs across Indian and East African markets. AkzoNobel sustains technical leadership through specialized brine processing capabilities in European coastal facilities. Cargill competes via its global agricultural logistics network, extending bulk salt distribution into Central American food manufacturing corridors.
Fortified salts are sodium chloride products enhanced with micronutrients—typically potassium iodate at 15–40 ppm iodine or ferrous sulfate at 1–2 mg iron per gram—through post-harvest spraying or premix homogenization during refining, serving primarily to prevent iodine deficiency disorders and anemia in populations with limited dietary diversity. Iodized salt dominates volume globally due to decades of universal salt iodization programs, while iron-fortified salt represents the fastest-expanding segment as anemia reduction initiatives intensify across South Asia and sub-Saharan Africa. The food industry end-user category anchors premium pricing, where pharmaceutical-grade specifications and batch certification command margin pools unavailable in commodity household channels.
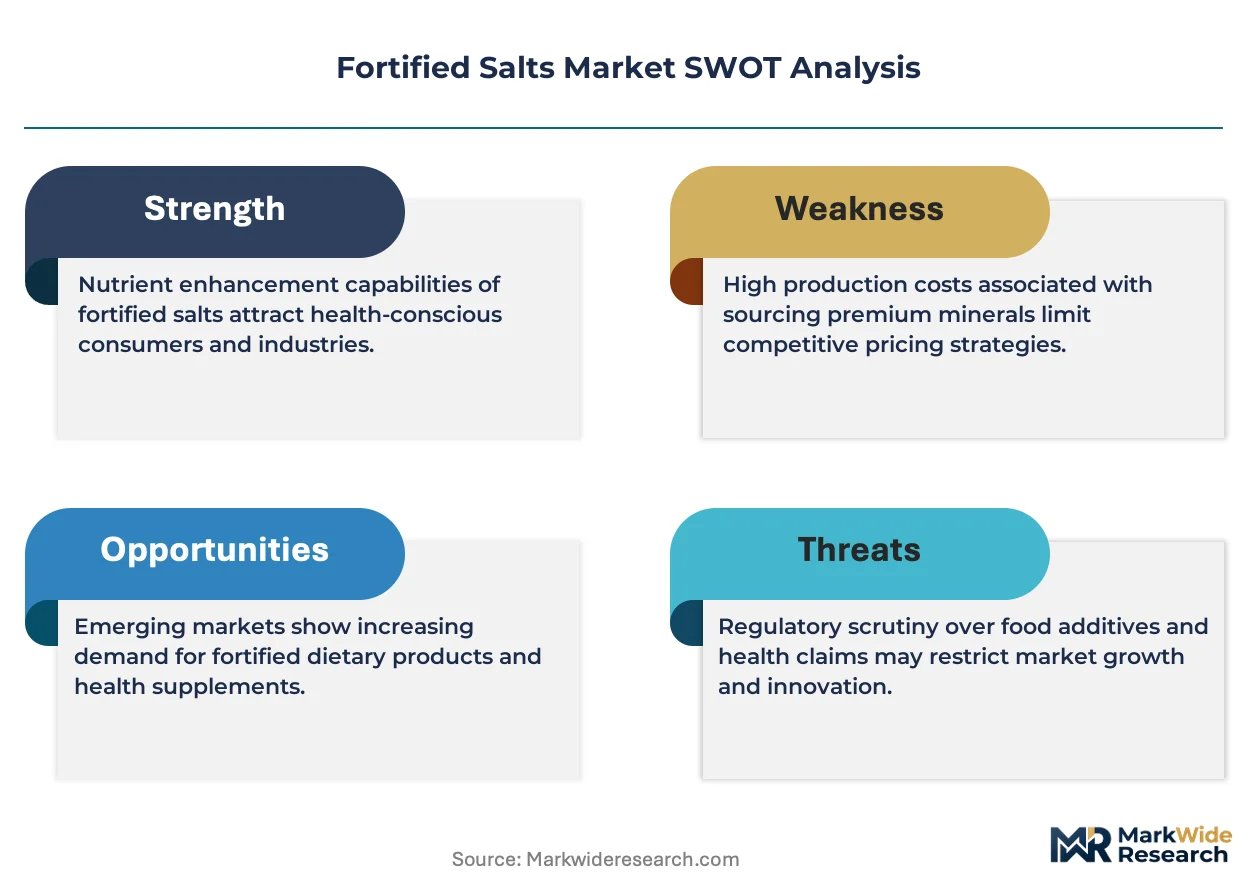
The FSSAI in India enforces mandatory iodization standards and pilot iron fortification protocols, directly shaping product composition requirements for domestic manufacturers. WHO guidelines on universal salt iodization and CODEX Alimentarius specifications for food-grade mineral fortificants establish the international compliance baseline that exporters must satisfy for market access. Stakeholders must monitor evolving micronutrient premix sourcing strategies and regional fortification mandate expansions to align capacity investments with shifting procurement specifications.
Market Dynamics
Microencapsulation technology is collapsing traditional spraying-based fortification economics, forcing producers to retool refining lines or cede margin to premix suppliers with proprietary coating IP.
Growth Catalysts
- FSSAI Mandates:India's mandatory iodization and pilot iron fortification programs create guaranteed offtake volumes for domestic refiners supplying government distribution channels.
- Processed Food Procurement:Industrial buyers in snack and ready-meal manufacturing are specifying certified premix inputs to meet retail chain nutritional labeling requirements.
- East African Distribution Networks:Kenya and Tanzania are expanding school feeding programs that specify iodized salt in commodity tenders, pulling volume through regional bulk procurement.
Market Restraints
- Potassium Iodate Price Volatility:The chemical precursor for iodization faces supply concentration among Chinese specialty chemical producers, exposing margin compression during input spikes.
- Premix Supplier Concentration:Three European and Indian compounders control microencapsulation IP for iron fortification, creating licensing bottlenecks for new market entrants.
- Shelf-Stability Limitations:Ferrous sulfate degradation in humid climates restricts iron-fortified salt distribution to cold-chain or rapid-turnover retail in tropical markets.
Strategic Opportunities
- Sub-Saharan Africa Expansion:Nigeria and Ethiopia lack universal fortification mandates but show rising anemia intervention funding from development finance institutions.
- Double-Fortification Formats:Converging iodine-iron-zinc premix technologies enable single-product positioning against multiple deficiency programs.
- E-commerce Direct Channels:Urban Indian households are purchasing specialty low-sodium fortified variants through platform subscriptions, bypassing traditional kirana store distribution.
Industry Challenges
- Brine Chemistry Expertise Gap:Refiners lack in-house capability to validate micronutrient homogeneity at 15-40 ppm dosing precision, requiring external laboratory partnerships that extend batch release timelines.
- Dual Certification Complexity:Exporters must simultaneously satisfy FSSAI domestic standards and CODEX Alimentarius specifications, creating documentation friction for multi-market producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Salts Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iodized Salt, Iron-fortified Salt, Fluoride Salt, Others End User: Households, Food Industry, Pharmaceuticals, Nutritional Supplements Distribution Channel: Supermarkets, Grocery Stores, Online Retail, Wholesale Form: Granular, Powdered, Liquid, Block |
| Companies Covered | Tata Chemicals Limited, AkzoNobel, Cargill, Compass Minerals International, China National Salt Industry Corporation, United Salt Corporation, Kutch Brine Chem Industries, Ankur Salt, Sambhar Salts Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Salts Market Emerging Trajectories
Active reformulation of fortification delivery systems is compressing cost structures while expanding the addressable population base beyond legacy universal salt iodization programs.
Fluidized bed microencapsulation is collapsing the cost gap between commodity iodized salt and premium iron-fortified variants. Food manufacturers in India and Brazil are adopting this technology to meet retail chain nutritional specifications without reformulating finished products. The process enables iron loading at 1-2 mg per gram with 18-month stability, eliminating the humidity-driven degradation that previously restricted tropical distribution.
WHO guidelines on universal salt iodization are tightening analytical validation requirements for national programs. Exporters to African and South Asian markets must now demonstrate spectrophotometric batch certification rather than paper-based compliance declarations. Indian refiners supplying East African tenders are investing in in-house atomic absorption capacity to preempt third-party testing delays.
Urban household purchasing is fragmenting toward specialty low-sodium fortified variants through quick-commerce platforms. Traditional kirana stores in Mumbai and Delhi are losing share to 10-minute delivery apps that aggregate multiple micronutrient formats. This channel shift is pulling premium pricing for certified pharmaceutical-grade specifications that command margin pools unavailable in commodity household channels.
Fortified Salts Market Segmentation
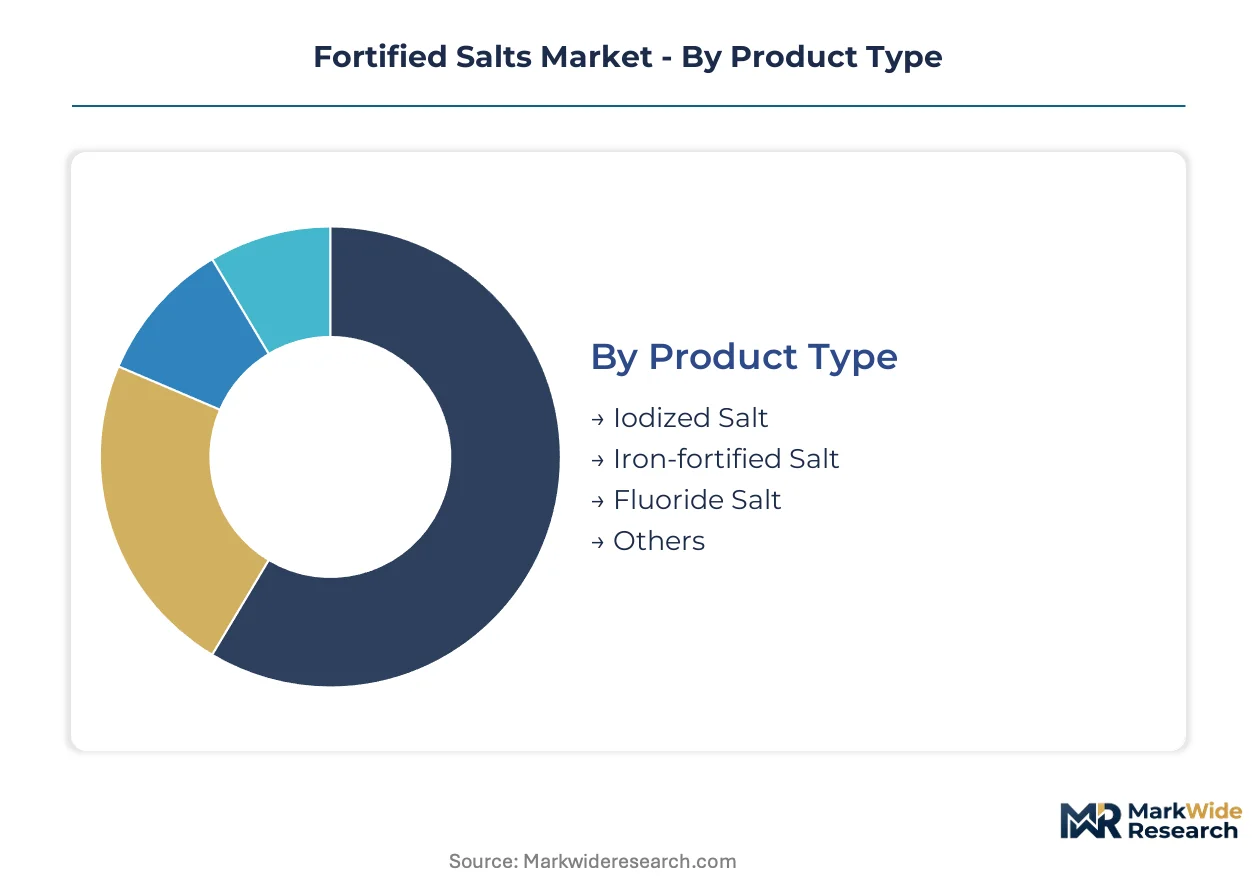
Fortified salt producers must align capacity configurations against four distinct segmentation axes. Product chemistry determines regulatory compliance pathways. End-user specifications separate commodity household volumes from certified industrial premix requirements.
Product Type:
Cost tier stratification separates legacy fortification formats from emerging multi-nutrient formulations.
- Iodized Salt:Sodium chloride fortified with potassium iodate at 15-40 ppm concentration through post-harvest spraying or dry mixing. Government distribution programs in India and East African school feeding tenders anchor volume demand, though margin compression intensifies as procurement centralizes.
- Iron-fortified Salt:Ferrous sulfate or microencapsulated iron premix integrated at 1-2 mg per gram during refining. FSSAI pilot programs and anemia reduction initiatives across South Asia are accelerating specification adoption, with fluidized bed coating technologies now enabling 18-month tropical stability.
- Fluoride Salt:Sodium fluoride or fluorosilicic acid doping for dental caries prevention in endemic regions.
- Others:Zinc-fortified and multi-micronutrient variants targeting specific deficiency profiles.
Iodized salt commands the established base. The steepest expansion runs through iron-fortified salt.
End User:
Application requirements fragment between mass-market distribution and precision-certified industrial supply.
- Food Industry:Processed food manufacturers specify pharmaceutical-grade premix inputs with batch spectrophotometric certification to meet retail chain nutritional labeling requirements. Snack and ready-meal producers in India and Brazil are driving specification upgrades.
- Households:Urban Indian consumers through quick-commerce platforms are shifting toward specialty low-sodium fortified variants, bypassing traditional kirana distribution.
- Pharmaceuticals:Compounding pharmacies and tablet manufacturers require USP-grade mineral inputs with validated homogeneity documentation.
- Nutritional Supplements:Sports nutrition and clinical nutrition formulators source concentrated premixes for capsule and powder blending.
Household channels command the established base. The steepest expansion runs through food industry procurement.
Distribution Channel:
Customer type determines margin capture and certification complexity across channel tiers.
- Online Retail:Quick-commerce platforms in Mumbai and Delhi aggregate multiple micronutrient formats with 10-minute delivery promises, extracting premium pricing for certified specifications unavailable in commodity channels.
- Supermarkets:Organized retail chains in urban India enforce nutritional labeling transparency, pushing suppliers toward documented premix sourcing.
- Grocery Stores:Traditional kirana networks remain dominant in rural penetration but are losing urban share to platform-based distribution.
- Wholesale:Bulk procurement for government distribution programs and institutional feeding operates on tender-based volume pricing with FSSAI compliance mandates.
Grocery stores command the established base. The steepest expansion runs through online retail.
Form:
Volume scale and handling requirements separate industrial processing inputs from consumer-ready packaging formats.
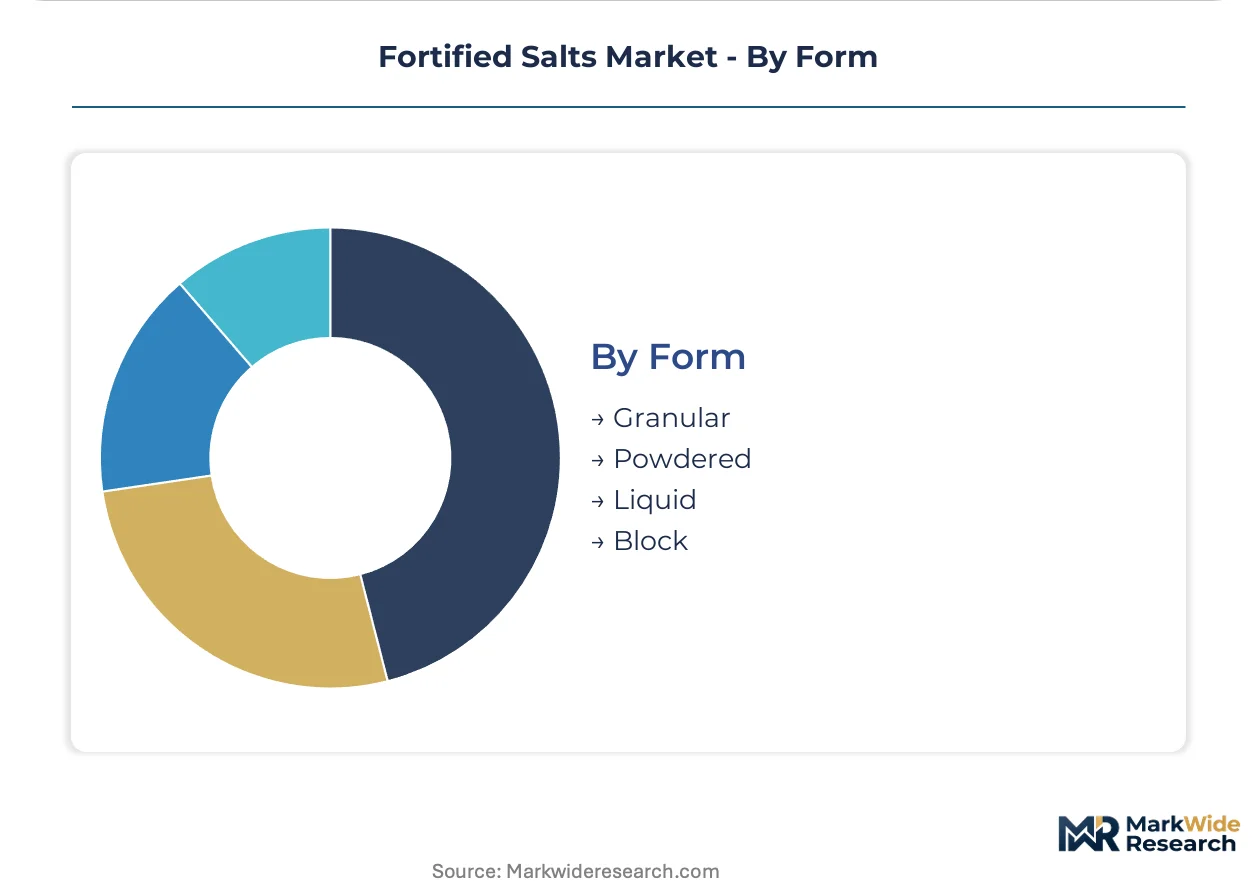
- Granular:Crystalline sodium chloride with uniform particle size distribution enables consistent fortificant adhesion during spraying and homogenization. Food manufacturers in Brazil and India specify granular inputs for direct production line integration.
- Powdered:Fine-milled salt for rapid dissolution in processed food matrices and pharmaceutical compounding.
- Liquid:Brine-based fortification concentrates for industrial-scale continuous processing.
- Block:Compressed salt licks for livestock nutritional supplementation in agricultural applications.
Granular formats command the established base. The steepest expansion runs through powdered formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Indian refiners to East African procurement programs are tightening regional supply-demand balances, while Chinese potassium iodate concentration shapes input cost structures across South Asian production networks.
India
FSSAI mandates on mandatory iodization and pilot iron fortification anchor government distribution volumes. The regulator's technical specifications for 15-40 ppm iodine dosing create compliance thresholds for domestic refiners. Gujarat's Kutch salt belt concentrates production capacity where Tata Chemicals and regional processors operate integrated refining operations.
Kenya
School feeding program tenders specifying iodized salt are pulling bulk procurement through Nairobi-based distribution hubs. The national standards bureau enforces WHO-aligned iodization protocols for imported consignments. Mombasa port logistics clusters handle regional transshipment into Tanzania and Uganda.
Brazil
Processed food manufacturers in São Paulo state are adopting microencapsulated iron premix specifications to meet retail chain nutritional labeling requirements. ANVISA governs food-grade mineral additive approvals for domestic formulation. The Campinas industrial corridor houses snack and ready-meal production facilities driving specification upgrades.
China
Potassium iodate and ferrous sulfate precursor production concentrates among specialty chemical producers in Jiangsu and Shandong provinces. SAMR oversees food-grade mineral fortificant standards under GB specifications. Tianjin port clusters manage bulk chemical export logistics to South Asian salt refiners.
Nigeria
Rising anemia intervention funding from development finance institutions is creating pilot procurement opportunities without universal fortification mandates. The national food and drug regulator evaluates premix import registrations on a program-by-program basis. Lagos-based distributors are testing iron-fortified salt channels through urban retail networks.
Fortified Salts Market Vendor Landscape
On the supply side, the industry is bifurcating between integrated chemical conglomerates with captive raw material positions and specialized salt refiners dependent on third-party premix sourcing. Tier-one players control integrated soda ash-to-salt value chains, while mid-scale operators concentrate on regional distribution efficiency. Two strategic archetypes dominate: backward-integrated chemical producers and logistics-anchored agricultural commodity traders. Capacity expansion in microencapsulation capabilities and strategic premix licensing agreements constitute the primary competitive moves reshaping positioning.
Among integrated chemical producers, Tata Chemicals Limited exemplifies the backward-integrated archetype through its captive soda ash and salt operations spanning Indian and East African markets. AkzoNobel occupies a position within the specialized brine processing tier, with European coastal facilities anchoring technical leadership in refined salt production. Cargill represents the agricultural commodity trader archetype, leveraging global logistics networks to extend bulk salt distribution into Central American food manufacturing corridors.
| Leading Market Players |
|---|
| Tata Chemicals Limited |
| AkzoNobel |
| Cargill |
| Compass Minerals International |
| China National Salt Industry Corporation |
| United Salt Corporation |
| Kutch Brine Chem Industries |
| Ankur Salt |
| Sambhar Salts Limited |
| Others |
Supply Flow & Price Mechanics
Potassium iodate production concentration in Jiangsu and Shandong provinces feeds directly into margin capture by Chinese specialty chemical suppliers, while downstream salt refiners in India and East Africa face compressed premix conversion economics. The input cost pass-through mechanism favors integrated producers with captive soda ash operations over standalone refiners dependent on third-party sourcing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across food manufacturing corridors in Brazil and India. Three-tier pricing structure across pharmaceutical-grade, food-grade, and commodity household levels separates batch-certified premix inputs from unverified bulk supply. Cost compression in commodity iodized salt is intensifying because procurement centralization in government distribution programs erodes supplier leverage. Household channels through quick-commerce platforms show the least price sensitivity, while bulk tender participants in East African school feeding programs face the most.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for potassium iodate and ferrous sulfate precursor flows. Manufacturing concentrates in China for chemical precursors, India for integrated salt refining, and Kenya for regional East African distribution. Raw material dependencies rest on potassium iodate, microencapsulated iron premix, and specialized brine processing chemicals. Single-source vulnerability in European microencapsulation IP holders creates licensing bottlenecks for iron fortification expansion. Distribution runs through Mombasa and Mumbai port clusters into government tender channels and quick-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified premix technical services and spectrophotometric batch validation are expanding faster than commodity salt production, creating attach-rate opportunities for laboratory partnerships and compliance documentation layers.
For Market Incumbents: Harden microencapsulation capabilities through proprietary fluidized bed licensing or exclusive premix supplier partnerships to defend against new entrants lacking coating IP. Secure backward integration into potassium iodate sourcing or locked-in offtake agreements with Jiangsu producers to mitigate input volatility. Anchor capacity expansion in Gujarat's Kutch belt to capture FSSAI-mandated volume growth. For New Entrants and Emerging Players: Build out regional distribution networks in Nigeria and Ethiopia where anemia intervention funding is rising without universal fortification mandates. Target pharmaceutical-grade premix supply to Brazilian processed food manufacturers facing ANVISA labeling requirements. Pursue white-label partnerships with quick-commerce platforms for specialty low-sodium variants in urban Indian households. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian salt refiners lacking in-house microencapsulation capabilities and dependent on European premix licensing. The 5-10 year viability window favors platforms with integrated chemical operations over standalone processors. Watch FSSAI iron fortification mandate expansion as the inflection signal for capacity utilization step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Licensing Agreement | Secures 18-month tropical stability IP for iron-fortified salt expansion into humid climates. |
| Backward Integration into Precursor Chemicals | Captures potassium iodate margin pools concentrated in Jiangsu and Shandong provinces. |
| Quick-Commerce Channel Partnership | Extracts premium pricing for certified pharmaceutical-grade specifications in Mumbai and Delhi. |
| East African Distribution Hub Expansion | Positions for Kenya and Tanzania school feeding program tender volumes through Mombasa logistics. |
| In-House Spectrophotometric Certification | Eliminates third-party testing delays for WHO-aligned analytical validation requirements. |
Methodological Framework
Operator-level perspectives from salt refinery plant managers, FSSAI compliance officers, food industry procurement leads, and quick-commerce category buyers anchored the qualitative base. Primary fieldwork combined with secondary validation from customs trade data, FSSAI technical specifications, WHO universal salt iodization guidelines, and SEC filings from listed chemical conglomerates. Bottom-up volume triangulation against top-down macroeconomic indicators ensured cross-verification of demand assumptions.
Scenario-bracketing around FSSAI mandate expansion timelines and potassium iodate price volatility bands structured the analytical framework across the projection horizon. Segmentation dimensions modeled include fortification chemistry tier, end-user certification requirements, distribution channel format, and regional regulatory cluster. CAGRs derived from installed capacity utilization curves and premix adoption rates within food manufacturing corridors. Forecast inputs incorporated microencapsulation technology cost curves and school feeding program procurement pipeline visibility.
Stress conditions across potassium iodate supply disruptions, FSSAI iron fortification mandate delays, and humid climate shelf-stability failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and premix supplier concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Feed Palatability Enhancers Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Trans-Resveratrol Market