
 Fortifying Agent Market | 2026-2036
Fortifying Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Fortifying Agent Market Analysis
The EU Green Deal is broadening compliance obligations for nutrient fortification across European food supply chains. DSM sustains leadership in vitamin premix formulation through its integrated biotechnology platforms. Cargill Incorporated anchors its position in mineral fortification via backward integration into food-grade salt and micronutrient sourcing. BASF SE competes on synthetic vitamin K2 and omega-3 fortification technologies for dairy applications.
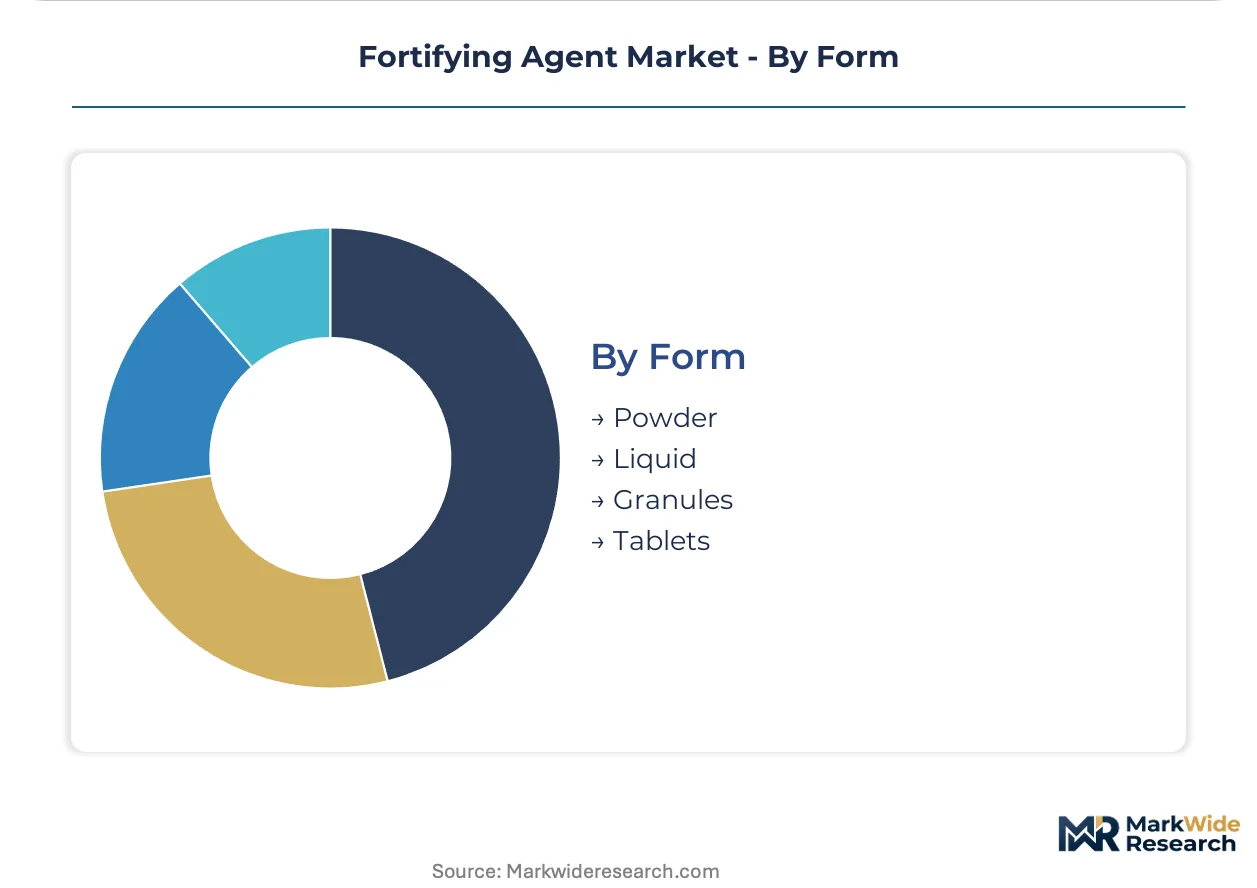
Fortifying agents are concentrated bioactive compounds—vitamins, minerals, amino acids, and dietary fibers—engineered for stability at temperatures between 80°C and 140°C during ultra-high-temperature dairy processing or extrusion baking. These agents compensate for nutrient losses in refined foods and enable health-claim labeling under regional food codes. Vitamins command the largest value share among product types due to high cost per kilogram and stringent stability requirements in aqueous beverages. Powder formulations dominate the form segment because of extended shelf life and ease of metering into continuous production lines, while liquid fortifiers are gaining ground in ready-to-drink beverage manufacturing where homogeneous dispersion is critical.
EFSA and EMA standards govern nutrient bioavailability claims and novel food ingredient approvals across Europe, forcing reformulation where health claim dossiers fail substantiation. REACH and F-Gas Regulation indirectly shape supply security by restricting certain solvent-based extraction chemistries used in vitamin production. Stakeholders must monitor evolving EFSA opinions on maximum permitted levels for fat-soluble vitamins, as downward revisions would force immediate recipe adjustments across bakery and supplement portfolios.
Market Dynamics
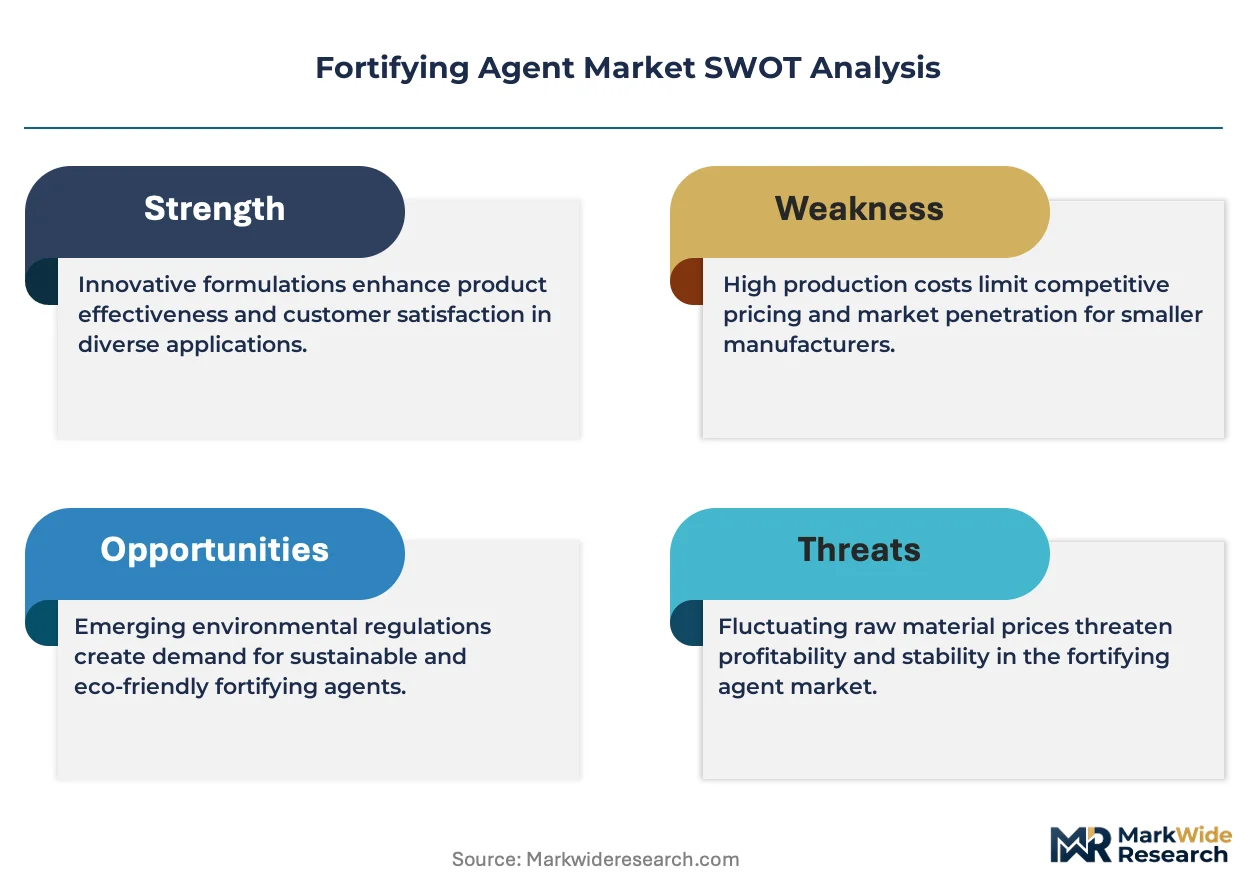
Ultra-high-temperature processing requirements in functional dairy are compressing formulation windows for heat-sensitive vitamins, forcing premix suppliers to engineer novel encapsulation chemistries or cede share to mineral-dominant portfolios.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Tightened substantiation requirements for bioactive compounds are filtering out low-dossier competitors and concentrating contract manufacturing among EFSA-validated formulators.
- Functional beverage expansion:Nutraceutical companies are extending fortification programs into ready-to-drink formats, creating pull for thermostable vitamin K2 and microencapsulated omega-3 systems.
- German manufacturing cluster:Food-grade mineral premix production has scaled significantly around specialized salt processing infrastructure, anchoring European supply security.
Market Restraints
- Input cost volatility:Food-grade salt and marine-derived omega-3 feedstocks face price swings tied to energy-intensive extraction and fishery quota restrictions.
- Supply concentration risk:Synthetic vitamin K2 and certain fat-soluble vitamin precursors depend on concentrated fermentation capacity in specific Asian manufacturing zones.
- REACH solvent restrictions:Certain extraction chemistries used in vitamin production face phase-out timelines, forcing costly process revalidation.
Strategic Opportunities
- Underpenetrated bakery segments:Extrusion baking applications for dietary fiber fortification remain technically underserved relative to dairy, offering whitespace for heat-stable prebiotic formulations.
- EU Green Deal compliance services:Nutrient lifecycle assessment and carbon footprint verification are emerging as premium service layers attached to premix supply contracts.
- Convergence of encapsulation and biotechnology:Integrated platforms combining fermentation-derived actives with lipid-shell stabilization are opening clean-label positioning in organic beverage channels.
Industry Challenges
- Formulation chemist scarcity:Expertise in vitamin stability modeling across 80°C to 140°C processing windows is concentrated among retiring specialists in European flavor houses.
- EFSA opinion volatility:Downward revisions to maximum permitted levels for fat-soluble vitamins force immediate recipe adjustments across bakery and supplement portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortifying Agent Market |
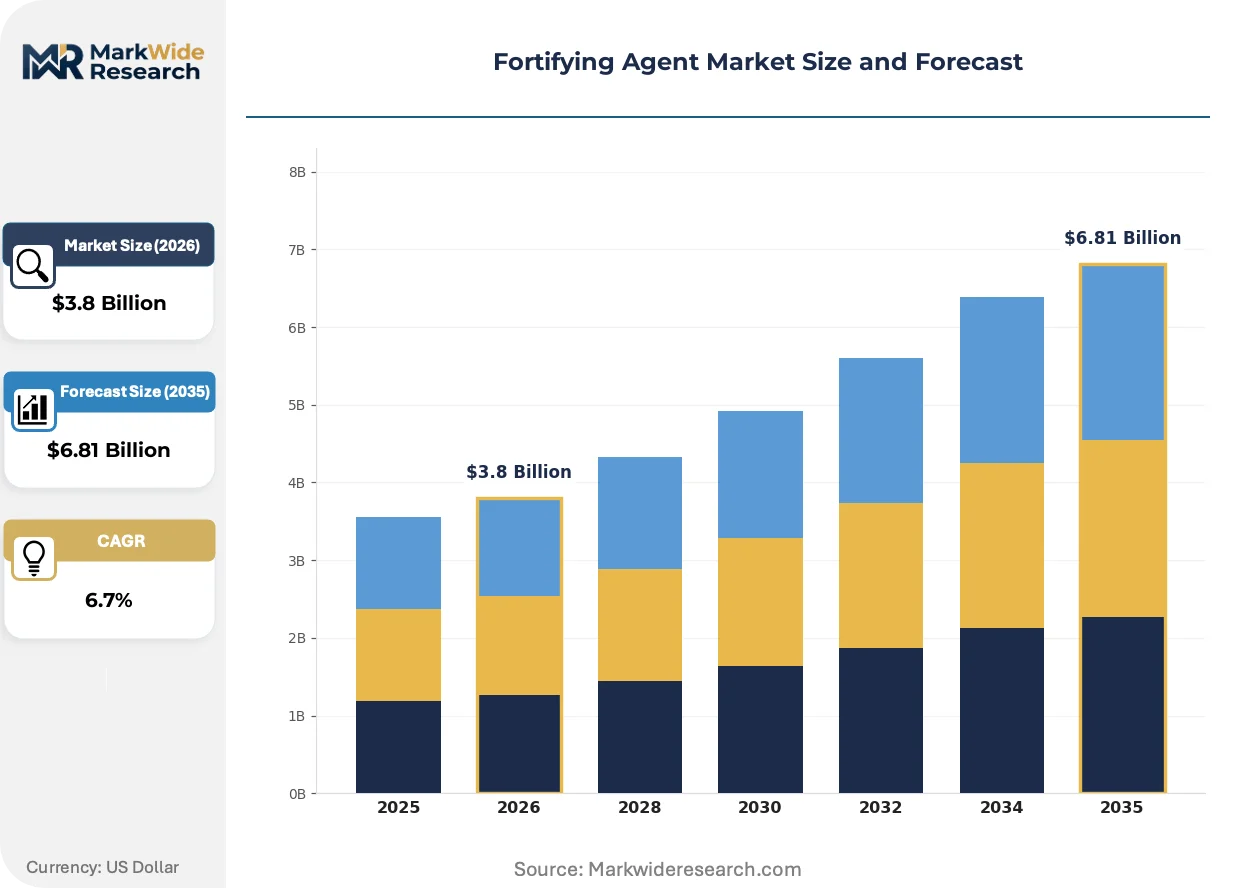
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Amino Acids, Fiber Application: Dairy Products, Beverages, Bakery Products, Supplements End User: Food Manufacturers, Nutraceutical Companies, Healthcare Providers, Consumers Form: Powder, Liquid, Granules, Tablets |
| Companies Covered | DuPont, Archer Daniels Midland Company, Cargill Incorporated, BASF SE, DSM, Advanced Organic Materials, Ingredion Incorporated, International Flavors & Fragrances Inc., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortifying Agent Market Emerging Trajectories
Encapsulation biotechnology is reshaping competitive positioning in fortifying agents, separating integrated platform suppliers from commodity premix blenders. Three developments are compressing formulation timelines and expanding addressable applications.
Microencapsulation via lipid-shell and complex-coacervation systems is electrifying vitamin stability in aqueous beverages. Ready-to-drink manufacturers are adopting these systems at accelerating pace to enable homogeneous dispersion without sedimentation. This technology is compressing the traditional trade-off between shelf life and bioavailability claims.
EFSA maximum level revisions for fat-soluble vitamins are forcing reformulation investments across European bakery and dairy portfolios. Manufacturers must resubmit health claim dossiers where prior substantiation fails under tightened bioavailability standards. Fat-soluble vitamin premixes face the most severe compliance compression, with several German and French suppliers accelerating novel food ingredient approvals as defensive hedges.
Buyer concentration among multinational beverage conglomerates is compressing supplier negotiation cycles and unbundling technical service from base premix supply. Tier-one nutraceutical contract manufacturers are responding by verticalizing in-house stability testing and regulatory dossier preparation. This pattern is most visible in German functional beverage clusters where three buyers account for disproportionate volume.
Fortifying Agent Market Segmentation

Fortifying agent selection hinges on processing temperature tolerance, bioavailability requirements, and regulatory claim substantiation. Each segmentation dimension carries distinct technical and commercial trade-offs that reshape supplier-customer contracting terms.
Product Type:
Customization intensity varies sharply across this category, from commodity mineral salts to precision-engineered vitamin matrices requiring encapsulation patents.
- Minerals:Food-grade iron, zinc, and selenium compounds formulated for thermal stability in extrusion baking. German salt-processing infrastructure anchors European supply security for these formulations.
- Vitamins:Synthetic and fermentation-derived compounds including fat-soluble A, D, E, K and water-soluble B-complex, C. Demand concentrates in functional dairy where UHT processing at 135-140°C forces lipid-shell encapsulation investments. EFSA maximum level revisions for fat-soluble variants drive reformulation urgency.
- Amino Acids:Lysine, methionine, and branched-chain formulations for protein fortification in sports nutrition.
- Fiber:Soluble and insoluble prebiotic compounds including inulin, resistant starch, and beta-glucan for digestive health positioning.
Leading the category by volume: Minerals. Expanding most quickly: Vitamins.
Application:
Margin structure follows processing severity, with UHT dairy commanding premium formulation services versus ambient-stable supplements.
- Dairy Products:Milk, yogurt, and cheese fortification requiring heat-stable vitamin K2 and microencapsulated omega-3 systems. EFSA bioavailability substantiation standards filter out low-dossier competitors in this segment.
- Beverages:Ready-to-drink functional formats demanding homogeneous dispersion without sedimentation. German beverage conglomerates concentrate procurement power, compressing supplier negotiation cycles.
- Bakery Products:Bread, pastry, and extruded snack fortification with dietary fibers and B-vitamins.
- Supplements:Capsule, tablet, and gummy delivery formats for direct consumer channels.
Dairy commands the steepest premium tier. Beverages are climbing the fastest.
End User:
Procurement sophistication separates multinational formulators from regional blenders, with technical service unbundling accelerating among tier-one buyers.
- Food Manufacturers:Industrial-scale bakeries and dairy processors requiring continuous-feed premix systems with validated metering accuracy.
- Nutraceutical Companies:Functional food and supplement specialists demanding integrated stability testing and regulatory dossier preparation. Three German buyers disproportionately concentrate volume in this channel.
- Healthcare Providers:Clinical nutrition and therapeutic food programs with prescription-grade specifications.
- Consumers:Direct-to-market channels including fortified salt and cooking oil for household use.
Food manufacturers dominate procurement tonnage. Nutraceutical companies are gaining share fastest.
Form:
Supply chain configuration separates powder's shelf-life advantage from liquid's dispersion performance in high-speed bottling lines.
- Powder:Spray-dried and agglomerated premixes with extended stability and ease of metering into continuous production. This format anchors mineral fortification across bakery and dry-mix beverage applications.
- Liquid:Emulsion and suspension systems for ready-to-drink manufacturing where homogeneous dispersion is critical. REACH solvent restrictions force costly process revalidation for lipid-based carriers in this segment.
- Granules:Intermediate particle size for controlled-release applications in supplement tableting.
- Tablets:Direct-compression and wet-granulation formats for consumer-facing supplement channels.
Powder leads by volume. Liquid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's specialized salt-processing corridors while consumption spreads across Western European dairy and beverage clusters. Asian fermentation capacity supplies synthetic vitamin precursors to European formulators under REACH compliance timelines.
Germany
Food-grade mineral premix manufacturing has scaled significantly around specialized salt processing infrastructure in Lower Saxony and North Rhine-Westphalia. The EU Nutrition and Health Claims Regulation filters out low-dossier competitors, concentrating contract manufacturing among EFSA-validated formulators. DSM maintains integrated biotechnology platforms for vitamin premix formulation at its Venlo-adjacent operations.
France
Dairy fortification demand concentrates in Brittany and Normandy milk processing basins requiring heat-stable vitamin K2 systems. ANSM and EFSA coordinate on novel food ingredient approvals for microencapsulated omega-3 applications. Paris-region nutraceutical specialists accelerate reformulation investments ahead of bioavailability standard revisions.
Netherlands
Ready-to-drink beverage manufacturing clusters around Rotterdam port logistics and dairy processing heritage in Friesland. REACH solvent restrictions force costly process revalidation for lipid-based vitamin carriers at emulsion production sites. Wageningen University corridor anchors stability testing and regulatory dossier preparation services.
United States
FDA substantiation requirements for nutrient content claims shape premix procurement by multinational beverage conglomerates. Corn Belt amino acid fermentation capacity supplies lysine and methionine for sports nutrition fortification. Chicago and Minneapolis functional food headquarters concentrate buyer power, compressing supplier negotiation cycles.
China
Synthetic vitamin K2 and fat-soluble vitamin precursor fermentation concentrates in Zhejiang and Jiangsu provinces. SAMR novel food ingredient approvals lag EFSA timelines, creating regulatory arbitrage for export-oriented producers. Yangtze River Delta chemical parks face dual carbon goals pressure on energy-intensive extraction chemistries.
Fortifying Agent Market Vendor Landscape
The competitive structure tilts toward integrated biotechnology platforms over commodity premix blenders. Tier-one suppliers separate from regional blenders through captive encapsulation patents and in-house stability testing capabilities. Two strategic archetypes dominate: fermentation-derived active specialists and mineral-salt backward integrators. Capacity expansion in German salt-processing corridors and technology licensing for lipid-shell systems constitute the dominant competitive moves.
Within the integrated platform tier, DSM and BASF SE exemplify biotechnology-anchored positioning, while Cargill Incorporated represents backward integration into food-grade salt and micronutrient sourcing. These three entities occupy distinct vectors of the premix value chain—DSM through fermentation-derived vitamins, BASF SE through synthetic K2 and omega-3 technologies, and Cargill through mineral supply security. Regional blenders lacking EFSA-validated dossiers face accelerating margin compression as buyer concentration hardens technical service requirements.
| Leading Market Players |
|---|
| DuPont |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| BASF SE |
| DSM |
| Advanced Organic Materials |
| Ingredion Incorporated |
| International Flavors & Fragrances Inc. |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Food-grade salt index movements cascade through European fortifying agent supply chains, compressing margin tiers for mineral premix suppliers while amplifying pricing power among backward-integrated salt processors in German manufacturing corridors.
Pricing Analysis
Yield-guaranteed pricing anchors premium vitamin premix contracts, where suppliers indemnify bioavailability outcomes in UHT dairy applications. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated formulators from regional blenders lacking dossier substantiation. Cost compression in standard-tier mineral salts intensifies because of energy-intensive extraction economics and REACH solvent phase-out timelines. Nutraceutical contract manufacturers exhibit highest price sensitivity, while clinical nutrition programs tolerate premium positioning for prescription-grade specifications.
Supply Chain Analysis
Synthetic vitamin K2 precursor supply rests on concentrated fermentation capacity in Zhejiang and Jiangsu provinces, with European formulators dependent on import channels subject to SAMR export approval lags. Food-grade salt feedstocks draw from German and Dutch evaporative processing infrastructure, while marine-derived omega-3 oils hinge on North Atlantic fishery quotas and energy-intensive molecular distillation. Single-source vulnerability concentrates in Asian fermentation zones for fat-soluble vitamin precursors. Distribution runs through Rotterdam port logistics for liquid emulsion systems and overland trucking corridors for powder premixes serving Central European dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Nutrition and Health Claims Regulation erects a compliance moat that filters low-dossier competitors and concentrates contract manufacturing among EFSA-validated formulators with validated stability testing capabilities.
For Market Incumbents: To counter buyer concentration among German beverage conglomerates, incumbents should deepen captive encapsulation patent portfolios and expand in-house regulatory dossier preparation services. Capacity addition in Lower Saxony salt-processing corridors reinforces supply security against Asian fermentation supply shocks.
For New Entrants and Emerging Players: German nutraceutical contract manufacturers represent the most penetrable channel partner type for novel microencapsulation technologies, given their unbundling of technical service from base premix supply. Extrusion baking applications for heat-stable prebiotic formulations offer whitespace with lower EFSA substantiation barriers than dairy. A co-development go-to-market angle with Wageningen University corridor stability testing services accelerates credibility building.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap mineral premix specialists with EFSA-validated dossiers in German manufacturing zones, positioned for compliance-driven consolidation. Long-term viability hinges on biotechnology-anchored platforms combining fermentation-derived actives with lipid-shell stabilization. The signal to watch is downward EFSA maximum level revisions for fat-soluble vitamins, which would force immediate recipe adjustments and accelerate defensive M&A among formulators lacking novel food ingredient pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Patent Expansion | Lipid-shell stabilization patents separate integrated platform suppliers from commodity blenders in aqueous beverage applications. |
| EFSA Dossier Preparation Verticalization | In-house regulatory substantiation capabilities capture technical service premiums unbundled from base premix supply contracts. |
| German Salt Corridor Capacity Addition | Backward integration into food-grade mineral processing anchors European supply security against input cost volatility. |
| Novel Food Ingredient Pipeline Investment | Defensive hedges against EFSA maximum level revisions protect bakery and dairy portfolio viability across reformulation cycles. |
| Carbon Footprint Verification Service Launch | EU Green Deal compliance layers attach premium pricing to premix contracts through lifecycle assessment capabilities. |
Methodological Framework
Document review covered EFSA scientific opinions, REACH registration dossiers, and EU Nutrition and Health Claims Regulation guidance documents, complemented by interviews with premix formulation chemists, regulatory affairs directors at nutraceutical contract manufacturers, procurement leads at German dairy processors, and stability testing specialists at Wageningen University corridor facilities. Secondary validation drew from customs trade data for food-grade salt and vitamin precursor imports, SEC filings of listed ingredient suppliers, and Cefic chemical industry reports. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from macroeconomic consumption indicators.
Segment-level value outputs reflect differential pricing for EFSA-validated versus non-validated formulations, with mineral and vitamin product types modeled separately alongside dairy, beverage, bakery, and supplement applications. End-user segmentation captured procurement sophistication variance between multinational food manufacturers and regional nutraceutical specialists. CAGRs were derived from regression analysis of historical premix consumption against dairy and beverage production indices, incorporating EFSA opinion revision probabilities and REACH solvent restriction implementation timelines as scenario weights.
Caveats apply where EFSA maximum level revisions, REACH solvent phase-out accelerations, or Asian fermentation supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory timeline adherence and bioavailability substantiation success rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
South America Feed Palatability Enhancers Market
Food Enhancers and Additives
High Ratio Shortening Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Instant Whipping Agents Market