
 United Kingdom Interesterified Fats Market | 2026-2036
United Kingdom Interesterified Fats Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Interesterified Fats Market Analytics
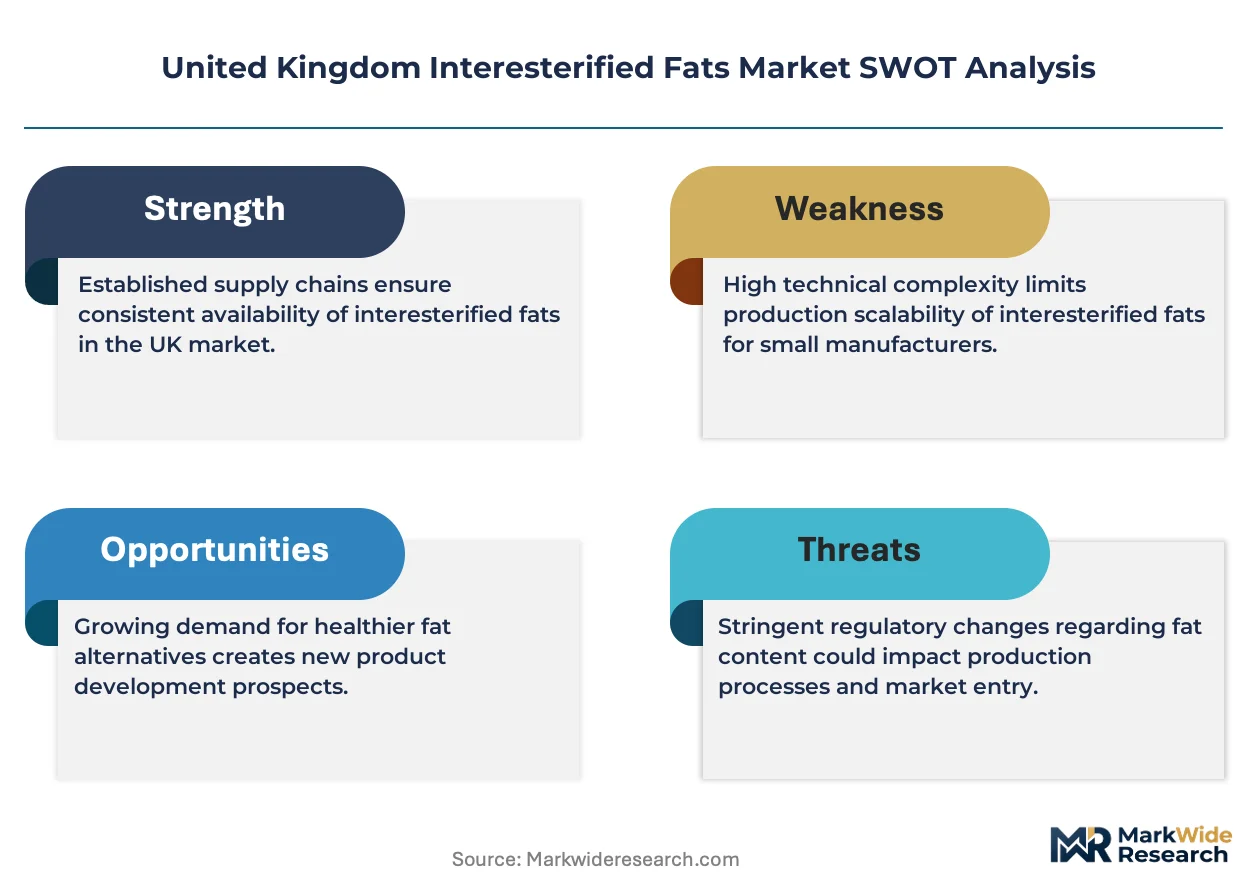
Technical advisory and reformulation support is hardening into a core revenue layer alongside commodity fat sales. Cargill Incorporated leverages its European R&D footprint to anchor premium positioning in enzymatic interesterification services. Bunge Limited competes through backward integration into oilseed crushing, which sustains margin control across the value chain.
Interesterified fats are triglycerides restructured through chemical or enzymatic catalysis to modify melting profiles, typically achieving slip points between 35°C and 45°C for tailored functionality in food matrices. The process rearranges fatty acids across glycerol backbones to create fats with specific crystallization behavior, primarily serving industrial bakers and spread manufacturers seeking trans-fat-free alternatives. Solid and semi-solid forms command structural priority given their dominance in shortening and margarine applications where plasticity and creaming performance determine procurement decisions. Dairy and confectionery end uses represent concentrated growth vectors as processors reformulate for cleaner label positioning under retailer scrutiny.
The Food Standards Agency trans-fat reduction framework and retained EU-origin food safety standards shape permissible lipid compositions in UK-manufactured products. BIS certification requirements for imported feedstock oils and the UK's post-EU border compliance regime govern supply chain configuration and sourcing economics. Stakeholders must monitor evolving divergence between UK and EU food safety regulations as this determines competitive access for continental suppliers versus domestic enzymatic processing investments.
Market Dynamics
The Food Standards Agency's trans-fat reduction framework is compressing formulation timelines across UK food manufacturing, forcing accelerated enzymatic interesterification adoption and restructuring supplier-processor relationships.
Growth Catalysts
- Bakery Reformulation Mandates:Industrial bakers in Greater Manchester and the West Midlands are retrofitting production lines to meet FSA slip-point specifications, creating sustained demand for tailored fat crystallization profiles.
- Retailer Clean-Label Pressure:Major UK grocery chains are enforcing trans-fat-free requirements through procurement contracts, compelling spread manufacturers to source enzymatically processed alternatives.
- Enzymatic Process Economics:Lipase-catalyzed interesterification is displacing chemical routes in Midlands processing facilities due to superior specificity and reduced downstream refining costs.
Market Restraints
- Palm Oil Price Volatility:Malaysian and Indonesian feedstock cost swings compress margin predictability for UK blenders lacking long-term supply agreements.
- Specialized Equipment Capex:Continuous enzymatic reactors require seven-figure capital commitments that exclude mid-scale compounders from process upgrading.
- Post-EU Border Friction:BIS certification delays for imported soybean and rapeseed oils extend inventory cycles and complicate just-in-time manufacturing.
Strategic Opportunities
- Confectionery White Space:Chocolate and coating manufacturers in Yorkshire represent underpenetrated demand for high-melting-point interesterified cocoa butter alternatives.
- Technical Service Bundling:Reformulation consulting tied to fat supply contracts is creating defensible revenue streams beyond commodity margins.
- Dairy Analogue Expansion:Plant-based cream and cheese processors are specifying interesterified coconut-palm blends for functional mouthfeel replication.
Industry Challenges
- Enzyme Stability Expertise:Lipase immobilization and reactor optimization require biocatalysis specialists scarce in traditional fat processing regions.
- Dual Regulatory Tracking:Manufacturers must simultaneously monitor FSA enforcement and retained EU standard divergence, complicating compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Interesterified Fats Market |
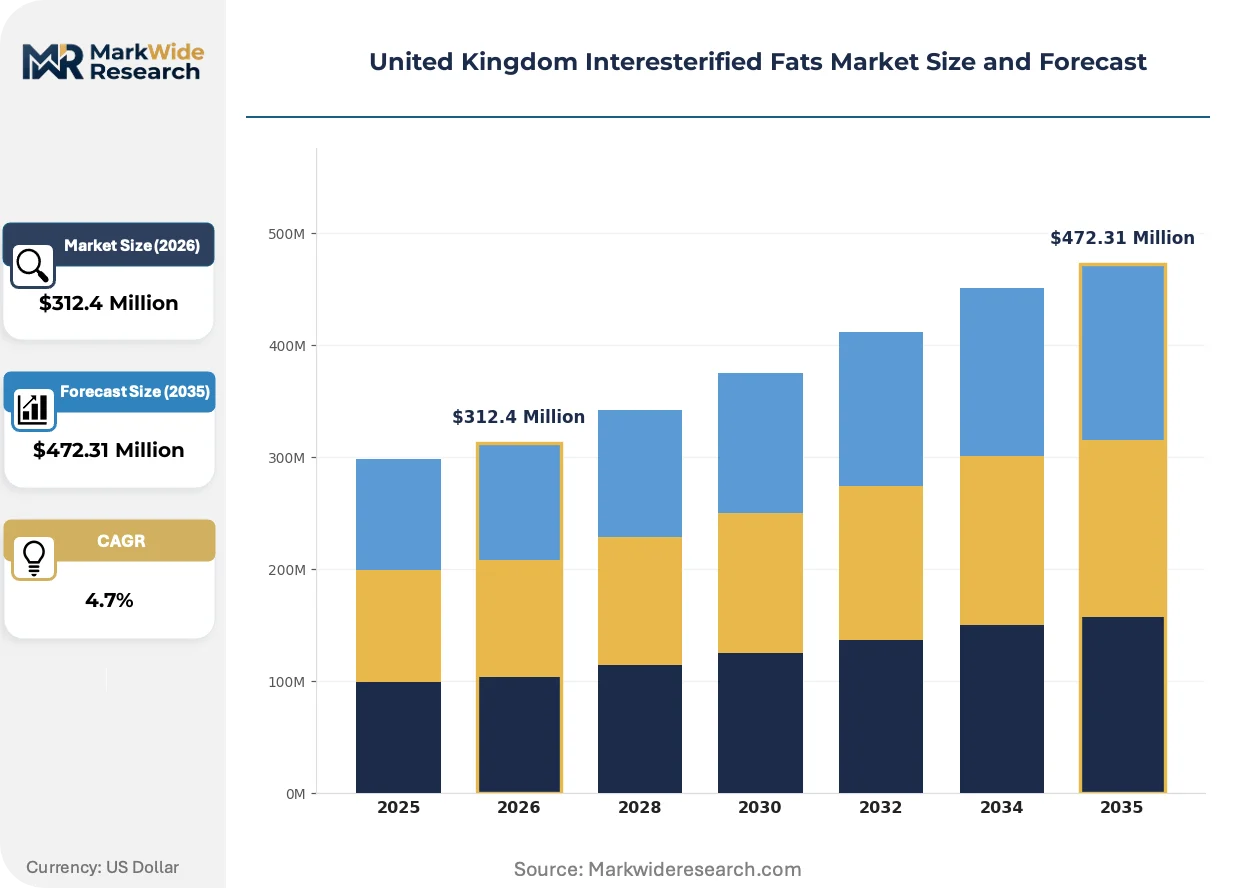
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Liquid, Solid, Semi-solid, Powder Application: Baking, Spreads, Confectionery, Dairy End User: Food Manufacturers, Restaurants, Catering Services, Retailers Product Type: Shortenings, Margarines, Creamers, Fillings |
| Companies Covered | Archer Daniels Midland Company, Fuji Oil Holdings, Cargill Incorporated, 3F Industries Limited, Intercontinental Specialty Fats Sdn, Bunge Limited, IOI Corporation Berhad, Oleo Fats Inc., Wilmar International Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Interesterified Fats Market Evolving Landscape
Process intensification and regulatory precision are converging to reshape UK fat processing economics, with technology adoption rates diverging sharply between capital-rich multinationals and regional compounders.
Continuous enzymatic interesterification using immobilized lipase packed-bed reactors is electrifying throughput economics in Midlands processing hubs. Industrial margarine manufacturers are retrofitting batch systems to continuous flow configurations within eighteen-month windows. This hardware transition is compressing unit production costs and enabling real-time crystallization control that batch chemistry cannot replicate.
The FSA's retained EU-origin maximum trans-fat limits are hardening into non-negotiable procurement specifications across UK retail channels. Food manufacturers reformulating shortening and spread portfolios face compressed validation timelines ahead of enforcement milestones. Bakery and confectionery segments are responding by locking multi-year supply agreements with domestic enzymatic processors to secure formulation stability.
Specification-driven procurement is consolidating buyer power among national bakery chains and retail private-label programs. Regional compounders accustomed to spot-market transactions are losing share to integrated suppliers offering certified trans-fat-free portfolios with full traceability documentation. This behavioral shift is most visible in England's industrial food processing corridor, where procurement teams now mandate enzymatic process verification as a condition of vendor qualification.
United Kingdom Interesterified Fats Market Segmentation
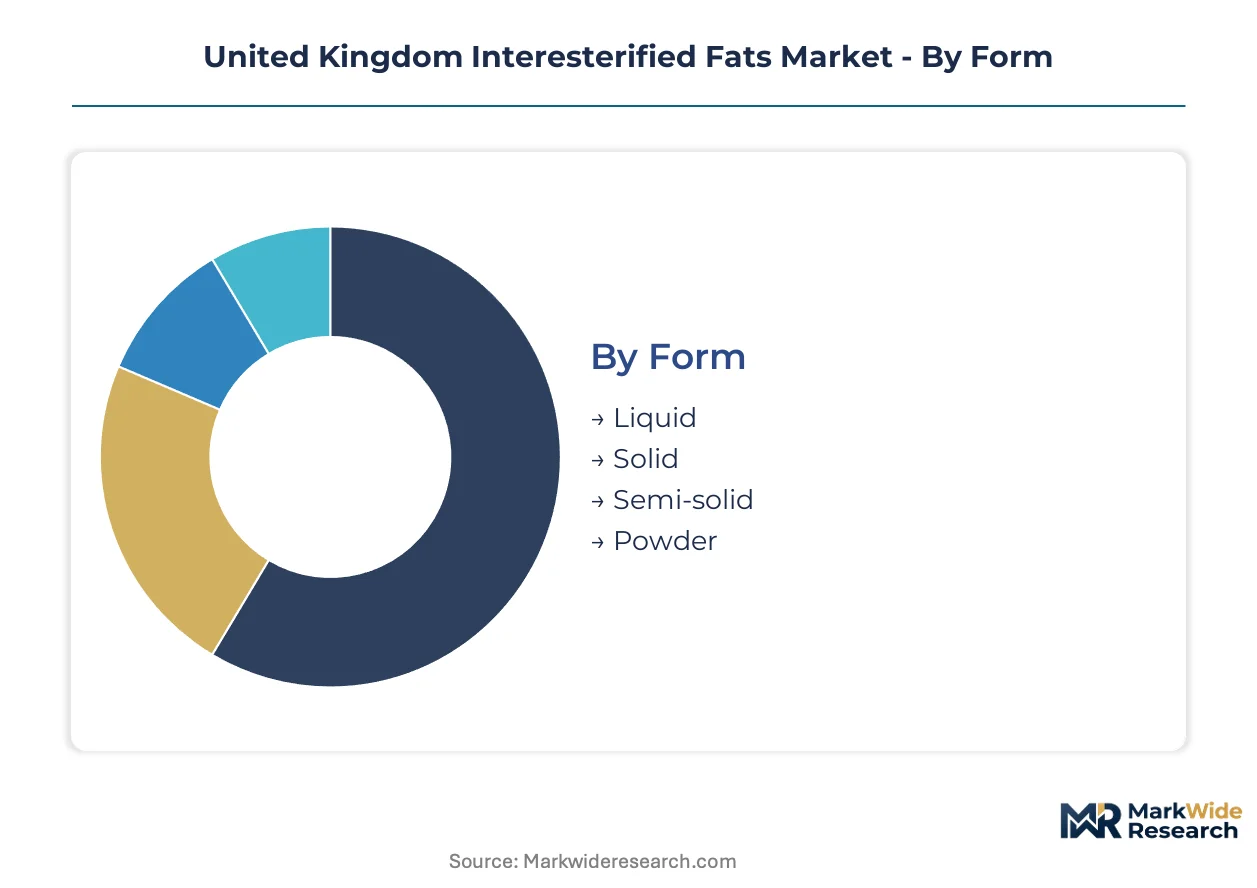
Interesterified fats command divergent specifications across form factors and end-use applications, with procurement teams in Greater Manchester and the West Midlands weighting crystallization behavior and slip-point precision differently by production line. Segmentation clarity determines vendor qualification outcomes as FSA trans-fat enforcement hardens into contract-level requirements.
Form:
Procurement specifications prioritize melting profile stability over shelf-life extension, driving divergent sourcing economics across physical states.
- Solid:Fully hydrogenated interesterified fats achieve slip points between 35°C and 45°C for industrial shortening applications. Bakery manufacturers in the West Midlands specify solid forms for laminated dough processing where plasticity retention under mechanical stress determines batch consistency.
- Semi-solid:Partially crystallized triglyceride structures deliver creaming performance in margarine production without trans-fat content. Spread manufacturers retrofitting Greater Manchester facilities source semi-solid interesterified bases to meet retailer clean-label mandates while maintaining spreadability at refrigeration temperatures.
- Liquid:Low-melting-point fractions serve spray coating and fluid shortening applications where pumpability at ambient temperature reduces heating energy.
- Powder:Encapsulated or plated formats support dry mix incorporation for instant bakery premixes and vending machine applications.
Solid leads on scale; semi-solid leads on momentum.
Application:
Reformulation timelines compress fastest where trans-fat replacement intersects high-volume production infrastructure.
- Baking:Laminated and chemically leavened goods require tailored solid fat indices for aeration and layer definition. Industrial bakers in England's food processing corridor are locking multi-year supply agreements with domestic enzymatic processors to secure formulation stability ahead of FSA enforcement milestones.
- Confectionery:Cocoa butter alternatives demand high-melting-point interesterified fats with sharp melting curves for snap and gloss retention. Chocolate manufacturers in Yorkshire represent underpenetrated demand as technical service bundling creates defensible supplier relationships beyond commodity margins.
- Spreads:Table and industrial margarine applications balance spreadability against structural integrity through controlled polymorphism.
- Dairy:Plant-based cream and cheese analogues specify interesterified coconut-palm blends for functional mouthfeel replication in clean-label positioning.
Baking dominates volume throughput; confectionery exhibits the steepest expansion trajectory.
End User:
Scale concentration and technical sophistication determine contract structure and pricing leverage.
- Food Manufacturers:National bakery chains and retail private-label programs consolidate procurement power through specification-driven vendor qualification. Midlands-based industrial compounders now mandate enzymatic process verification as a condition of supply base entry.
- Restaurants:Quick-service and casual dining chains specify interesterified frying fats for extended fry-life and reduced polymerization.
- Catering Services:Institutional foodservice operators prioritize cost stability through long-term supply agreements with integrated oilseed processors.
- Retailers:Grocery chains enforce trans-fat-free requirements through procurement contracts that cascade down to ingredient supplier audits.
Food manufacturers anchor procurement volume; retailers dictate compliance architecture.
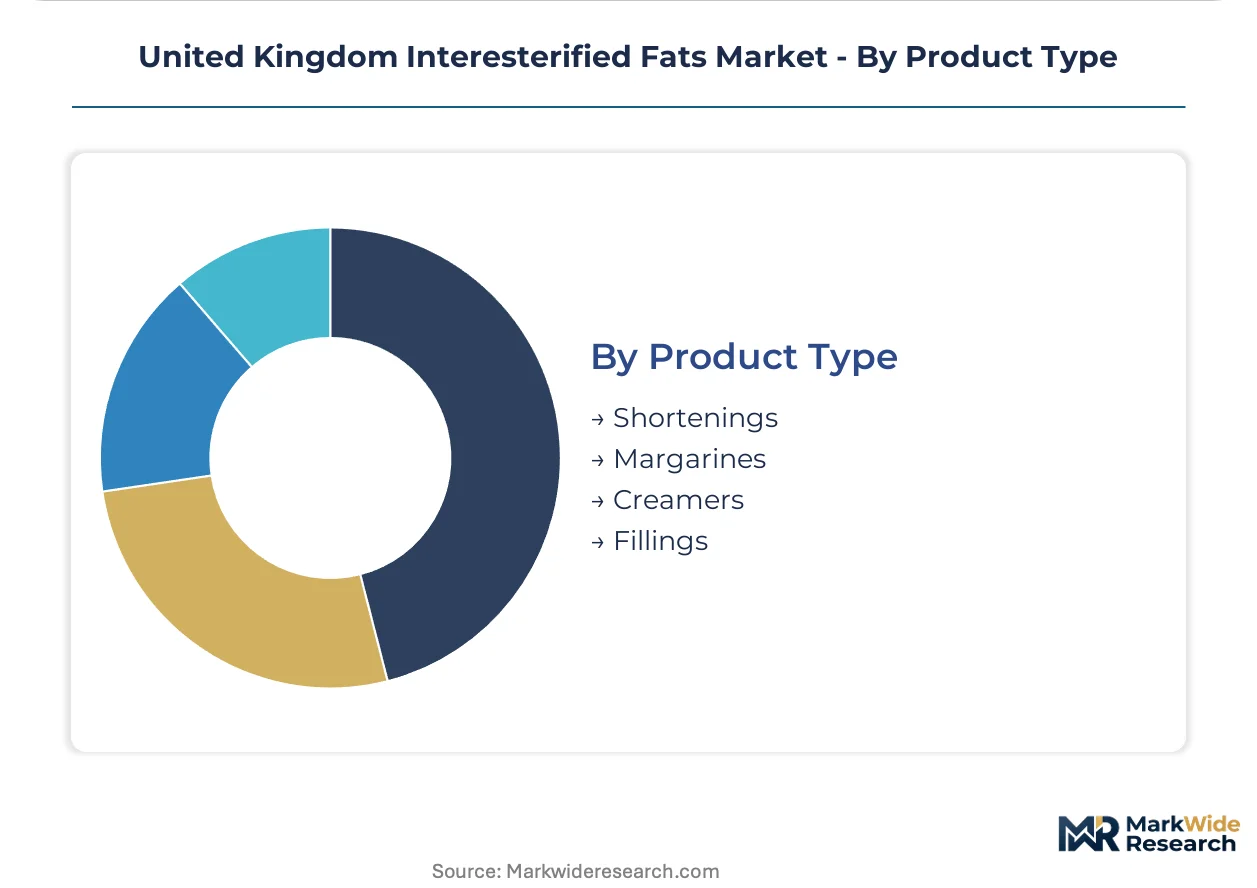
Product Type:
Functional performance requirements separate premium enzymatic offerings from commodity chemical routes.
- Shortenings:All-purpose and emulsified shortenings for industrial baking command the largest production volumes. Lipase-catalyzed interesterification is displacing chemical routes in Midlands facilities due to superior specificity and reduced downstream refining costs.
- Margarines:Industrial and retail spread formulations require precise control of solid fat content across temperature ranges for plasticity and mouthfeel.
- Creamers:Non-dairy coffee whiteners utilize interesterified fats for whitening power and stability in acidic hot beverages.
- Fillings:Cream and fondant bases for confectionery and bakery applications demand narrow melting ranges for texture stability.
Shortenings maintain production dominance; margarines accelerate fastest on reformulation intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United Kingdom present contrasting regulatory enforcement timelines for trans-fat reduction, with the former accelerating voluntary industry commitments while the latter imposes stricter mandatory limits through retained EU-origin standards.
England
Industrial bakers in Greater Manchester and the West Midlands drive enzymatic interesterification adoption as the Food Standards Agency enforces trans-fat ceilings. The FSA's retained EU-origin maximum limits harden into procurement specifications across retail channels. Midlands processing facilities retrofit batch systems to continuous flow configurations, compressing unit production costs.
Scotland
Confectionery manufacturers in Glasgow and Edinburgh seek high-melting-point interesterified cocoa butter alternatives for snap and gloss retention. Scotland's food safety regulator aligns with FSA frameworks while maintaining distinct enforcement protocols. Aberdeen's specialty fat compounders invest in lipase immobilization expertise to serve chocolate coating applications.
Wales
Dairy analogue processors in South Wales specify interesterified coconut-palm blends for plant-based cream and cheese formulations. Welsh Government food innovation grants accelerate clean-label reformulation projects. Cardiff's emerging food tech cluster attracts enzymatic processing investments targeting retail private-label programs.
Northern Ireland
Cross-border supply chain friction complicates just-in-time manufacturing for Belfast-based spread manufacturers sourcing feedstock oils. Post-EU border compliance extends inventory cycles for imported soybean and rapeseed oils. Derry's regional compounders face capital constraints excluding them from continuous enzymatic reactor upgrades.
United Kingdom Interesterified Fats Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilseed processors commanding premium positioning through backward integration while regional compounders compete on spot-market flexibility. The vendor base concentrates among multinational agribusinesses with European R&D footprints and enzymatic processing capabilities. Three archetypes dominate: capital-rich multinationals leveraging technical service bundling, mid-scale regional blenders dependent on chemical routes, and specialty fat compounders serving niche confectionery applications. M&A activity targets enzymatic technology acquisition, while capacity expansion concentrates in Midlands processing hubs.
Among integrated agribusinesses, Cargill Incorporated and Bunge Limited exemplify the capital-intensive tier where technical advisory services harden into core revenue layers. Fuji Oil Holdings and IOI Corporation Berhad occupy positions as Asia-Pacific-origin specialists with established European distribution networks. Wilmar International Limited represents the scale-driven archetype with upstream oilseed crushing assets that sustain margin control across value chains.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Fuji Oil Holdings |
| Cargill Incorporated |
| 3F Industries Limited |
| Intercontinental Specialty Fats Sdn |
| Bunge Limited |
| IOI Corporation Berhad |
| Oleo Fats Inc. |
| Wilmar International Limited |
| Others |
Value Network & Pricing Analysis
Continuous enzymatic reactor retrofits in Midlands processing facilities are compressing unit production costs while simultaneously concentrating supply power among capital-rich multinationals capable of seven-figure hardware commitments. This technology transition reshapes pricing dynamics as batch-dependent regional compounders lose procurement leverage to integrated suppliers offering certified trans-fat-free portfolios with full traceability documentation.
Pricing Analysis
Capacity additions in Greater Manchester and the West Midlands are reshaping price floors for enzymatically processed interesterified fats. Three-tier pricing structure across premium enzymatic, standard chemical-route, and economy unverified tiers separates suppliers by FSA compliance certification and technical service bundling. Cost compression in the standard tier is intensifying because lipase-catalyzed production achieves superior specificity with reduced downstream refining. National bakery chains exhibit least price sensitivity due to locked multi-year supply agreements, while regional compounders remain most exposed to spot-market volatility.
Supply Chain Analysis
BIS certification requirements for imported feedstock oils are gating supplier qualification and extending inventory cycles for UK blenders. Malaysian and Indonesian palm oil plantations, Argentine soybean crushing facilities, and Ukrainian rapeseed processors anchor upstream supply concentration. UK manufacturers draw from these origins for triglyceride feedstocks essential to interesterification reactions. Single-source vulnerability persists around lipase enzyme supply anchored to Danish and Japanese biocatalysis specialists. Distribution runs through integrated oilseed processors with captive crushing assets rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Interesterified Fats Market operates as a stable compounder where regulatory enforcement of trans-fat ceilings drives predictable reformulation demand across England's industrial food processing corridor.
For Market Incumbents: Cement technical service bundling as a defensible revenue layer by embedding reformulation consulting within fat supply contracts. Deepen backward integration into oilseed crushing to sustain margin control against palm oil price volatility. Prioritize lipase immobilization expertise acquisition to offset biocatalysis specialist scarcity threatening reactor optimization.
For New Entrants and Emerging Players: Specialty confectionery manufacturers in Yorkshire represent an underserved buyer archetype seeking high-melting-point cocoa butter alternatives with technical partnership models. Plant-based dairy analogue processors in South Wales offer secondary penetration potential through clean-label coconut-palm blend specifications. A technical service-led go-to-market approach bypasses commodity margin compression dominant in spot-market transactions.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional compounders stranded on chemical processing routes without continuous enzymatic upgrade capital. The sector's five-to-ten year viability rests on FSA enforcement trajectory divergence from retained EU standards. Acquisition targets should demonstrate established retailer private-label relationships and enzymatic process verification credentials. The signal to watch is BIS certification timeline changes affecting feedstock import economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Enzymatic Reactor Deployment | Midlands facilities achieve real-time crystallization control that batch chemistry cannot replicate. |
| Backward Integration into Oilseed Crushing | Captive supply of Malaysian and Indonesian feedstock insulates margin predictability from price swings. |
| Technical Service Bundling | Reformulation consulting tied to fat contracts creates defensible revenue beyond commodity pricing. |
| Retailer Private-Label Program Lock-In | Multi-year agreements with national bakery chains secure volume throughput ahead of FSA milestones. |
| Lipase Immobilization Expertise Acquisition | Biocatalysis specialist teams enable reactor optimization scarce in traditional fat processing regions. |
Research Methodology
Direct dialogue with plant managers at Midlands processing facilities, procurement leads at national bakery chains, FSA regulatory affairs specialists, and technical R&D directors at enzymatic technology providers grounded qualitative insights. Secondary validation drew from UK customs and trade data, Food Standards Agency enforcement documentation, BIS certification records, and SEC filings of integrated agribusinesses. Bottom-up volume modeling across form factors and applications triangulated against top-down market sizing from oilseed crush statistics and industrial fat consumption surveys.
Top-down macroeconomic indicators and bottom-up segment-level production capacity data converged in the analytical framework. Segmentation dimensions modeled include physical form, end-use application, end-user archetype, and product type across the projection horizon. CAGRs were derived from regression analysis of historical enzymatic adoption rates and FSA compliance timeline assumptions. Forecast inputs incorporated palm oil futures curve trajectories and Midlands processing facility expansion announcements.
Inputs from FSA enforcement schedules and Malaysian Palm Oil Board export statistics were available through the study window; gaps in real-time inventory cycle data for cross-border feedstock movements introduce uncertainty bands around short-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding regulatory divergence timelines and enzyme cost curves. Material revision risks center on BIS certification protocol changes and palm oil price volatility spikes. A model refresh is warranted upon material change in FSA trans-fat limit enforcement milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Emulsion Stabilizer for Beverages Market
Food Enhancers and Additives
Europe Food Flavor and Enhancer Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market