
 Europe Chocolate Market | 2026-2036
Europe Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chocolate Market Analysis
Belgian and Swiss artisan producers is restructuring cocoa processing capacity across the Alpine corridor and the Flanders plain. Barry Callebaut leverages vertical integration from bean sourcing to couverture to sustain margin control across the supply chain. Lindt & Sprüngli anchors premium positioning through R&D intensity in conching technology and controlled-origin bean selection. Ferrero Group competes through geographic dominance in the hazelnut-chocolate segment and tight channel control in Southern Europe.
Europe chocolate comprises cocoa mass, cocoa butter, sugar, and milk solids formulated through roasting, grinding, conching, and tempering to achieve defined particle size below 30 microns and stable polymorphic crystal structures for snap, gloss, and shelf stability; its primary purpose spans direct confectionery consumption and industrial ingredient supply for bakery, dairy, and food service applications. Dark chocolate leads product type composition due to health-positioning and reduced sugar formulations, while ruby chocolate represents the fastest-growing variant driven by novel anthocyanin-derived color and fruit-forward flavor profiles without added dyes. Supermarkets dominate distribution channel volume, though online retail captures the fastest growth as direct-to-consumer subscription models and premium gifting platforms expand.
EFSA governs food safety and novel ingredient approvals, REACH regulates chemical inputs in processing aids and packaging migrants, and the EU Green Deal drives deforestation-free supply chain due diligence for cocoa imports. These frameworks elevate compliance costs for smaller processors while advantaging scaled operators with dedicated regulatory affairs and traceability infrastructure. Stakeholders must monitor evolving EUDR implementation timelines and carbon border adjustments to calibrate sourcing strategies and capital allocation.
Market Dynamics
EU Green Deal deforestation-free mandates are forcing cocoa processors to rebuild traceability infrastructure from farm to finished product, compressing margins for small operators while rewarding scaled players with dedicated compliance teams.
Growth Catalysts
- EFSA sustainability mandates:Novel ingredient approvals for reduced-sugar and plant-based formulations accelerate clean-label product pipelines across German and Swiss retail channels.
- Belgian heritage manufacturing clusters:Concentrated artisan capacity in Flanders drives premium export demand and technical knowledge spillover into adjacent processing regions.
- Conching technology R&D intensity:Particle-size refinement below 20 microns enables texture differentiation in ultra-premium dark chocolate segments.
Market Restraints
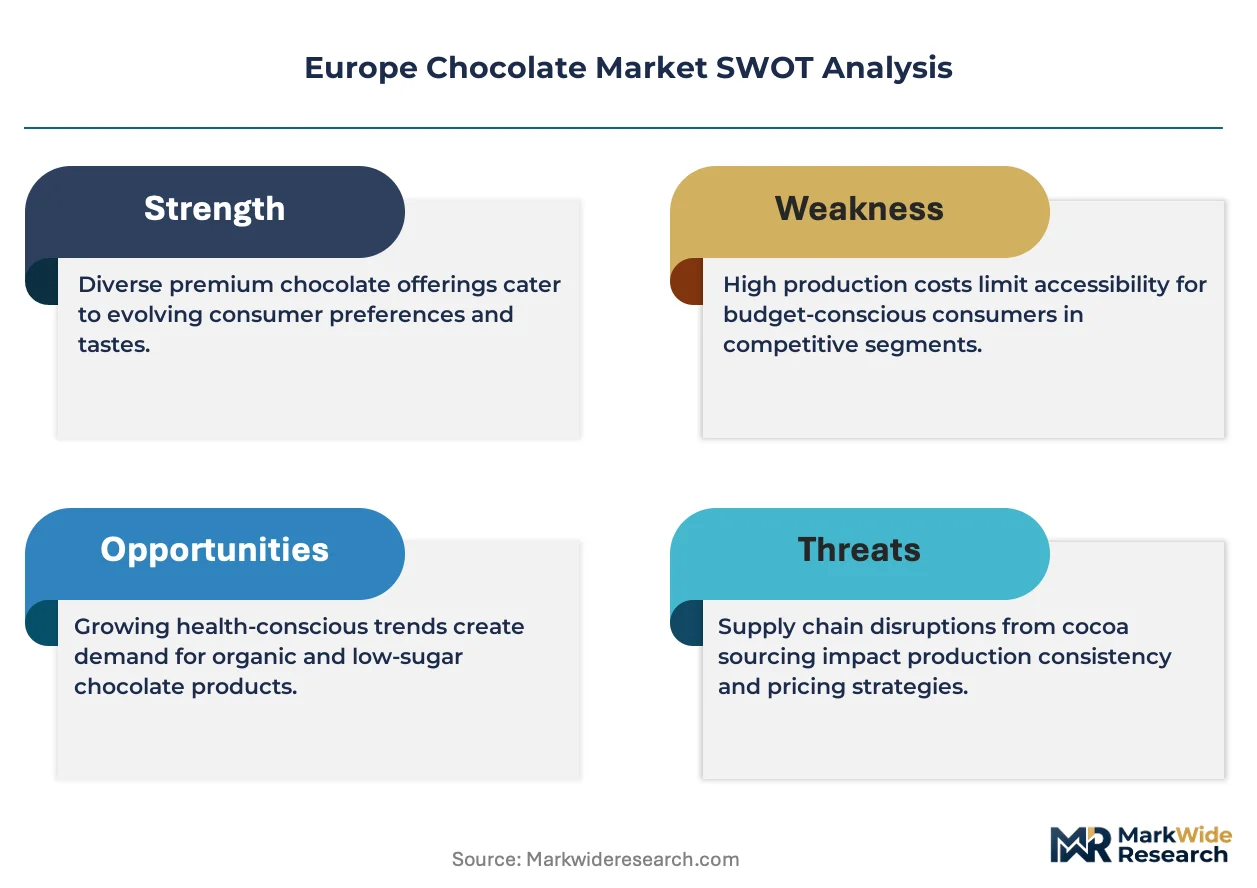
- Cocoa butter price volatility:Weather-driven supply fluctuations in West African origins compress processor margins and complicate forward contracting.
- REACH chemical input restrictions:Processing aid approvals face extended ECHA evaluation timelines, delaying formulation innovations.
- Sugar reduction technical ceiling:Mouthfeel degradation below specific thresholds limits clean-label claims without bulking agent compromises.
Strategic Opportunities
- EUDR implementation tailwinds:Early compliance investments position scaled operators for preferential supplier status as due diligence mandates activate.
- Ruby chocolate variant expansion:Anthocyanin-derived color technology opens fruit-forward positioning without artificial dye dependencies.
- Direct-to-consumer subscription channels:Premium gifting platforms bypass traditional retail margin structures in urban German and French markets.
Industry Challenges
- Bean-to-bar traceability engineering:GPS polygon mapping and mass-balance verification require capex-heavy IT infrastructure beyond mid-tier processor reach.
- Polymorphic crystal training scarcity:Tempering expertise for stable Form V chocolate structures concentrates among aging Swiss and Belgian master chocolatiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chocolate Market |
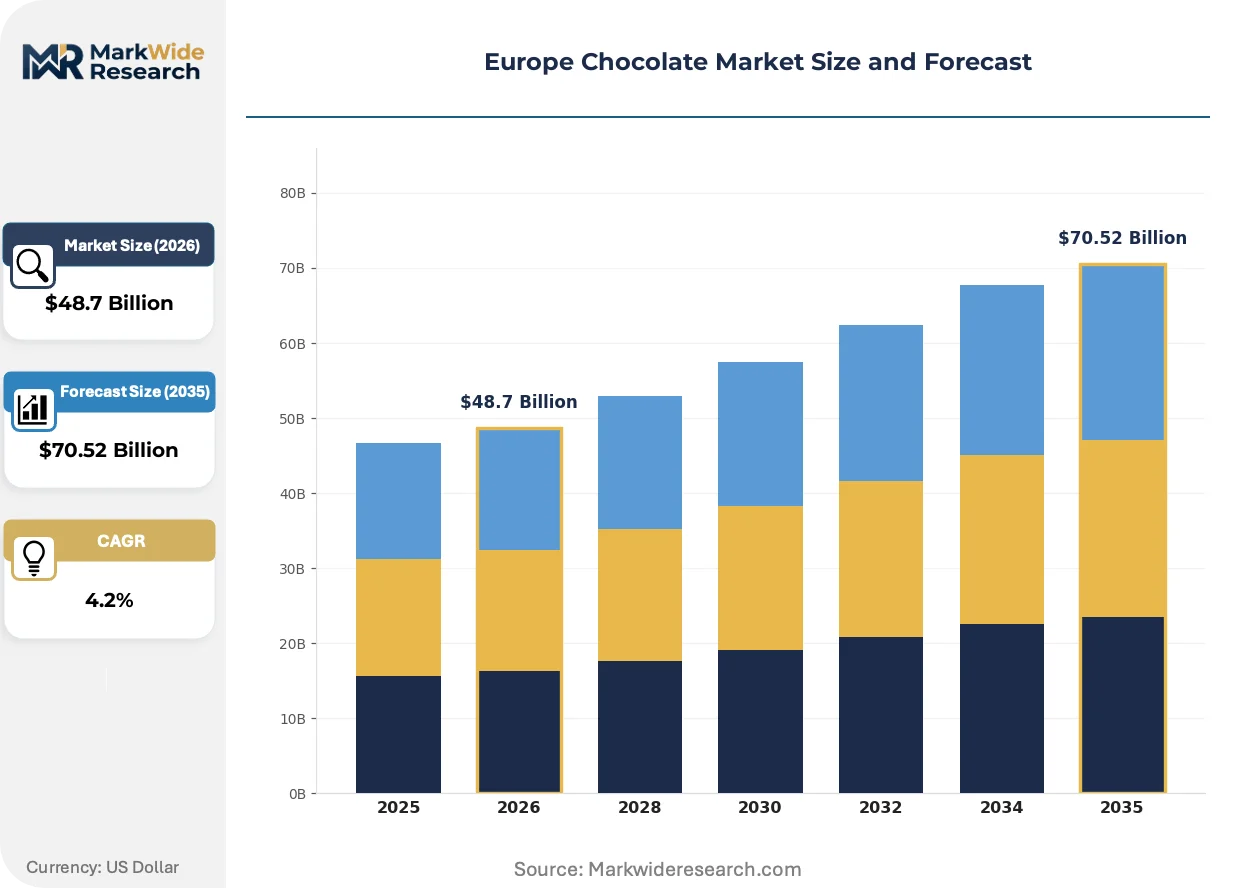
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Food Manufacturers, Bakeries, Restaurants Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Packaging Type: Bars, Boxes, Bites, Gifts |
| Companies Covered | Mars, Lindt & Sprüngli, Nestle S.A., Cargill Cocoa & Chocolate, The Hershey Company, Barry Callebaut, Ferrero Group, Olam Cocoa, Mondelez International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chocolate Market Emerging Trajectories
Chocolate processing is converging with precision fermentation and novel fat structuring technologies that rewrite formulation possibilities beyond traditional cocoa butter dependencies.
Precision fermentation-derived cocoa butter alternatives are consolidating technical pathways for climate-resilient supply chains. Barry Callebaut and mid-scale Swiss processors pilot microbial lipid platforms to reduce origin concentration risk. This technology is consolidating R&D budgets toward bioengineered fat structuring rather than geographic diversification alone.
EU Green Deal deforestation-free regulations now mandate GPS polygon verification for all cocoa imports into European customs territories. EUDR enforcement compresses supplier qualification timelines and elevates documentation burdens. Smallholder-dependent origins face exclusion risk as traceability infrastructure gaps persist.
Subscription-based premium gifting is displacing seasonal supermarket purchasing in urban consumer segments. Direct-to-consumer platforms capture recurring revenue through curated dark chocolate assortments and limited-edition releases. This pattern concentrates in German metropolitan markets and Swiss expatriate channels where convenience and provenance signaling overlap.
Europe Chocolate Market Segmentation
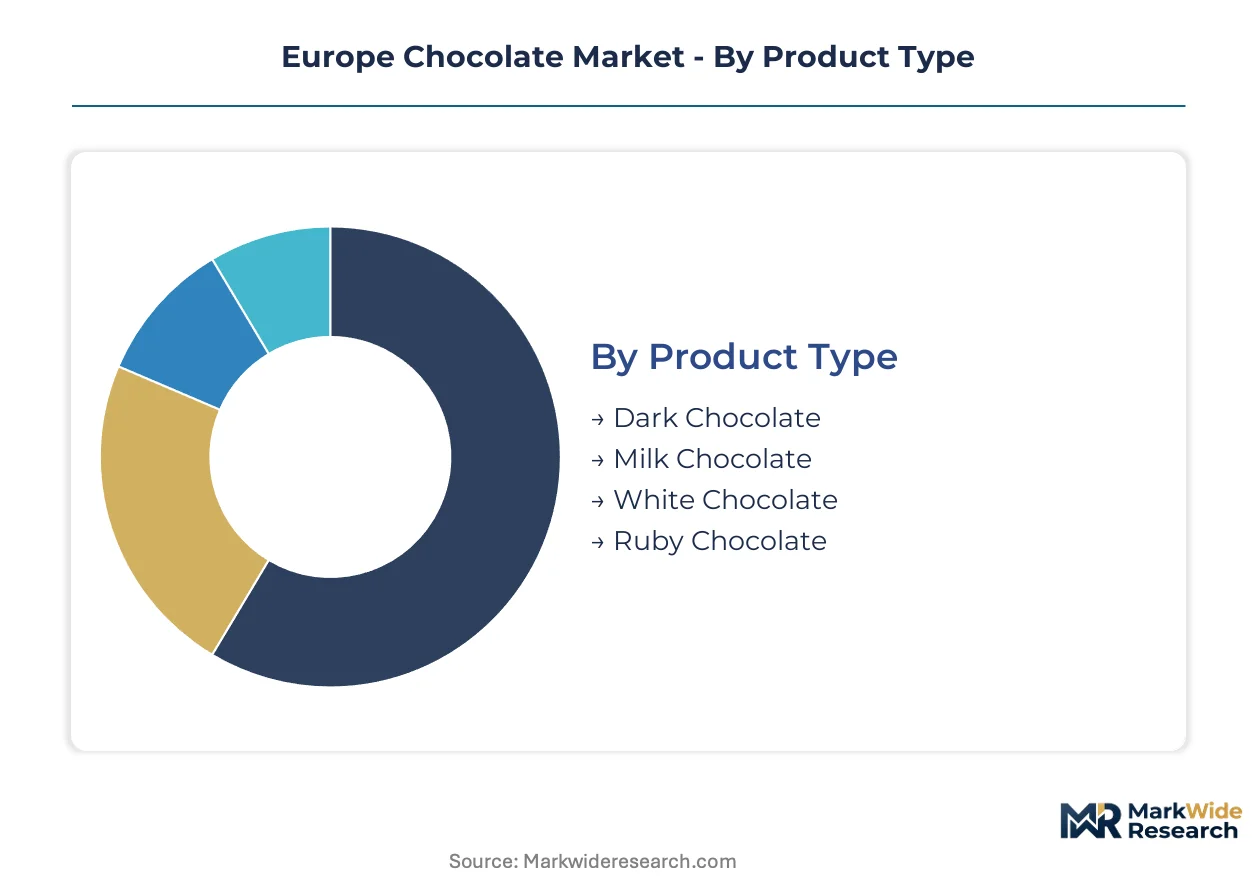
European chocolate segmentation reveals how supply chain configuration aligns with distinct margin profiles and regulatory exposure. Each category channels specific EUDR compliance burdens and EFSA formulation requirements toward differentiated customer bases.
Product Type:
Bean sourcing concentration in West Africa and Latin America shapes product-level compliance intensity across Swiss and Belgian processing clusters.
- Dark Chocolate:Formulated with cocoa mass exceeding 50% and minimal milk solids, this segment carries the highest cocoa butter input ratio. German retail channels absorb the bulk of reduced-sugar dark formulations driven by EFSA clean-label positioning.
- Milk Chocolate:Milk powder and condensed milk integration at 12-14% solids content defines this mass-market staple. Swiss heritage manufacturers anchor continental supply through Alpine dairy proximity and controlled-origin bean selection protocols.
- White Chocolate:Cocoa butter dominates at 20% minimum with no cocoa mass, creating pure fat-based margin exposure to Ivorian and Ghanaian origin volatility.
- Ruby Chocolate:Anthocyanin-derived pink coloration from specific cocoa bean varieties enables fruit-forward positioning without synthetic dyes.
Dark chocolate absorbs the bulk of installed capacity; ruby chocolate is expanding most quickly.
End User:
Customer type determines whether traceability investments translate to price realization or remain absorbed as compliance overhead.
- Retail Consumers:Direct consumption demand concentrates in premium gifting and daily indulgence occasions. German and French urban markets drive subscription channel adoption for curated dark chocolate assortments.
- Food Manufacturers:Industrial couverture and compound chocolate supply for dairy, bakery, and confectionery applications requires batch consistency and EUDR documentation at scale.
- Bakeries:Tempered chocolate decorations and enrobing applications need stable Form V crystal structures for shelf-stable finished goods.
- Restaurants:Plated dessert and pastry chef demand prioritizes origin storytelling and limited-edition releases for menu differentiation.
Food manufacturers command the largest volume flows; retail consumers are gaining share fastest through direct-to-channel disruption.
Distribution Channel:
Channel selection dictates margin capture versus traceability cost recovery timelines under tightening EUDR enforcement.
- Supermarkets:Hypermarket and supermarket chains dominate volume throughput across Germany, Switzerland, and Belgium. Private-label penetration and promotional intensity compress branded premium positioning.
- Online Retail:Direct-to-consumer platforms bypass traditional retail margin structures through subscription models and premium gifting platforms concentrated in German metropolitan markets.
- Convenience Stores:Impulse-oriented single-serve formats target travel and urban commuter occasions with limited origin signaling capacity.
- Specialty Shops:Artisan chocolatiers and heritage brand flagship stores enable bean-to-bar provenance narratives and conching technology education.
Supermarkets retain the deepest volume footprint; online retail is climbing the fastest as logistics infrastructure matures.
Packaging Type:
Format economics determine whether premium positioning survives REACH packaging migrant restrictions and plastic reduction mandates.
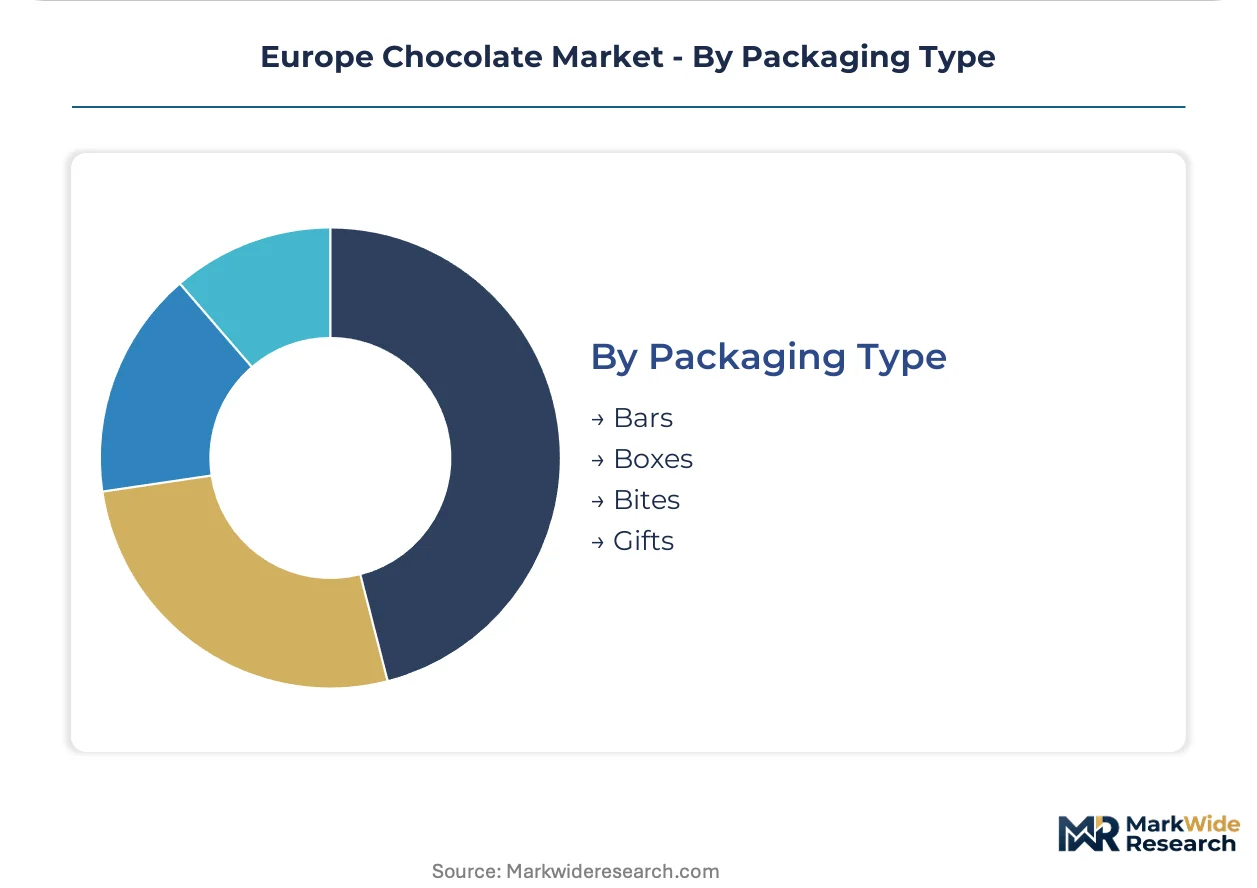
- Bars:Standard tablet formats from 50g to 200g anchor mass-market and premium shelf presence. Swiss and Belgian manufacturers leverage bar formats for origin-specific labeling and conching technology callouts.
- Boxes:Assortment packaging for gifting occasions carries higher margin realization but elevated packaging compliance costs under REACH chemical input evaluations.
- Bites:Single-serve miniature formats target portion control and on-the-go consumption with reduced per-unit origin documentation burden.
- Gifts:Seasonal and occasion-based premium packaging commands peak pricing in German and French Q4 retail cycles.
Bars constitute the core production volume; gift formats generate the steepest margin expansion during seasonal peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African cocoa bean origins anchor European processing capacity across Alpine and Low Country manufacturing corridors. EUDR traceability mandates reshape procurement patterns from farm-gate through finished couverture. Processing gravity concentrates where heritage conching expertise intersects with dairy supply proximity.
Germany
Retail subscription platforms and reduced-sugar dark chocolate formulations drive demand in Berlin and Munich metropolitan zones. EFSA clean-label approvals accelerate novel ingredient pipelines through German regulatory affairs channels. The Cologne-Düsseldorf corridor hosts industrial couverture capacity serving Central European bakery and dairy manufacturers.
Switzerland
Alpine dairy proximity and controlled-origin bean selection protocols sustain premium milk chocolate positioning. Swissmedic food safety coordination with EFSA streamlines novel formulation approvals for Geneva and Zurich-based processors. The Lake Geneva region concentrates conching technology R&D and master chocolatier training capacity.
Belgium
Flanders heritage manufacturing clusters export technical knowledge spillover into adjacent Dutch and French processing regions. EU Green Deal deforestation-free due diligence mandates compress margins for Antwerp-dependent small operators. Brussels anchors artisan bean-to-bar capacity alongside industrial scale couverture production for European food service channels.
France
Parisian premium gifting platforms and restaurant dessert applications prioritize origin storytelling and limited-edition releases. REACH chemical input restrictions on processing aids delay formulation innovations through extended ECHA evaluation timelines. The Île-de-France region concentrates direct-to-consumer logistics infrastructure for subscription chocolate assortments.
Italy
Hazelnut-chocolate segment demand and Southern European channel control priorities shape procurement from Turin-based processors. EUDR GPS polygon verification requirements strain traceability infrastructure for smallholder-dependent supply routes into Genoa port facilities. Piedmont clusters anchor gianduja heritage manufacturing and hazelnut roasting technical expertise.
Europe Chocolate Market Vendor Landscape
Global majors compete with regional champions across traceability infrastructure and conching technology differentiation. The vendor base stratifies into scaled integrated processors, heritage brand specialists, and industrial ingredient suppliers. Three archetypes dominate: bean-to-bar vertically integrated operators, premium R&D-intensive chocolatiers, and commodity-focused couverture suppliers. Competitive moves concentrate on EUDR compliance investments and precision fermentation partnerships for climate-resilient fat structuring.
Within the heritage premium tier, Lindt & Sprüngli and Barry Callebaut exemplify divergent strategic positions. Lindt & Sprüngli occupies a position emphasizing conching technology mastery and controlled-origin bean selection protocols. Barry Callebaut represents scaled vertical integration from West African sourcing through European couverture production. Ferrero Group sits within the hazelnut-chocolate specialization archetype, anchoring Southern European market presence through geographic segment focus.
| Leading Market Players |
|---|
| Mars |
| Lindt & Sprüngli |
| Nestle S.A. |
| Cargill Cocoa & Chocolate |
| The Hershey Company |
| Barry Callebaut |
| Ferrero Group |
| Olam Cocoa |
| Mondelez International |
| Others |
Supply Flow & Price Mechanics
Precision fermentation-derived cocoa butter alternatives are redrawing cost curves while concentrating R&D investment among scaled processors with captive biotech partnerships. This technological pivot simultaneously elevates capital barriers for artisan producers and compresses origin-dependency premiums that historically anchored Swiss and Belgian pricing power.
Pricing Analysis
Service bundling separates premium heritage positioning from commodity couverture tiers, with EUDR compliance documentation and origin verification now standard in premium contracts. Three-tier pricing structure across premium, standard, and economy levels tracks cocoa butter content ratios and conching intensity grades. Price differentiation hinges on bean-to-bar traceability depth and master chocolatier certification status. Cost compression in standard-tier milk chocolate is intensifying because supermarket private-label expansion absorbs EUDR overhead into thinner margins. Food manufacturers exhibit highest price sensitivity due to volume contracting leverage, while specialty shops and direct-to-consumer platforms absorb premium markups with minimal elasticity.
Supply Chain Analysis
Master chocolatier and tempering technician scarcity in the Lake Geneva region and Flanders plain constrains capacity expansion for ultra-premium segments. Cocoa bean supply concentrates in Ivory Coast, Ghana, and Ecuador, with West African origins dominating butter extraction yields. Processing draws from Ivorian mass, Ghanaian butter, and Ecuadorian flavor-grade beans as core inputs. Single-source vulnerability runs through Abidjan and Tema port logistics chokepoints during West African monsoon disruptions. Distribution runs through Antwerp bulk handling, Cologne industrial couverture channels, and Zurich premium finished goods corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal deforestation-free mandates have erected a compliance moat that rewards early traceability infrastructure investors while screening out undercapitalized processors. EUDR due diligence requirements now function as a barrier-to-entry filter that consolidates supplier relationships around scaled operators with dedicated regulatory affairs teams.
For Market Incumbents:Acquire GPS polygon mapping and mass-balance verification software platforms to harden EUDR compliance advantage before enforcement timelines activate. Secure backward integration into Ivorian and Ghanaian farm-gate sourcing through equity partnerships with cooperative federations. Lindt & Sprüngli and Barry Callebaut already anchor this positioning; mid-tier Swiss processors face displacement without equivalent traceability capex deployment.
For New Entrants and Emerging Players:Direct-to-consumer subscription platforms offer the most penetrable route for bypassing supermarket margin compression and EUDR documentation burdens that crush traditional retail economics. Target German metropolitan markets and Swiss expatriate channels where convenience-provenance overlap sustains recurring revenue capture. White-space exists in ruby chocolate variant specialization and precision fermentation-derived fat structuring partnerships that sidestep West African origin concentration.
For Investors and Strategic Acquirers:Exit pathways concentrate in trade sales to scaled integrated processors seeking EUDR-compliant origin assets and conching technology IP. Five-to-ten year viability favors operators with demonstrated mass-balance verification and Swissmedic-EFSA regulatory coordination capabilities. Acquisition target archetype: mid-scale Belgian or Swiss processors with installed tempering capacity and established Antwerp-Zurich distribution relationships. Watch for EUDR enforcement timeline acceleration as the critical inflection signal that compresses valuation multiples for non-compliant assets.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure Buildout | GPS polygon verification and mass-balance IT systems secure preferential supplier status under EU Green Deal enforcement. |
| Precision Fermentation Partnership | Microbial lipid platforms reduce Ivorian-Ghanaian origin dependency and climate-resilient supply chain exposure. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket margin structures in Berlin and Munich metropolitan zones. |
| Ruby Chocolate Variant Expansion | Anthocyanin-derived color technology opens fruit-forward positioning without synthetic dye REACH restrictions. |
| Heritage Brand Flagship Network | Brussels and Zurich flagship stores enable bean-to-bar provenance education and premium price realization. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe chocolate market assessment. Primary interviews with cocoa procurement directors, EUDR compliance officers, master chocolatiers, supermarket category buyers, and direct-to-consumer platform operators validated supply chain and pricing assumptions. Secondary sources included EFSA novel food approvals, ECHA REACH processing aid evaluations, EU Green Deal implementation guidance, and Swissmedic food safety coordination protocols. Bottom-up volume modeling across product types and distribution channels triangulated against top-down value estimates from customs and industry association aggregates.
Data-stream reconciliation across customs import volumes, processor production disclosures, and retail scanner data produced consistent trajectory estimates across the analysis window. Segmentation dimensions modeled include product type composition, end-user application, distribution channel structure, and packaging format economics. CAGRs were derived from fitted growth curves against historical volume-value relationships. Industry-specific forecast inputs incorporated cocoa butter price volatility assumptions and EUDR compliance cost pass-through elasticity.
The model holds under stable EUDR implementation timelines and continued West African origin supply continuity; deviation in enforcement acceleration or El Niño-driven crop failures would shift volume and value trajectories. Forecasts reflect assumptions about precision fermentation scale-up rates and consumer acceptance of bioengineered fat alternatives. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
US Dark Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
India Industrial Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
Ice Cream Coating Market
Confectionery
United States and Europe Macarons Market
Confectionery
Diet Candy Market
Confectionery
Italy Chocolate Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Chocolate Spread Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Premium Chocolate Market
Confectionery
Gummy Candy Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Low Calorie Hard Candy Market