
 Green Pea Grits Market | 2026-2036
Green Pea Grits Market Size, Share, and Industry Trends Forecast 2026-2036
Green Pea Grits Market Foresight
Single-serve and bulk-format dual packaging is recalibrating buyer choice across institutional and retail channels. Roquette Frères leverages its European protein extraction infrastructure to supply food-grade pea grits at scale. AGT Food and Ingredients anchors its position through backward integration into Canadian yellow pea farming. Best Cooking Pulses specializes in certified gluten-free milling protocols that differentiate its output for allergen-sensitive buyers.
Green pea grits consist of milled dehulled split peas, typically processed to particle sizes between 0.25 and 1.0 millimeters, serving as a high-protein, high-fiber ingredient in formulated foods and clean-label recipes. Organic product lines command premium shelf positioning as retailers respond to EU organic regulation enforcement and USDA National Organic Program compliance requirements. The snacks application category leads volume uptake, driven by extruded chip and puffed formulation trials, while breakfast foods represent the fastest-growing segment as cereal manufacturers replace refined corn and wheat bases with pulse-derived alternatives. Direct sales channels capture the strongest margin pools by eliminating distributor markups for large food manufacturers.
The FDA's Food Safety Modernization Act shapes processing standards through preventive controls for human food, while the USDA National Organic Program governs certification thresholds for organic-labeled pea grits. Health Canada and PMRA oversee maximum residue limits for agricultural inputs entering the Canadian supply chain. EFSA and EU organic regulations further constrain import eligibility for non-EU suppliers. Stakeholders must monitor evolving protein content labeling requirements and carbon footprint disclosure rules to maintain formulation and sourcing competitiveness.
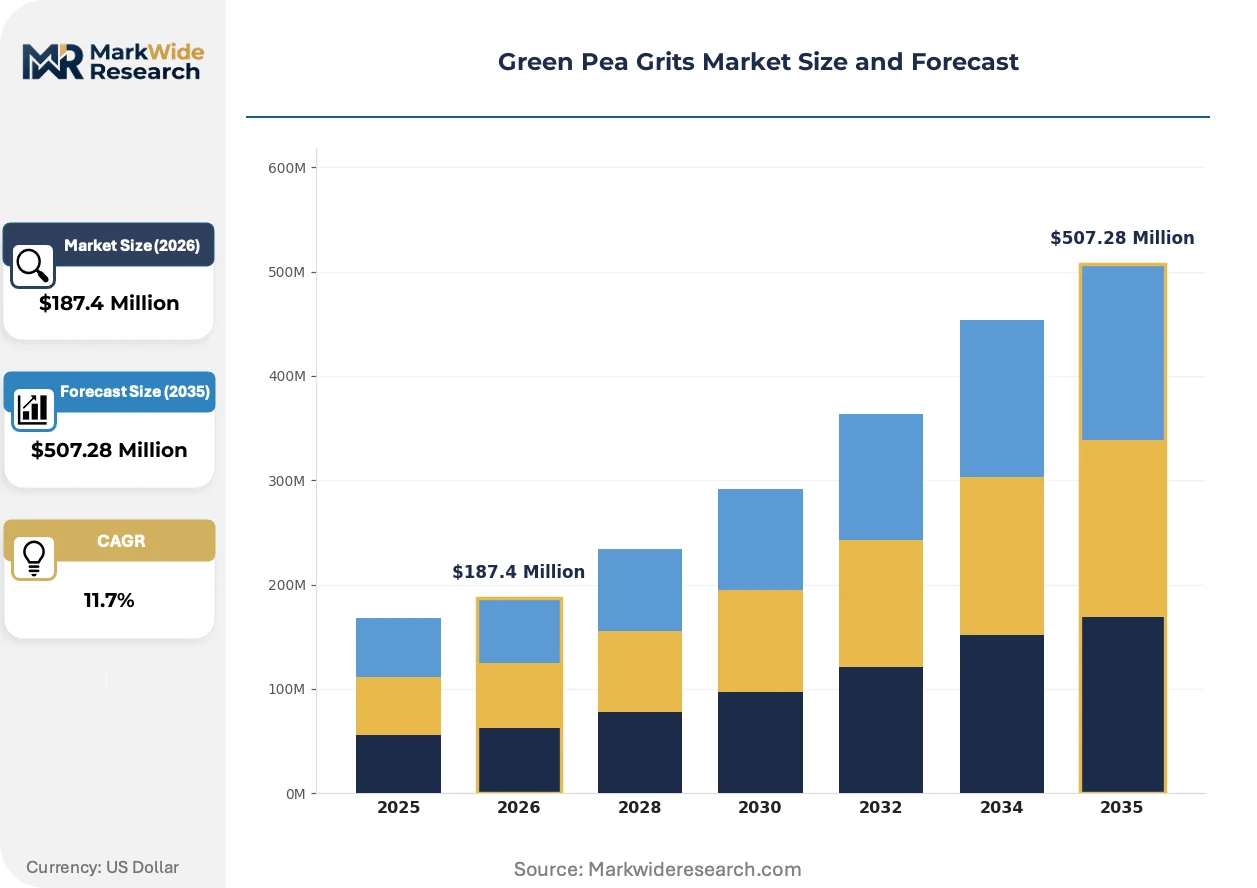
Market Dynamics
Clean-label procurement mandates from North American food manufacturers are compressing formulation timelines and forcing ingredient suppliers to certify gluten-free and organic grits at unprecedented speed. This pressure cascades through milling operations, farming contracts, and packaging specifications.
Growth Catalysts
- USDA National Organic Program:Certification thresholds for organic-labeled pea grits are unlocking premium shelf positioning at major retailers, expanding addressable volume for compliant suppliers.
- Extruded snack trials:Food manufacturers are validating pulse-derived bases in puffed and chip formulations, creating pull-through demand for consistent particle-size grits.
- EU Green Deal protein targets:Sustainable sourcing mandates are redirecting institutional procurement toward legume-based alternatives, favoring dehulled split pea derivatives.
Market Restraints
- Yellow pea price volatility:Input costs fluctuate with Canadian prairie harvest yields, squeezing margin predictability for non-integrated millers.
- EFSA import constraints:EU organic regulations limit eligibility for non-EU suppliers, fragmenting supply access for North American producers.
- Refined corn and wheat substitution:Established cereal bases retain cost advantages in price-sensitive breakfast formulations, slowing displacement timelines.
Strategic Opportunities
- Direct sales channel expansion:Large food manufacturers are eliminating distributor markups, creating margin capture potential for suppliers with captive milling capacity.
- Breakfast cereal pivot:Manufacturers replacing refined grain bases with pulse-derived alternatives represent underpenetrated volume for certified grit suppliers.
- Single-serve format innovation:Dual packaging configurations for institutional and retail channels are opening new buyer segments with differentiated service requirements.
Industry Challenges
- Preventive controls compliance:FDA Food Safety Modernization Act requirements demand HACCP-aligned process documentation that smaller millers struggle to resource.
- Carbon footprint disclosure readiness:Emerging scope-three reporting obligations require farm-level data integration that legacy supply chains lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Pea Grits Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Gluten-Free, Non-GMO End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Application: Snacks, Breakfast Foods, Soups, Sauces |
| Companies Covered | Roquette Frères, AGT Food and Ingredients, The Scoular Company, Ingredion Incorporated, ADM, Avena Foods, Martino Rossi SpA, Best Cooking Pulses, ANCHOR INGREDIENTS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Pea Grits Market Shifts & Advancements
Precision particle-size milling is compressing specification windows and enabling new texture profiles in extruded applications. This technical refinement is redrawing competitive boundaries between commodity suppliers and specialty millers.
Air-classification milling technology is rewriting the economics of fine-grit production. Snack manufacturers in the United States are adopting 0.25-0.5mm fractions at accelerated trial rates. The technology is compressing lead times for custom particle distributions and eroding the advantage of mass-commodity suppliers.
EU Green Deal sustainable protein targets are reshaping import eligibility criteria for non-European suppliers. The regulation is forcing North American exporters to document carbon intensity and farming practices at batch level. Organic-certified grit lines face the steepest compliance burden, with EFSA verification timelines extending sourcing cycles.
Buyer consolidation among private-label retailers is compressing supplier negotiation cycles and unbundling technical service from commodity supply. Large food manufacturers in the United States are centralizing pea grit procurement under direct contract models. This shift is marginalizing traditional distributor networks and rewarding millers with in-house formulation support capabilities.
Green Pea Grits Market Segmentation
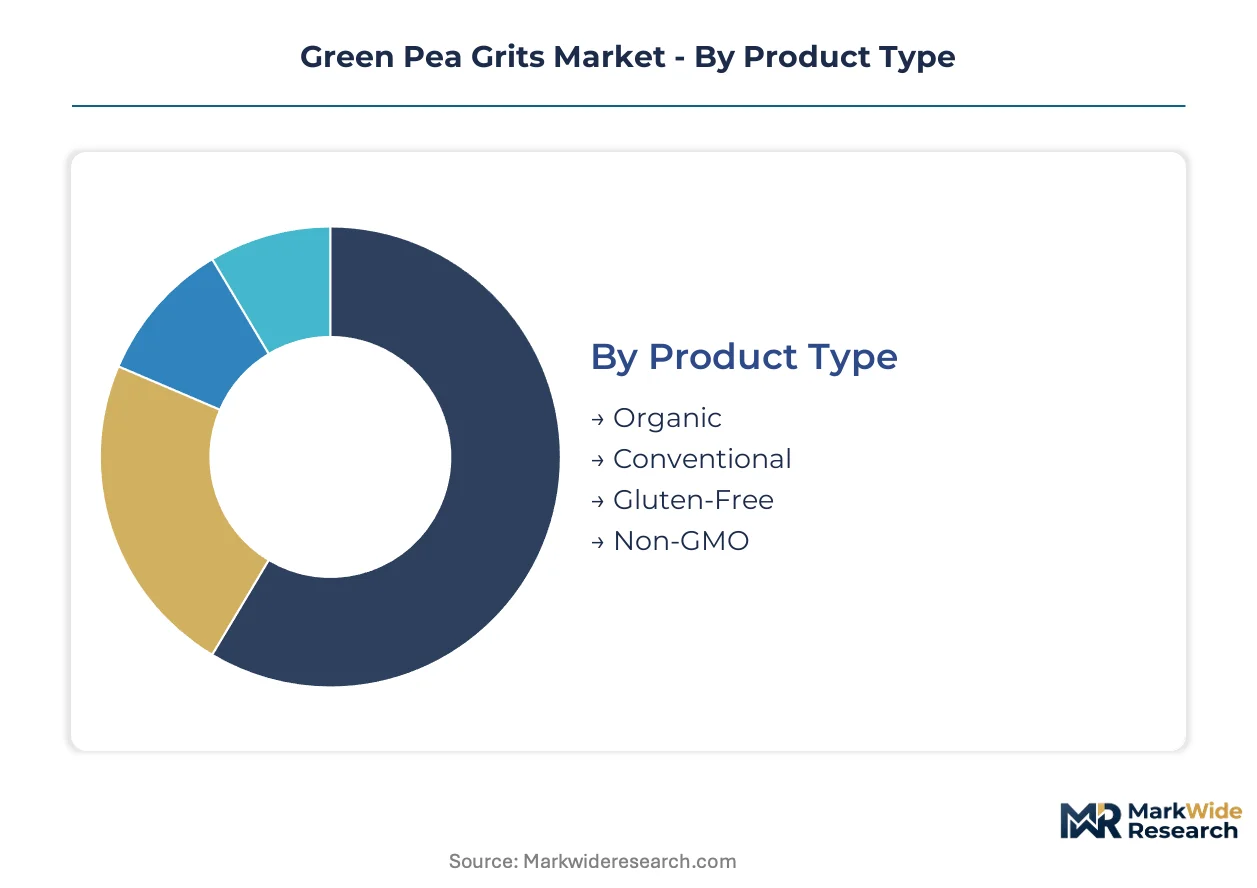
Green pea grits buyers upgrade formulations across multiple decision axes simultaneously. Product certification, end-use application, channel access, and particle-size specification each trigger distinct procurement workflows and margin structures.
Product Type:
Clean-label mandates force buyers to recertify ingredient bases on compressed timelines, with organic and gluten-free lines commanding premium positioning.
- Organic:Milled from certified dehulled split peas meeting USDA National Organic Program thresholds. Retailers in the United States reserve premium shelf placement for compliant suppliers, though EFSA verification extends sourcing cycles for EU-bound shipments.
- Gluten-Free:Processed under certified milling protocols with allergen-segregated production lines. Food manufacturers validate these grits in extruded snack trials where cross-contamination risks disqualify conventional alternatives.
- Conventional:Standard dehulled yellow pea grits serving price-sensitive formulations.
- Non-GMO:Identity-preserved supply chains documenting seed provenance and farming inputs.
Organic sits at the top of the volume ranking, with Gluten-Free climbing the fastest.
End User:
Procurement scale and technical service requirements diverge sharply across buyer categories, with direct-contract manufacturers capturing the strongest margin pools.
- Food Manufacturers:Large-scale buyers centralizing pea grit procurement under direct contract models. These buyers eliminate distributor markups and demand in-house formulation support from millers with captive production capacity.
- Retailers:Private-label consolidation compresses supplier negotiation cycles. Buyers unbundle technical service from commodity supply, rewarding millers who deliver consistent particle-size distributions at volume.
- Restaurants:Institutional procurement shifting toward single-serve and bulk-format dual packaging configurations.
- Home Cooks:Small-volume buyers accessing grits through specialty stores and online channels.
Food Manufacturers command the dominant share of procurement volume, with Retailers expanding most quickly.
Distribution Channel:
Channel selection determines margin capture and buyer relationship intensity, with direct sales models rewarding suppliers who integrate milling and technical support.
- Direct Sales:Large food manufacturers in the United States bypass distributor networks entirely. This channel captures the strongest margin pools by eliminating intermediary markups for suppliers with captive milling capacity.
- Online:E-commerce platforms serving home cooks and small-batch food producers with flexible order minimums.
- Supermarkets:Mass retail placement for conventional and organic product lines with standardized packaging.
- Specialty Stores:Curated retail channels emphasizing certified gluten-free and organic certifications.
Direct Sales leads channel profitability, with Online gaining share fastest among emerging buyer segments.
Application:
Texture requirements and formulation trials drive segment-specific demand for precise particle-size distributions.
- Snacks:Extruded chip and puffed formulations validate pulse-derived bases at accelerated trial rates. Snack manufacturers adopt 0.25-0.5mm fractions enabled by air-classification milling technology.
- Breakfast Foods:Cereal manufacturers displace refined corn and wheat bases with pulse-derived alternatives. This segment shows the steepest expansion trajectory as clean-label mandates intensify.
- Soups:Thickening applications requiring consistent hydration properties from milled pea derivatives.
- Sauces:Binding and emulsification functions in formulated food products.
Snacks holds the largest installed base, with Breakfast Foods on the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The green pea grits industry traces its commercial origins to Canadian prairie agriculture, where large-scale yellow pea cultivation supplied early milling operations for North American food manufacturers. This agricultural foundation established processing expertise that subsequently diffused to European and Asian markets as clean-label demand expanded.
United States
Extruded snack trials and breakfast cereal reformulation drive procurement volumes from food manufacturers. FDA Food Safety Modernization Act preventive controls shape processing compliance requirements for domestic millers. Minneapolis-St. Paul anchors the Upper Midwest processing corridor, where ingredient suppliers co-locate with major cereal and snack production facilities.
Canada
Prairie yellow pea harvests supply raw material for integrated millers with backward control over farming inputs. Health Canada and PMRA residue limit enforcement constrains agricultural chemical use across Saskatchewan and Alberta growing regions. Port of Vancouver serves as the primary export gateway for Asian-bound certified organic shipments.
Germany
EU Green Deal sustainable protein procurement mandates redirect institutional foodservice demand toward legume-derived ingredients. EFSA organic verification protocols extend import sourcing cycles for non-European suppliers. Hamburg's port infrastructure handles bulk pulse processing for Central European distribution networks.
France
Roquette Frères leverages its Lestrem protein extraction complex to supply food-grade pea grits at continental scale. EU organic regulation enforcement reserves premium retail positioning for certified suppliers. The Hauts-de-France region concentrates pea protein processing capacity near established agricultural supply chains.
China
Domestic snack manufacturers trial pulse-derived bases in puffed and extruded formulations for regional markets. SAMR food safety standards govern import eligibility and domestic production licensing. Yangtze River Delta processing clusters experiment with air-classification milling technology for fine-grit specifications.
Green Pea Grits Market Competitive Landscape
The competitive structure tilts toward integrated agricultural processors with captive supply chains and specialty millers with certified production protocols. Tiered supplier concentration separates mass-commodity volume players from certified organic and gluten-free specialists. Strategic archetypes include vertically integrated crop-to-ingredient operators, toll-milling service providers, and certified-allergen-free specialty suppliers. Dominant competitive moves encompass direct-contract bypass of distributor networks and precision particle-size milling capability investments.
Among European integrated processors, Roquette Frères exemplifies the crop-to-ingredient archetype through its established protein extraction infrastructure. AGT Food and Ingredients occupies a position within the North American integrated tier, representing backward integration into prairie pea farming. Best Cooking Pulses anchors the certified-specialist segment, exemplifying allergen-segregated milling protocols for sensitive formulation buyers.
| Leading Market Players |
|---|
| Roquette Frères |
| AGT Food and Ingredients |
| The Scoular Company |
| Ingredion Incorporated |
| ADM |
| Avena Foods |
| Martino Rossi SpA |
| Best Cooking Pulses |
| ANCHOR INGREDIENTS |
| Others |
Supply & Pricing Matrix
Canadian yellow pea harvest yields feed directly into three-tier pricing stratification across organic, gluten-free, and conventional grit lines. Prairie weather volatility compresses margin predictability for non-integrated millers while rewarding suppliers with backward integration into Saskatchewan and Alberta farming operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic grits from conventional alternatives. Price differentiation rests on USDA National Organic Program compliance and gluten-free certification status. Cost compression in the conventional tier is intensifying because refined corn and wheat substitutes retain cost advantages. Food manufacturers exhibit the highest price sensitivity, while specialty retailers absorbing certified lines show greater tolerance for premium positioning.
Supply Chain Analysis
Refurbishment and reconditioning flows for milling equipment extend asset lifecycles across Canadian prairie processing facilities. Raw material supply concentrates in Canada, the United States, and France, drawing from yellow pea cultivation, protein extraction infrastructure, and air-classification milling technology inputs. Single-source vulnerability runs through Saskatchewan harvest concentration. Distribution runs through direct-contract channels for large manufacturers and distributor networks for smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green pea grits function as a stable compounder anchored by clean-label procurement mandates that institutionalize pulse-derived ingredient adoption across formulated foods.
For Market Incumbents: Deepen captive milling capacity in the Upper Midwest corridor to defend against air-classification technology disruption from precision particle-size specialists. Expand organic certification coverage to capture EFSA-compliant export volumes before EU Green Deal enforcement tightens. Prioritize direct sales channel control to eliminate distributor margin leakage. For New Entrants and Emerging Players: Enter via breakfast cereal reformulation partnerships where refined grain displacement creates white-space demand for certified grit suppliers. Target institutional foodservice procurement in Germany and France where EU Green Deal protein targets redirect sourcing toward legume alternatives. Lead with single-serve packaging innovation to differentiate from commodity bulk suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA Food Safety Modernization Act compliance costs marginalize smaller millers lacking HACCP-aligned process documentation. The five-to-ten year viability window favors integrated crop-to-ingredient operators with carbon footprint disclosure readiness. Watch for scope-three reporting mandate acceleration as the inflection signal for supply chain valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Farming | AGT Food and Ingredients anchors margin control through Saskatchewan yellow pea cultivation. |
| Precision Particle-Size Milling Investment | Air-classification technology enables 0.25-0.5mm fraction supply for extruded snack trials. |
| Organic Certification Expansion | USDA National Organic Program compliance unlocks premium retail placement and EU export eligibility. |
| Direct Sales Channel Development | Bypassing distributor networks captures strongest margin pools from large food manufacturers. |
| Carbon Footprint Disclosure Program | Farm-level data integration addresses emerging scope-three reporting obligations for institutional buyers. |
Research Methodology
Multiple input streams — primary interviews with milling operations directors and food manufacturer procurement leads, secondary validation through USDA organic certification databases and FDA preventive controls guidance, customs trade data for pea grit shipments — were reconciled through bottom-up volume triangulation against top-down category spend analysis.
Historical volume trajectories were cross-referenced against expert panel assessments to construct projections across the analysis window. Segmentation dimensions modeled include product certification tier, end-use application, distribution channel structure, and particle-size specification grade. CAGRs were derived from fitted growth curves incorporating extruded snack trial adoption rates and breakfast cereal reformulation timelines.
The model holds under stable clean-label procurement mandate enforcement; deviation in EU organic regulation stringency or Canadian prairie harvest yields would shift volume and value outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Spain Rice Market
Grains
Lentil Market
Grains
Sorghum Market
Grains
Rice Flour Market
Grains
Millet Flour Market
Grains
North America Wheat Flour Market
Grains
Brazil Maize Market
Grains
Barley Grass Market
Grains
Bangladesh Rice Market
Grains
Millets Market
Grains
Soy Grits Market
Grains
China Rice Market
Grains
North America Wheat Market
Grains
Organic Oats Market
Grains
Egypt Rice Market
Grains
China Wheat Protein Market