
 UAV Payload Market | 2026-2036
UAV Payload Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Payload Market Outlook
Defense procurement concentration is pivoting toward sovereign unmanned systems programs as allied nations reduce dependency on imported platforms. RTX leverages its electro-optical and signals intelligence portfolio to anchor prime contractor relationships with the U.S. Department of Defense. Lockheed Martin Corporation sustains integrated mission systems development across high-altitude long-endurance programs. Elbit Systems Ltd. dominates tactical UAV payload exports to European and Asia-Pacific militaries seeking non-U.S. supply sources.
UAV payload denotes the mission-specific equipment carried by unmanned aerial vehicles, encompassing sensor suites, communications relay hardware, and cargo delivery apparatus typically constrained by strict size-weight-and-power budgets measured in watts and kilograms; these systems perform intelligence gathering, precision targeting, infrastructure survey, or logistical distribution functions remotely without onboard human operators. Camera systems and electro-optical technology occupy mature margin pools where volume manufacturing and supply chain scale protect incumbent positions. Sensors and LiDAR segments attract accelerated investment as autonomous navigation and three-dimensional mapping applications expand across commercial and research end users.
The Federal Aviation Administration governs commercial UAV payload certification and beyond-visual-line-of-sight waivers in the United States, while the European Union Aviation Safety Agency enforces design standards under the UAS regulatory framework across EU member states. Military payload interoperability requirements from NATO standardization agreements further constrain supplier qualification and market access for non-aligned manufacturers. Stakeholders must monitor evolving frequency allocation rulings and export control list revisions that could abruptly resegment addressable markets between sovereign and foreign suppliers.
Market Dynamics
Miniaturization of synthetic aperture radar and hyperspectral imaging systems is compressing size-weight-and-power constraints across fixed-wing and rotary-wing unmanned fleets, forcing payload suppliers to deliver multi-sensor integration within shrinking wattage and kilogram budgets.
Growth Catalysts
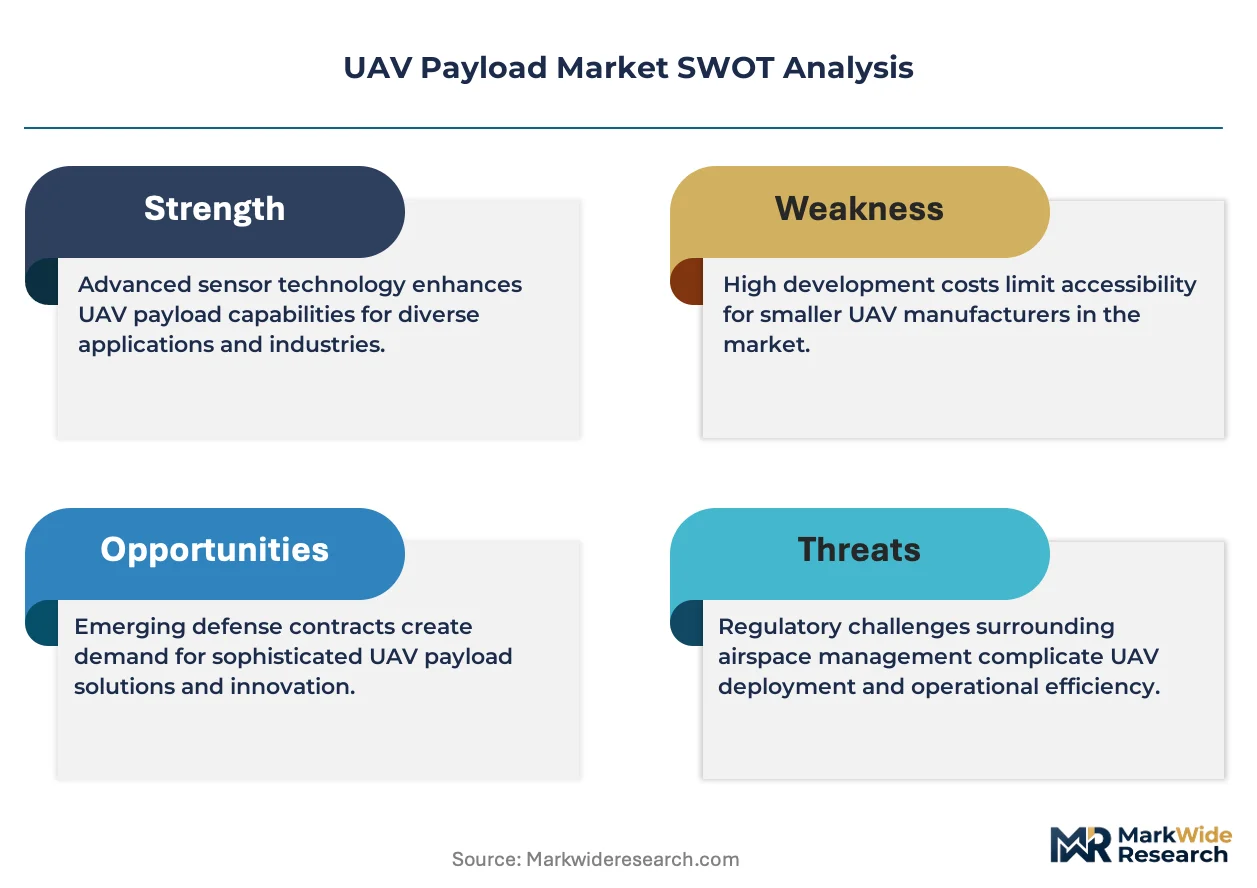
- NATO standardization agreements:Military payload interoperability requirements from these agreements are mandating common interface standards across allied unmanned fleets, creating pull-through demand for certified multi-sensor suites.
- Autonomous navigation:Commercial end users in infrastructure survey and precision agriculture are accelerating LiDAR payload procurement for three-dimensional mapping applications without human piloting.
- Turkey:Domestic industrial base expansion for sovereign military operators is generating captive demand for electro-optical and signals intelligence payloads that bypass foreign supplier dependency.
Market Restraints
- Export control list revisions:Abrupt resegmentation of addressable markets between sovereign and foreign suppliers is constraining supplier qualification and market access for non-aligned manufacturers.
- Frequency allocation rulings:Evolving spectrum governance from the Federal Aviation Administration and European Union Aviation Safety Agency is creating regulatory friction for beyond-visual-line-of-sight communications relay hardware.
- Gallium nitride component supply:Concentration of high-frequency power amplifier manufacturing in limited geographies is exposing payload suppliers to input cost volatility and single-source risk.
Strategic Opportunities
- Israel:Tactical UAV payload exports to European and Asia-Pacific militaries seeking non-U.S. supply sources represent underpenetrated white space for sovereign industrial bases.
- Hyperspectral-cognitive radio convergence:Integration of spectral imaging with adaptive spectrum management is opening payload architectures that compress multiple intelligence functions into single airborne nodes.
- U.S. Department of Defense prime contractor relationships:Electro-optical portfolio anchoring through established defense procurement channels offers pathway to integrated mission systems development across high-altitude long-endurance programs.
Industry Challenges
- DO-178C and DO-254 certification timelines:Software and hardware airworthiness compliance for military payload software is extending development cycles and compressing competitive windows for new entrants.
- Multi-sensor thermal management:Integration complexity with legacy platform cooling architectures is forcing payload redesigns that absorb unplanned engineering hours and mass allocation.
- Signals intelligence algorithm talent:Scarcity of cleared personnel with machine learning and spectral analysis expertise is constraining development velocity for next-generation electronic warfare payloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Payload Market |
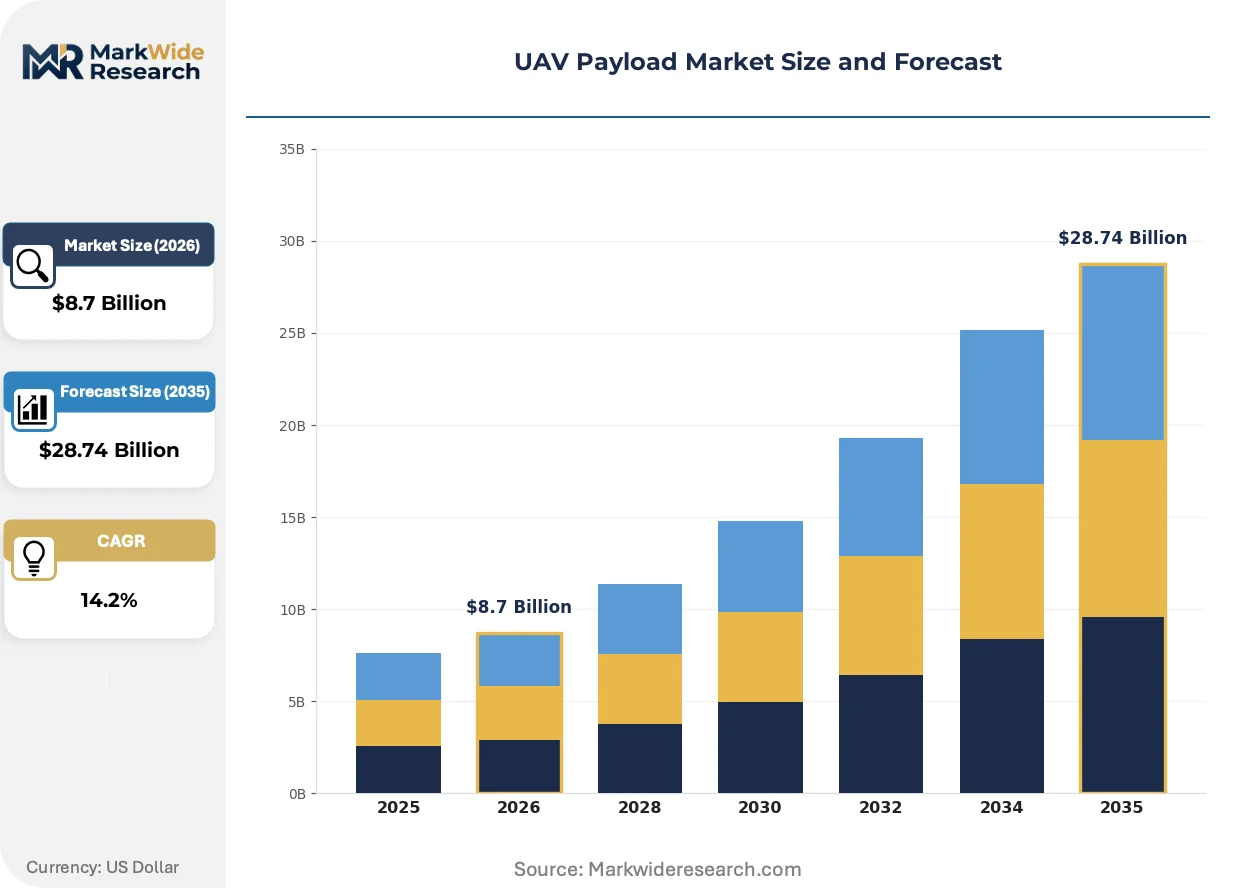
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Communication Equipments, Sensors, Delivery Mechanisms Industry Vertical: Agriculture, Defense, Infrastructure, Environmental Monitoring Technology: Electro-Optical, LiDAR, Radar, Hyperspectral End User: Government, Commercial, Research Organizations, Emergency Services |
| Companies Covered | RTX, Northrop Grumman Corporation, Lockheed Martin Corporation, Teledyne Technologies Incorporated, Israel Aerospace Industries Ltd., L3Harris Technologies Inc, Elbit Systems Ltd., General Atomics Aeronautical Systems, AeroVironment, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Payload Market Strategic Shifts
Active reshaping of the UAV payload market stems from convergence between sovereign defense procurement autonomy and commercial autonomy-enabling sensor proliferation, compressing development cycles across dual-use technology trajectories.
Synthetic aperture radar miniaturization is expanding into tactical unmanned platforms previously limited by payload capacity constraints. Defense procurement agencies across NATO member states are adopting these systems for all-weather intelligence gathering at previously unattainable endurance levels. The technology is expanding into missions formerly reserved for manned reconnaissance aircraft, compressing the cost-per-intelligence-hour economics of airborne surveillance.
The European Union Aviation Safety Agency UAS regulatory framework is enforcing design standards that mandate specific failure modes and redundancy architectures for commercial payload certification. Industrial consequence includes forced redesign of single-string sensor systems into fault-tolerant configurations that add mass and power draw. Small commercial survey operators in Germany and France are responding by consolidating fleet purchases around pre-certified platform-payload bundles rather than mixing components.
Buyer concentration among sovereign military operators is compressing vendor negotiation cycles and unbundling traditional after-sales service packages. Prime contractors are displacing component suppliers from direct end-user relationships, capturing margin through integrated logistics support contracts. This pattern is most visible in United States Department of Defense procurement, where electro-optical payload specifications now flow through systems integrators rather than direct sensor vendor engagement.
UAV Payload Market Segmentation
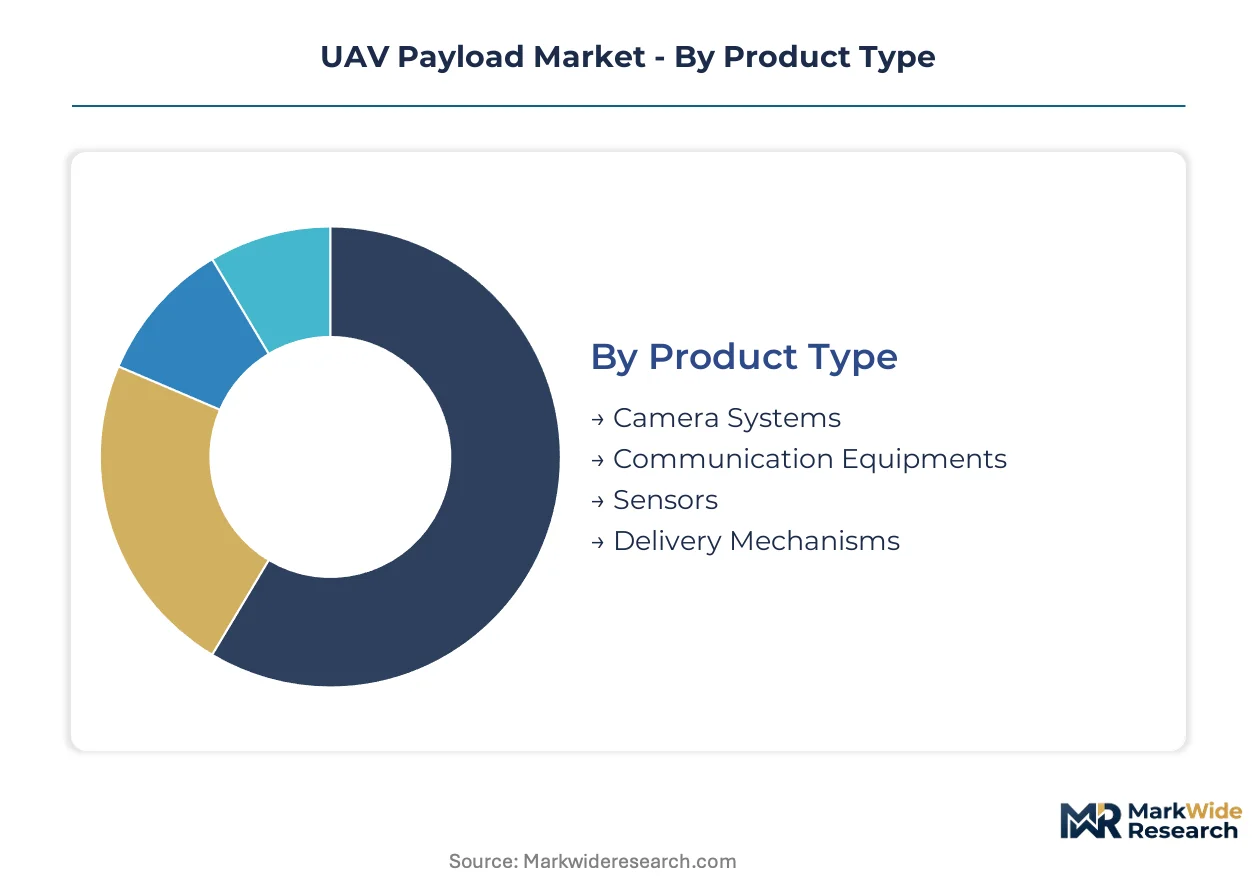
UAV payload segmentation reveals divergent margin structures across mature electro-optical hardware and emerging autonomous sensor suites. Procurement patterns split between volume-driven commercial operators optimizing per-unit economics and defense integrators prioritizing multi-sensor interoperability over cost minimization.
Product Type:
Volume concentrates in commoditized imaging hardware while premium capture shifts toward integrated multi-function payloads that compress size-weight-and-power budgets.
- Camera Systems:Electro-optical and infrared imaging modules dominate unit shipments across commercial survey and tactical military applications. Defense procurement agencies in the United States and Israel specify hardened variants with gyro-stabilized gimbals for high-altitude long-endurance platforms, though margin compression from Chinese manufacturing is forcing Western suppliers toward software-defined image processing differentiation.
- Sensors:Synthetic aperture radar, signals intelligence receivers, and chemical detection arrays command the highest payload values per kilogram. NATO standardization agreements for interoperability are mandating common interface standards that favor suppliers with existing prime contractor relationships, particularly for beyond-visual-line-ofsight missions requiring all-weather capability.
- Communication Equipments:Beyond-visual-line-of-sight relay hardware and tactical data links face regulatory friction from evolving FAA and EASA frequency allocation rulings.
- Delivery Mechanisms:Cargo release systems and precision airdrop apparatus remain nascent outside military logistics trials and isolated medical supply networks.
Today's leader: Sensors. Tomorrow's challenger: Communication Equipments.
Industry Vertical:
Defense procurement anchors revenue concentration while commercial verticals expand addressable volume through autonomous navigation enablement.
- Defense:Sovereign military operators in Turkey, Israel, and the United States drive specification complexity through multi-sensor integration demands for fixed-wing and rotary-wing unmanned fleets. Miniaturization of synthetic aperture radar and hyperspectral imaging systems is compressing development cycles as procurement agencies seek manned-aircraft intelligence capabilities at unmanned cost structures.
- Agriculture:Precision farming operators in France and Germany are consolidating fleet purchases around pre-certified platform-payload bundles under EASA UAS regulatory framework mandates. LiDAR and multispectral camera procurement is climbing fastest as autonomous crop monitoring displaces piloted aerial survey.
- Infrastructure:Linear asset inspection for pipelines and power transmission corridors generates recurring payload demand from European utility operators.
- Environmental Monitoring:Research institutions and government agencies deploy hyperspectral payloads for carbon sequestration verification and wildfire early detection.
Defense commands current value capture. Agriculture represents the steepest expansion trajectory as regulatory clarity enables beyond-visual-line-of-sight operations.
Technology:
Maturity gradients separate established electro-optical margins from emerging spectral and radar technologies requiring cleared algorithm talent.
- Electro-Optical:Visible and infrared imaging systems occupy mature margin pools where RTX and Lockheed Martin sustain positions through volume manufacturing scale and supply chain integration. Camera payload specifications increasingly flow through systems integrators rather than direct sensor vendor engagement, compressing component supplier pricing power.
- Hyperspectral:Spectral imaging arrays that capture contiguous wavelength bands are gaining share fastest in mineral exploration and agricultural stress detection applications. Integration with cognitive radio architectures is opening payload designs that compress multiple intelligence functions into single airborne nodes, though DO-178C certification timelines extend development cycles.
- LiDAR:Three-dimensional mapping payloads face thermal management complexity when integrated with legacy platform cooling architectures.
- Radar:Miniaturized synthetic aperture systems are expanding into tactical platforms previously limited by payload capacity constraints.
Electro-Optical maintains installed base dominance. Hyperspectral is climbing the fastest as dual-use defense-commercial applications proliferate.
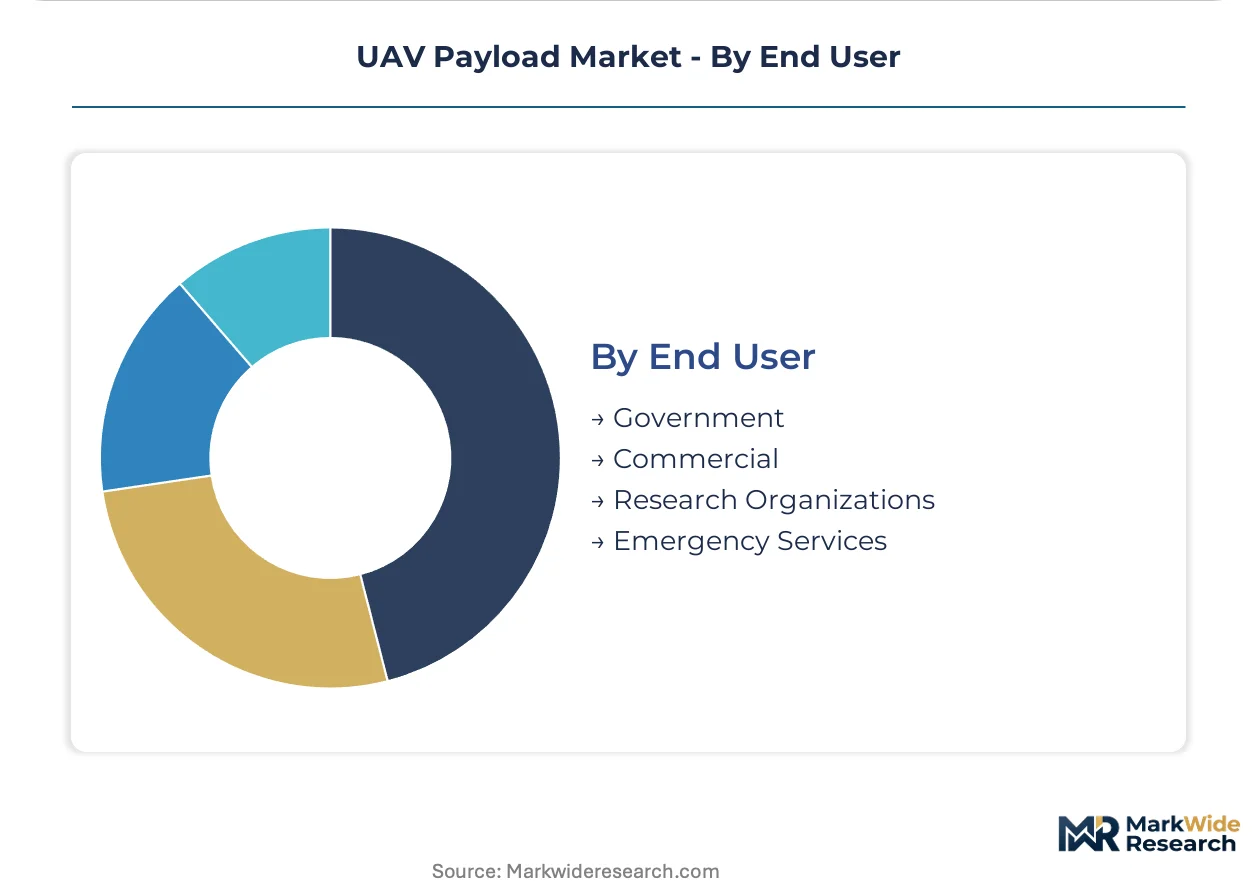
End User:
Government concentration is displacing direct supplier relationships while commercial fragmentation forces platform-payload bundling strategies.
- Government:Defense procurement agencies and homeland security operators specify mission-critical payloads through integrated logistics support contracts that capture after-sales service margin for prime contractors. Elbit Systems and RTX leverage electro-optical and signals intelligence portfolios to anchor these relationships, particularly in the United States and Israel where sovereign industrial base requirements constrain foreign supplier access.
- Commercial:Survey operators, agricultural enterprises, and infrastructure managers are consolidating purchases around pre-certified bundles under FAA Part 107 and EASA UAS framework compliance pressures. Single-string sensor redesigns into fault-tolerant configurations add mass and power draw that disadvantage standalone payload vendors.
- Emergency Services:Fire departments and search-and-rescue units generate episodic demand for thermal imaging and delivery mechanism payloads.
- Research Organizations:Academic and institutional users drive experimental hyperspectral and radar applications with limited production scale.
Government dominates revenue concentration. Commercial end users are expanding most quickly as certification pathways stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics talent clusters in the United States, Israel, and Turkey anchor sovereign payload development, while commercial sensor manufacturing concentrates in Germany and Japan where precision optics supply chains integrate with automotive LiDAR ecosystems.
United States
The Department of Defense drives multi-sensor integration demand for high-altitude long-endurance platforms through prime contractor relationships. FAA Part 107 and beyond-visual-line-of-sight waiver frameworks govern commercial certification pathways. Greater Boston and Southern California host electro-optical engineering clusters where RTX and Lockheed Martin anchor integrated mission systems development.
Israel
Domestic military procurement and tactical UAV export programs generate concentrated demand for signals intelligence and electro-optical payloads. The Israeli Ministry of Defense imposes sovereign industrial base requirements that constrain foreign supplier access. Elbit Systems and Israel Aerospace Industries anchor development in the Haifa-Tel Aviv corridor, supplying European and Asia-Pacific militaries seeking non-U.S. sources.
Turkey
Sovereign unmanned systems programs are expanding fixed-wing and rotary-wing fleets with captive payload production. Defense procurement agencies prioritize domestic electro-optical and synthetic aperture radar manufacturing under industrial autonomy mandates. Ankara and Istanbul host emerging sensor integration facilities that bypass foreign supplier dependency for military operators.
Germany
Precision agriculture and infrastructure survey operators consolidate fleet purchases around pre-certified platform-payload bundles. EASA UAS regulatory framework mandates fault-tolerant sensor configurations that add mass and power draw. Bavaria and Baden-Württemberg concentrate LiDAR and multispectral camera manufacturing, integrating automotive perception technology into commercial UAV applications.
Japan
METI-funded autonomous navigation programs accelerate three-dimensional mapping payload procurement for disaster response and industrial inspection. JIS standards and radio equipment certification procedures create compliance barriers for foreign hardware suppliers. Tokyo-Osaka industrial corridors host precision optics manufacturers transitioning camera module expertise from consumer electronics into UAV sensor markets.
UAV Payload Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where prime contractors capture integrated logistics support margins. Defense procurement concentration favors suppliers with established electro-optical and signals intelligence portfolios. Three archetypes dominate: systems integrators bundling multi-sensor suites, component specialists delivering size-weight-and-power-optimized modules, and sovereign industrial base champions serving captive domestic demand. Competitive moves center on prime contractor relationship anchoring and multi-sensor thermal management capability acquisition.
Within the systems integrator tier, RTX, Lockheed Martin Corporation, and Elbit Systems Ltd. exemplify archetypes spanning U.S. defense prime positioning, high-altitude mission systems integration, and tactical export specialization respectively. RTX occupies a position anchored to Department of Defense electro-optical procurement channels. Lockheed Martin Corporation represents integrated mission systems development across endurance-focused programs. Elbit Systems Ltd. sits within the sovereign export specialist category, serving European and Asia-Pacific militaries through non-U.S. supply relationships.
| Leading Market Players |
|---|
| RTX |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Teledyne Technologies Incorporated |
| Israel Aerospace Industries Ltd. |
| L3Harris Technologies Inc |
| Elbit Systems Ltd. |
| General Atomics Aeronautical Systems |
| AeroVironment, Inc. |
| Others |
Value Chain & Pricing Dynamics
NATO standardization agreements for multi-sensor interoperability are forcing payload suppliers to absorb certification costs and redesign single-string systems into fault-tolerant configurations, compressing margins and triggering consolidation around pre-certified platform-payload bundles.
Pricing Analysis
Capacity additions in China's precision optics manufacturing are reshaping price floors for electro-optical camera modules, forcing Western suppliers toward software-defined differentiation. Three-tier pricing structure across hardened military-grade, commercial-certified, and uncertified economy levels separates buyers by application criticality and regulatory exposure. Pricing pressure stems from gallium nitride component supply concentration and Chinese volume manufacturing entry. Commercial survey operators exhibit highest price sensitivity, while defense integrators prioritize interoperability over unit cost.
Supply Chain Analysis
DO-178C and DO-254 certification requirements gate supplier qualification, extending development timelines and concentrating tier-one relationships around established prime contractors. Manufacturing concentrates in the United States, Israel, and Turkey for sovereign defense payloads, with precision optics sourcing from Germany and Japan. Critical dependencies include gallium nitride high-frequency power amplifiers, synthetic aperture radar subcomponents, and cleared algorithm talent pools. Single-source vulnerability in gallium nitride fabrication exposes suppliers to input cost volatility. Distribution runs through systems integrators capturing integrated logistics support margins, displacing direct component vendor engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Miniaturization of synthetic aperture radar and hyperspectral imaging systems is compressing size-weight-and-power constraints, enabling premium-tier payload pricing for multi-sensor integration while commoditizing standalone electro-optical hardware.
For Market Incumbents: Acquire thermal management engineering capabilities to address multi-sensor integration complexity with legacy platform cooling architectures. Anchor prime contractor relationships through electro-optical portfolio bundling with signals intelligence offerings. Chinese manufacturing entry in camera modules threatens margin pools; respond with software-defined image processing differentiation and DO-178C certification investment to maintain defense channel access. For New Entrants and Emerging Players: Begin with tactical UAV payload exports to European and Asia-Pacific militaries seeking non-U.S. supply sources, where sovereign industrial base requirements constrain incumbent access. Target commercial agriculture operators in France and Germany consolidating fleet purchases around pre-certified platform-payload bundles under EASA mandates. Go-to-market through precision agriculture OEM partnerships rather than direct sensor sales. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists delivering size-weight-and-power-optimized modules for autonomous navigation applications. Five-to-ten year viability favors suppliers with cleared personnel pools and existing NATO standardization agreement compliance. Watch frequency allocation rulings from FAA and EASA as inflection indicator for beyond-visual-line-of-sight communications relay hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Thermal Management Acquisition | Addresses integration complexity with legacy platform cooling architectures that force unplanned engineering hours. |
| Prime Contractor Relationship Anchoring | Captures integrated logistics support margins through electro-optical and signals intelligence portfolio bundling. |
| Hyperspectral-Cognitive Radio Convergence | Opens payload architectures compressing multiple intelligence functions into single airborne nodes for NATO interoperability. |
| Pre-Certified Platform-Payload Bundling | Responds to EASA UAS regulatory framework mandates forcing fault-tolerant sensor redesigns in Germany and France. |
| Cleared Algorithm Talent Recruitment | Resolves scarcity constraining development velocity for next-generation electronic warfare payloads in U.S. and Israeli clusters. |
Study Parameters
Direct dialogue with payload engineering directors, defense procurement officers at NATO member agencies, commercial UAV fleet operators, and precision agriculture enterprise technology buyers grounded qualitative findings. Secondary validation drew from FAA Part 107 waiver databases, EASA UAS regulatory filings, NATO standardization agreement documentation, and customs records for electro-optical component trade flows. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Bottom-up modeling built product-type and industry-vertical segments across the projection horizon, with technology and end-user dimensions layered for cross-tabulation. CAGRs derived from historical procurement pattern analysis and forward-looking sovereign unmanned systems program announcements. Synthetic aperture radar miniaturization curves and autonomous navigation adoption rates in precision agriculture served as industry-specific forecast inputs.
Caveats apply where export control list revisions or abrupt frequency allocation rulings could materially shift the outlook between sovereign and foreign supplier addressable markets. Forecasts reflect assumptions regarding NATO standardization agreement implementation timelines and gallium nitride component supply stability. A model refresh is warranted upon material change in EASA UAS regulatory enforcement intensity or U.S. Department of Defense beyond-visual-line-of-sight waiver granting velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Asia Pacific Commercial Drone Market
UAV
Solar-Powered UAV Market
UAV
Industrial Drones Market
UAV
Commercial UAV Market
UAV
UAV Payload and Subsystems Market
UAV
Global VTOL UAV Market
UAV
Europe Drone Services Market
UAV
GCC Drone Pilot Training Market
UAV
Combat Drone Market
UAV
Global Drone Sensor Market
UAV
Small Drone Market
UAV
Global Aerial Imaging Market
UAV
Global Multirotor UAV Market
UAV
UAV Navigation Systems Market
UAV
Drone Motors Market
UAV
Enterprise Drone Management Solutions Market