
 Asia Pacific Commercial Drone Market | 2026-2036
Asia Pacific Commercial Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Commercial Drone Market Insights
The capability gap between vertically integrated manufacturers and component-assemblers is unwinding as flight-control software becomes the decisive cost center. SZ DJI Technology Co., Ltd. leverages its Shenzhen supply base to dominate consumer-to-prosumer transitions. Chengdu JOUAV Automation Tech Co., Ltd. anchors its position in long-endurance fixed-wing systems for geospatial clients. Guangzhou EHang Intelligent Technology Co. Ltd. competes through autonomous passenger-grade certification pathways.
Asia Pacific commercial drones are uncrewed aerial vehicles with maximum takeoff weights from under one kilogram to above twenty-five kilograms, powered by lithium-polymer or hydrogen fuel-cell propulsion, and operated via ground-control stations with real-time kinematic GPS correction. Their primary commercial purpose spans precision payload delivery, orthomosaic mapping, and infrastructure thermography across civilian airspace. Multi-rotor platforms occupy the volume lead due to vertical-takeoff flexibility in dense urban and uneven terrain environments. Fixed-wing systems sustain higher margins in corridor-mapping and maritime-patrol contracts requiring extended loiter times. Hybrid configurations are emerging as the fastest-growing product type as operators seek to consolidate fleet diversity.
China's MIIT enforces radio-transmission and airworthiness standards that filter out uncertified hardware, while Japan's METI designates specific low-altitude corridors for logistics trials. Australia's Civil Aviation Safety Authority mandates remote pilot licensing tiers that shape operator business-model scalability. Stakeholders must monitor how India's Directorate General of Civil Aviation relaxes beyond-visual-line-of-sight restrictions for agricultural and emergency-response fleets, as this regulatory pivot will determine which technology suppliers capture the subcontinent's operator procurement cycles.
Market Dynamics
Flight-control software licensing costs now exceed airframe manufacturing expenses, compressing margins for component-assemblers while rewarding vertically integrated developers who control sensor fusion algorithms and real-time kinematic correction stacks.
Growth Catalysts
- Japan's METI corridor designations:Low-altitude flight paths for logistics trials in Osaka and Tokyo metropolitan zones accelerate beyond-visual-line-of-sight mission authorization for delivery operators.
- Precision agriculture spraying:Southeast Asian palm plantation and rice paddy operators deploy multi-rotor fleets for fungicide application, replacing manual backpack sprayers with GPS-guided autonomous systems.
- Hydrogen fuel-cell propulsion:Extended loiter times for maritime patrol and corridor-mapping contracts in Australian mining regions enable fixed-wing platforms to capture higher-margin surveillance engagements.
Market Restraints
- Lithium-polymer supply concentration:Battery cell production clusters in China's Guangdong and Jiangsu provinces create input cost volatility and single-source dependency for regional assemblers.
- MIIT radio-transmission certification:China's Ministry of Industry and Information Technology hardware approval timelines extend six to nine months, filtering uncertified radio modules from commercial deployment.
- Pilot licensing tier requirements:Australia's Civil Aviation Safety Authority remote operator certification costs scale with mission complexity, constraining small-fleet agricultural contractors from expanding service coverage.
Strategic Opportunities
- India's DGCA BVLOS relaxation:The Directorate General of Civil Aviation's pending agricultural and emergency-response exemptions will unlock subcontinent-scale procurement cycles for compliant platform suppliers.
- Hybrid configuration demand:Operators in Indonesia's archipelago terrain seek vertical-takeoff fixed-wing endurance, consolidating fleet diversity into single-airframe solutions.
- Geospatial subscription models:Mining and infrastructure clients in Western Australia shift from capital purchase to per-survey data licensing, opening recurring revenue channels for flight-control software owners.
Industry Challenges
- Autonomous navigation engineering scarcity:Real-time kinematic GPS integration and sensor fusion expertise concentrates in Shenzhen and Chengdu talent pools, limiting operator technical staffing in secondary markets.
- Passenger-grade certification complexity:Autonomous aerial vehicle airworthiness pathways through China's MIIT and Japan's MLIT impose multi-year validation timelines for urban mobility developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Commercial Drone Market |
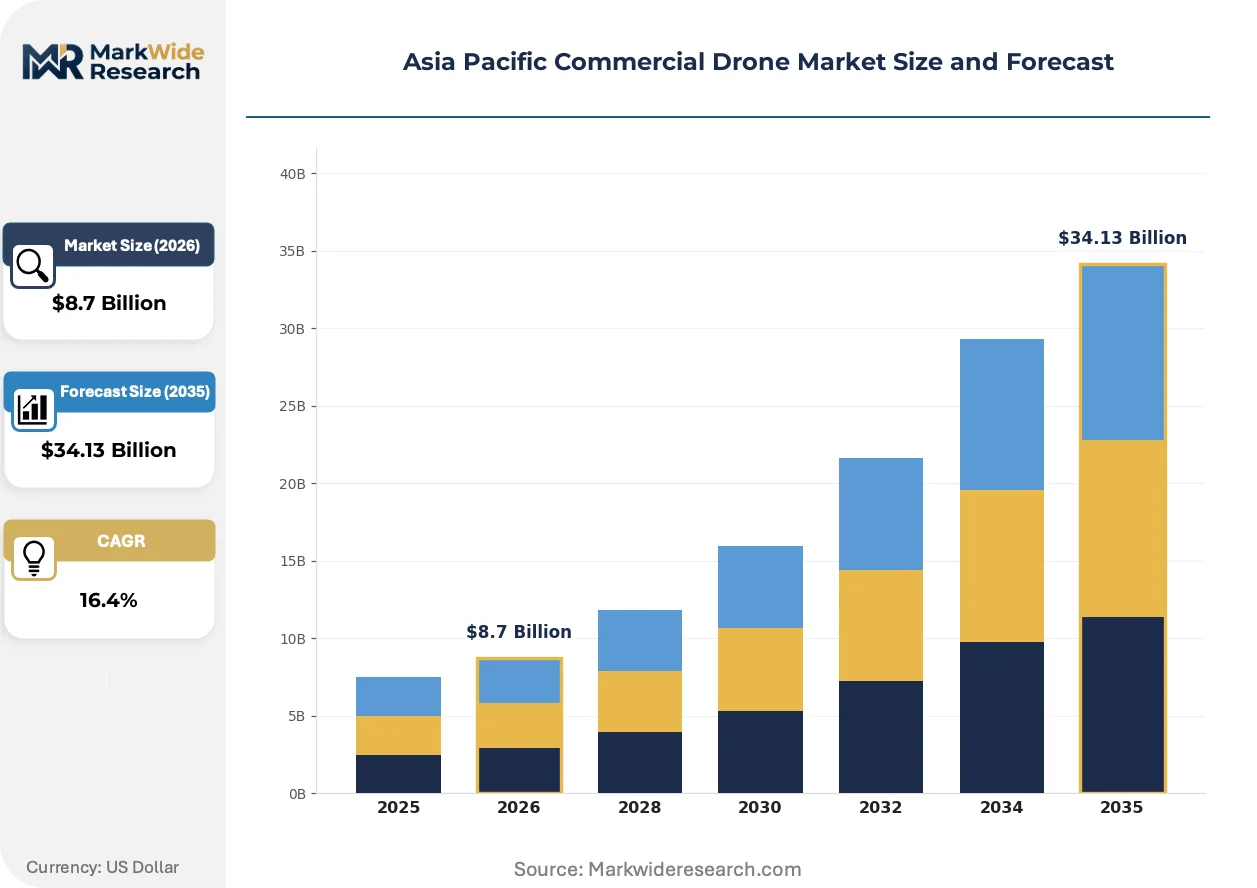
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Single-Rotor End User: Agriculture, Infrastructure, Logistics, Media Application: Aerial Photography, Surveying, Delivery, Inspections Technology: GPS, LiDAR, Thermal Imaging, Autopilot |
| Companies Covered | Guangzhou EHang Intelligent Technology Co. Ltd., Chengdu JOUAV Automation Tech Co., Ltd., SZ DJI Technology Co., Ltd., Yuneec International, Autel Robotics Co., Ltd., Terra Drone Corporation, XAG Co., Ltd., ACSL Inc., MicroMultiCopter (MMC) Aero Technology Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Commercial Drone Market Trends and Innovations
Software-defined flight autonomy is compressing hardware differentiation cycles, forcing airframe manufacturers to compete on sensor payload integration speed rather than mechanical endurance or lift capacity alone.
Swappable hydrogen fuel-cell power modules are displacing lithium-polymer battery packs as the dominant endurance solution for fixed-wing maritime patrol contracts. Australian mining corridor surveyors now specify fuel-cell platforms for twelve-hour loiter missions. This chemistry transition is compressing battery-centric supply chain margins while elevating fuel-cell stack integrators to tier-one vendor status.
China's MIIT enforcement of GB radio-transmission and airworthiness standards is filtering uncertified hardware from commercial channels. The regulation's industrial consequence is a two-tier vendor base: certified developers with Shenzhen supply base access versus excluded assemblers dependent on gray-market radio modules. Agricultural spraying operators in Guangxi and Yunnan provinces now specify MIIT-certified platforms exclusively, locking out uncertified competitors.
Per-flight data licensing is replacing capital equipment ownership among Australian mining geospatial clients. Major iron ore and coal operators in the Pilbara region now contract survey outcomes rather than purchasing airframes. This procurement pivot is visible most acutely in Western Australia, where Rio Tinto and BHP procurement teams have eliminated drone capital expenditure line items in favor of orthomosaic-as-a-service contracts with certified operators.
Asia Pacific Commercial Drone Market Segmentation
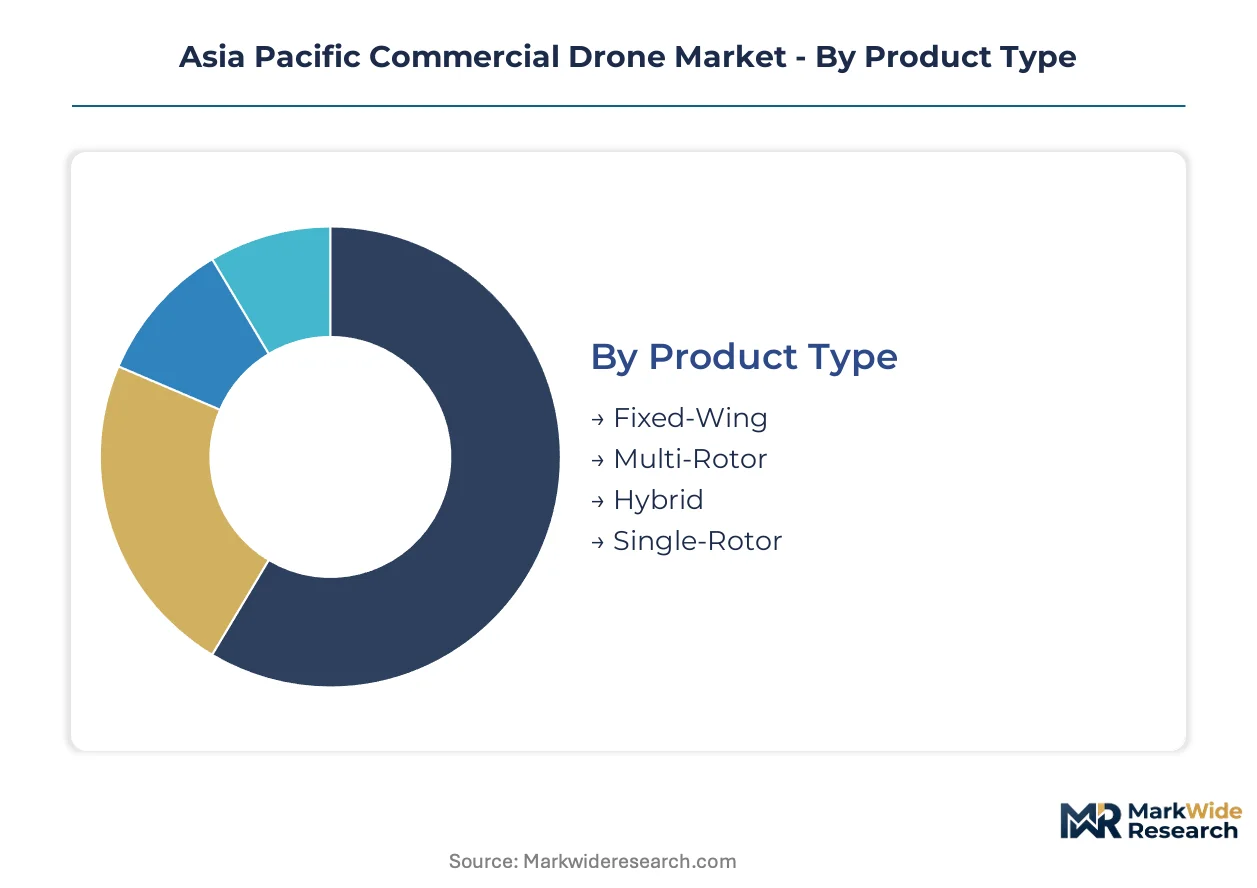
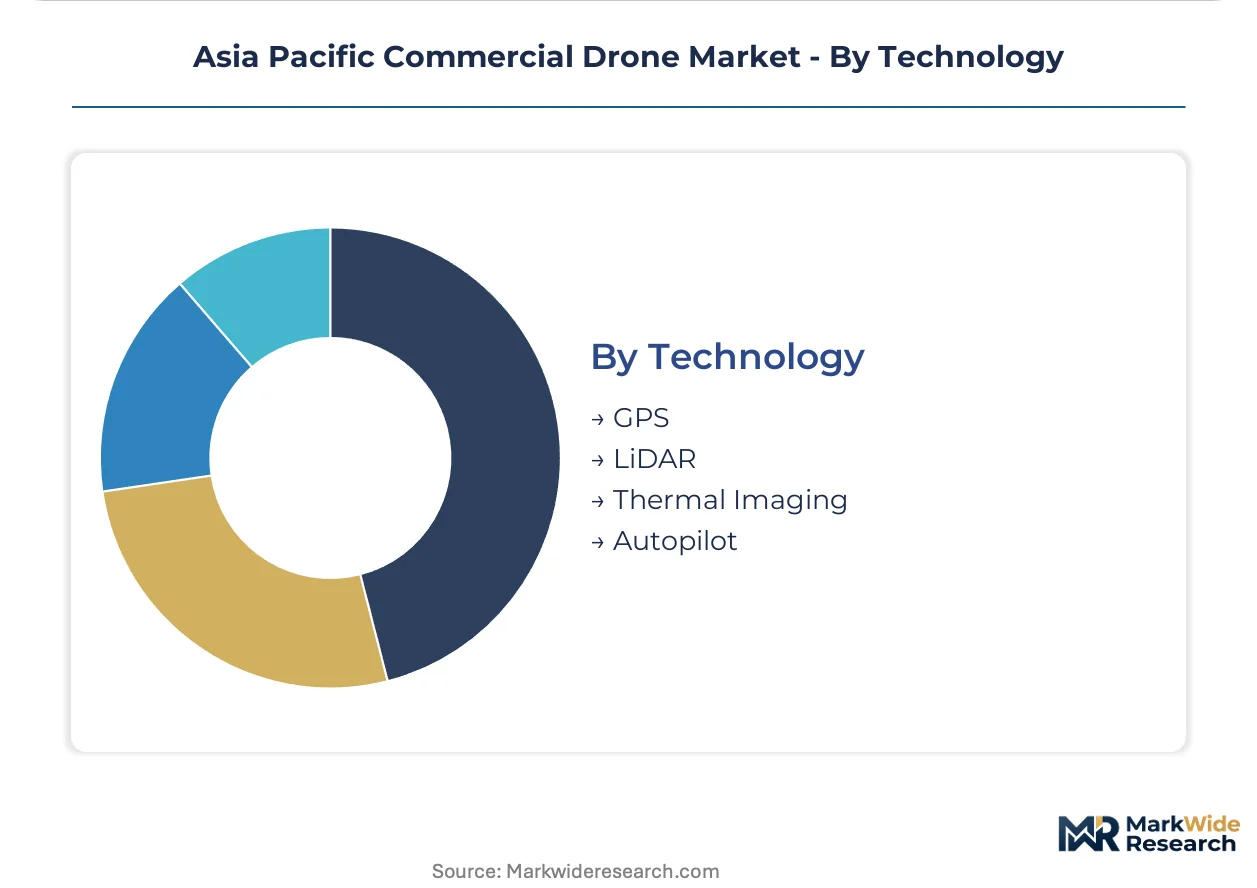
Segmentation in the Asia Pacific commercial drone market reveals how regulatory boundaries and payload requirements reshape procurement patterns across jurisdictions. Product configurations and sensor technologies face divergent certification pathways that determine operator eligibility for beyond-visual-line-of-sight missions.
Product Type:
MIIT airworthiness certification in China and METI corridor designations in Japan create divergent hardware approval pathways that favor specific aerodynamic configurations.
- Multi-Rotor:Vertical-takeoff platforms with four to eight rotors dominate dense urban and uneven terrain deployments. Demand concentrates in Indonesia's palm plantation monitoring and Vietnam's rice paddy spraying, where GPS-guided autonomous fungicide application replaces manual backpack sprayers.
- Fixed-Wing:Long-endurance systems with pusher or tractor propulsion configurations sustain higher margins in corridor-mapping contracts. Australian mining surveyors in the Pilbara region specify these platforms for twelve-hour loiter missions, with hydrogen fuel-cell modules displacing lithium-polymer packs as the endurance standard.
- Hybrid:VTOL-fixed-wing combinations merge vertical launch flexibility with extended cruise efficiency for archipelago logistics.
- Single-Rotor:Helicopter-style platforms with tail rotors serve heavy-lift cargo niches in remote infrastructure resupply.
Established volume favors Multi-Rotor; emerging adoption favors Hybrid.
End User:
Customer procurement sophistication varies sharply by sector maturity, with mining and agriculture operators advancing fastest toward outcome-based contracting models.
- Agriculture:Southeast Asian plantation operators deploy multi-rotor fleets for precision spraying across palm oil and rice cultivation zones. Thailand's Department of Agriculture now subsidizes GPS-guided autonomous systems to replace manual labor in disease-prone growing regions.
- Infrastructure:Power transmission and pipeline operators contract thermographic inspection services rather than owning airframes. This shift is most visible in Australia's transmission network maintenance programs.
- Logistics:Last-mile delivery trials in Japan's METI-designated corridors and Singapore's maritime port zones test regulatory tolerance for autonomous payload release.
- Media:Broadcast and cinematography operators drive prosumer-to-professional transitions in content capture, with South Korean production studios leading 4K aerial acquisition adoption.
Procurement maturity concentrates in Infrastructure; subsidy acceleration favors Agriculture.
Application:
Mission type determines sensor payload requirements and flight-control software licensing tiers that now exceed airframe costs.
- Surveying:Orthomosaic and digital elevation model generation for mining and construction clients. Western Australian iron ore operators have eliminated capital expenditure line items in favor of per-survey data licensing contracts with certified operators.
- Inspections:Infrastructure thermography and structural assessment for power lines, wind turbines, and cellular towers. Demand clusters in Japan's offshore wind development zones and Australia's solar farm maintenance programs.
- Aerial Photography:Content capture for media, real estate, and tourism marketing remains volume-driven but margin-compressed.
- Delivery:Medical supply and consumer package transport trials operate under restricted regulatory exemptions in designated flight corridors.
Recurring revenue models favor Surveying; regulatory constraint limits Delivery.
Technology:
Sensor fusion capabilities and real-time correction stacks now constitute the primary cost center, compressing margins for hardware assemblers lacking algorithmic control.
- GPS:Real-time kinematic correction enables centimeter-level positioning for precision agriculture and surveying missions. SZ DJI Technology leverages Shenzhen supply base integration to dominate prosumer-to-professional transitions in GPS-guided platforms.
- LiDAR:Laser scanning systems penetrate canopy and terrain for forestry and mining volumetric analysis. Deployment concentrates in Malaysia's timber concession monitoring and New Zealand's precision viticulture programs.
- Thermal Imaging:Infrared sensors detect heat anomalies in power transmission and photovoltaic installations.
- Autopilot:Software-defined flight autonomy compresses hardware differentiation cycles, forcing airframe manufacturers to compete on sensor integration speed.
Commoditization pressure hits GPS; premium capture concentrates in LiDAR.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in Asia Pacific commercial drones tilt toward component concentration in Chinese manufacturing clusters against platform assembly and service revenue capture in Australian and Japanese markets. Trade balances diverge sharply between raw material importers and vertically integrated system exporters.
China
Domestic absorption of lithium-polymer cells and flight-control chipsets from Guangdong and Jiangsu provinces feeds SZ DJI Technology's captive supply chains. MIIT radio-transmission certification timelines filter uncertified hardware from commercial channels. Shenzhen anchors the world's densest drone manufacturing ecosystem, with component suppliers clustering within fifty-kilometer radii of final assembly facilities.
Japan
METI corridor designations in Osaka and Tokyo metropolitan zones accelerate beyond-visual-line-of-sight authorization for logistics operators. Remote pilot licensing through Japan's civil aviation regulator constrains small-fleet contractors from scaling service coverage. Nagoya-based industrial conglomerates supply precision gyroscopes and optical sensors to regional platform integrators.
Australia
Mining corridor surveyors in Western Australia's Pilbara region have eliminated capital expenditure line items for drone hardware. Civil Aviation Safety Authority remote operator certification tiers shape business-model scalability for agricultural contractors. Perth anchors geospatial service provider clusters serving iron ore and coal operators with per-survey data licensing contracts.
India
The Directorate General of Civil Aviation's pending agricultural and emergency-response exemptions will unlock subcontinent-scale procurement cycles. Subsidy programs through state agriculture departments accelerate GPS-guided autonomous spraying adoption in disease-prone growing regions. Bangalore and Hyderabad host emerging flight-control software development talent pools.
Indonesia
Palm plantation operators deploy multi-rotor fleets for precision fungicide application across Sumatra and Kalimantan growing zones. Archipelago terrain drives demand for hybrid vertical-takeoff fixed-wing configurations that consolidate fleet diversity. Jakarta-based logistics operators trial last-mile delivery in designated urban airspace corridors.
Asia Pacific Commercial Drone Market Competitive Landscape
Concentration sits with vertically integrated developers who control sensor fusion algorithms and real-time kinematic correction stacks. Component-assemblers lacking captive flight-control software face margin compression as licensing costs exceed airframe manufacturing expenses. Two strategic archetypes dominate: Shenzhen supply base integrators and long-endurance fixed-wing specialists. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion through certified operator network partnerships.
Within the vertically integrated tier, SZ DJI Technology Co., Ltd. and Guangzhou EHang Intelligent Technology Co. Ltd. represent contrasting certification pathways—consumer-to-prosumer transitions versus autonomous passenger-grade airworthiness pursuits. Chengdu JOUAV Automation Tech Co., Ltd. anchors the long-endurance fixed-wing archetype for geospatial clients. These three Chinese entities exemplify how regulatory compliance velocity and supply base proximity determine competitive positioning in a market where software-defined autonomy compresses hardware differentiation cycles.
| Leading Market Players |
|---|
| Guangzhou EHang Intelligent Technology Co. Ltd. |
| Chengdu JOUAV Automation Tech Co., Ltd. |
| SZ DJI Technology Co., Ltd. |
| Yuneec International |
| Autel Robotics Co., Ltd. |
| Terra Drone Corporation |
| XAG Co., Ltd. |
| ACSL Inc. |
| MicroMultiCopter (MMC) Aero Technology Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's fifty-kilometer component clustering compresses procurement lead times for flight-control chipsets and lithium-polymer cells, simultaneously anchoring price floors for certified platforms and squeezing margin room for assemblers lacking captive supply access. This scale geometry concentrates pricing power with vertically integrated developers who internalize sensor fusion algorithm costs while exposing component-dependent operators to input volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture flight-control software licensing and MIIT certification bundling, while economy tiers compete on airframe unit costs alone. Cost compression in the standard tier is intensifying because hydrogen fuel-cell module suppliers are elevating power system specifications for Australian mining contracts. Agricultural spraying contractors in Southeast Asia exhibit the highest price sensitivity, whereas Western Australian mining geospatial clients prioritize per-survey outcome guarantees over capital expenditure minimization.
Supply Chain Analysis
Port congestion along the Shenzhen-Singapore trade lane elevates inbound logistics costs for flight-control hardware destined for Australian and Indonesian assembly points. Component manufacturing concentrates in China, South Korea, and Japan, with raw material dependencies spanning lithium-cobalt oxide cathodes, precision MEMS gyroscopes, and real-time kinematic GPS correction modules. Single-source vulnerability sits with Guangdong province lithium-polymer cell production clusters. Distribution runs through certified operator networks in Perth, Tokyo, and Jakarta rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flight-control software engineering talent pools in Shenzhen and Chengdu are tightening faster than regional training pipelines can replenish, creating a capability bottleneck that determines which platform developers sustain margin capture versus hardware assemblers facing algorithmic licensing cost inflation.
For Market Incumbents: Compound defensive positioning through backward integration into semiconductor sourcing for flight-control chipsets and through exclusive certification pathway partnerships with Australia's Civil Aviation Safety Authority. The emerging threat of hydrogen fuel-cell stack integrators achieving tier-one vendor status in Australian mining contracts demands upstream control over power module specifications. For New Entrants and Emerging Players: Lead with India's DGCA agricultural exemption window as the most penetrable geography, targeting GPS-guided autonomous spraying systems for disease-prone growing regions in Maharashtra and Punjab. A state agriculture department subsidy-aligned go-to-market angle bypasses direct price competition with established Chinese OEMs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flight-control software owners with recurring revenue streams over airframe manufacturers facing hardware commoditization. Long-term viability over a five-to-ten-year horizon rests on sensor fusion algorithm differentiation rather than mechanical design patents. The inflection signal to watch is India's DGCA beyond-visual-line-of-sight authorization timeline for emergency-response fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Flight-Control Software Licensing | Recurring revenue capture from Australian mining geospatial clients shifts value upstream from hardware. |
| MIIT Certification Investment | Radio-transmission approval through China's Ministry of Industry and Information Technology filters uncertified competitors from commercial channels. |
| Hydrogen Fuel-Cell Integration | Extended loiter times for maritime patrol contracts in Australian mining corridors displace battery-centric platforms. |
| Geographic Operator Network Partnership | Certified operator density in Perth and Jakarta accelerates per-survey data licensing adoption over capital sales. |
| Autonomous Navigation R&D Expansion | Real-time kinematic GPS integration expertise concentrates competitive advantage in Shenzhen and Chengdu talent pools. |
Research Methodology
A standing panel of flight-control software engineers, remote pilot licensing instructors, mining geospatial procurement managers, and agricultural spraying fleet operators provided ongoing calibration across the study period. Primary interview data combined with secondary validation from MIIT certification registries, Australia's Civil Aviation Safety Authority operator licensing databases, and Japan's METI corridor designation filings enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, application, and technology dimensions alongside regulatory compliance tier as an industry-specific segmentation layer. CAGRs were derived from fitted growth curves incorporating hydrogen fuel-cell adoption velocity and India's DGCA exemption timeline as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained MIIT enforcement intensity or India's regulatory authorization trajectory would require recalibration. Forecasts reflect documented assumptions regarding lithium-polymer supply concentration and pilot licensing tier scalability. Practitioners should keep alternative scenarios live as China's dual carbon goals and Japan's MLIT urban air mobility certification pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Airborne Digital Battlefield Market
UAV
Racing Drone Market
UAV
Electric Glider Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
UAV Battery Market
UAV
Miniature Drone Market
UAV
Ultra-Long Endurance Drone Market
UAV
Global Aerial Survey Services Market
UAV
Drone Leasing Market
UAV
Delivery Drones Market
UAV
Global Drone Autopilots Market
UAV
Global Multirotor UAV Market
UAV
Combat Drone Market
UAV
Drone Wireless Charging Station Market
UAV
Drone Delivery Services Market
UAV
Latin America Small UAV Market