
 Industrial Drones Market | 2026-2036
Industrial Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Drones Market Insights
Subscription-based flight analytics and predictive maintenance bundles is rebalancing how vendors monetize hardware deployments. DJI Innovations leverages its manufacturing scale to anchor consumer-to-industrial crossover demand. AeroVironment specializes in defense-grade endurance platforms for government end users. Skydio competes through autonomous obstacle-avoidance stacks that reduce pilot training thresholds.
Industrial drones are unmanned aerial vehicles engineered for commercial operations, typically incorporating carbon-fiber composite airframes, redundant flight controllers, and payload capacities ranging from sub-kilogram sensors to multi-kilogram LiDAR units, designed to execute remote sensing, cargo delivery, or automated inspection tasks in hazardous or inaccessible environments. Rotary-wing configurations dominate short-range infrastructure inspection due to vertical takeoff flexibility and precision hovering, while fixed-wing platforms sustain longer endurance missions across mining and agricultural survey blocks. RTK positioning technology is capturing margin pools in geodetic surveying, where centimeter-level accuracy commands premium pricing from construction and engineering clients.
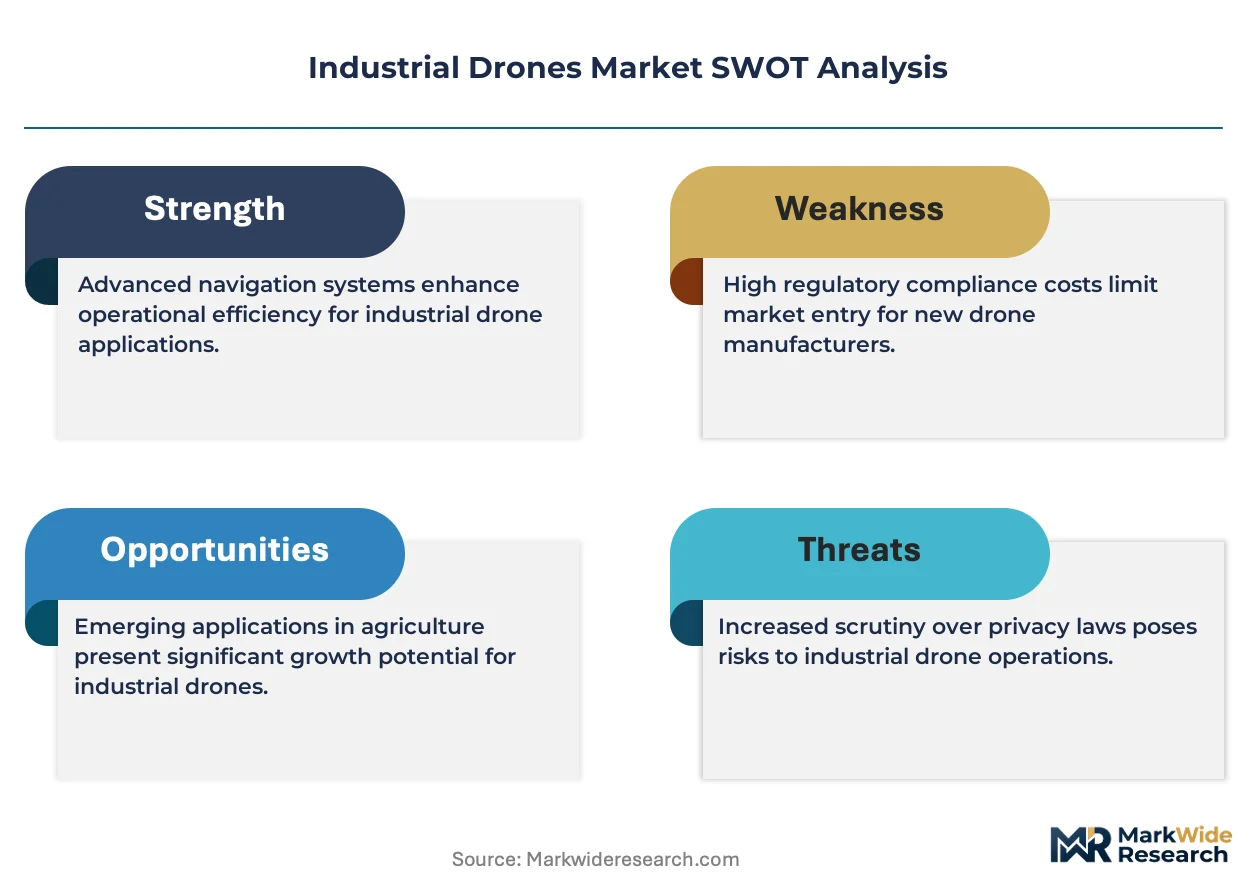
The FAA's Part 107 framework and the EU's CE marking under the UAS Delegated Regulation shape airworthiness certification pathways and operational altitude ceilings, directly filtering which platforms gain commercial deployment clearance. China's MIIT enforces GB standards on radio transmission frequencies, constraining cross-border hardware compatibility for manufacturers serving multiple jurisdictions. Stakeholders must weigh regulatory fragmentation against platform standardization bets when allocating R&D budgets and territorial market entry sequencing.
Market Dynamics
The FAA's Part 107 expansion is compressing operational barriers for beyond-visual-line-of-sight missions, while RTK positioning technology is capturing premium margin pools in geodetic surveying workflows.
Growth Catalysts
- Precision Agriculture Expansion:Brazilian crop monitoring enterprises are scaling rotary-wing fleet deployments across soybean and sugarcane belts. RTK-enabled variable-rate application is displacing manual scouting methods.
- EU UAS Delegated Regulation:CE marking harmonization is streamlining cross-border commercial certification for fixed-wing inspection platforms. Engineering firms in Germany's industrial corridor are accelerating asset inspection integration.
- Carbon-Fiber Composite Airframes:Sub-kilogram sensor payload integration is extending flight endurance for mining survey blocks. Material cost curves are flattening for multi-rotor manufacturers.
Market Restraints
- GB Standards Fragmentation:China's MIIT radio frequency mandates constrain cross-border hardware compatibility for manufacturers serving multiple jurisdictions. Platform standardization bets carry territorial sequencing risk.
- Redundant Flight Controller Costs:Dual-IMU and triple-redundant autopilot systems inflate bill-of-materials by 15-25% for defense-grade endurance platforms. Mid-tier commercial buyers face procurement compression.
- LiDAR Unit Supply Concentration:Multi-kilogram payload sourcing clusters among North American and Israeli component suppliers. Geopolitical friction disrupts delivery timelines for Asian system integrators.
Strategic Opportunities
- Subscription Analytics Bundles:Predictive maintenance software layered onto hardware deployments is rebalancing vendor monetization toward recurring revenue. Brazilian agribusiness cooperatives represent underpenetrated adopters.
- Autonomous Obstacle-Avoidance Convergence:Computer vision stacks fused with RTK positioning are reducing pilot training thresholds for infrastructure inspection. German utility operators are piloting reduced-crew deployments.
- FERC Pipeline Inspection Mandates:US energy infrastructure operators face escalating regulatory pressure for aerial leak detection. Methane-sensing payload integration is creating certified service provider tiers.
Industry Challenges
- Part 107 Remote Pilot Certification Bottlenecks:FAA knowledge test capacity constraints and recurrent training requirements throttle operator pipeline expansion. Flight schools face instructor scarcity for night operation endorsements.
- Legacy SCADA Integration Complexity:Industrial drone data streams require middleware development for enterprise asset management systems. German engineering firms report 6-12 month deployment cycles for full workflow integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Drones Market |
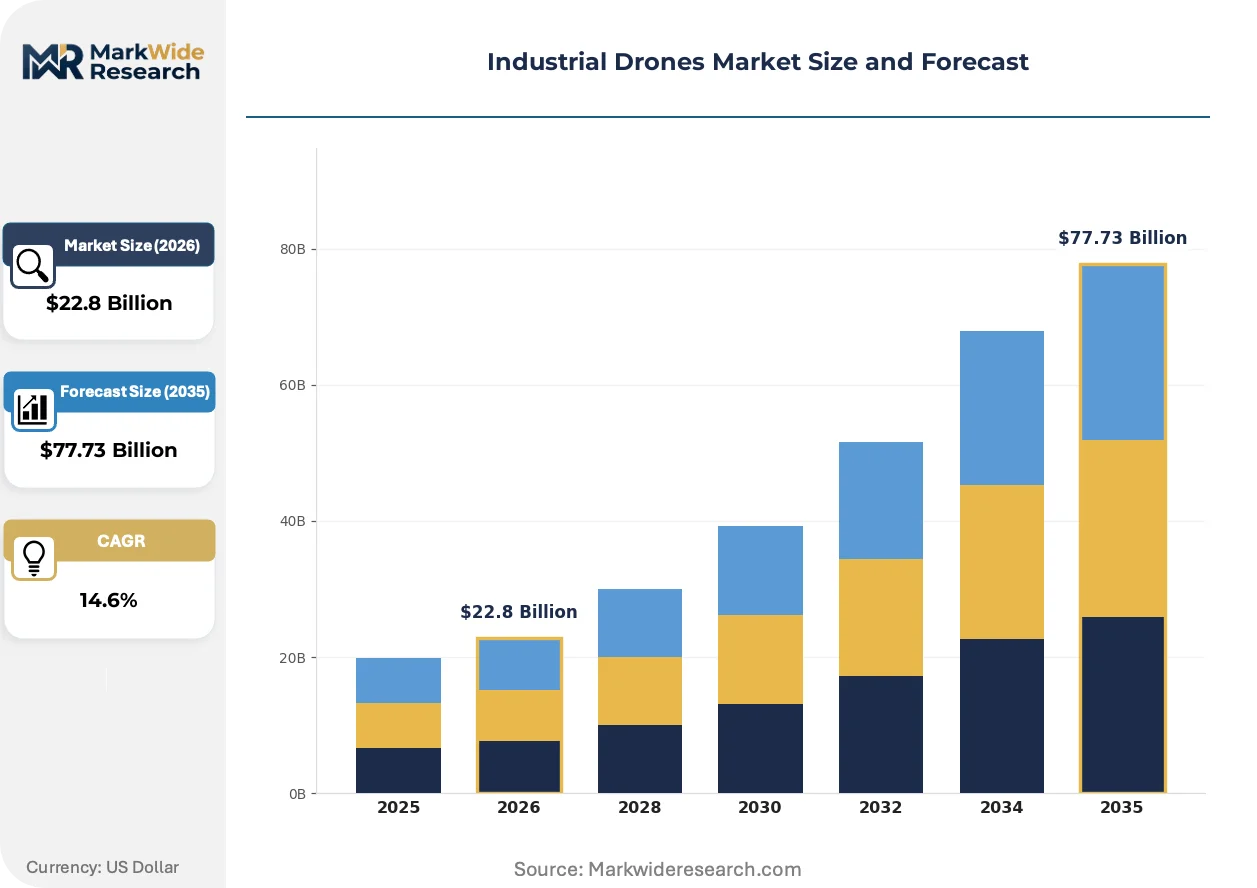
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $77.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano Drones, Mini Drones Technology: GPS Guidance, Visual Navigation, Infrared Sensors, LIDAR, RTK Positioning Application: Surveillance, Precision Agriculture, Infrastructure Inspection, Mining, Emergency Response End User: Construction Companies, Surveying Firms, Mining Operators, Emergency Services, Agriculture Enterprises |
| Companies Covered | JOUAV, Parrot, DJI Innovations, EHang, Insitu, Skydio, AeroVironment, Freefly Systems, XAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Drones Market Trends and Innovations
Edge computing architectures are redistributing data processing from ground stations to onboard flight controllers, compressing latency for real-time decision loops in autonomous inspection missions.
Swarm coordination algorithms are decentralizing mission execution across multiple rotary-wing units operating without centralized control nodes. Mining operators in Australia's Pilbara region are deploying coordinated survey formations across 50-square-kilometer blocks. Distributed computing loads are reducing single-point-of-failure risks while compressing total survey duration by 60-70% compared to sequential single-unit operations.
EU AI Act risk classification frameworks are imposing conformity assessment obligations on autonomous navigation systems deployed in urban air mobility corridors. German drone service providers must document algorithmic transparency for beyond-visual-line-of-sight operations in populated areas. Fixed-wing cargo platforms crossing into civil airspace face escalating documentation burdens that favor established aerospace certification specialists over emerging hardware vendors.
Agribusiness procurement departments are unbundling hardware acquisition from flight-hour service contracts, treating drone operations as variable opex rather than capital deployment. Brazilian soybean cooperatives are contracting certified operator networks through seasonal subscription tiers rather than maintaining captive fleets. Equipment utilization rates and pilot certification currency become vendor accountability metrics, shifting performance risk from buyer balance sheets to service provider operations.
Industrial Drones Market Segmentation
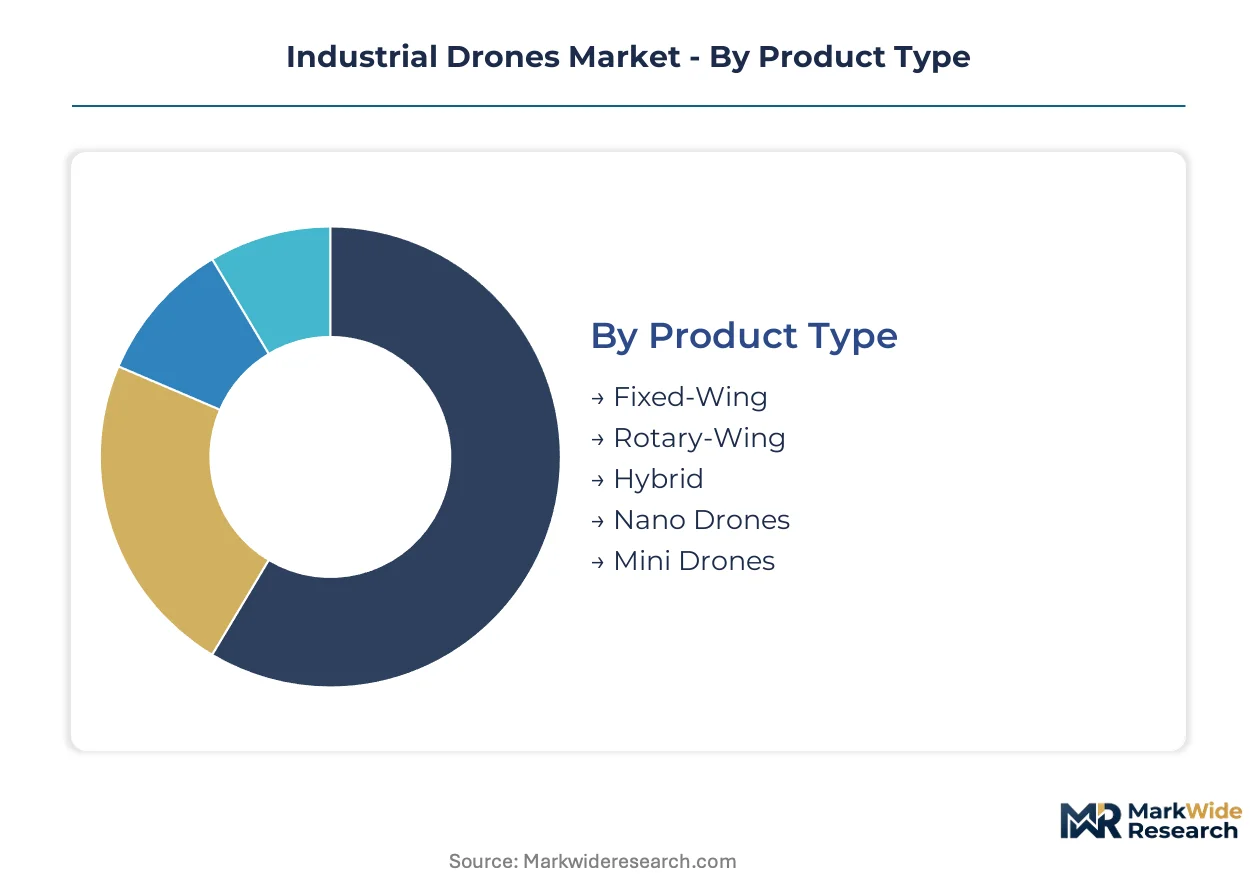
Industrial drone procurement decisions pivot on flight endurance requirements, payload precision needs, and regulatory compliance thresholds across jurisdictions. Fleet operators weigh airframe longevity against sensor upgradeability when structuring capital deployment cycles.
Product Type:
Upgrade cycles vary dramatically by airframe architecture, with composite material fatigue and avionics obsolescence driving replacement timelines.
- Fixed-Wing:Extended-endurance platforms with rigid airframes and pusher-prop configurations dominate mining survey blocks across Australia's Pilbara region. Brazilian agribusiness cooperatives favor these units for soybean belt mapping where runway access exists.
- Rotary-Wing:Multi-rotor configurations with vertical takeoff capability anchor infrastructure inspection workflows in Germany's industrial corridor. German utility operators deploy these for precision hovering around transmission towers where maneuverability outweighs endurance.
- Hybrid:Tilt-rotor designs combine VTOL flexibility with fixed-wing cruise efficiency for long-range cargo missions.
- Nano Drones:Sub-250-gram platforms navigate confined industrial spaces for indoor asset monitoring.
- Mini Drones:Compact rotary units serve rapid-deployment emergency response scenarios.
Volume placements concentrate in Rotary-Wing; the faster expansion belongs to Hybrid.
Technology:
Technology selection locks operators into specific accuracy tiers and regulatory compliance pathways, with sensor fusion stacks commanding premium positioning.
- GPS Guidance:Standard satellite-based navigation systems provide meter-level accuracy for broad-area reconnaissance and basic flight path management. Construction companies in Brazil deploy these for preliminary site surveys where centimeter precision remains unnecessary.
- RTK Positioning:Real-time kinematic systems with ground station correction achieve centimeter-level accuracy for geodetic surveying workflows. German engineering firms integrate these for construction staking and volumetric measurement where error tolerance is minimal.
- Visual Navigation:Camera-based simultaneous localization and mapping enables GPS-denied operation.
- Infrared Sensors:Thermal payload integration supports electrical infrastructure fault detection.
- LIDAR:Laser scanning arrays generate dense point clouds for topographic modeling.
Deployment frequency peaks with GPS Guidance; steepest expansion trajectory belongs to RTK Positioning.
Application:
Application segmentation reflects divergent payload requirements and operational risk profiles across industrial verticals.
- Precision Agriculture:Variable-rate application systems with multispectral sensors enable targeted input deployment across Brazilian soybean and sugarcane belts. RTK-enabled spraying reduces chemical waste while boosting yield consistency.
- Infrastructure Inspection:Automated defect detection algorithms process high-resolution imagery from transmission towers and pipeline corridors. German utility operators are piloting reduced-crew deployments with autonomous obstacle-avoidance stacks.
- Surveillance:Perimeter monitoring and security patrol applications leverage thermal and optical payloads.
- Mining:Volumetric stockpile measurement and pit mapping operations span extended survey blocks.
- Emergency Response:Search-and-rescue and disaster assessment missions require rapid deployment capability.
Activity concentrates in Precision Agriculture; gaining share fastest is Infrastructure Inspection.
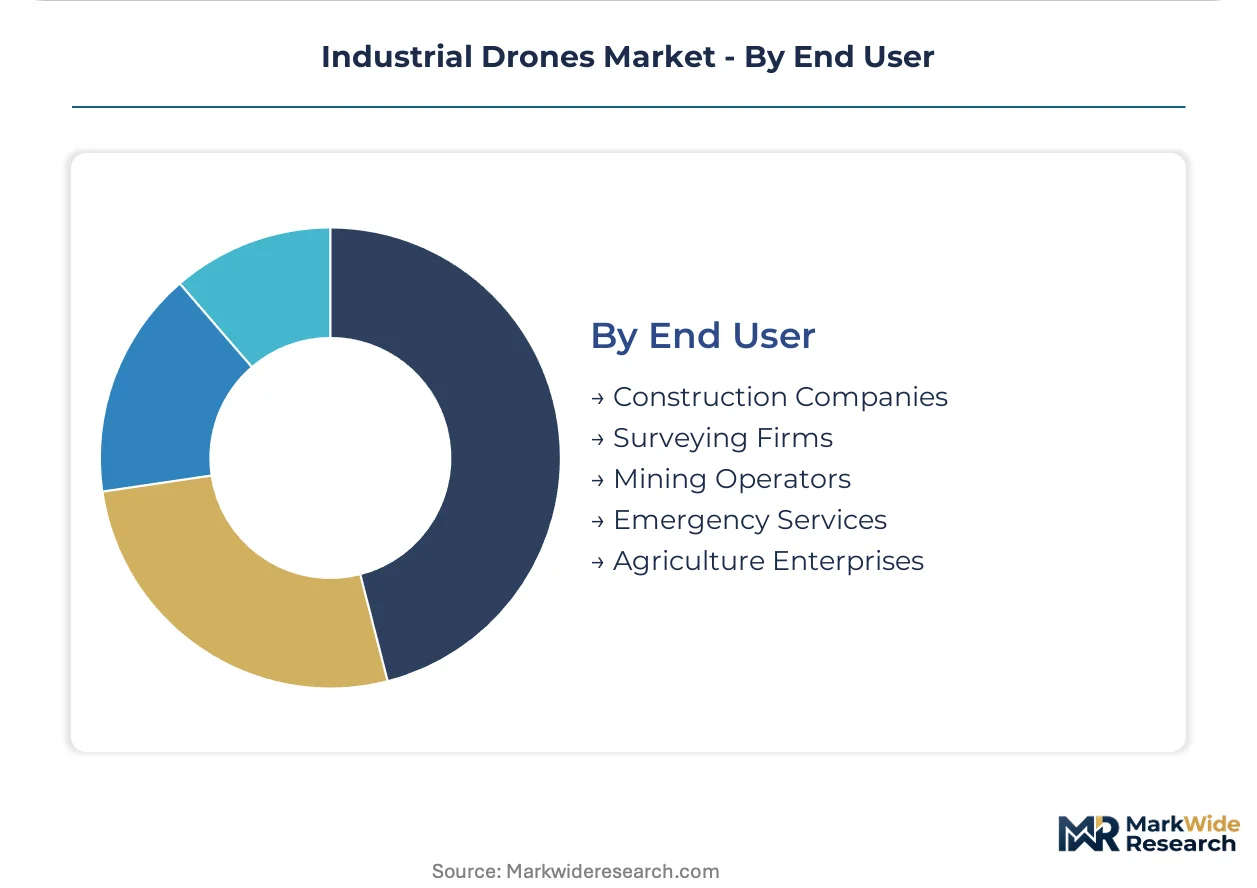
End User:
End-user procurement maturity determines whether drone operations remain captive or shift to outsourced service models.
- Agriculture Enterprises:Brazilian cooperatives increasingly favor seasonal flight-hour contracts over fleet ownership. Equipment utilization and pilot certification currency shift to vendor accountability metrics.
- Construction Companies:German engineering firms face 6-12 month deployment cycles for full SCADA integration. Middleware development for enterprise asset management systems extends implementation timelines.
- Surveying Firms:Geodetic specialists drive RTK positioning adoption for cadastral and construction staking work.
- Mining Operators:Australian Pilbara region deployers favor swarm coordination across 50-square-kilometer survey blocks.
- Emergency Services:First responder units prioritize rapid-launch mini drone systems for situational awareness.
Contract volume concentrates in Agriculture Enterprises; climbing the fastest belongs to Construction Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese manufacturing clusters, while consumption spreads across agricultural belts and industrial corridors in the Americas and Europe. Regulatory fragmentation shapes territorial entry sequencing for hardware vendors.
United States
FERC pipeline inspection mandates and FAA Part 107 BVLOS expansion drive utility sector adoption. The FAA's recurrent training requirements and night operation endorsements constrain operator pipeline growth. Texas energy corridor operators deploy methane-sensing payloads for leak detection compliance.
Germany
Engineering firms integrate RTK-enabled inspection workflows across the industrial corridor. EU UAS Delegated Regulation CE marking harmonizes cross-border certification. North Rhine-Westphalia utility operators pilot reduced-crew autonomous deployments with obstacle-avoidance stacks.
Brazil
Soybean and sugarcane belt cooperatives scale rotary-wing fleets for crop monitoring. ANVISA agrochemical application protocols govern spray drone certification. São Paulo state agribusinesses contract seasonal flight-hour services rather than maintaining captive fleets.
China
Domestic precision agriculture and infrastructure inspection absorb manufacturing output. MIIT GB standards on radio frequencies constrain hardware export compatibility. Yangtze River Delta system integrators face LiDAR component sourcing delays from geopolitical friction.
Australia
Mining operators in the Pilbara region deploy swarm coordination across extended survey blocks. CASA operational approvals for BVLOS missions enable automated stockpile measurement. Western Australia volumetric surveying contracts compress total duration through distributed multi-unit formations.
Industrial Drones Market Competitive Landscape
Top-tier vendors anchor manufacturing scale and software integration, while mid-tier specialists compete on payload customization and regional service density. The vendor base stratifies across three tiers: diversified aerospace conglomerates with captive drone divisions, pure-play unmanned systems manufacturers with full-stack capabilities, and component-focused subsystem suppliers. Competitive positioning hinges on backward integration into flight controllers, strategic partnerships with sensor fusion providers, and geographic expansion through certified operator networks.
Within the pure-play tier, DJI Innovations and Skydio exemplify divergent strategic bets on manufacturing scale versus autonomous software stacks. AeroVironment occupies a position bridging defense-grade endurance platforms with government procurement channels. Shenzhen-based EHang and Guangzhou-based XAG represent Chinese manufacturing-origin competitors navigating export compliance complexity.
| Leading Market Players |
|---|
| JOUAV |
| Parrot |
| DJI Innovations |
| EHang |
| Insitu |
| Skydio |
| AeroVironment |
| Freefly Systems |
| XAG |
| Others |
Pricing and Supply Chain Analysis
Flight controller firmware engineers concentrated in Shenzhen's Pearl River Delta manufacturing corridor create labor-cost differentials that widen pricing-tier spreads between premium RTK-enabled platforms and economy GPS-guided units. Tier-one system integrators leverage this talent density to compress development cycles, while mid-tier vendors absorb margin pressure from certification-heavy European market entry requirements.
Pricing Analysis
Margin tightening in economy-tier rotary-wing units reflects carbon-fiber composite oversupply from Yangtze River Delta molders. Three-tier pricing structure across premium, standard, and economy levels separates RTK-enabled surveying platforms from GPS-guided reconnaissance units and basic inspection drones. Price differentiation hinges on CE marking tier under EU UAS Delegated Regulation and ground-station bundling intensity. Brazilian agribusiness cooperatives exhibit acute price sensitivity, while German engineering firms prioritize accuracy premiums over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Israeli and North American LiDAR array suppliers serving Asian system integrators. Component sourcing draws from China's MIIT-regulated radio module foundries, German precision sensor specialists, and Taiwanese flight controller fabricators. Raw material dependencies span carbon-fiber prepreg, rare-earth magnet alloys for brushless motors, and gallium nitride semiconductors for power management. Tariff exposure on radio frequency components disrupts cross-border hardware compatibility. Distribution runs through certified operator networks and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where flight controller firmware engineering capacity props pricing power for full-stack vendors. Pilot certification bottlenecks under FAA Part 107 recurrent training requirements limit operator pipeline expansion, reinforcing hardware-plus-service bundling premiums.
For Market Incumbents: Anticipate margin compression from Chinese manufacturing-origin competitors by deepening backward integration into RTK ground station production and securing exclusive sensor fusion partnerships. Defense-grade endurance platform specialists face procurement channel consolidation as government buyers consolidate vendor lists. Prioritize CE marking investment for EU UAS Delegated Regulation compliance to defend corridor access against emerging pure-plays. For New Entrants and Emerging Players: The price-point gap between premium RTK-enabled platforms and economy GPS-guided units offers white-space targeting for mid-tier hybrid airframe specialists. Brazilian agribusiness cooperatives present the most penetrable end-user segment through seasonal flight-hour service contracts rather than hardware sales. German utility operators piloting reduced-crew autonomous deployments represent a certification-fast-follow opportunity for obstacle-avoidance stack integration. For Investors and Strategic Acquirers: The window for entry favors pure-play autonomous software stack developers with computer vision IP. Long-term viability hinges on algorithmic transparency documentation for EU AI Act conformity assessment obligations. Acquisition target archetype: regional certified operator networks with captive pilot certification pipelines. Watch FAA Part 107 BVLOS expansion velocity as inflection indicator for infrastructure inspection automation penetration.| Strategic Initiative | Industry Significance |
|---|---|
| RTK Ground Station Network Expansion | Centimeter-level accuracy commands premium pricing from German engineering and surveying clients. |
| Autonomous Navigation Software Certification | EU AI Act conformity documentation enables beyond-visual-line-of-sight operations in populated corridors. |
| Certified Operator Network Acquisition | Pilot certification currency shifts performance risk from buyer balance sheets to vendor operations. |
| Carbon-Fiber Airframe Manufacturing Scale-Up | Material cost curve flattening compresses economy-tier production economics for multi-rotor platforms. |
| Methane-Sensing Payload Integration Partnership | FERC pipeline inspection mandates create certified service provider tiers for US energy infrastructure operators. |
Research Methodology
SEC filings, FAA regulatory dockets, and EU UAS Delegated Regulation implementation guidance formed the secondary backbone, cross-referenced with customs records on carbon-fiber composite and LiDAR unit trade flows. Primary interviews with flight operations directors at Brazilian agribusiness cooperatives, German utility engineering managers, and Australian mining survey coordinators supplied demand-side validation. Bottom-up fleet deployment estimates triangulated against top-down hardware shipment data from manufacturing clusters.
Historical trendline analysis of precision agriculture adoption rates and infrastructure inspection automation penetration informed projection modeling across the analysis window. Segmentation dimensions encompassed airframe architecture, positioning technology tier, application vertical, and end-user procurement maturity. CAGRs derived from installed base growth curves and replacement cycle compression in RTK-enabled surveying workflows. Forecast inputs incorporated BVLOS regulatory expansion timelines and swarm coordination algorithm deployment rates in mining operations.
Inputs from OEM production schedules and certified operator network capacity disclosures were available through the study window; gaps in real-time pilot certification pipeline data introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions on regulatory harmonization velocity and sensor fusion cost curves. Deviation in FAA Part 107 night operation endorsement capacity or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Rc Helicopter Market
UAV
Drone-As-A-Service Market
UAV
Drone Inspection Service Market
UAV
Fixed Wing Military Drones Market
UAV
North America Drone Services Market
UAV
Global Target Drone Market
UAV
Drone Wireless Charging Station Market
UAV
Global Inspection Drones Market
UAV
Military UAV Sensor Market
UAV
Auto-Follow Drone Market
UAV
Nano Drones Market
UAV
Drone Telematics Market
UAV
Global Drone Light Shows Market
UAV
Global Aerial Survey Services Market
UAV
North America Fuel Cell UAV Market
UAV
Passenger Drones Market