
 Enterprise Drone Management Solutions Market | 2026-2036
Enterprise Drone Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Drone Management Solutions Market Foresight
Multi-source procurement of flight control modules is restructuring how enterprise operators assemble their drone stacks. DJI leverages its manufacturing scale to dominate hardware-software bundling, while DroneDeploy competes through cloud-native mission planning and photogrammetry workflows. PrecisionHawk anchors its position in agricultural analytics, occupying a specialized niche that larger platforms have not replicated.
Enterprise drone management solutions encompass software platforms that orchestrate UAV fleets through real-time telemetry, airspace deconfliction algorithms, and automated flight path optimization with sub-meter GPS correction. These systems serve commercial and government operators seeking to scale beyond-visual-line-of-sight operations while maintaining compliance with evolving aviation rules. Fleet management platforms are attracting the deepest investment as operators consolidate dispersed pilot teams under unified scheduling and maintenance protocols. Cloud-based deployment is displacing on-premises installations among mid-sized energy operators who prioritize elastic compute for seasonal inspection surges. Data analytics tools represent the fastest-expanding margin pool as raw imagery yields to AI-derived asset condition scoring.
The FAA, EASA, and Australia's Civil Aviation Safety Authority each enforce distinct remote pilot certification and airspace integration requirements that shape product roadmaps and market access conditions. The FAA's Part 107 evolution and EASA's specific category framework are forcing vendors to modularize compliance engines by jurisdiction. Stakeholders must monitor which regulatory bodies achieve mutual recognition of drone operational approvals first, as this will determine where platform providers can achieve geographic leverage without redundant certification investments.
Market Dynamics
Fleet orchestration platforms are consolidating fragmented pilot operations under unified command structures as operators scale beyond-visual-line-of-sight missions across dispersed infrastructure assets.
Growth Catalysts
- Beyond-visual-line-of-sight corridor expansion:The FAA's Remote ID mandate and Australia's Civil Aviation Safety Authority BVLOS frameworks are compelling infrastructure operators to invest in compliant command-and-control infrastructure.
- Multi-site construction coordination:Large-scale builders are deploying centralized fleet management to synchronize aerial surveys across geographically dispersed project portfolios.
- EU U-space regulatory rollout:EASA's specific category framework for unmanned aircraft is driving modular compliance engine development for European operators.
Market Restraints
- Hardware-software bundling concentration:Manufacturing scale advantages in Asia-Pacific flight control modules create procurement dependency risks for Western software vendors.
- Airspace deconfliction compute costs:Real-time telemetry processing for sub-meter GPS correction demands elastic cloud infrastructure that strains mid-sized operator budgets.
- Jurisdictional certification redundancy:Non-recognition of drone operational approvals between the FAA, EASA, and CASA forces redundant compliance investments.
Strategic Opportunities
- German energy inspection surge:Seasonal grid maintenance cycles in Germany are creating demand for elastic compute deployments that scale with inspection volume spikes.
- AI-derived asset scoring:Raw imagery analytics are yielding to machine learning condition assessment tools that command premium pricing in predictive maintenance contracts.
- Agricultural analytics specialization:Crop health monitoring applications remain underpenetrated by generalist platforms, creating white space for purpose-built solutions.
Industry Challenges
- Certified remote pilot scarcity:Multi-jurisdiction Part 107 and specific category licensing requirements are outpacing qualified operator supply.
- Legacy system integration friction:Enterprise resource planning connectivity with cloud-native mission planning platforms requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Drone Management Solutions Market |
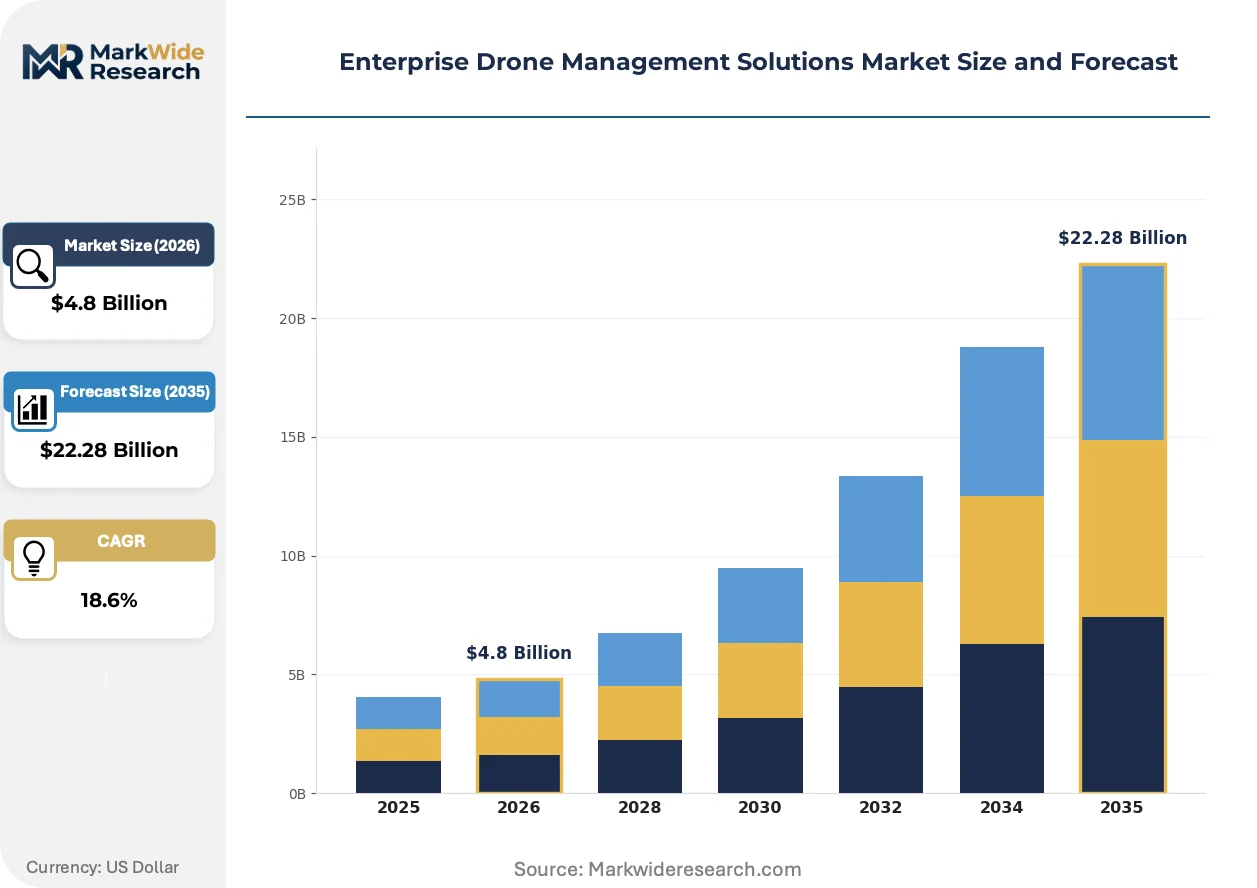
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Flight Control Software, Fleet Management Platforms, Data Analytics Tools, Maintenance Scheduling Systems Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing Application Area: Precision Agriculture, Infrastructure Inspection, Public Safety Surveillance, Logistics & Delivery End User Industry: Construction Firms, Energy Operators, Emergency Response Units, Surveying Agencies |
| Companies Covered | DroneDeploy, DJI, Skycatch, Skyward, Kespry, PrecisionHawk, Aerodyne Group, Airware, Pix4D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Drone Management Solutions Market Shifts & Advancements
Telemetry standardization and edge computing architectures are compressing decision latency in distributed drone operations. Platform vendors are racing to embed predictive maintenance algorithms that anticipate component failures before flight aborts.
Computer vision-based obstacle detection is converging with real-time kinematic GPS correction to enable autonomous navigation in GPS-denied environments. Mining operators in Australia are deploying these fused systems for underground infrastructure mapping. This convergence is compressing the pilot-to-aircraft ratio from one-to-one toward one-to-many fleet supervision models.
EASA's specific category framework is forcing vendors to modularize compliance engines by jurisdiction rather than shipping monolithic global platforms. Industrial consequences include delayed product launches and elevated R&D overhead for multi-regional coverage. Agricultural analytics providers are responding by prioritizing EU certification ahead of feature expansion.
Energy utilities are unbundling after-sales service from hardware procurement, purchasing predictive analytics subscriptions separately from aircraft fleets. This disintermediation is disrupting traditional bundled sales channels. The shift is most visible in United States transmission line inspection programs, where operators now source flight services from specialized third-party providers rather than maintaining captive fleets.
Enterprise Drone Management Solutions Market Segmentation
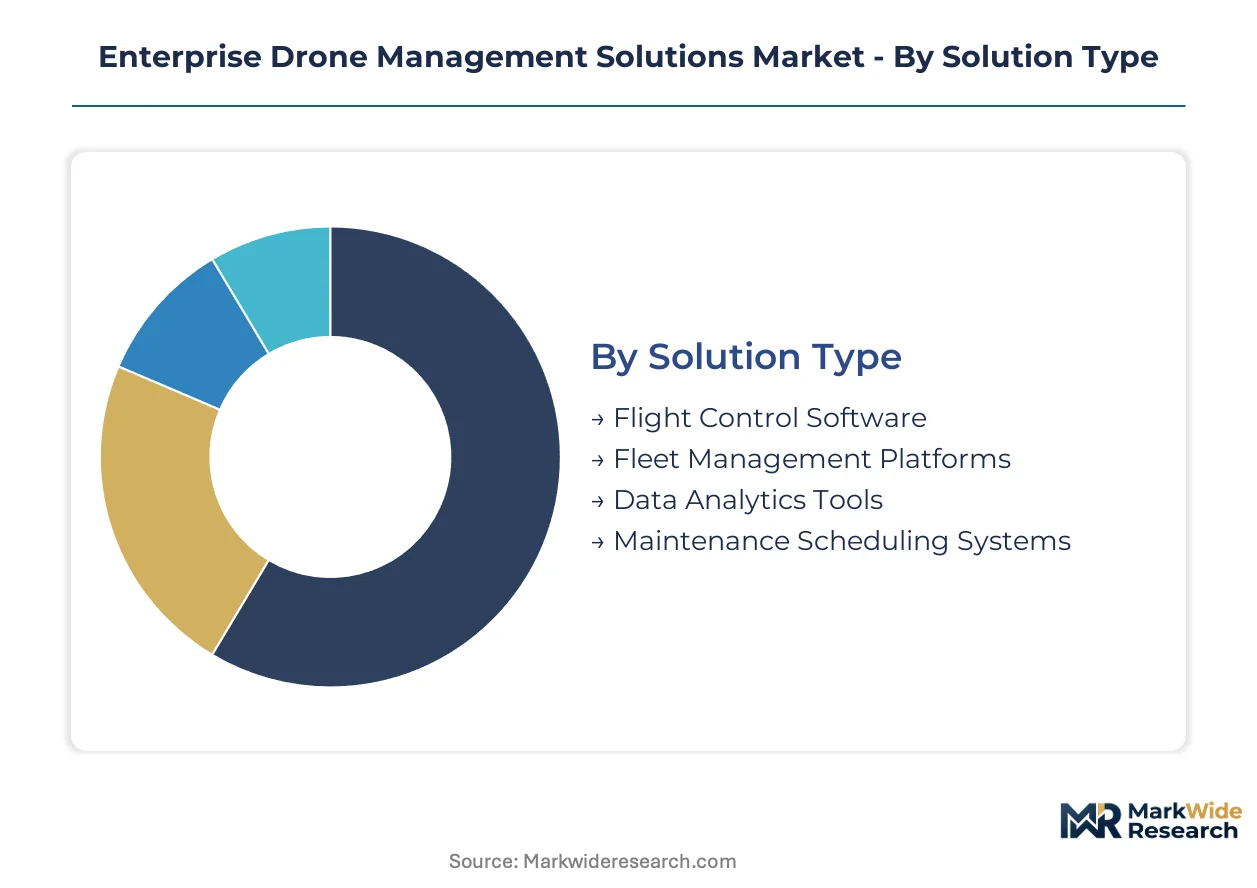
Enterprise operators assemble drone stacks through discrete procurement decisions across software, infrastructure, and operational domains. Segmentation reveals where standardization yields to customization as fleets scale beyond-visual-line-of-sight.
Solution Type:
Customization intensity varies sharply across this category, with modular compliance engines demanding bespoke development while flight control modules trend toward commoditization.
- Fleet Management Platforms:Unified command structures consolidate dispersed pilot teams under centralized scheduling and maintenance protocols. Energy operators in the United States and Germany are deploying these systems to synchronize multi-site inspection cycles, with EASA's specific category framework forcing modular compliance adaptations.
- Data Analytics Tools:Machine learning pipelines transform raw imagery into AI-derived asset condition scoring for predictive maintenance contracts. These tools command premium pricing in transmission line inspection programs where operators unbundle analytics subscriptions from hardware procurement.
- Flight Control Software:Real-time telemetry processing with sub-meter GPS correction enables autonomous navigation in GPS-denied environments.
- Maintenance Scheduling Systems:Predictive algorithms anticipate component failures before flight aborts, compressing downtime for commercial operators.
Most installed capacity flows through Fleet Management Platforms. Expansion is steepest in Data Analytics Tools.
Deployment Model:
Cost tier stratification dominates procurement decisions, with elastic compute premiums separating mid-sized operators from enterprise-scale deployments.
- Cloud-Based:Elastic infrastructure scales with seasonal inspection surges without capital-heavy on-premises investment. Mid-sized energy operators in Germany prioritize this model for grid maintenance cycles, though real-time telemetry processing costs strain budgets at scale.
- Edge Computing:Distributed architectures compress decision latency for autonomous navigation in underground mining operations. Australian operators deploy fused computer vision and RTK-GPS systems through edge nodes to enable one-to-many fleet supervision.
- Hybrid:Blended architectures balance sensitive data localization with burst compute elasticity.
- On-Premises:Air-gapped installations serve defense and critical infrastructure operators with stringent data sovereignty requirements.
Cloud-Based deployments hold the largest installed base. Edge Computing is gaining share fastest among autonomous navigation applications.
Application Area:
Application maturity determines whether operators deploy generalist platforms or pursue purpose-built specialization.
- Infrastructure Inspection:Transmission line and pipeline surveys leverage AI-derived condition scoring to prioritize maintenance spend. United States utilities now source flight services from third-party providers rather than maintaining captive fleets, disintermediating traditional bundled sales channels.
- Precision Agriculture:Crop health monitoring remains underpenetrated by generalist platforms, creating white space for specialized analytics. Purpose-built solutions occupy niches that larger fleet management vendors have not replicated.
- Public Safety Surveillance:Real-time situational awareness demands low-latency telemetry for emergency response coordination.
- Logistics & Delivery:Last-mile aerial cargo requires beyond-visual-line-of-sight corridor certification that remains limited to select jurisdictions.
Infrastructure Inspection carries the heaviest installed base. Precision Agriculture shows the steepest expansion trajectory as specialized platforms capture unserved demand.
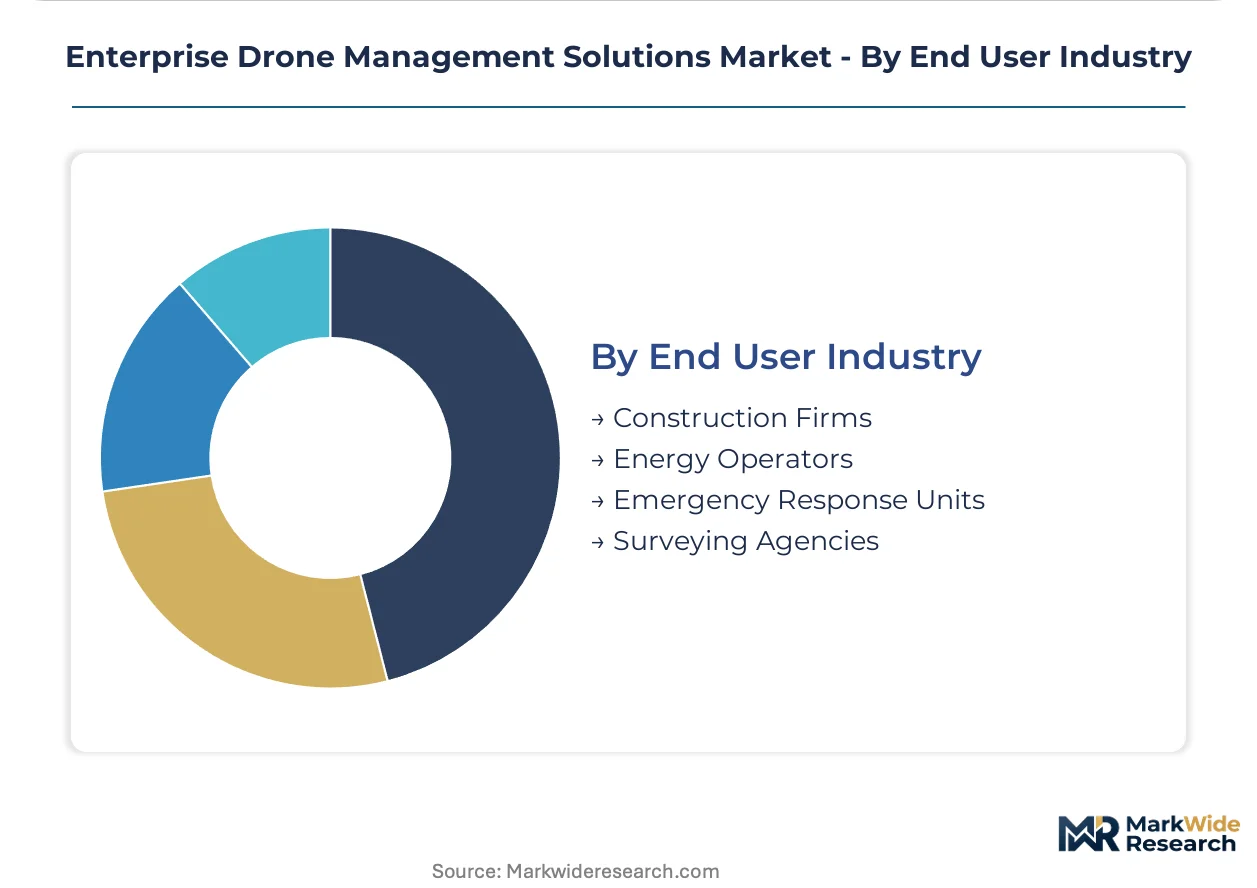
End User Industry:
Customer type segmentation reflects divergent procurement authority structures, from centralized corporate IT to distributed field operations.
- Energy Operators:Seasonal inspection surges drive demand for elastic compute deployments that scale with volume spikes. German grid operators and United States transmission utilities are unbundling predictive analytics from hardware procurement, reshaping vendor relationships.
- Construction Firms:Large-scale builders deploy centralized fleet management to synchronize aerial surveys across geographically dispersed project portfolios. Multi-site coordination requirements favor unified command structures over fragmented pilot operations.
- Emergency Response Units:Public safety agencies require FAA Part 107 and EASA specific category compliance for rapid deployment scenarios.
- Surveying Agencies:Geospatial professionals demand sub-meter GPS correction and photogrammetry workflow integration.
Energy Operators account for the largest deployment base. Construction Firms are expanding most quickly as fleet management platforms consolidate fragmented aerial survey operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where drone management vendors prioritize certification investments, with compliance cost differentials between jurisdictions driving platform localization strategies and partnership decisions.
United States
The FAA's Remote ID mandate and expanding beyond-visual-line-of-sight corridors are compelling infrastructure operators to upgrade command-and-control systems. Transmission utilities in Texas and California are unbundling predictive analytics from hardware procurement, sourcing flight services from specialized third-party providers rather than maintaining captive fleets.
Germany
Seasonal grid maintenance cycles are creating concentrated demand for elastic compute deployments that scale with inspection volume spikes. EASA's specific category framework is forcing vendors to modularize compliance engines, delaying product launches for multi-regional coverage. Industrial clusters in Bavaria and North Rhine-Westphalia anchor specialized agricultural analytics development.
Australia
Civil Aviation Safety Authority BVLOS frameworks are accelerating investment in compliant fleet orchestration platforms. Mining operators in Western Australia are deploying edge-computing architectures with fused computer vision and RTK-GPS systems for underground infrastructure mapping. Perth and Brisbane host concentrated pilot training and certification activity.
China
Manufacturing scale advantages in flight control modules are restructuring procurement patterns for Western software vendors. Domestic operators benefit from integrated hardware-software bundling that reduces deployment friction. Shenzhen and Beijing anchor development clusters where telemetry standardization and predictive maintenance algorithms are advancing rapidly.
Enterprise Drone Management Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native specialization and vertical analytics niches. The vendor landscape stratifies between hardware-software bundlers with manufacturing scale advantages and pure-play software platforms competing through workflow integration. Three archetypes dominate: integrated hardware-software providers, cloud-native mission planning specialists, and purpose-built vertical analytics vendors. Competitive moves center on modular compliance engine development for multi-jurisdiction coverage and predictive maintenance algorithm embedding to capture recurring revenue streams.
Within the cloud-native tier, DroneDeploy exemplifies workflow-centric positioning through photogrammetry and mission planning specialization. DJI anchors the integrated hardware-software archetype, leveraging manufacturing scale to dominate bundled procurement decisions. PrecisionHawk occupies the vertical analytics position, representing purpose-built agricultural solutions that generalist platforms have not replicated. These three entities collectively illustrate how competitive differentiation fragments across bundling strategy, cloud architecture, and sector-specific analytics depth.
| Leading Market Players |
|---|
| DroneDeploy |
| DJI |
| Skycatch |
| Skyward |
| Kespry |
| PrecisionHawk |
| Aerodyne Group |
| Airware |
| Pix4D |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FAA Part 107-compliant platforms and uncertified alternatives manifests in both subscription pricing tiers and hardware sourcing complexity. Premium fleet management vendors command recurring revenue premiums through modular compliance engines while mid-tier operators absorb elevated procurement costs from Asia-Pacific flight control module dependencies.
Pricing Analysis
Distributor margins on cloud-native mission planning platforms compress as direct-to-energy-operator sales channels expand. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth and GPS correction precision. Pricing pressure stems from hardware-software bundling concentration among Shenzhen-based manufacturers. Mid-sized construction firms exhibit highest price sensitivity, while transmission utilities prioritize predictive analytics accuracy over subscription cost.
Supply Chain Analysis
Freight cost volatility on semiconductor shipments from Taiwan and South Korea disrupts just-in-time delivery schedules for RTK-GPS correction modules. Flight control hardware concentrates in China, with specialized edge-computing components sourced from Japan and Germany. Supply chain risk centers on single-source vulnerability for sub-meter GPS chipsets. Distribution runs through specialized industrial distributors serving energy and mining verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge where EASA's specific category compliance costs exceed FAA Part 107 certification burdens, favoring vendors with modular jurisdiction-switching capabilities.
For Market Incumbents: Anchor market position through backward integration into predictive maintenance algorithm development and exclusive channel partnerships with German grid operators. Cloud-native specialists threaten bundled hardware-software margins through unbundled analytics subscriptions. Certification investment in Australia's CASA BVLOS frameworks provides defensive moat against Asia-Pacific bundlers.
For New Entrants and Emerging Players: Mid-sized agricultural cooperatives remain underserved by generalist fleet management platforms, presenting white-space entry through purpose-built crop health monitoring workflows. Precision agriculture applications show lowest competitive density relative to infrastructure inspection saturation. Go-to-market through agricultural equipment dealerships with embedded pilot training bundles accelerates adoption.
For Investors and Strategic Acquirers: Consolidation pressure builds where jurisdictional certification redundancy forces redundant R&D overhead across FAA, EASA, and CASA compliance engines. Long-term viability favors platforms with modular architecture enabling geographic expansion without feature replication. Acquisition targets include edge-computing specialists with mining-sector validation. Watch for mutual recognition agreements between aviation authorities as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Compliance Engine Development | EASA's specific category framework forces jurisdiction-by-jurisdiction adaptation rather than global platform shipments. |
| Predictive Maintenance Algorithm Embedding | Energy utilities in Texas and California now unbundle analytics subscriptions from hardware procurement entirely. |
| Edge Computing Architecture Deployment | Australian mining operators in Western Australia deploy fused computer vision and RTK-GPS for underground mapping. |
| Vertical Analytics Specialization | Agricultural analytics providers in Bavaria prioritize EU certification ahead of feature expansion. |
| Third-Party Flight Service Partnership | United States transmission utilities source inspection services from specialized providers rather than captive fleets. |
Research Methodology
Direct dialogue with fleet operations managers, aviation regulatory consultants, energy utility planning officers, and cloud platform engineers grounded qualitative findings. Secondary validation drew from FAA Remote ID implementation guidance, EASA specific category framework documentation, CASA BVLOS corridor approvals, and hyperscaler drone platform capex disclosures. Bottom-up and top-down triangulation cross-checked vendor shipment estimates against operator deployment surveys.
Bottom-up modeling aggregated segment-level adoption curves across fleet management platforms, data analytics tools, flight control software, and maintenance scheduling systems. Top-down validation applied energy inspection cycle seasonality and construction project pipeline data. CAGRs derived from regression analysis of historical deployment velocity against regulatory milestone timing. Modeled inputs included BVLOS corridor certification pace and elastic compute pricing trajectories.
Inputs from aviation authority filing databases and utility procurement records were available through the study window; gaps in real-time telemetry cost benchmarking introduce uncertainty bands around cloud-deployment forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Aerial Smart Weapons Market
UAV
UAV Payload Market
UAV
Global Drone Analytics Market
UAV
Drone Data Management Market
UAV
Industrial Drones Market
UAV
Tethered Drones Market
UAV
Global Smart Commercial Drones Market
UAV
Global Drone Sensor Market
UAV
Nano Drones Market
UAV
Anti-Drone Technology Market
UAV
North America Fuel Cell UAV Market
UAV
Inspection Drones in Confined Space Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Short-Range Delivery Drone Market
UAV
Europe Small UAV Market
UAV
Drone-Based Consulting Services Market