
 North America Luxury Appliance Market | 2026-2036
North America Luxury Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Luxury Appliance Market Analytics
Built-in refrigeration with integrated paneling is rotating the North America luxury appliance market toward whole-kitchen aesthetic systems. Sub-Zero Group, Inc. anchors this shift with its proprietary dual-compression architecture that extends freshness intervals. Viking Range LLC competes through its heritage-positioned professional ranges that dominate the open-kitchen segment. Miele differentiates via its in-house production of brushless motors and proprietary water-softening systems for dishwashing.
North America luxury appliances comprise premium-grade cooking, cooling, cleaning, and climate-control equipment engineered for residential and commercial installations demanding superior materials, acoustic performance, and design cohesion. Stainless steel gauges below 16, sealed burner systems exceeding 23,000 BTU, and decibel ratings under 40 dB define the technical threshold separating luxury from mass-market tiers. Refrigerators and smart appliances command the deepest margin pools, while connected devices represent the fastest-expanding technology dimension as Wi-Fi-enabled diagnostics and remote preheat functions become baseline expectations. The residential end user segment sustains volume leadership, though hotels are emerging as a high-velocity channel for built-in specification.
The U.S. Department of Energy and Natural Resources Canada jointly shape efficiency mandates that determine product eligibility for rebate programs and import certification. The EPA's ENERGY STAR Most Efficient designation and California's Title 20 appliance regulations create a dual-compliance floor that filters out non-compliant manufacturers. CSA Group standards govern electrical safety across Canadian provinces, adding a parallel testing requirement for cross-border distribution. Stakeholders must monitor how pending federal efficiency tier revisions will force compressor redesigns and whether smart-appliance cybersecurity frameworks will emerge as a new compliance dimension.
Market Dynamics
The U.S. Department of Energy's compressor efficiency mandates are forcing wholesale redesigns of cooling systems, compressing development cycles while elevating technical barriers to entry across the North American market.
Growth Catalysts
- California's Title 20 regulations:The state's appliance efficiency standards create a premium tier for compliant manufacturers, concentrating demand among builders seeking rebate eligibility for custom residential projects.
- Smart kitchen integration:Wi-Fi-enabled diagnostics and remote preheat functions have become baseline expectations in California's custom home segment, accelerating replacement cycles.
- Hotel channel expansion:Built-in specification is emerging as a high-velocity channel, with hospitality developers prioritizing acoustic performance and design cohesion for luxury properties.
Market Restraints
- Copper and steel input volatility:Stainless steel gauges below 16 define luxury thresholds, exposing manufacturers to commodity price swings that compress margin pools on refrigeration lines.
- Cross-border testing requirements:CSA Group standards for Canadian electrical safety impose parallel certification costs, fragmenting production planning for U.S.-based assembly operations.
- Compressor redesign capex:Dual-compression architecture development demands specialized engineering talent scarce in domestic labor markets, extending product launch timelines.
Strategic Opportunities
- Texas high-end residential construction:Austin's luxury housing pipeline is accelerating built-in appliance specification, creating geographic white space beyond traditional coastal demand centers.
- ENERGY STAR Most Efficient designation:The EPA's premium certification tier offers rebate access and retail differentiation for manufacturers achieving superior thermal performance metrics.
- Climate-control convergence:Integration of precision cooling with whole-home energy management systems is opening specification opportunities in net-zero residential developments.
Industry Challenges
- Brushless motor engineering scarcity:In-house production of advanced drive systems requires specialized electromechanical expertise concentrated among a limited supplier base.
- Dual-compliance timeline compression:Simultaneous U.S. DOE and Natural Resources Canada efficiency revisions are forcing concurrent redesign cycles that strain R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Luxury Appliance Market |
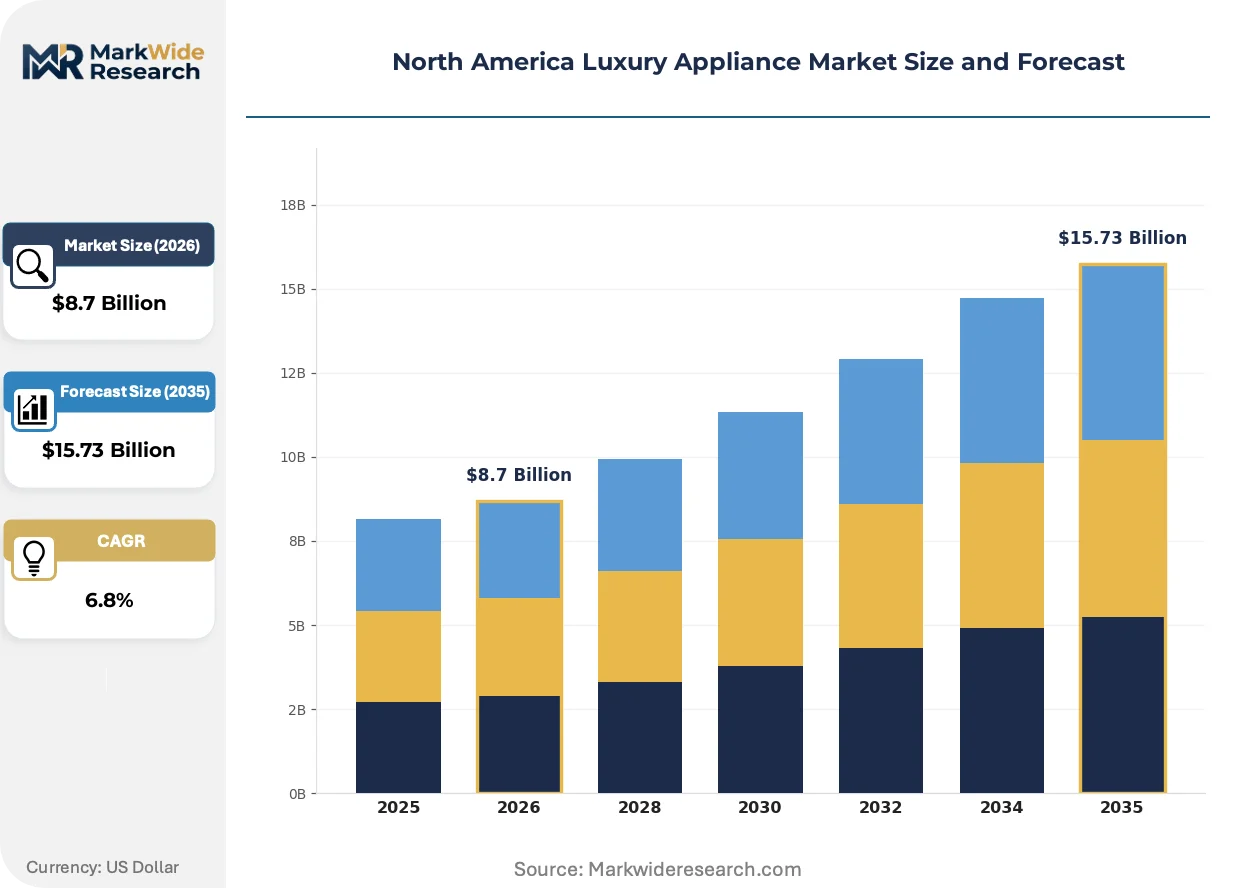
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Washers End User: Residential, Hotels, Restaurants, Retailers Technology: Smart Appliances, Energy Efficient, Connected Devices, Traditional Appliances Distribution Channel: Online Sales, Showrooms, Retail Stores, Direct Sales |
| Companies Covered | Dacor, Inc., Viking Range LLC, Sub-Zero Group, Inc., JennAir, GE Appliances (Monogram), Miele, Thermador, Electrolux Group, BSH Home Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Luxury Appliance Market Evolving Landscape
Built-in refrigeration with integrated paneling is rotating the market toward whole-kitchen aesthetic systems, while regulatory pressure and procurement evolution reshape competitive requirements.
Variable-speed inverter compressors are displacing traditional single-speed units in premium refrigeration lines. Custom home builders in California and Florida are specifying these systems for humidity control precision. The technology is displacing legacy fixed-speed architectures by enabling tighter temperature bands that extend produce freshness intervals.
Natural Resources Canada's joint efficiency mandates with the U.S. Department of Energy are synchronizing cross-border certification requirements. Manufacturers must now design for a unified testing protocol covering both markets. Refrigeration product lines face the steepest compliance burden, with redesign cycles compressed to maintain ENERGY STAR eligibility.
Direct-to-developer specification is eroding traditional distributor influence in luxury residential construction. High-end builders in Miami and Austin now engage manufacturers for whole-kitchen package pricing, bypassing regional appliance dealers. This channel compression is most visible in multi-unit luxury developments where design cohesion commands premium positioning.
North America Luxury Appliance Market Segmentation
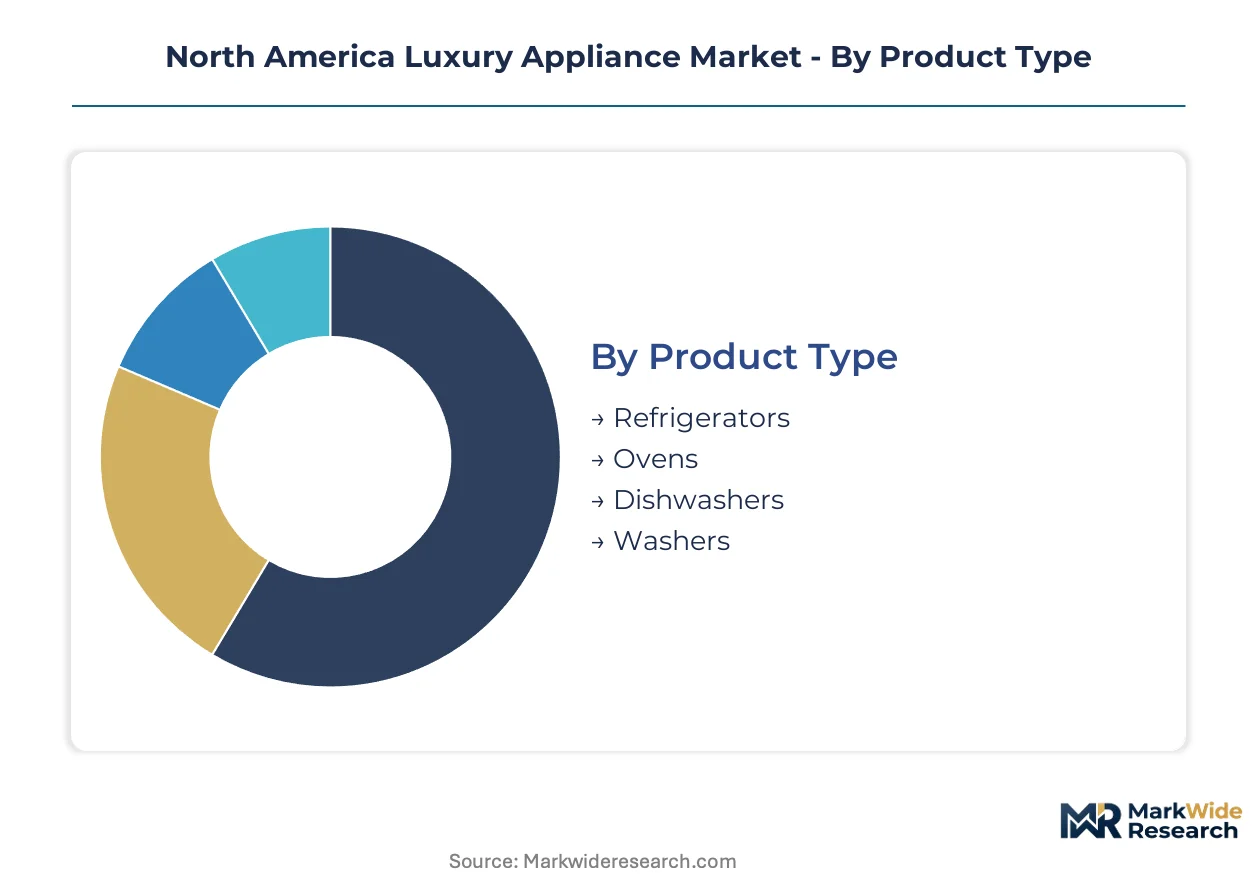
Segmentation in the North America luxury appliance market reveals how regulatory pressure and procurement evolution reshape competitive requirements across distinct buyer clusters. Understanding these divides exposes where margin pools concentrate and which channels are compressing traditional distributor influence.
Product Type:
Refrigeration lines dominate domestic specification volume, while cooking equipment shows stronger cross-border export alignment with Canadian hospitality developers.
- Refrigerators:Built-in units with integrated paneling and dual-compression architecture define the premium tier, with demand concentrating in California's custom home segment where ENERGY STAR Most Efficient eligibility determines builder procurement. The U.S. Department of Energy's compressor mandates are forcing wholesale cooling system redesigns that elevate technical barriers.
- Ovens:Professional-grade ranges exceeding 23,000 BTU anchor open-kitchen specifications, with Austin's luxury housing pipeline accelerating built-in appliance adoption beyond traditional coastal centers. Sealed burner systems and acoustic performance under 40 dB separate luxury from mass-market tiers.
- Dishwashers:In-house brushless motor production and proprietary water-softening systems characterize premium lines. Texas and Florida custom builders specify these for whole-kitchen package pricing.
- Washers:Precision temperature control and sub-40 dB operation define luxury thresholds. Demand clusters in net-zero residential developments requiring climate-control convergence.
Refrigerators hold the largest share; momentum sits with ovens as open-kitchen design expands beyond coastal markets.
End User:
Residential buyers concentrate in high-end construction corridors, while hospitality developers prioritize acoustic performance and design cohesion for multi-unit luxury properties.
- Residential:Custom home builders in California, Texas, and Florida drive specification volume, with smart kitchen integration now a baseline expectation rather than premium upgrade. Wi-Fi-enabled diagnostics and remote preheat functions accelerate replacement cycles in this segment.
- Hotels:Built-in specification is emerging as a high-velocity channel, with Miami and Austin hospitality developers engaging manufacturers directly for whole-kitchen package pricing that bypasses regional dealers.
- Restaurants:Professional-grade equipment with sealed burner systems and stainless steel gauges below 16 define procurement standards. Cross-border distribution to Canada requires parallel CSA Group certification.
- Retailers:Showroom-based specification is eroding as direct-to-developer engagement grows, though high-end retail maintains influence in replacement cycles and design-conscious consumer segments.
Residential commands volume leadership; hotels are climbing the fastest as a specification channel.
Technology:
Smart functionality concentrates development investment, while energy efficiency determines regulatory compliance and rebate access across both U.S. and Canadian markets.
- Smart Appliances:Wi-Fi-enabled diagnostics, remote preheat functions, and connected energy management integration define this tier. California's Title 20 regulations and custom builder expectations make smart features baseline rather than premium.
- Energy Efficient:Variable-speed inverter compressors and superior thermal performance metrics qualify products for ENERGY STAR Most Efficient designation and associated rebate programs. Natural Resources Canada and U.S. DOE joint mandates synchronize cross-border testing protocols.
- Connected Devices:Remote monitoring and predictive maintenance capabilities target hospitality and multi-unit residential developers prioritizing operational uptime.
- Traditional Appliances:Non-connected, fixed-speed architectures persist in replacement cycles and price-sensitive luxury tiers, though regulatory pressure is compressing their market position.
Smart appliances hold the largest share; energy efficient lines are gaining share fastest as compliance deadlines approach.
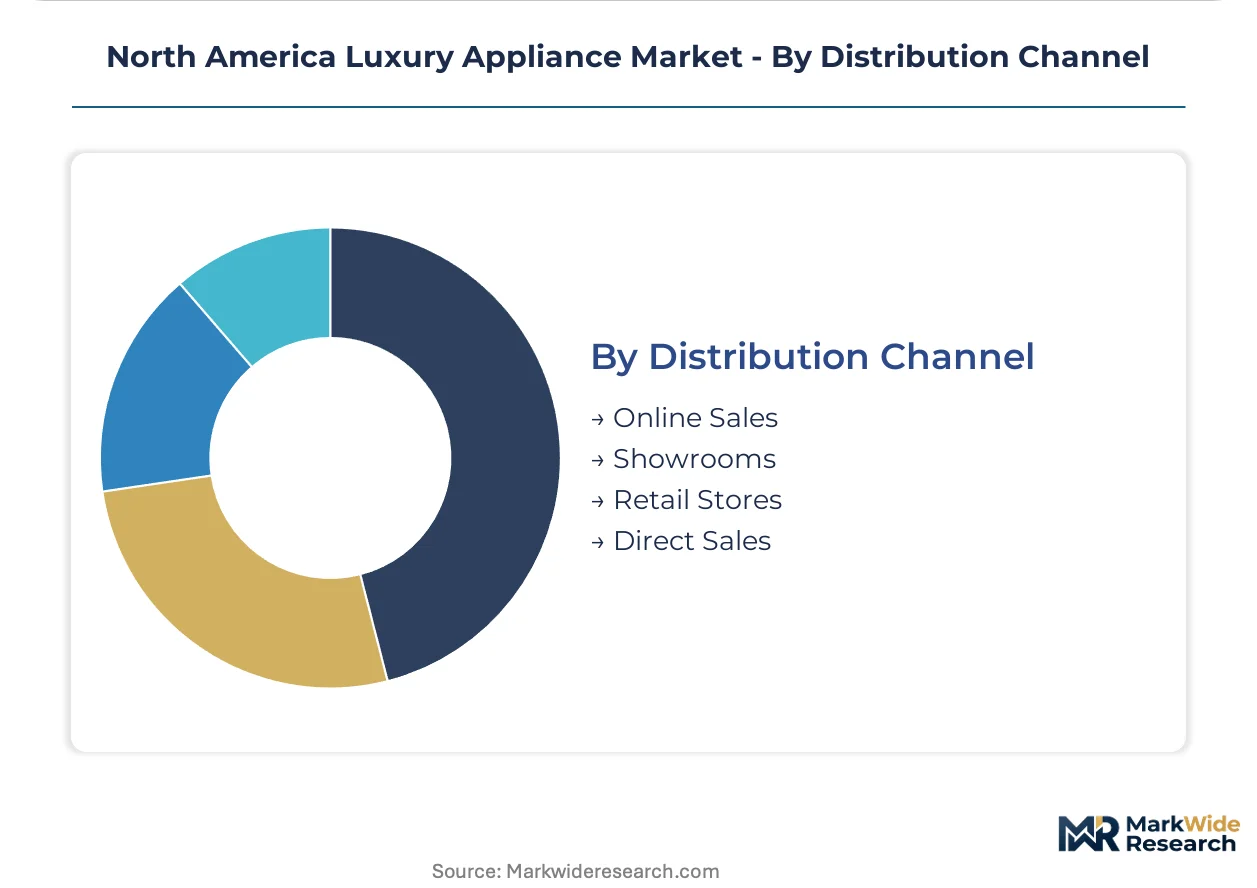
Distribution Channel:
Direct engagement is displacing traditional intermediaries in new construction, while showrooms retain influence in replacement and renovation cycles.
- Online Sales:Digital procurement is expanding for replacement appliances and standard configurations, though custom built-in specification still requires physical consultation for design cohesion.
- Showrooms:Design-focused display environments maintain relevance for consumer renovation projects and builder design center partnerships, particularly in California and Florida markets.
- Retail Stores:Regional appliance dealers face channel compression as Austin and Miami developers engage manufacturers directly for whole-kitchen package pricing.
- Direct Sales:Manufacturer-to-developer relationships are eroding distributor influence in multi-unit luxury developments where acoustic performance and design cohesion command premium positioning.
Direct sales hold the largest share; online sales show the steepest expansion trajectory as replacement cycles digitalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Texas and Florida show the least price sensitivity to premium built-in specification, while Canadian hospitality developers face stricter cross-border compliance costs that compress margin tolerance. California's custom home segment anchors volume leadership through rebate-eligible efficiency procurement. Mexico's emerging luxury residential corridor introduces new geographic white space for manufacturer-direct engagement.
United States
Austin and Miami luxury housing pipelines are accelerating whole-kitchen package specification beyond traditional coastal centers. The U.S. Department of Energy's compressor efficiency mandates are forcing wholesale cooling system redesigns that elevate technical barriers for domestic manufacturers. California's Title 20 regulations concentrate demand among builders seeking ENERGY STAR Most Efficient eligibility for custom residential projects.
Canada
Natural Resources Canada's joint efficiency mandates with U.S. regulators are synchronizing cross-border certification requirements for refrigeration product lines. CSA Group standards govern electrical safety across Canadian provinces, adding parallel testing costs that fragment production planning for U.S.-based assembly operations. Toronto and Vancouver hospitality developers prioritize acoustic performance and design cohesion for multi-unit luxury properties.
Mexico
Mexico City and Nuevo León luxury residential construction is creating geographic white space for manufacturer-direct specification channels. The country's national energy efficiency regulator is developing appliance standards that may converge with U.S. DOE timelines. Monterrey industrial clusters are attracting component suppliers seeking proximity to Texas demand centers.
North America Luxury Appliance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American luxury appliance market. The vendor base clusters around heritage-positioned professional range specialists, integrated refrigeration architects, and European-engineered system houses. Three strategic archetypes dominate: dual-compression refrigeration innovators, sealed-burner cooking equipment heritage brands, and in-house electromechanical production specialists. Competitive moves center on direct-to-developer channel compression and compressor architecture redesign cycles forced by regulatory deadlines.
Among heritage-positioned American fabricators, Viking Range LLC and Sub-Zero Group, Inc. anchor the professional-grade and integrated refrigeration tiers respectively. Miele represents the European-engineered archetype with in-house production capabilities. These three occupy positions that exemplify the market's segmentation between cooking heritage, cooling architecture, and electromechanical vertical integration.
| Leading Market Players |
|---|
| Dacor, Inc. |
| Viking Range LLC |
| Sub-Zero Group, Inc. |
| JennAir |
| GE Appliances (Monogram) |
| Miele |
| Thermador |
| Electrolux Group |
| BSH Home Appliances |
| Others |
Value Network & Pricing Analysis
Ninety-day compressor lead times from specialty electromechanical suppliers concentrate pricing power among dual-compression refrigeration architects while forcing project-based contract structures on Texas and Florida custom builders seeking whole-kitchen package certainty. This inventory compression elevates after-service revenue as a margin defense against commodity input swings.
Pricing Analysis
After-service contracts and replacement parts drive lifetime value capture in built-in refrigeration lines, with three-tier pricing structure across premium, standard, and economy levels separating ENERGY STAR Most Efficient certified units from rebate-ineligible alternatives. Price differentiation hinges on California Title 20 compliance tier and acoustic performance certification under 40 dB. Cost compression in standard-tier cooking equipment is intensifying because of copper and steel input volatility. Residential replacement buyers show highest price sensitivity; Miami hospitality developers show least.
Supply Chain Analysis
China and South Korea anchor brushless motor and inverter compressor fabrication for North American luxury appliance assembly, while domestic U.S. plants handle final integration and panel customization. Raw material dependencies center on cold-rolled stainless steel below 16 gauge, copper winding wire, and rare-earth magnet feedstock. Single-source vulnerability in specialized compressor engineering talent strains R&D bandwidth. Distribution runs through direct-to-developer channels for new construction and showroom partnerships for renovation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around procurement pattern shifts as direct-to-developer engagement bypasses traditional regional dealers, creating niche entry points for specialized component suppliers and climate-control convergence specialists.
For Market Incumbents: Shield compressor architecture leadership by capturing scarce electromechanical engineering talent through targeted recruitment in Midwest industrial corridors. Deepen backward integration into brushless motor production to offset supplier concentration risk. Defend against emerging European system houses by accelerating ENERGY STAR Most Efficient certification timelines ahead of U.S. DOE mandate deadlines.
For New Entrants and Emerging Players: Anchor in Texas high-end residential construction corridors where Austin's luxury housing pipeline outpaces established coastal supply relationships. Target net-zero residential developments requiring climate-control convergence as the most penetrable application segment. Pursue manufacturer-direct specification partnerships with Miami hospitality developers seeking acoustic performance guarantees.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because direct-to-developer channel compression favors scaled players with captive compressor engineering capabilities. Acquisition target archetype: mid-cap specialists with in-house electromechanical production and CSA Group cross-border certification infrastructure. Watch U.S. DOE efficiency tier revision announcements as inflection signal for forced redesign cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Architecture Redesign | U.S. DOE mandates force dual-compression development to maintain ENERGY STAR eligibility. |
| Direct-to-Developer Channel Buildout | Bypasses regional dealers in Austin and Miami multi-unit luxury developments. |
| Cross-Border Certification Investment | CSA Group parallel testing secures Natural Resources Canada rebate access. |
| Smart Kitchen Platform Integration | Wi-Fi-enabled diagnostics meet California custom builder baseline expectations. |
| Climate-Control Convergence Development | Precision cooling integration targets net-zero residential specification opportunities. |
Research Methodology
Initial hypotheses were tested against primary input from custom home builders, hospitality procurement directors, compressor engineering specialists, and regional appliance distributors and refined through secondary validation against U.S. DOE efficiency filings, Natural Resources Canada certification databases, EPA ENERGY STAR product listings, and CSA Group testing protocols. Bottom-up demand modeling triangulated against top-down construction permit data.
Variance decomposition across the projection horizon isolates volume sensitivity to regulatory deadline timing, commodity input bands, and channel shift velocity. Segmentation dimensions span product type, end user archetype, technology tier, and distribution channel. CAGRs derive from installed base replacement cycles and new construction specification rates. Forecast inputs incorporate California Title 20 compliance trajectories and Texas luxury housing pipeline velocity.
Material uncertainties — U.S. DOE efficiency tier revision timing, copper and steel price volatility, and smart-appliance cybersecurity framework emergence — sit outside the modeled envelope. Forecasts reflect assumptions about cross-border certification synchronization and developer procurement pattern stability. Recalibration cycles align with material shifts in federal mandate announcements and commodity futures curve movements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
White Goods Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
North America Home Appliances Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Residential Cooker Hoods Market