
 UAE Dog Food Market | 2026-2036
UAE Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Dog Food Market Intelligence
Cold-pressed and minimally processed kibble manufacturing is tilting formulation priorities toward nutrient retention and digestibility claims. Mars GCC leverages its regional production footprint to anchor shelf presence across UAE hypermarket chains. Naturally for Pets LLC specializes in grain-free and raw-aligned SKUs that compete on ingredient transparency rather than price. Nestlé Middle East FZE extends its Purina portfolio through veterinary channel partnerships that control professional recommendation flows.
Dog food encompasses complete and complementary nutrition products formulated to meet canine dietary requirements across life stages, with dry extruded kibble typically containing 18-32% protein, 10-20% fat, and moisture levels below 10% for shelf stability. Premium brand segments capture disproportionate margin pools as Emirati consumers trade up to functional ingredient claims including joint support and digestive health. Online retail channels are gaining fastest among sales channels, though pet stores retain high engagement for trial-sized purchases and breed-specific consultation. Mid-range positioning faces compression as private label entrants from supermarket operators occupy value-tier shelf space.
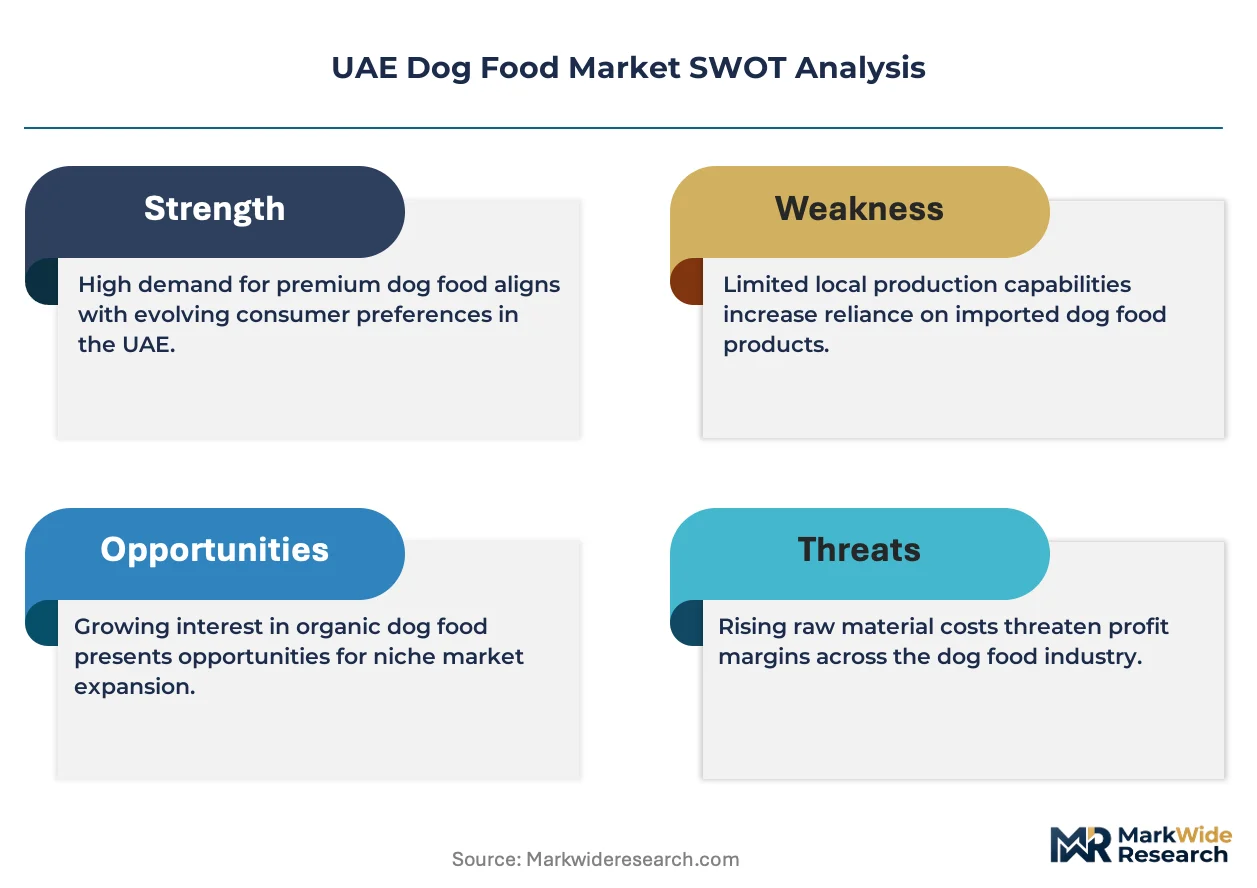
MOCCAE enforces import permit requirements and Arabic labeling mandates that shape product registration timelines for international suppliers. The Emirates Authority for Standardization and Metrology (ESMA) governs pet food safety specifications under UAE standards alignment with Codex principles. FSSAI-equivalent Gulf coordination through GCC Standardization Organization (GSO) frameworks creates overlapping compliance obligations for brands distributing across multiple Gulf states. Stakeholders must monitor evolving MOCCAE enforcement intensity on novel protein claims and raw food safety protocols as premium segment innovation accelerates.
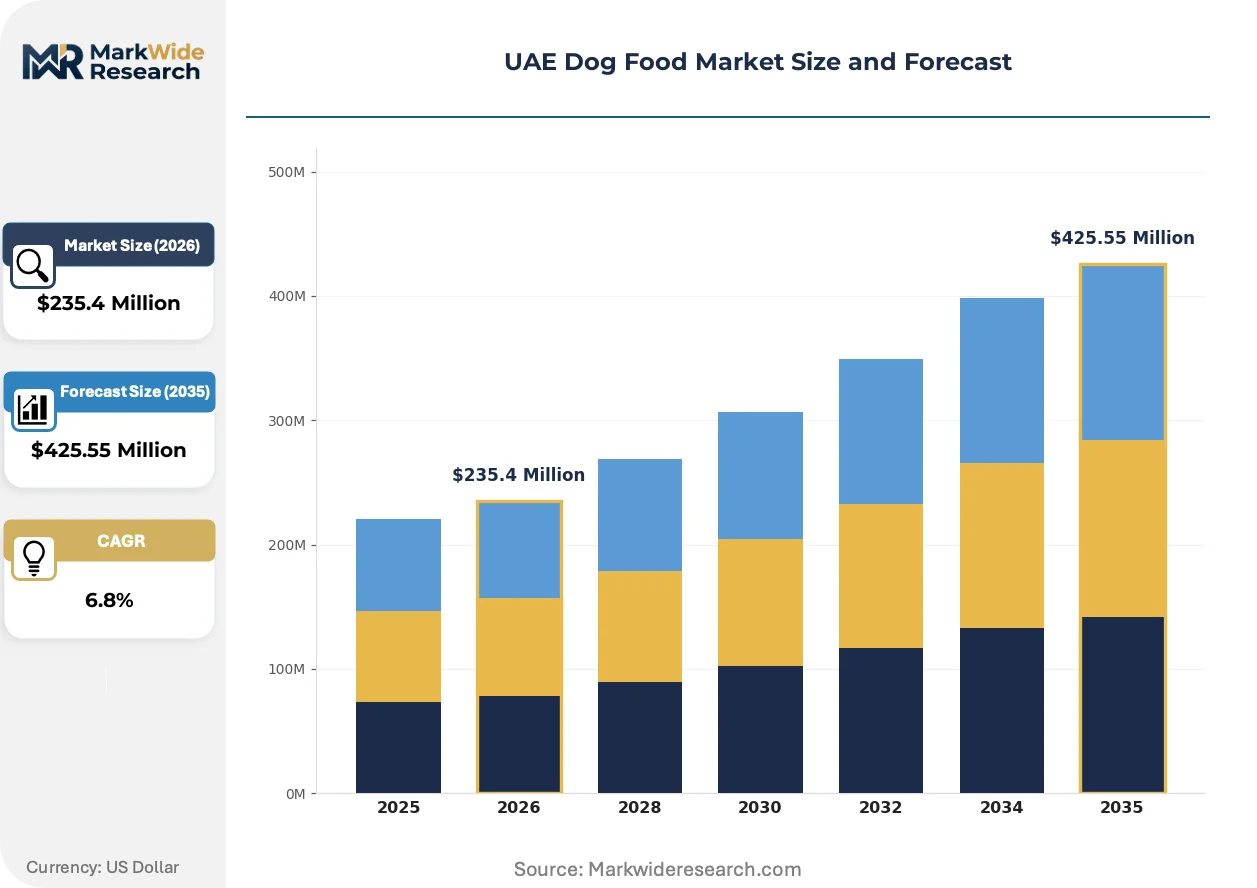
Market Dynamics
MOCCAE's tightened import permit and Arabic labeling mandates are restructuring competitive entry barriers, forcing international suppliers to extend registration timelines and localize packaging operations before shelf placement.
Growth Catalysts
- ESMA Safety Alignment:Codex-based pet food specifications under Emirates Authority for Standardization and Metrology governance are elevating consumer trust in commercial nutrition products.
- Dubai Expatriate Density:High-income professional communities concentrated in Dubai Marina and Downtown districts sustain premium pet retail foot traffic and veterinary-channel loyalty.
- Cold-Press Formulation:Nutrient-retention processing methods are capturing formulation R&D investment as manufacturers compete on digestibility claims.
Market Restraints
- Protein Input Volatility:Novel protein sourcing from insect meal and hydrolyzed fish creates price instability for mid-tier brands without captive supply contracts.
- GCC Regulatory Overlap:Gulf Standardization Organization framework alignment forces redundant compliance testing for brands distributing across Saudi Arabia, Kuwait, and Qatar.
- Raw Food Safety Friction:MOCCAE enforcement intensity on unprocessed frozen diets limits segment expansion despite consumer interest.
Strategic Opportunities
- Abu Dhabi Veterinary Channel:Underdeveloped specialist clinic networks in Khalifa City and Al Raha Beach present white-space for professional recommendation capture.
- Subscription Direct-to-Consumer:Auto-replenishment platforms bypass hypermarket slotting fees while capturing lifetime value from multi-dog households.
- Functional Ingredient Premiumization:Joint support and digestive health claims command shelf price multiples that offset formulation cost inflation.
Industry Challenges
- Arabic Labeling Talent Scarcity:Technical translation capacity for veterinary terminology bottlenecks product registration timelines.
- Multi-Channel Inventory Fragmentation:Separate stock-keeping requirements for pet store trial sizes, veterinary prescription formats, and e-commerce bulk SKUs strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Dog Food Market |
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $425.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Ingredients Sales Channel: Online Retail, Supermarkets, Pet Stores, Direct Sales Brand Segment: Premium, Mid-Range, Economy, Private Label |
| Companies Covered | Saint Vincent Group GT LLC, Naturally for Pets LLC, Charoen Pokphand Group, Pet Shop LLC, Nestlé Middle East FZE, Thumbay Marketing & Distribution Co, Mars GCC, Real Pet Food Co, Waitrose Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Dog Food Market Strategic Shifts & Innovations
Formulation science and channel architecture are simultaneously transforming how nutrition reaches canine end-users, with processing methods and purchase pathways undergoing parallel reinvention.
Cold-pressed kibble manufacturing is collapsing the nutrient-degradation tradeoff that historically forced brands to choose between shelf stability and bioavailability claims. Premium-positioned manufacturers in Dubai's Al Quoz industrial zone are retrofitting extrusion lines to operate at sub-90°C temperatures. The structural consequence is compression of the mid-market segment as consumers migrate to transparency-positioned brands without accepting raw-frozen inconvenience.
MOCCAE's 2024 enforcement circular on novel protein substantiation is accelerating laboratory testing partnerships between importers and Dubai-based analytical facilities. The industrial consequence is extended product launch timelines for international entrants without regional quality infrastructure. Brands with existing UAE registration dossiers are capturing shelf space as competitors navigate documentation backlogs.
Pet owner purchasing is fragmenting across channel types based on life-stage needs, with trial-sized acquisition concentrating in physical retail while replenishment shifts to platform commerce. Boutique pet stores in Jumeirah and Al Barsha retain high engagement for breed-specific consultation and new product sampling. This behavioral bifurcation is most visible among millennial expatriate households maintaining multiple large-breed dogs.
UAE Dog Food Market Segmentation
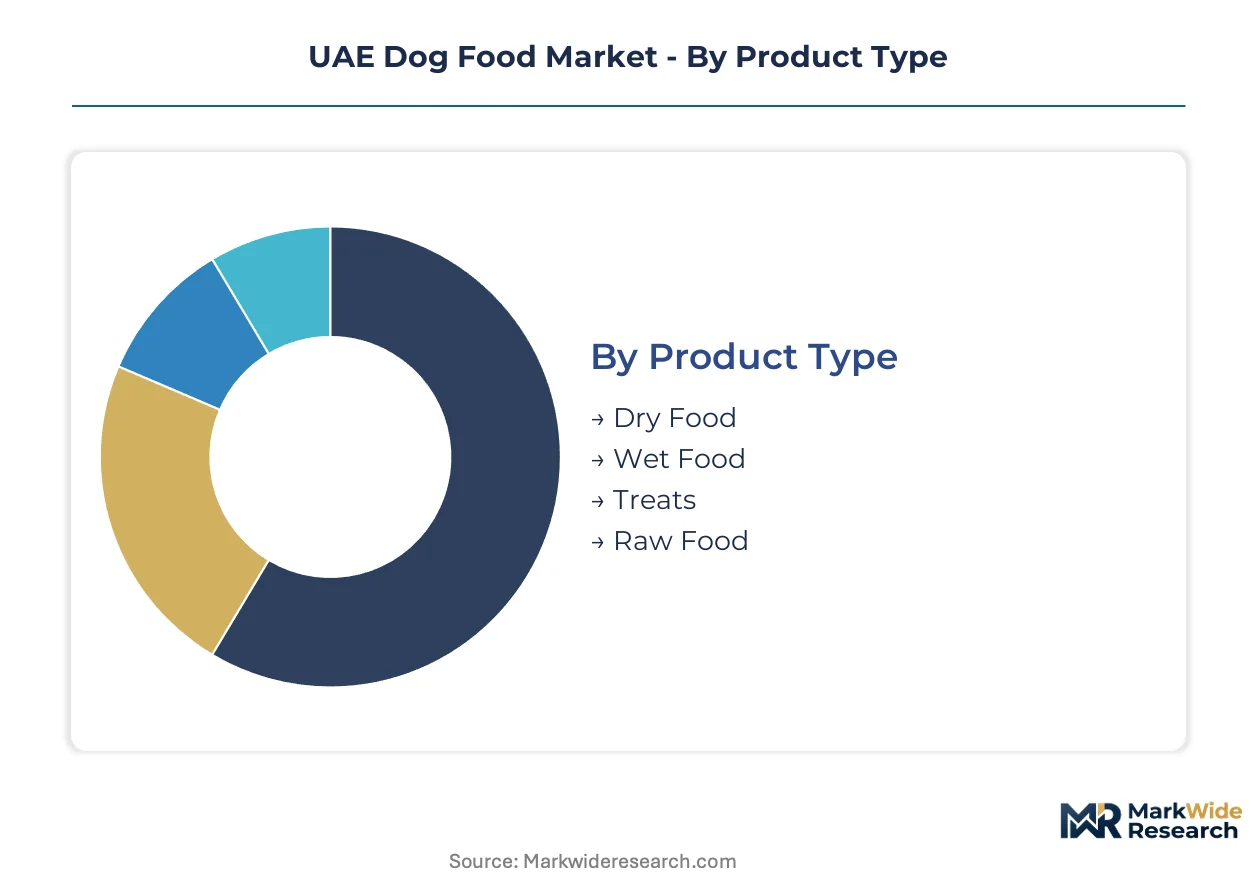
UAE dog food purchasing fragments across four distinct category axes, each governing different margin pools and inventory velocity. Product type determines manufacturing capital intensity, while sales channel ownership separates subscription platforms from physical retail slotting fee economics.
Product Type:
Inventory turns vary dramatically across this category, with wet food requiring cold chain logistics that compress shelf life against dry kibble's 18-month stability window.
- Dry Food:Extruded kibble formulations with 6-10% moisture content dominate household penetration due to storage convenience and cost-per-calorie efficiency. Dubai Marina and Downtown expatriate households sustain premium dry food demand through bulk purchasing patterns that favor 15-20kg bag formats.
- Wet Food:Canned or pouch formats with 75-85% moisture content command higher per-serving margins and address hydration-sensitive breeds. Abu Dhabi's Al Raha Beach veterinary clinics recommend wet food for renal health management, creating professional endorsement channels that bypass supermarket price competition.
- Treats:Functional reward formats with dental or training positioning rotate fastest at Jumeirah boutique retailers where trial-sized SKUs drive impulse attachment.
- Raw Food:Frozen or freeze-dried unprocessed diets face MOCCAE safety protocol friction that limits retail distribution to specialized cold storage facilities in Al Quoz industrial zones.
Dry food dominates installed base. Raw food is where expansion concentrates despite regulatory headwinds.
Ingredient Type:
Cost tier separation runs deepest here, with organic certification adding 40-60% formulation cost premiums that filter customer self-selection.
- Meat-Based:Traditional protein-forward formulations using chicken, beef, or lamb meal as primary ingredients. Khalifa City hypermarkets move volume through familiar protein claims that reduce consumer education burdens.
- Grain-Free:Carbohydrate-restricted recipes substituting legumes or tubers for wheat and corn. Al Barsha pet stores report grain-free SKUs climbing fastest among French Bulldog and Golden Retriever owners seeking digestive sensitivity solutions.
- Organic:Certified ingredient chains with documented pesticide and antibiotic exclusion. ESMA-aligned documentation requirements extend registration timelines for international suppliers without UAE quality infrastructure.
- Functional Ingredients:Glucosamine, probiotics, and omega fatty acid fortification targeting joint mobility and coat condition. Veterinary channel partnerships in Dubai Healthcare City control professional recommendation flows for this segment.
Meat-based formulations dominate installed base. Functional ingredients represent the fastest-growing trajectory as aging pet populations drive preventive health spending.
Sales Channel:
Customer type bifurcation separates subscription auto-replenishment households from consultative first-time buyers requiring breed-specific guidance.
- Online Retail:Platform commerce with auto-replenishment algorithms capturing multi-dog household lifetime value. Noon and Amazon UAE fulfillment centers in Dubai South enable next-day delivery that erodes pet store convenience advantages.
- Supermarkets:Carrefour and Lulu hypermarket chains leverage private label penetration to occupy value-tier shelf space. Mid-range brands face compression as retailer-owned SKUs capture price-sensitive volume.
- Pet Stores:Jumeirah and Al Barsha boutiques sustain high engagement through trial-sized sampling and breed-specific consultation. Physical retail retains loyalty for large-breed puppy owners navigating rapid growth stage transitions.
- Direct Sales:Veterinary clinic dispensing and breeder network distribution bypass retail markup structures. MOCCAE prescription format regulations govern professional channel inventory requirements.
Supermarkets dominate installed base. Online retail is where expansion concentrates as platform infrastructure matures.
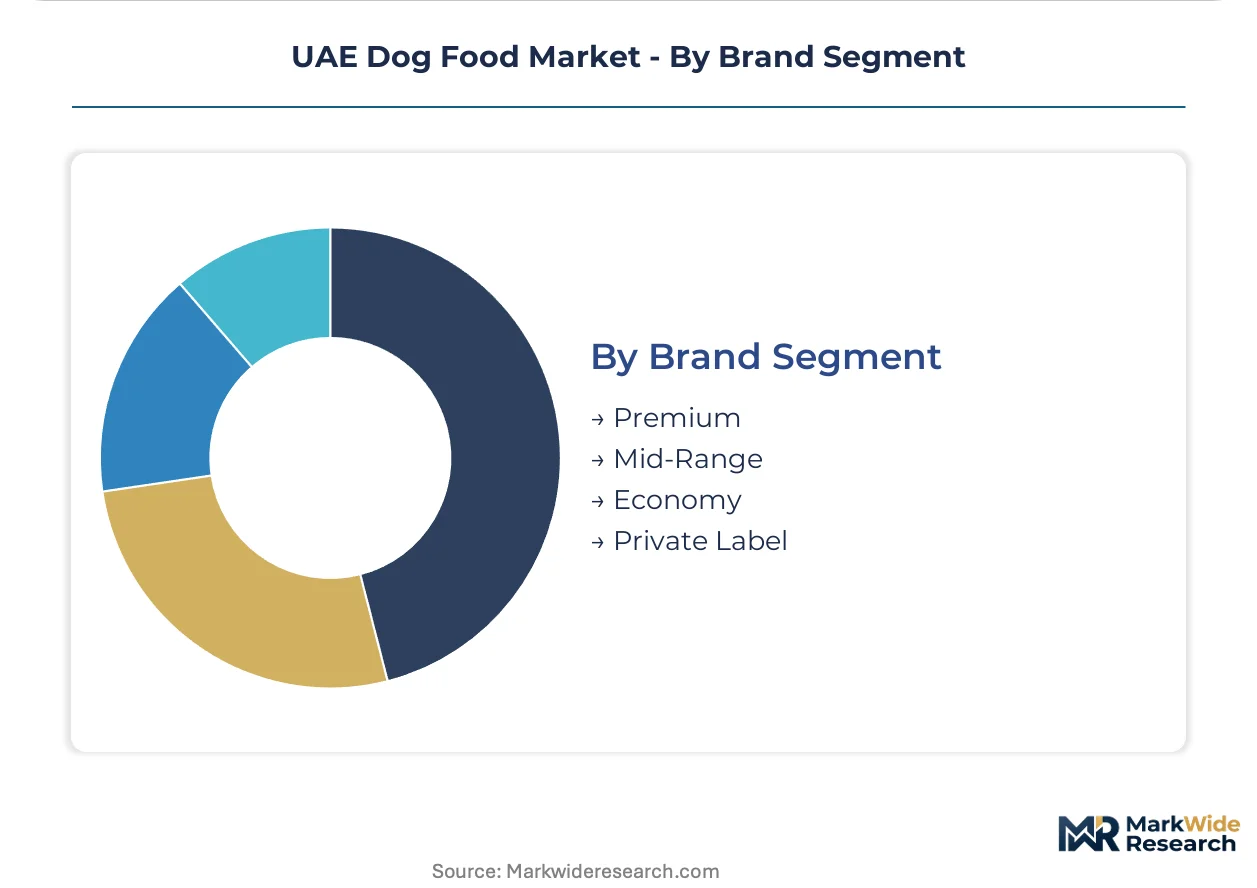
Brand Segment:
Margin concentration stratifies across four tiers with private label entrants compressing mid-range positioning from below.
- Premium:Cold-pressed and minimally processed positioning with ingredient transparency claims and veterinary endorsement partnerships. Mars GCC and Nestlé Middle East FZE anchor this tier through regional production scale.
- Mid-Range:Balanced nutrition positioning facing squeeze between premium trade-up and private label value capture. Shelf space erosion accelerates as supermarket operators expand house brand portfolios.
- Economy:Price-driven formulations with standard extrusion processing and commodity protein inputs. Volume concentrates in Sharjah and Ajman households with multiple large-breed dogs.
- Private Label:Retailer-controlled brands exploiting hypermarket slotting fee avoidance and direct import relationships. Lulu and Carrefour private labels gain share fastest in standard adult maintenance formulations.
Premium brands dominate installed base. Private label is where expansion concentrates as retail vertical integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand-based Charoen Pokphand Group exports protein meal and extruded formulations to UAE distributors, anchoring supply corridors that feed Dubai's pet retail consolidation. This trade flow concentrates premium nutrition sourcing within Southeast Asian manufacturing clusters before MOCCAE-regulated entry.
Dubai
High-income expatriate households in Dubai Marina and Downtown districts sustain premium pet retail foot traffic through bulk purchasing of 15-20kg dry food formats. MOCCAE import permit enforcement shapes product registration timelines for international suppliers seeking shelf placement in Jumeirah boutiques. Al Quoz industrial zone hosts cold-pressed manufacturing retrofits that compress mid-market positioning through nutrient-retention claims.
Abu Dhabi
Khalifa City and Al Raha Beach veterinary clinics drive professional recommendation flows for wet food formats addressing renal health management. ESMA safety alignment with Codex principles elevates consumer trust in commercial nutrition products dispensed through clinic channels. Underdeveloped specialist networks in these districts present white-space for brands capturing professional endorsement capture.
Sharjah
Price-sensitive volume concentrates among multiple large-breed dog households seeking economy-tier formulations through hypermarket chains. Lulu and Carrefour private label penetration occupies value-tier shelf space that compresses mid-range brand positioning. Local distribution infrastructure supports cost-efficient logistics for standard adult maintenance SKUs.
Northern Emirates
Ajman households with working dog populations generate steady demand for commodity protein inputs without premium functional ingredient claims. Limited veterinary channel density channels purchases toward supermarket and online platform commerce. Fulfillment infrastructure from Dubai South distribution centers enables next-day delivery coverage that erodes local retail convenience advantages.
UAE Dog Food Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mars GCC and Nestlé Middle East FZE anchor premium positioning through regional production scale and veterinary partnership networks. Specialist operators including Naturally for Pets LLC occupy transparency-positioned niches competing on ingredient claims rather than price. Competitive moves concentrate on portfolio diversification into functional ingredient categories and subscription platform development bypassing hypermarket slotting fees.
Among UAE-registered entities, Saint Vincent Group GT LLC and Thumbay Marketing & Distribution Co exemplify distribution-architecture specialists controlling import logistics and retail placement. Mars GCC represents scale-driven multinational positioning with captive manufacturing footprint. Naturally for Pets LLC occupies the ingredient-transparency archetype competing through grain-free and raw-aligned SKU development.
| Leading Market Players |
|---|
| Saint Vincent Group GT LLC |
| Naturally for Pets LLC |
| Charoen Pokphand Group |
| Pet Shop LLC |
| Nestlé Middle East FZE |
| Thumbay Marketing & Distribution Co |
| Mars GCC |
| Real Pet Food Co |
| Waitrose Ltd |
| Others |
Cost & Logistics Intelligence
Al Quoz industrial zone manufacturing capacity anchors cold-pressed kibble production that commands shelf price multiples against standard extrusion imports. This supply concentration grants regional producers margin leverage while MOCCAE compliance costs compress mid-tier positioning.
Pricing Analysis
Standard extrusion versus cold-pressed versus freeze-dried formats separate three distinct pricing tiers. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity and MOCCAE registration investment. Price differentiation hinges on veterinary endorsement partnerships and Arabic labeling compliance capacity. Pricing pressure stems from private label expansion at Carrefour and Lulu hypermarkets. Economy-tier buyers in Sharjah and Ajman exhibit highest price sensitivity, while Dubai Marina multi-dog households show lowest sensitivity to per-kilogram premiums.
Supply Chain Analysis
Tariff exposure between Thailand and UAE elevates landed costs for Charoen Pokphand Group protein meal shipments. Thailand, Southeast Asian manufacturing clusters, and European specialty ingredient suppliers feed UAE formulation operations. Raw material dependencies center on poultry meal, fish hydrolysate, and functional additive premixes. Single-source vulnerability concentrates in novel protein insect meal suppliers without captive contracts. Distribution runs through Dubai South fulfillment centers for platform commerce and Al Quoz cold storage for raw food formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel fragmentation across subscription platforms, veterinary clinics, and boutique retail creates niche capture opportunities for specialists. Expatriate household purchasing bifurcation between trial-sized physical retail and bulk replenishment online sustains multiple positioning strategies.
For Market Incumbents: Pre-empt private label encroachment by locking veterinary channel exclusivity through MOCCAE prescription format partnerships. Mars GCC and Nestlé Middle East FZE should accelerate backward integration into UAE-based cold-pressed manufacturing to defend margin position against Thai import cost volatility. Certification investment in ESMA-aligned quality infrastructure raises rival documentation barriers.
For New Entrants and Emerging Players: Build out subscription direct-to-consumer platforms targeting Khalifa City and Al Raha Beach multi-dog households with auto-replenishment algorithms. Abu Dhabi veterinary channel white-space offers the most penetrable entry point for professional recommendation capture. Grain-free and functional ingredient positioning with transparent supply chain documentation provides differentiated go-to-market angle against incumbent scale.
For Investors and Strategic Acquirers: Long-term, this sits as a premiumization play because preventive health spending on aging pet populations sustains functional ingredient margin expansion. Acquisition targets should emphasize UAE-registered entities with established MOCCAE dossiers and veterinary clinic distribution relationships. Watch MOCCAE enforcement intensity on raw food safety protocols as inflection indicator for segment expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Professional recommendation flows through Dubai Healthcare City clinics control premium segment access. |
| Cold-Pressed Manufacturing Retrofit | Al Quoz production capacity captures nutrient-retention claims that compress mid-market positioning. |
| Subscription Platform Launch | Auto-replenishment algorithms bypass Carrefour slotting fees while capturing multi-dog household lifetime value. |
| Arabic Labeling Localization | Technical translation capacity for veterinary terminology accelerates MOCCAE registration timelines. |
| Functional Ingredient Portfolio Extension | Glucosamine and probiotic fortification commands price multiples in aging pet preventive health spending. |
Research Approach
Operator-level perspectives from pet food manufacturing directors, veterinary clinic procurement managers, hypermarket category buyers, and MOCCAE regulatory affairs specialists anchored the qualitative base. Secondary validation drew from ESMA safety specifications, GCC Standardization Organization framework documents, MOCCAE import permit circulars, and customs trade data for protein meal shipments. Bottom-up demand modeling across product type, ingredient category, sales channel, and brand tier triangulated against top-down market sizing from production capacity estimates.
Scenario-bracketing framed projections across regulatory enforcement intensity variations and expatriate household formation patterns. Segmentation dimensions modeled include product format, ingredient positioning, channel ownership structure, and geographic demand concentration throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to historical penetration rates and income elasticity assumptions for premium pet nutrition.
Stress conditions across MOCCAE enforcement intensity, novel protein input cost volatility, and private label expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and household formation trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Dog Brush Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Dog Supplement Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Smart Pet Leash Market