
 Europe Organic and Natural Pet Food Market | 2026-2036
Europe Organic and Natural Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic and Natural Pet Food Market Intelligence
The gap between premium organic formulations and conventional commodity pet food is rebalancing around ingredient transparency and certified sourcing claims. Farmina Pet Foods leverages its Italian manufacturing base to control veterinary channel distribution across Southern Europe. Yarrah anchors its competitive position through dedicated organic certification and Dutch supply chain integration. Mars, Incorporated dominates mass-market shelf space while extending premium portfolio lines through its Royal Canin and Whiskas brand architecture.
Europe organic and natural pet food comprises formulated diets manufactured without synthetic pesticides, antibiotics, or genetically modified organisms, with primary commercial purpose of delivering certified clean-label nutrition aligned to EU organic regulation 2018/848. Dry food retains the largest volume share due to logistics efficiency and extended shelf stability, while wet food and treats capture disproportionate margin pools through premium positioning and emotional purchase triggers. The ingredient source dimension shows meat-based formulations leading absolute sales, though plant-based and grain-free variants are carving faster growth trajectories among allergy-sensitive pet populations.
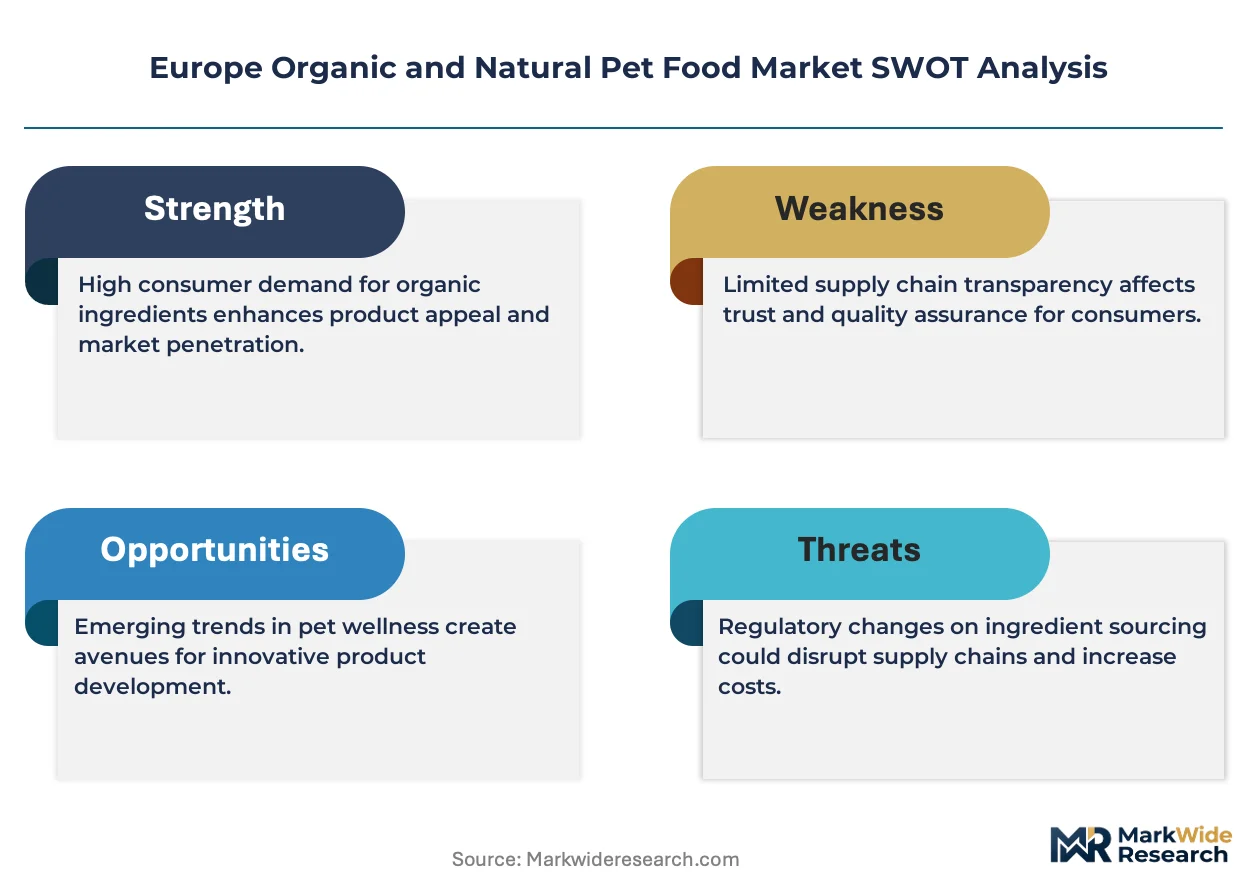
EMA feed legislation, EU organic certification under Regulation 2018/848, and national veterinary oversight through bodies such as Germany's Federal Office of Consumer Protection and Food Safety collectively shape product standards and market access thresholds. EFSA nutritional adequacy requirements force reformulation investments that filter smaller uncertified competitors from retail distribution. Stakeholders must monitor evolving EU packaging waste directives and the CSRD sustainability disclosure framework, which will soon require granular supply chain emissions reporting from pet food manufacturers serving European markets.
Market Dynamics
EU Green Deal implementation is compressing feed sourcing timelines and forcing manufacturers to restructure supply chains around traceable organic inputs before 2030 compliance deadlines bite.
Growth Catalysts
- Regulation 2018/848:Mandatory EU organic certification creates defensible market positions for compliant manufacturers while filtering uncertified competitors from retail channels.
- Urban France and Germany:Concentrated pet ownership in metropolitan corridors generates premium demand density that rewards localized distribution investments.
- Veterinary channel integration:Professional recommendation networks in Southern Europe drive prescription-grade organic adoption among health-conscious dog owners.
Market Restraints
- Organic protein input costs:Certified meat and fish meal prices track 40-60% above conventional feed-grade equivalents, compressing gross margins at volume tiers.
- Benelux supply concentration:Dutch and Belgian organic ingredient processors control critical mid-stream capacity, creating single-source vulnerability for Southern European manufacturers.
- EFSA nutritional adequacy timelines:Reformulation validation cycles extend 18-24 months, delaying product launches and freezing SKU portfolios during regulatory transitions.
Strategic Opportunities
- Eastern European underpenetration:Poland, Czech Republic, and Hungary show sub-5% organic pet food penetration against Western European baselines, offering first-mover positioning.
- CSRD-aligned sustainability reporting:Early adoption of granular supply chain emissions disclosure creates procurement preference with retail buyers facing their own disclosure mandates.
- Subscription direct-to-home:Automated replenishment models bypass traditional veterinary and specialty retail gatekeepers while capturing lifetime value data.
Industry Challenges
- Organic certification talent scarcity:Qualified supply chain auditors and regulatory affairs specialists command 35-50% salary premiums against conventional pet food equivalents.
- Legacy ERP integration:Batch-level traceability requirements under EU organic rules force expensive middleware development or full system replacement.
- Cross-border veterinary licensing:National regulatory bodies such as Germany's Federal Office of Consumer Protection and Food Safety impose non-harmonized approval timelines that fragment product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic and Natural Pet Food Market |
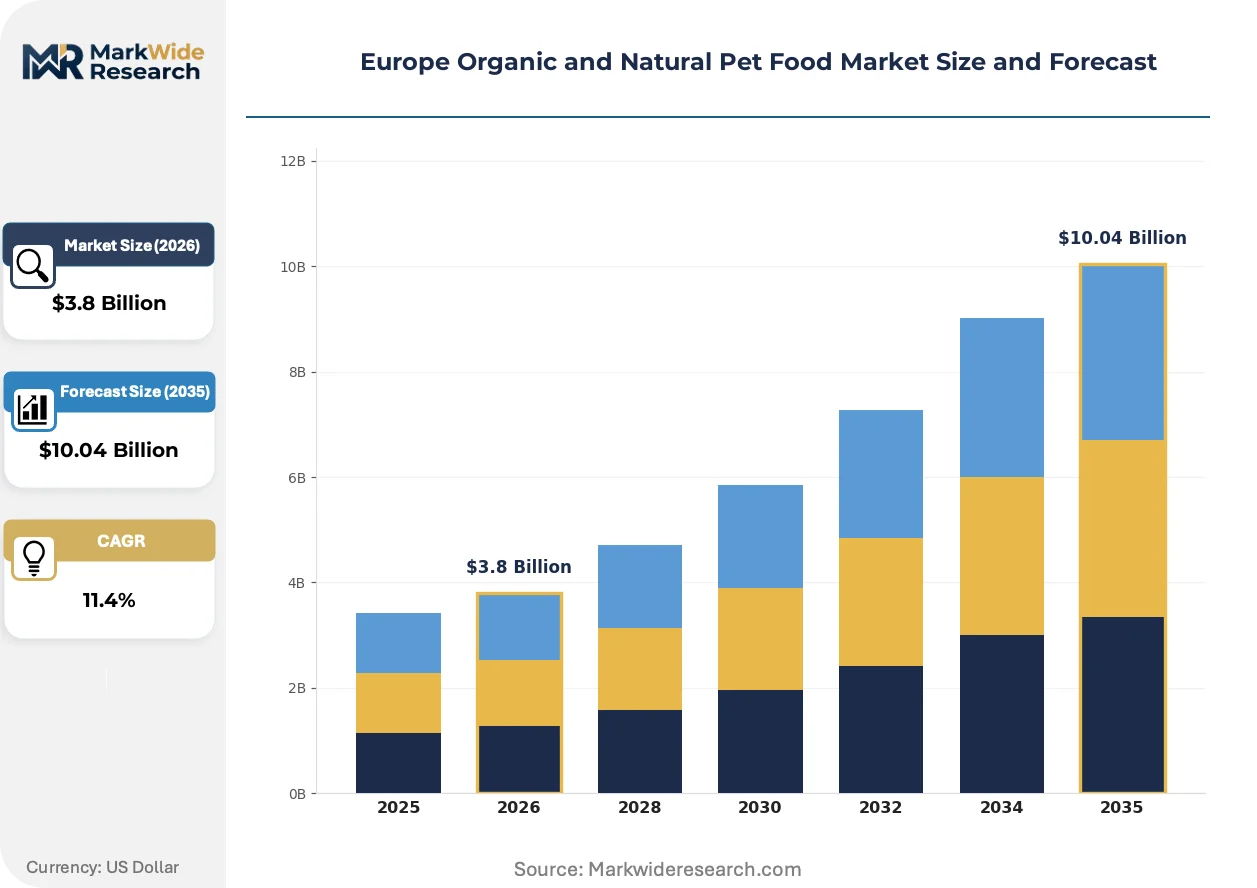
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Meat-Based, Plant-Based, Grain-Free, Organic Packaging Type: Bags, Cans, Pouches, Tubs Sales Channel: Online Retail, Specialty Stores, Supermarkets, Veterinarians |
| Companies Covered | Farmina Pet Foods, Yarrah, Nestlé Purina Pet Care, Affinity Petcare, Smalls Pet Food, Mars, Incorporated, Lily's Kitchen, Almo Nature, Hill's Pet Nutrition, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic and Natural Pet Food Market Strategic Shifts & Innovations
Clean-label ingredient verification technologies are displacing paper-based audit trails as the primary trust mechanism between manufacturers and retail buyers across European markets.
Blockchain-enabled supply chain tracking is integrating veterinary-grade feed documentation with retail-facing QR code verification. Premium manufacturers in Italy and France are adopting these systems at 20-30% annual adoption velocity. The technology is compressing certification costs while enabling real-time contamination response that paper systems cannot match.
EU packaging waste directives are forcing material transitions toward mono-polymer and paper-based formats by 2030. Wet food producers face particular pressure given multi-layer barrier requirements. German and Dutch manufacturers are responding with pilot-scale industrial compostable trials ahead of mandated Extended Producer Responsibility fee restructuring.
Veterinary recommendation dependence is fragmenting as digitally-native pet owners self-educate through independent certification databases. Specialty retail in Scandinavia and the Netherlands is losing share to manufacturer-direct subscription models that offer price transparency and customization. This behavioral pivot is most visible among millennial dog owners in Copenhagen and Amsterdam urban cores.
Europe Organic and Natural Pet Food Market Segmentation
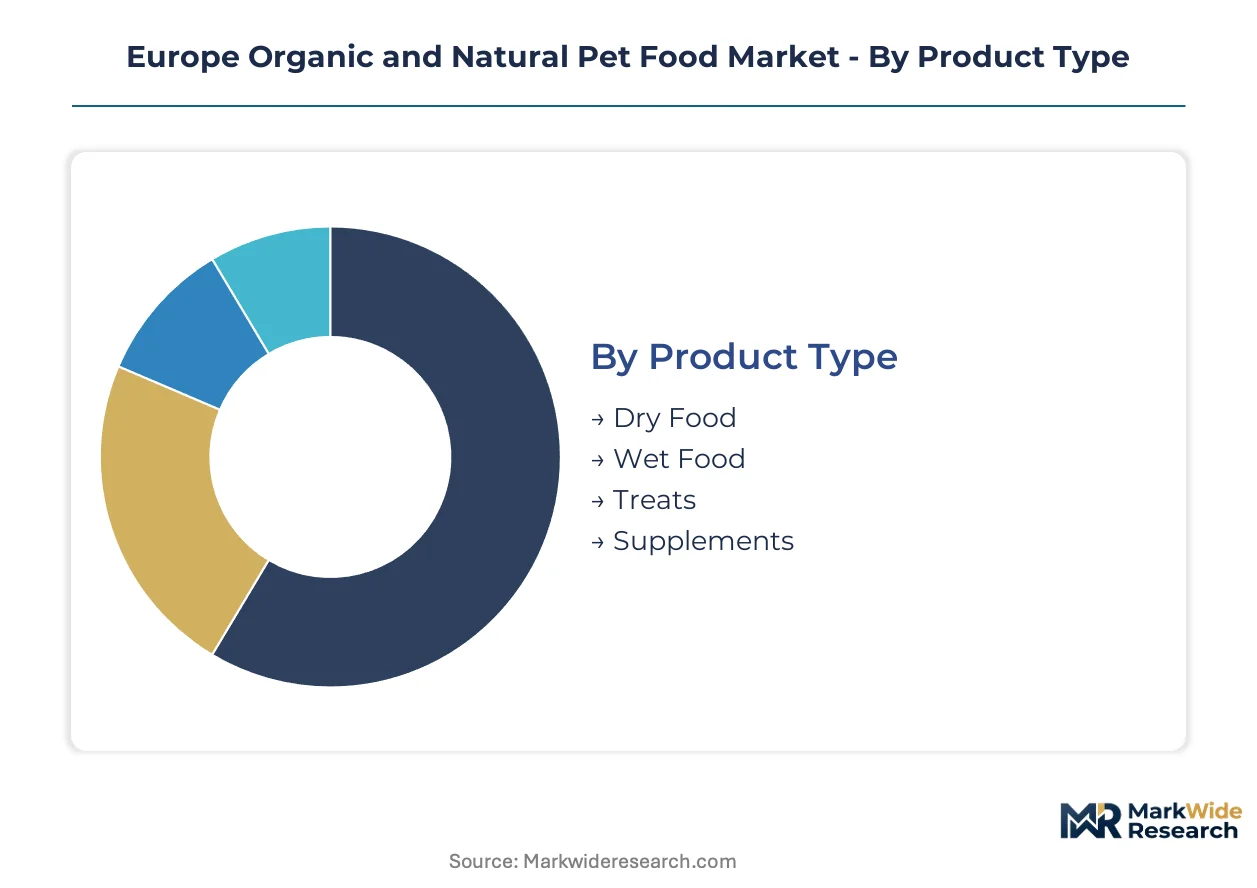
Segmentation in Europe organic and natural pet food reveals how certification tiers, ingredient sourcing, and channel access partition purchasing power across distinct consumer cohorts. Manufacturers configure product architectures around these fault lines to capture margin premiums or defend volume positions.
Product Type:
Pet owners upgrade from conventional diets to organic formulations through staged transitions that favor familiar formats before experimentation with wet or functional variants.
- Dry Food:Extruded kibble and baked formulations using certified organic grains, proteins, and fats deliver caloric density with shelf stability exceeding 18 months. Urban households in Germany and France favor bulk dry purchases for multi-dog environments where storage efficiency matters. EFSA nutritional adequacy requirements force micronutrient fortification that raises production costs 15-25% above conventional equivalents.
- Wet Food:Retort-processed meals in gravy or pâté formats achieve higher moisture content and palatability acceptance among senior pets or fussy eaters. Premium positioning in Italian veterinary channels drives prescription-grade wet organic adoption for dogs with renal or digestive sensitivities. The format carries disproportionate margin but faces EU packaging waste directive pressure on multi-layer barrier materials.
- Treats:Functional and reward formats using single-source organic proteins or vegetable bases.
- Supplements:Powder, liquid, and chewable additions targeting joint health, coat quality, or digestive function.
Volume placements concentrate in Dry Food; the faster expansion belongs to Wet Food.
Ingredient Source:
Ingredient sourcing decisions cascade through certification costs, allergen labeling, and protein digestibility metrics that reshape formulation economics.
- Meat-Based:Formulations built on certified organic chicken, beef, lamb, or fish meal as primary protein inputs. Dutch and Belgian processors control mid-stream rendering capacity for organic meat meals, creating supply concentration that Southern European manufacturers must navigate through long-term contracting.
- Plant-Based:Pea, lentil, and potato protein concentrates replace animal inputs for allergy management or owner lifestyle alignment. Scandinavian markets show elevated plant-based adoption where environmental concern correlates with pet dietary choices.
- Grain-Free:Legume and tuber carbohydrate substitutes eliminate wheat, corn, or rice for gluten-sensitive pet populations.
- Organic:100% certified organic ingredient content meeting EU Regulation 2018/848 standards for synthetic-free production.
Meat-Based commands absolute revenue; Plant-Based climbs the fastest.
Packaging Type:
Packaging selection reflects shelf-life requirements, portion control needs, and mounting regulatory pressure on material circularity.
- Bags:Multi-wall paper or flexible plastic structures for dry food bulk distribution dominate logistics efficiency.
- Cans:Steel or aluminum containers for wet food sterilization deliver maximum shelf stability but carry heavy embodied carbon.
- Pouches:Flexible stand-up or flat formats with spout or tear-notch closures enable portion-controlled wet food dispensing. German manufacturers pilot industrial compostable pouch films ahead of Extended Producer Responsibility fee restructuring.
- Tubs:Rigid plastic or molded fiber containers for fresh or refrigerated organic formats.
Bag shipments dominate tonnage; pouch adoption accelerates most quickly.
Sales Channel:
Channel strategy determines margin capture, customer data access, and veterinary endorsement leverage.
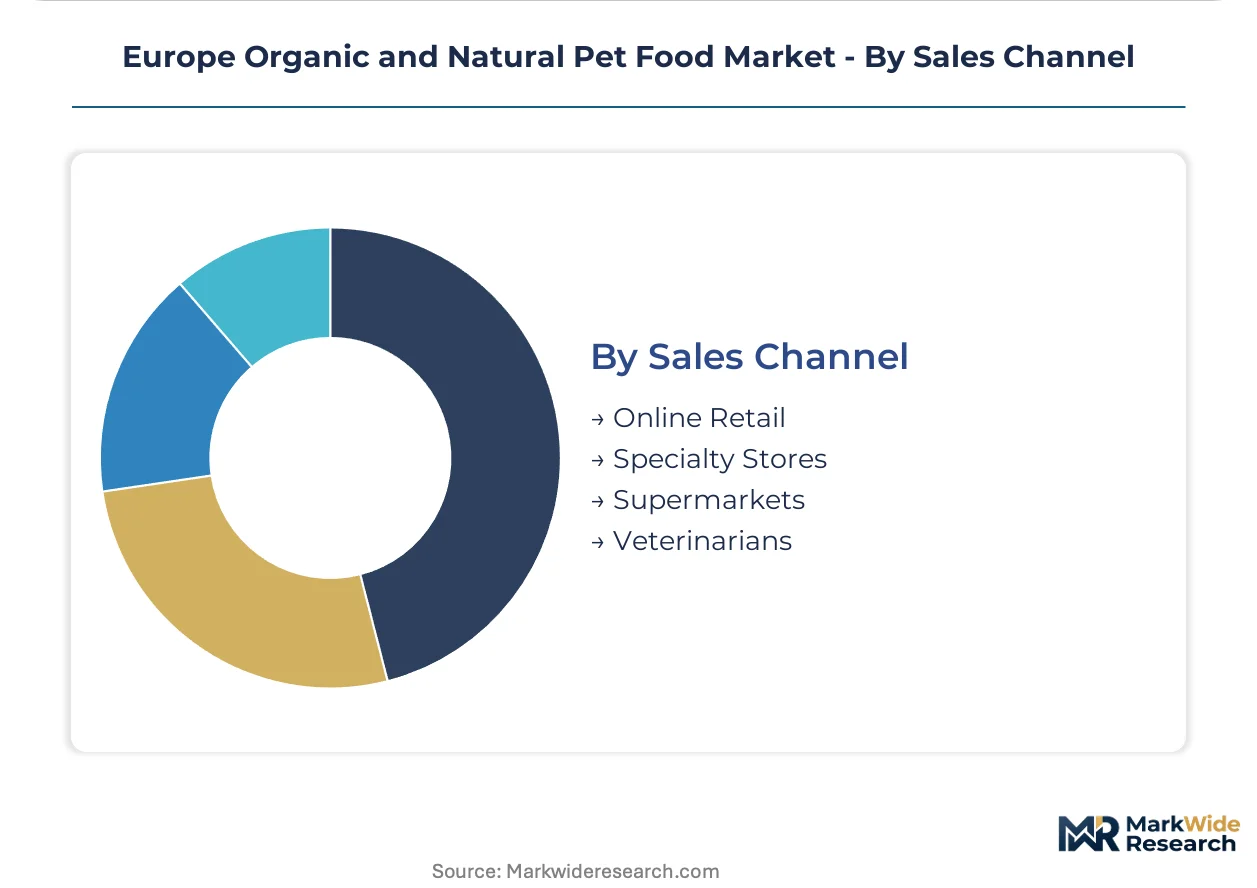
- Online Retail:Direct-to-consumer and marketplace platforms enable subscription replenishment and customization. Amsterdam and Copenhagen urban cores show highest European penetration of automated organic pet food delivery, displacing specialty retail share among digitally-native millennial owners.
- Specialty Stores:Independent pet retailers with trained staff and curated organic assortments. Benelux and Scandinavian independents face margin compression from manufacturer-direct competition.
- Supermarkets:Mass-market grocers with limited organic SKUs competing on price transparency.
- Veterinarians:Professional recommendation networks in Southern Europe drive prescription-grade organic adoption through clinical credibility and diet-health outcome linkage.
Supermarket volume remains largest; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amsterdam anchors European organic pet food distribution innovation through subscription-first models that bypass traditional retail gatekeepers. Metropolitan corridors in France and Germany concentrate premium demand density. Regulatory pressure from EU Green Deal implementation reshapes sourcing requirements across all national markets.
Germany
Urban dog ownership in Berlin, Hamburg, and Munich corridors drives certified organic formulation demand. The Federal Office of Consumer Protection and Food Safety enforces non-harmonized veterinary licensing timelines that fragment product rollouts. Bavarian manufacturing clusters absorb reformulation investments triggered by EFSA nutritional adequacy requirements.
France
Paris and Lyon metropolitan areas concentrate premium pet diet spending among health-conscious millennial owners. ANSM veterinary oversight integrates with EU Regulation 2018/848 certification mandates for retail market access. Southern France veterinary channel networks drive prescription-grade organic adoption through clinical credibility.
Italy
Northern Italian manufacturing bases around Milan and Turin control veterinary channel distribution across Southern Europe. REACH-aligned chemical safety standards influence packaging material transitions. Italian producers leverage regional rendering capacity for organic meat meal inputs despite Benelux supply concentration.
Netherlands
Randstad organic ingredient processors command critical mid-stream capacity for European manufacturers. Dutch supply chain integration anchors Yarrah's competitive positioning through dedicated certification infrastructure. Amsterdam's digitally-native pet owner cohort displaces specialty retail share through automated replenishment platforms.
United Kingdom
London and Southeast England concentrate premium organic pet food demand among urban professional households. Post-Brexit regulatory divergence from EU 2018/848 standards creates parallel certification requirements for cross-channel suppliers. Midlands distribution hubs manage logistics complexity for island-bound organic ingredient flows.
Europe Organic and Natural Pet Food Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and veterinary channel access. The market structures around three concentration layers: mass-market shelf space holders, veterinary-channel specialists, and direct-to-consumer subscription operators. Strategic archetypes include integrated European manufacturers with captive organic supply, Dutch-certified pure-plays with supply chain transparency positioning, and diversified multinational portfolios spanning conventional through premium tiers. Dominant competitive moves center on backward integration into organic protein rendering and subscription platform development to capture lifetime customer value.
Within the certified organic pure-play tier, Farmina Pet Foods and Yarrah exemplify geographic anchoring strategies—Italian manufacturing control versus Dutch supply chain integration. Mars, Incorporated occupies a position spanning mass-market through premium portfolio architecture. These three represent distinct archetypes: Southern European veterinary channel leverage, Benelux supply transparency specialization, and multinational scale diversification.
| Leading Market Players |
|---|
| Farmina Pet Foods |
| Yarrah |
| Nestlé Purina Pet Care |
| Affinity Petcare |
| Smalls Pet Food |
| Mars, Incorporated |
| Lily's Kitchen |
| Almo Nature |
| Hill's Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Certified organic protein meal indices in the Benelux region cascade through three distinct pricing tiers, compressing margins for Southern European manufacturers who lack captive rendering capacity while rewarding Dutch-integrated pure-plays with cost transparency advantages under EU Regulation 2018/848.
Pricing Analysis
Veterinary-grade outcome pricing anchors premium tiers, with prescription organic formulations commanding 40-60% markups over conventional equivalents based on clinical credibility and diet-health outcome linkage. Price differentiation stratifies across certified organic, natural, and conventional tiers, with certification level and channel access as primary drivers. Pricing pressure stems from organic protein input costs tracking substantially above feed-grade equivalents, squeezing volume-tier margins. Mass-market supermarket buyers exhibit highest price sensitivity, while veterinary-channel purchasers demonstrate lowest elasticity due to health outcome prioritization.
Supply Chain Analysis
Return flows of non-conforming organic batches drive traceability investments, with blockchain-enabled verification replacing paper audit trails to compress recall response times. Supply concentration centers on the Netherlands and Belgium for organic ingredient processing, with Italy and Germany anchoring downstream formulation. Raw material dependencies include certified organic meat meals, grain inputs, and mono-polymer packaging films. Single-source vulnerability in Benelux mid-stream capacity creates structural risk for Southern European manufacturers. Distribution runs through veterinary channels in Southern Europe, specialty retail in Scandinavia, and automated subscription platforms in Amsterdam and Copenhagen urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled supply chain verification is displacing legacy paper-based audit systems, forcing capital reallocation toward traceability infrastructure before 2030 packaging waste compliance deadlines.
For Market Incumbents: Deploy backward integration into organic protein rendering to secure supply certainty against Benelux concentration risk. Capture veterinary channel gatekeeper relationships through clinical trial investment that links organic formulations to measurable health outcomes. Defend against subscription-platform disintermediation by building proprietary direct-to-consumer data capabilities. For New Entrants and Emerging Players: Enter via Eastern European white-space markets where organic penetration sits below Western European baselines, particularly Poland and Czech Republic urban corridors. Target digitally-native millennial owners in underpenetrated metropolitan zones with transparent certification storytelling. Leverage CSRD-aligned sustainability reporting as procurement wedge with retail buyers facing disclosure mandates. For Investors and Strategic Acquirers: The window for entry favors Dutch-certified pure-plays with integrated supply chain transparency infrastructure. Long-term viability hinges on defensible organic certification moats rather than brand equity alone. Monitor EFSA nutritional adequacy timeline extensions as signal for competitive filtration intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Rendering | Captures Benelux-independent supply security for Southern European manufacturers under EU 2018/848. |
| Blockchain Traceability Deployment | Compresses certification costs while enabling real-time contamination response that paper systems cannot match. |
| Veterinary Channel Partnership Expansion | Locks prescription-grade adoption through clinical credibility in Italian and French professional networks. |
| Subscription Platform Development | Bypasses specialty retail gatekeepers while capturing lifetime value data from Amsterdam and Copenhagen cohorts. |
| CSRD-Aligned Emissions Disclosure | Creates procurement preference with retail buyers facing granular supply chain reporting mandates. |
Research Approach
Document review covered EU regulatory filings under Regulation 2018/848, EFSA nutritional adequacy assessments, and national veterinary licensing records, complemented by interviews with organic certification specialists, supply chain auditors, and regulatory affairs leads at manufacturers across Italy, Germany, and the Netherlands. Secondary validation drew from customs trade data on organic ingredient flows, retail audit databases tracking channel share shifts, and sustainability disclosure frameworks. Bottom-up SKU-level modeling triangulated against top-down market sizing from production capacity and consumption surveys.
Output metrics span volume tonnage and value realization across product type, ingredient source, packaging format, and sales channel dimensions throughout the forecast period. CAGRs derive from regression analysis against organic certification adoption curves and premiumization elasticity coefficients. Industry-specific inputs include EFSA reformulation timeline distributions and veterinary channel recommendation velocity indices.
Revisions become necessary when EFSA nutritional adequacy requirements extend validation cycles, when EU packaging waste directives accelerate material transition costs, or when organic certification talent scarcity intensifies salary premiums beyond modeled assumptions. Practitioners should monitor Benelux processor capacity utilization and blockchain traceability adoption rates for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Parrot Cage Market
Pet Care Products
Dog Harness Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Bird Toy Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Pet Food Market
Pet Care Products
Paw Plunger Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Dry Pet Food Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
Dog Biscuit Market
Pet Care Products
Pet Transport Cage Market